
 Methionine Market | 2026-2036
Methionine Market Size, Share, and Industry Trends Forecast 2026-2036
Methionine Market Intelligence
The EU Green Deal is consolidating demand for sustainably produced feed-grade amino acids across European livestock operations. Evonik Industries AG leverages its integrated biotechnology platform to maintain cost leadership in DL-Methionine production. Adisseo anchors its competitive position through captive raw material sourcing and global distribution networks. Novus International differentiates via specialty methionine hydroxy analogue formulations targeting precision nutrition protocols.
Methionine is a sulfur-containing essential amino acid with the chemical formula C5H11NO2S, synthesized industrially through acrolein-based chemistry or fermentation processes to achieve feed-grade or pharmaceutical-grade purity. Its primary commercial purpose centers on protein synthesis optimization in monogastric animals where endogenous production remains insufficient. DL-Methionine occupies the dominant volume position in animal feed applications due to established cost economics and universal metabolic utilization across poultry and swine species. L-Methionine commands premium positioning within pharmaceutical and nutritional supplement channels where chirality-specific efficacy determines product value. The powder form sustains manufacturing scale advantages, though liquid formulations are gaining traction in automated feed milling operations.
The European Commission's F-Gas Regulation and REACH framework constrain petrochemical feedstock pathways for methionine synthesis, while China's MEE enforces wastewater discharge standards affecting acrolein-derived production economics. The FDA's feed additive approval pathways and USDA organic livestock standards shape market access conditions for novel methionine sources in North American markets. Stakeholders must monitor regulatory divergence between bio-based fermentation routes and conventional chemical synthesis as carbon border adjustments reshape competitive cost structures.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing European livestock operators to requalify their entire amino acid supply chains, creating a bifurcation between bio-based and petrochemical-derived methionine sourcing strategies.
Growth Catalysts
- Poultry Feed Intensification:Industrial broiler operations in Brazil and Indonesia are expanding standardized feed formulations requiring consistent sulfur amino acid supplementation.
- REACH Compliance Premium:European compound feed manufacturers face mandatory substitution timelines for high-carbon-intensity additives, redirecting procurement toward fermentation-derived alternatives.
- Precision Fermentation Scale-Up:Microbial cell factory platforms utilizing methanol-oxidizing bacteria are achieving commercial titer rates competitive with acrolein chemistry.
Market Restraints
- Acrolein Feedstock Volatility:Propylene price swings directly compress margins for chemical synthesis routes concentrated in China's coastal provinces.
- MEE Wastewater Standards:China's Ministry of Ecology and Environment discharge limits impose capital-intensive treatment retrofits on existing petrochemical facilities.
- Enzymatic Racemization Limits:Biological production of DL-Methionine remains constrained by cofactor regeneration costs in continuous fermentation systems.
Strategic Opportunities
- India Poultry Integration:Contract farming expansion in Andhra Pradesh and Telangana creates concentrated demand nodes for feed-grade amino acid distributors.
- EU Carbon Border Adjustments:The phased implementation of CBAM certificates favors low-carbon-intensity methionine producers with verified lifecycle assessments.
- Aquaculture Formulation Gains:Shrimp and salmon feed producers are adopting hydroxy analogue methionine for improved water stability in extruded pellets.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial biotech process engineers with commercial amino acid experience command premium compensation in Jiangsu and Shandong hiring markets.
- Dual Certification Complexity:Simultaneous FAMI-QS and GMP+ feed safety audits create timeline bottlenecks for suppliers serving both European and Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methionine Market |
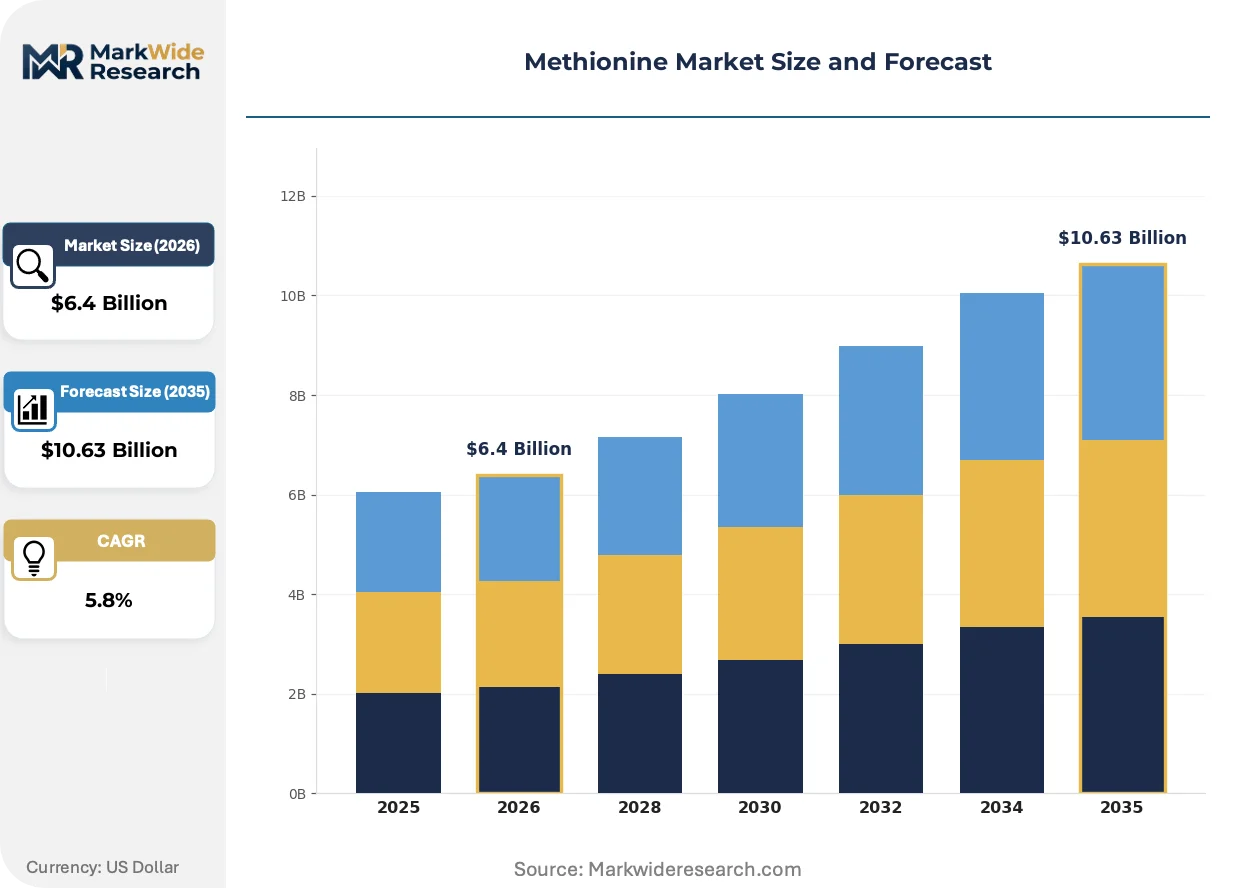
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DL-Methionine, L-Methionine, Methionine Hydroxy Analogue, Others End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Tablets Application: Animal Feed, Pharmaceuticals, Food Products, Nutritional Supplements |
| Companies Covered | Sumitomo Chemical Co., Ltd, Chongqing Unisplendour Chemical Co., Ltd, Evonik Industries AG, Ajinomoto Co., Inc., Sichuan Hebang Group Industry Co., Ltd, Adisseo, CJ CheilJedang Corp, Bluestar Adisseo Co., Ltd., Novus International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methionine Market Strategic Shifts & Innovations
Biotechnology platforms are displacing conventional petrochemical synthesis as the dominant production paradigm, while regulatory carbon accounting and automated feed milling reshape downstream value capture.
Precision fermentation utilizing methylotrophic yeast strains is integrating carbon capture feedstocks directly into methionine biosynthesis pathways. North American and European biotech startups are piloting these systems at demonstration scale. The technology is compressing the carbon intensity differential between regional production bases.
The European Commission's F-Gas Regulation and accompanying delegated acts are phasing down hydrofluorocarbon use in process cooling equipment. Methionine manufacturers operating REACH-registered facilities must retrofit refrigeration systems or relocate synthesis steps. German and Dutch chemical parks are consolidating amino acid production to share upgraded infrastructure.
Automated feed mills are unbundling liquid methionine delivery from traditional dry blending contracts. Large integrators in the US and Brazil are installing dedicated hydroxy analogue storage and metering systems. This equipment shift favors suppliers with technical service capabilities over commodity distributors.
Methionine Market Segmentation
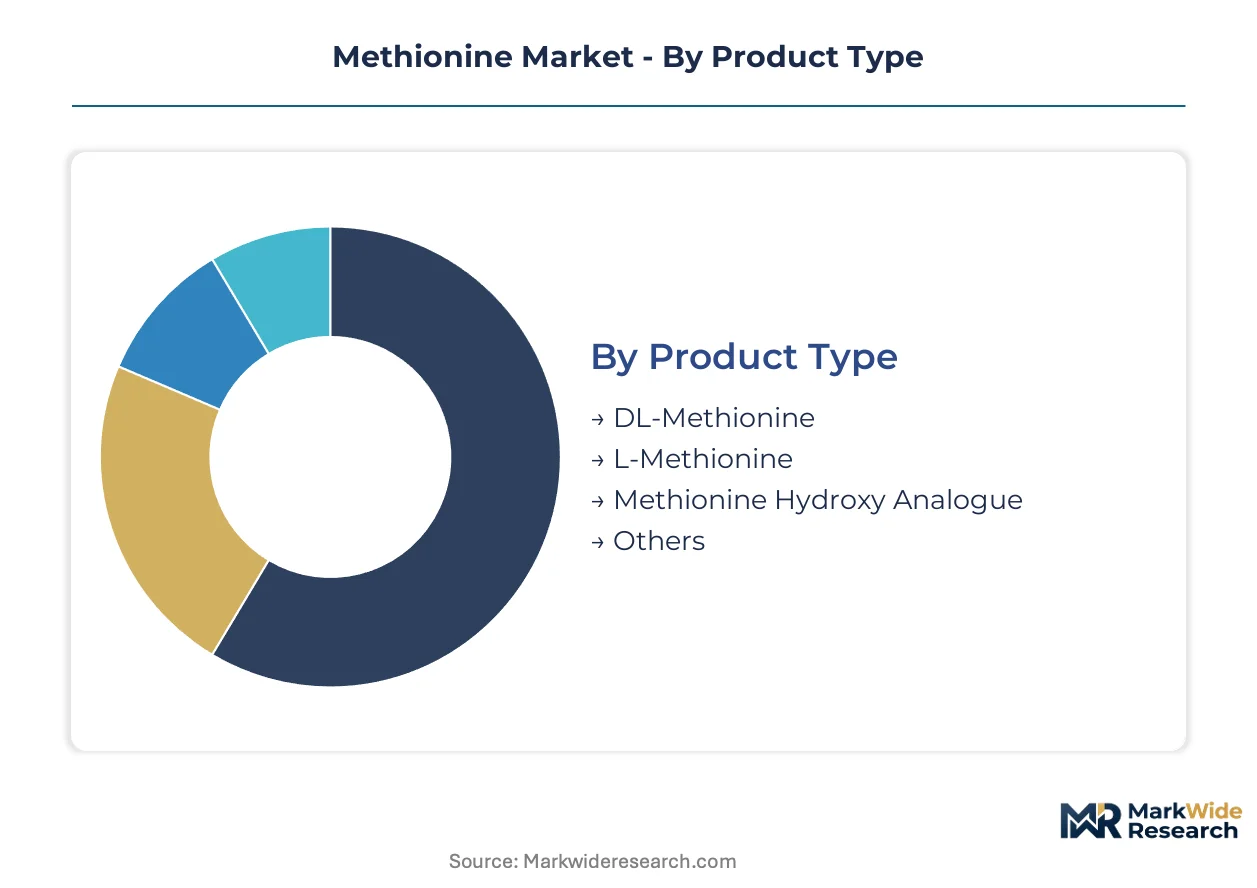
Methionine procurement patterns diverge sharply across end-use sectors, with feed manufacturers prioritizing cost-per-unit protein equivalence while pharmaceutical buyers enforce chirality purity standards. Understanding these segment-specific value drivers exposes where pricing power concentrates and which production technologies command sustainable premiums.
Product Type:
Cost tier determines buyer switching thresholds between synthetic and bio-based variants.
- DL-Methionine:Racemic mixture produced via acrolein chemistry dominates volume economics. Broiler operations in Brazil and Indonesia standardize on this grade for its universal metabolic utilization across monogastric species. Jiangsu and Shandong facilities anchor global supply, though EU carbon border adjustments are eroding their cost advantage into European markets.
- L-Methionine:Enantiomerically pure form commands pharmaceutical-grade premiums. Chirality-specific efficacy requirements from parenteral nutrition formulators and high-end supplement brands concentrate demand in North American and European compounding pharmacies. Fermentation-derived batches carry verified lifecycle credentials that REACH-registered buyers increasingly mandate.
- Methionine Hydroxy Analogue:Liquid precursor bypassing intestinal absorption steps. Automated feed mills favor this form for direct metering into extrusion systems.
- Others:Includes protected methionine sources for ruminant bypass protein applications.
DL-Methionine leads volumes today; L-Methionine is gaining share fastest.
End User:
Application maturity separates price-tolerant niches from commodity procurement battles.
- Poultry:Industrial broiler and layer operations represent the most standardized demand node. Contract farming expansion in Andhra Pradesh and Telangana creates concentrated procurement volumes where distributors compete on logistics reliability rather than formulation innovation.
- Swine:Post-weaning diets require precise sulfur amino acid balancing to optimize feed conversion ratios. European sow farms under F-Gas Regulation compliance timelines face elevated costs that favor regional fermentation suppliers over Chinese petrochemical imports.
- Ruminants:Protected methionine bypasses rumen degradation to reach the small intestine intact. Dairy nutritionists in Wisconsin and the Netherlands specify these products for high-producing herds where milk protein content determines farmgate returns.
- Aquaculture:Shrimp and salmon feed producers adopt hydroxy analogue forms for water stability in extruded pellets. Marine ingredient substitution pressures intensify amino acid supplementation requirements as fishmeal inclusion rates decline.
Poultry dominates absolute consumption; aquaculture presents the steepest expansion trajectory.
Form:
Distribution infrastructure and handling economics dictate format selection across customer tiers.
- Powder:Free-flowing crystalline product sustaining manufacturing scale advantages. Dry blending operations at legacy feed mills continue specifying this form for compatibility with existing batching equipment.
- Liquid:Hydroxy analogue solutions enabling automated metering and reduced dust exposure. Large US and Brazilian integrators are installing dedicated storage and pumping systems that lock in supplier relationships through technical service dependencies.
- Granules:Dust-reduced agglomerated form improving flowability in pneumatic conveying systems.
- Tablets:Unit-dose format for companion animal supplements and pharmaceutical compounding.
Powder maintains volume leadership; liquid formats are climbing the fastest as mill automation accelerates.
Application:
Regulatory pathway complexity fragments competitive dynamics across use cases.
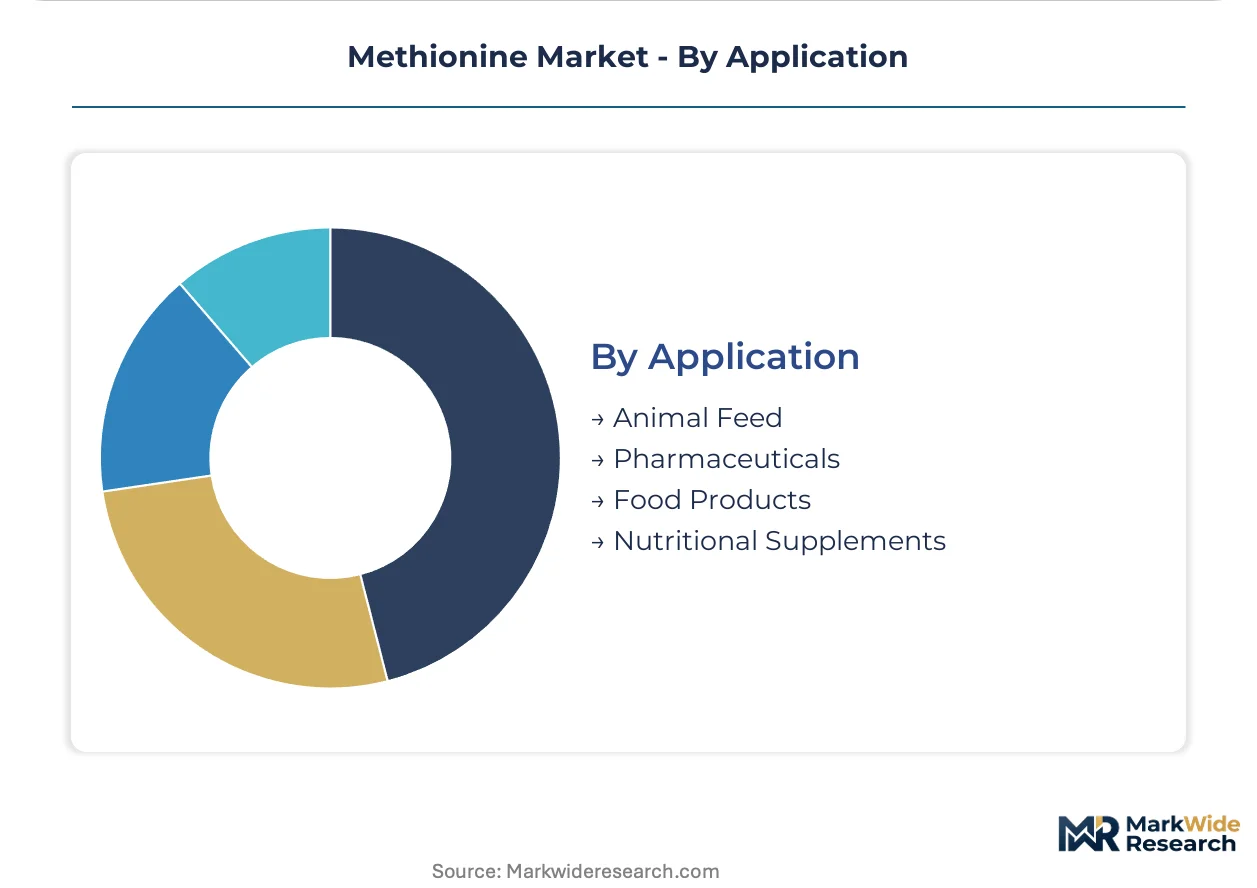
- Animal Feed:Volume anchor where FAMI-QS and GMP+ certifications create dual audit burdens for suppliers serving European and Asian markets simultaneously. Feed-grade purity specifications tolerate racemic mixtures, keeping DL-Methionine cost-competitive against bio-based alternatives.
- Pharmaceuticals:USP and EP monograph compliance mandates analytical documentation batches that fermentation producers can deliver more readily than petrochemical synthesis operations. Parenteral nutrition and hepatoprotective drug formulations require endotoxin-controlled L-Methionine with certificate-of-analysis traceability.
- Food Products:Fortification applications in bakery and beverage matrices where methionine balances plant protein amino acid profiles.
- Nutritional Supplements:Sports nutrition and clinical dietetic segments where clean-label positioning favors fermentation-derived sourcing claims.
Animal Feed commands absolute tonnage; Nutritional Supplements is expanding most quickly on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with commercial amino acid fermentation experience command premium compensation in Jiangsu and Shandong hiring markets. Talent scarcity constrains scale-up velocity for biological production platforms.
China
Industrial methionine synthesis concentrates in Jiangsu and Shandong provinces where acrolein-based chemistry dominates. MEE wastewater discharge standards force capital-intensive treatment retrofits on coastal petrochemical facilities. Qingdao and Nantong chemical parks host the majority of global DL-Methionine manufacturing capacity.
Germany
REACH-registered compound feed manufacturers face mandatory substitution timelines for high-carbon-intensity additives. The F-Gas Regulation phases down hydrofluorocarbon use in process cooling equipment, requiring refrigeration retrofits. German chemical parks consolidate amino acid production to share upgraded infrastructure.
United States
Large poultry integrators install dedicated hydroxy analogue storage and metering systems for automated feed mills. FDA feed additive approval pathways shape market access for novel methionine sources. Midwestern sow farms and southeastern broiler operations drive concentrated procurement volumes.
Brazil
Industrial broiler operations expand standardized feed formulations requiring consistent sulfur amino acid supplementation. Contract farming growth in southern states creates demand nodes for feed-grade amino acid distributors. São Paulo and Paraná anchor poultry integration and feed milling automation.
India
Contract farming expansion in Andhra Pradesh and Telangana generates concentrated procurement volumes for distributors. BIS standards and FSSAI regulations govern feed additive quality specifications. Poultry integration in southern states favors logistics reliability over formulation innovation.
Methionine Market Key Industry Players
Capital-heavy producers compete with asset-light technology licensors across divergent synthesis pathways. The market structure consolidates around integrated petrochemical operators and specialized fermentation platforms. Three archetypes dominate: acrolein-based chemical synthesizers, precision fermentation specialists, and hydroxy analogue formulators. Capacity expansion and strategic technology licensing represent the primary competitive moves.
Within the integrated chemical synthesis tier, Evonik Industries AG and Adisseo occupy positions exemplifying European petrochemical-rooted production. Among Asian fermentation-focused operators, Ajinomoto Co., Inc. and CJ CheilJedang Corp represent biotechnology-forward archetypes. Sumitomo Chemical Co., Ltd anchors Japanese chemical industry participation in sulfur amino acid supply chains.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd |
| Chongqing Unisplendour Chemical Co., Ltd |
| Evonik Industries AG |
| Ajinomoto Co., Inc. |
| Sichuan Hebang Group Industry Co., Ltd |
| Adisseo |
| CJ CheilJedang Corp |
| Bluestar Adisseo Co., Ltd. |
| Novus International |
| Others |
Cost & Logistics Intelligence
Precision fermentation scale-up is compressing the carbon intensity differential between regional production bases while simultaneously redrawing cost curves and supplier power across the methionine value chain. This biotechnology transition erodes the historical cost advantage of acrolein-based facilities in China's coastal provinces as EU carbon border adjustments penalize petrochemical-derived imports.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, feed-grade certified, and commodity feed-grade levels dominates methionine procurement. Price differentiation rests on chirality purity and REACH-registered lifecycle documentation, with fermentation-derived L-Methionine commanding substantial premiums over racemic DL-Methionine. Cost compression in commodity feed-grade tiers is intensifying because Jiangsu and Shandong petrochemical facilities face MEE wastewater compliance retrofits. Contract farming operations in Brazil and Indonesia exhibit the highest price sensitivity, while European compound feed manufacturers under F-Gas Regulation timelines show tolerance for certified-premium sourcing.
Supply Chain Analysis
Freight cost differentials between bulk liquid hydroxy analogue shipments and powder container loads are reshaping distributor economics across Atlantic and Pacific lanes. Manufacturing concentrates in China, Germany, and the United States, with Jiangsu and Shandong provinces hosting acrolein-based capacity while German chemical parks consolidate fermentation operations. Raw material flows draw from propylene feedstocks, methanol-oxidizing bacterial cultures, and sulfur recovery streams. Single-source vulnerability runs through China's coastal petrochemical corridor where MEE discharge standards threaten production continuity. Distribution runs through integrated feed mill technical service partnerships rather than commodity trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methionine market functions as a geographic-arbitrage play where EU carbon border adjustments widen the landed cost gap between Chinese petrochemical exports and regional fermentation supply. This differential rewards capacity positioning in low-carbon-intensity production zones.
For Market Incumbents: Acquire fermentation platform technology to offset carbon border exposure on European sales. Evonik and Adisseo should deepen backward integration into methanol feedstock supply while securing FAMI-QS and GMP+ dual certification ahead of REACH substitution timelines. Captive raw material sourcing and shared infrastructure in German-Dutch chemical parks defend margin position against Chinese import erosion. For New Entrants and Emerging Players: Begin with precision fermentation pilots utilizing methylotrophic yeast strains to serve European pharmaceutical and nutritional supplement channels where chirality-specific premiums persist. Contract farming expansion in Andhra Pradesh and Telangana offers the most penetrable demand node for feed-grade distributors lacking technical service capabilities. A go-to-market angle anchored on verified lifecycle assessments unlocks procurement from REACH-registered compound feed manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists because talent scarcity in Jiangsu and Shandong hiring markets constrains organic scale-up velocity for biological production platforms. The acquisition target archetype comprises demonstration-scale precision fermentation operators with carbon capture integration patents. Watch for CBAM certificate price trajectories as the inflection indicator for petrochemical facility stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | Captive supply of methylotrophic fermentation carbon sources insulates margins from commodity volatility. |
| REACH-Registered Fermentation Scale-Up | Verified lifecycle documentation unlocks premium procurement from EU compound feed manufacturers facing F-Gas compliance. |
| Dual Certification Investment | Simultaneous FAMI-QS and GMP+ accreditation eliminates timeline bottlenecks for suppliers serving European and Asian markets. |
| Liquid Hydroxy Analogue Technical Service Partnerships | Automated feed mill integration creates supplier lock-in through dedicated storage and metering system dependencies. |
| Carbon Capture Biosynthesis Integration | Direct CO2 feedstock utilization compresses carbon intensity metrics for CBAM-competitive European market access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation process engineers, compound feed procurement leads, poultry integration operations managers, and pharmaceutical compounding pharmacists with secondary validation from customs trade data, SEC 10-K filings, ECHA REACH registrations, and MEE discharge compliance records. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Segment-weighting approaches applied differential growth assumptions across product type, end-use sector, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from installed capacity trajectories, feed conversion ratio optimization trends, and substitution elasticity estimates between DL-Methionine and hydroxy analogue forms. Industry-specific inputs included broiler operation stocking densities, sow farm sulfur amino acid balancing protocols, and shrimp feed extrusion formulation specifications.
Several conditions sit outside the modeled scope, including abrupt propylene price shocks, unilateral F-Gas Regulation enforcement acceleration, and breakthrough enzymatic racemization cost reductions. Forecasts reflect documented assumptions about CBAM implementation phasing and fermentation titer rate improvements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Electronic Batio3 Powder Market