
 Zinc Chloride Market | 2026-2036
Zinc Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Chloride Market Outlook
The electronics industry vertical is broadening its offtake of high-purity zinc chloride for soldering flux and battery electrolyte formulations. TIB Chemicals AG leverages its European manufacturing footprint to serve specialty flux customers with consistent battery-grade output. Weifang Dongfangsheng Chemical Co., Ltd. anchors the global supply base through large-scale anhydrous production in Shandong Province. American Elements differentiates via ultra-high-purity offerings targeting semiconductor and research applications.
Zinc chloride is a hygroscopic inorganic salt with the formula ZnCl₂, typically produced through the reaction of zinc metal or zinc oxide with hydrochloric acid, yielding white crystalline solids that deliquesce in moist air and form acidic aqueous solutions. The compound functions primarily as a Lewis acid catalyst, metal surface fluxing agent, and wood preservative, with anhydrous grades commanding premium positioning due to stringent moisture specifications below 2%. The industry vertical segmentation shows electronics and pharmaceuticals capturing expanding margin pools as purity thresholds rise, while agriculture applications in soil micronutrient delivery represent a mature volume channel with stable offtake patterns. Application-level demand concentrates in flux and catalyst categories where technical specifications directly determine supplier qualification and pricing power.
EPA regulations under the Toxic Substances Control Act govern zinc chloride manufacturing emissions and workplace exposure limits in the United States, while REACH registration requirements in Europe mandate comprehensive safety data documentation for import and production volumes exceeding one tonne annually. China's MIIT enforces GB standards for industrial chemical purity that shape export competitiveness from domestic producers. Stakeholders must monitor evolving battery electrolyte purity standards and regional carbon-intensity disclosures that will increasingly filter supplier eligibility across automotive and energy storage value chains.
Market Dynamics
Battery electrolyte purity specifications from automotive OEMs are compressing supplier margins while elevating technical qualification barriers for zinc chloride producers across all major manufacturing zones.
Growth Catalysts
- Battery-grade demand surge:Lithium-ion and zinc-air battery manufacturers in China and Germany are expanding electrolyte formulation capacity, pulling high-purity anhydrous material into long-term supply agreements.
- REACH compliance premium:European REACH registration requirements for volumes exceeding one tonne annually create a documented safety moat that rewards established registrants with pricing power over non-registered imports.
- Printed circuit board fluxing:Miniaturization trends in electronics assembly are intensifying soldering flux consumption where zinc chloride serves as the active Lewis acid component.
Market Restraints
- Hydrochloric acid cost volatility:Feedstock acid prices fluctuate with chlor-alkali capacity utilization, directly pressuring production economics for acid-route manufacturers.
- Shandong supply concentration:Weifang and surrounding industrial clusters in Shandong Province account for a disproportionate share of global anhydrous output, creating geographic risk exposure.
- Aqueous grade substitution:Lower-cost zinc bromide and alternative flux chemistries are capturing price-sensitive applications in agricultural and basic industrial segments.
Strategic Opportunities
- Indian battery manufacturing:PLI scheme incentives for domestic cell production are attracting electrolyte compounders seeking localized zinc chloride supply.
- Semiconductor-grade purification:Ultra-high-purity specifications below 50 ppm total metals are opening premium positioning for producers with advanced crystallization and sublimation capabilities.
- Carbon-intensity disclosure alignment:EU CSRD and emerging automotive supply chain requirements favor producers with verified low-carbon process routes and renewable energy integration.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and coulometric Karl Fischer expertise for sub-ppm impurity detection is concentrated among a limited pool of specialized technicians.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA pre-manufacture notices, REACH dossier updates, and China MIIT GB standard compliance create overlapping regulatory burdens.
- Legacy aqueous infrastructure retrofit costs:Converting spray-dried or crystalline production lines to anhydrous sublimation systems demands substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Chloride Market |
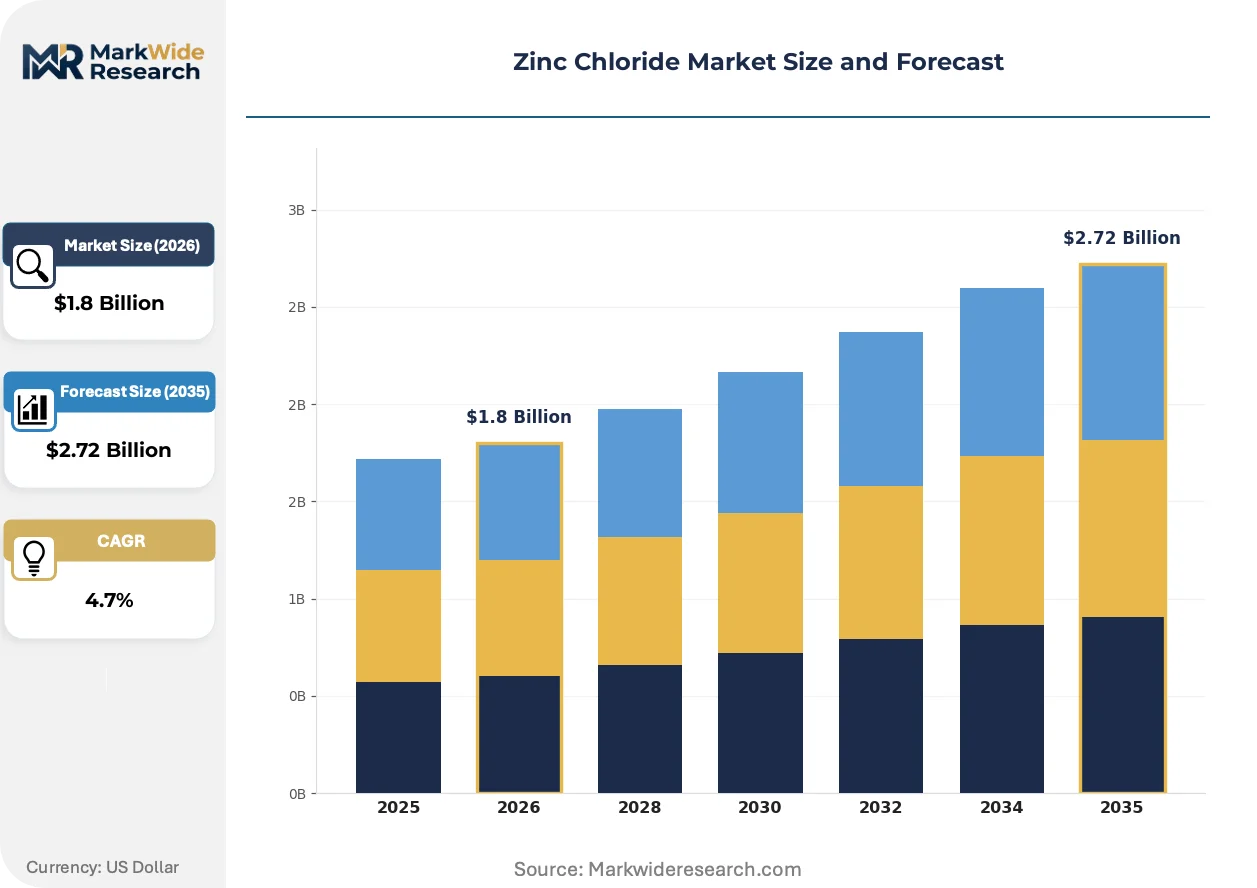
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Hexahydrate, Dihydrate, Zinc Chloride Solution Industry Vertical: Pharmaceuticals, Agriculture, Textiles, Electronics Application: Preservative, Flux, Catalyst, Chemical Intermediate Form: Solid, Liquid, Granules, Powder |
| Companies Covered | Weifang Dongfangsheng Chemical Co., Ltd., Global Chemical Co., Ltd., TIB Chemicals AG, Flaurea Chemicals, Vijaychem Industries, Zaclon LLC, Pan-Continental Chemical Co., Ltd., Tianjin Nanping Chemical Co., Ltd., American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Chloride Market Strategic Shifts
Electrolyte formulation chemistry and regulatory disclosure requirements are restructuring how zinc chloride producers qualify, price, and distribute material across battery and electronics value chains.
Membrane electrolysis-derived high-purity zinc metal is overtaking traditional thermal reduction feedstocks for battery-grade zinc chloride production. Automotive cell manufacturers in Germany and South Korea are specifying this lower-impurity route in their supplier qualification protocols. The shift is compressing acceptable heavy metal thresholds from 100 ppm to sub-10 ppm levels across the qualified supplier base.
China's MIIT GB standard revisions for industrial chemical purity are tightening moisture and insoluble matter specifications for export-grade material. Domestic producers in Shandong Province are responding with upgraded drying and packaging infrastructure to maintain overseas market access. The regulatory friction most acutely affects flux-grade shipments destined for European electronics assemblers.
Long-term offtake contracting is displacing spot market transactions in battery electrolyte supply chains. Tier-one cell producers in China and Germany are negotiating five-year supply agreements with fixed volume floors and price escalation clauses tied to energy input costs. The contracting pattern is most visible in automotive OEM direct procurement relationships where supply security outweighs price optimization.
Zinc Chloride Market Segmentation
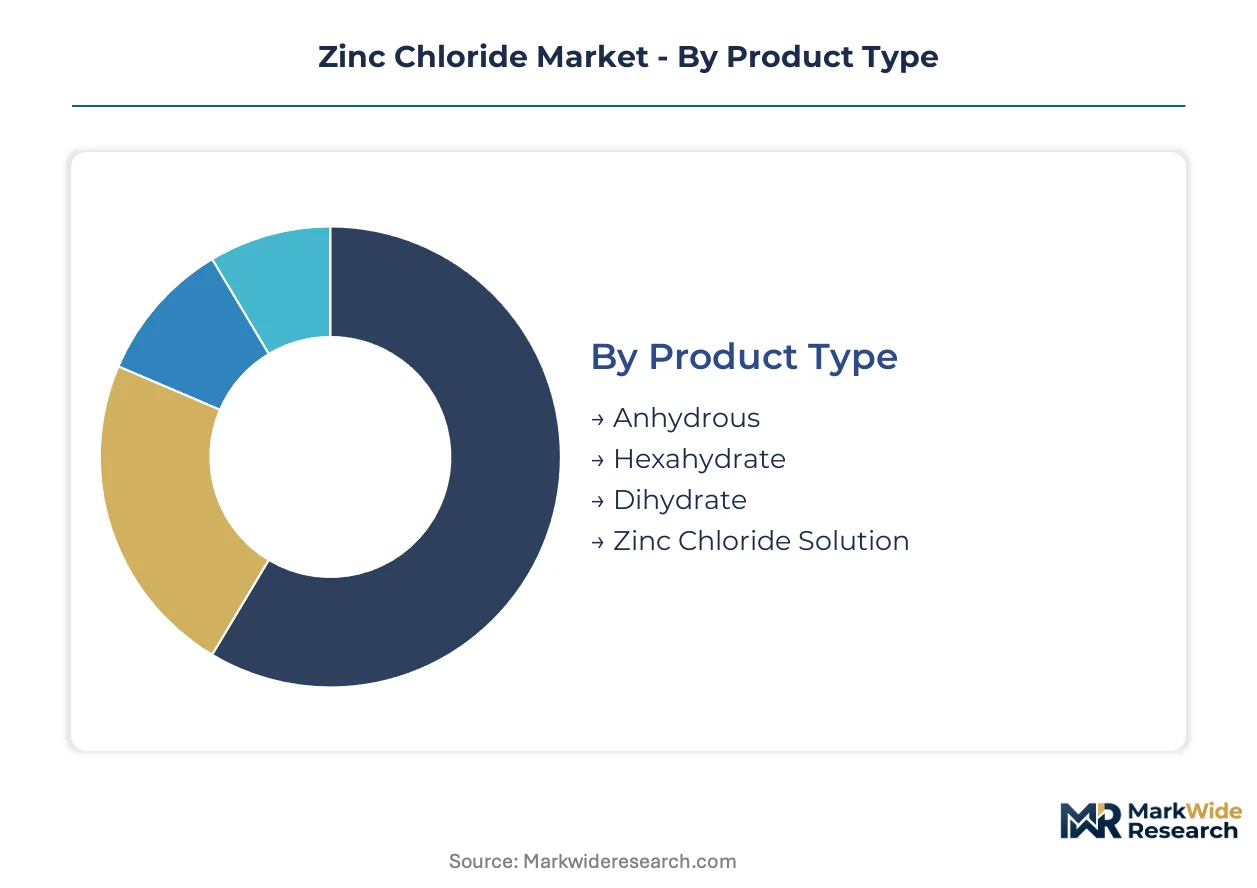
Zinc chloride procurement patterns diverge sharply across grade specifications and end-use requirements. Electronics assemblers and battery manufacturers impose purity thresholds that filter supplier eligibility, while agricultural and textile buyers prioritize cost efficiency over analytical precision.
Product Type:
Supply concentration in Shandong Province tilts competitive dynamics toward anhydrous grades with sub-2% moisture specifications.
- Anhydrous:White crystalline solids produced via zinc metal or zinc oxide reaction with hydrochloric acid, demanding sealed packaging against hygroscopic degradation. Battery electrolyte compounders in Germany and China specify this grade for lithium-ion and zinc-air cell formulations where moisture content below 0.5% determines cell cycle life.
- Hexahydrate:Crystalline hydrate form with defined water content, serving pharmaceutical synthesis and laboratory reagent markets where solubility control matters more than absolute dryness. European REACH registrants capture premium positioning through documented impurity profiles.
- Dihydrate:Intermediate hydration state for cost-sensitive flux applications.
- Zinc Chloride Solution:Pre-dissolved aqueous format for wood preservative dipping and textile processing baths.
Today's leader: Anhydrous. Tomorrow's challenger: Hexahydrate.
Industry Vertical:
Margin pools concentrate where purity thresholds intersect with regulatory documentation burdens.
- Electronics:Printed circuit board manufacturers consume high-purity material for soldering flux where Lewis acid activity enables oxide removal at miniaturized joint scales. Automotive cell producers in South Korea and Germany are specifying sub-10 ppm heavy metal thresholds that compress the qualified supplier base.
- Pharmaceuticals:GMP-compliant grades for active pharmaceutical ingredient synthesis and catalyst recovery systems. FDA and EMA inspection protocols elevate documentation requirements above industrial chemical norms.
- Agriculture:Soil micronutrient delivery and animal feed supplementation represent mature volume channels with stable offtake and price-sensitive procurement.
- Textiles:Mercerizing agent for cotton fiber treatment and dye fixation processes.
Electronics commands the steepest expansion trajectory. Pharmaceuticals offers defensive margin stability.
Application:
Functional chemistry requirements stratify supplier qualification pathways.
- Flux:Active component in soldering formulations where oxide dissolution kinetics determine joint reliability. Electronics miniaturization trends intensify consumption as pad sizes shrink and thermal profiles tighten.
- Catalyst:Lewis acid applications in Friedel-Crafts alkylation and polymerization chemistry. Pharmaceutical manufacturers favor this route for stereoselective synthesis steps.
- Preservative:Wood treatment and textile rot resistance where aqueous solution delivery dominates.
- Chemical Intermediate:Feedstock for zinc phosphide production and organozinc reagent synthesis.
Flux applications anchor current volume. Catalyst demand is climbing fastest on pharmaceutical outsourcing trends.
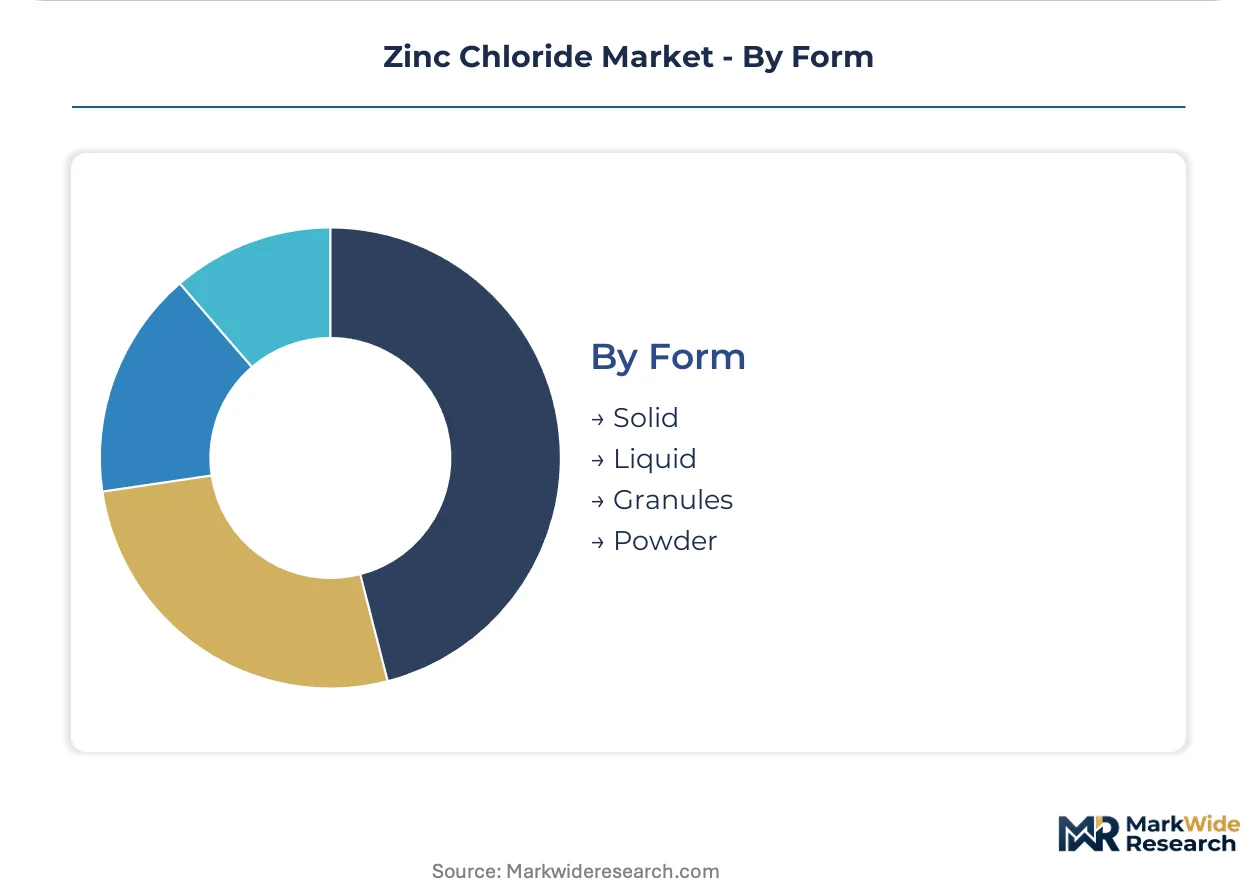
Form:
Physical state selection tracks handling economics and dissolution kinetics.
- Solid:Crystalline or fused masses for controlled dissolution in batch chemical processing.
- Liquid:Pre-formulated aqueous solutions for wood treatment and textile mercerizing where concentration standardization reduces on-site handling.
- Granules:Free-flowing particulate for agricultural spreader application and dust-controlled industrial handling.
- Powder:Fine particulate for rapid dissolution in pharmaceutical and laboratory settings where batch time minimization matters.
Liquid formulations lead on handling convenience. Granules are gaining share fastest in agricultural mechanization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province concentrates the bulk of global anhydrous zinc chloride capacity, with Weifang industrial clusters supplying battery-grade material to German and South Korean cell manufacturers. Demand dispersion across electronics, battery electrolyte, and flux applications creates distinct procurement patterns in each major consuming zone.
China
Battery electrolyte compounders in Jiangsu and Guangdong provinces are pulling anhydrous grades into long-term supply agreements with automotive OEMs. MIIT GB standard revisions are tightening moisture specifications for export-grade material. Shandong Province producers are upgrading drying infrastructure to maintain European electronics market access.
Germany
Automotive cell manufacturers in Baden-Württemberg and Bavaria are specifying sub-10 ppm heavy metal thresholds that compress qualified supplier bases. REACH registration requirements create documented safety moats rewarding established registrants. Ludwigshafen and surrounding chemical clusters anchor specialty flux formulation for miniaturized electronics assembly.
United States
Semiconductor and research applications in California and Texas are driving ultra-high-purity demand below 50 ppm total metals. EPA TSCA pre-manufacture notices govern new production capacity and workplace exposure limits. Gulf Coast chlor-alkali corridors feed hydrochloric acid supply chains for domestic zinc chloride manufacturing.
India
PLI scheme incentives for domestic battery cell production are attracting electrolyte compounders seeking localized supply. BIS standards for industrial chemical purity shape import substitution dynamics. Gujarat and Maharashtra industrial corridors are emerging as procurement hubs for flux-grade material serving electronics assembly expansion.
South Korea
Automotive battery producers in Gyeonggi and Chungcheong provinces are qualifying membrane-electrolysis derived feedstocks for premium electrolyte formulations. MFDS pharmaceutical standards create parallel demand channels for GMP-compliant hexahydrate grades. Busan-Ulsan chemical complexes support backward integration into high-purity zinc metal processing.
Zinc Chloride Market Competitive Environment
Long-term offtake contracting dominates the current landscape as tier-one cell producers negotiate five-year supply agreements with fixed volume floors. The supplier base stratifies across integrated chemical conglomerates, regional specialty producers, and ultra-high-purity specialists. Three archetypes occupy distinct positions: Shandong-based scale producers serving commodity flux markets, European REACH-registered registrants capturing compliance premiums, and North American purification specialists targeting semiconductor applications. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers align with automotive supply chain carbon-intensity disclosure requirements.
Among Chinese producers, Weifang Dongfangsheng Chemical Co., Ltd. and Tianjin Nanping Chemical Co., Ltd. occupy positions within the scale-driven archetype serving battery and flux demand. TIB Chemicals AG represents the European REACH-registered tier where documentation moats sustain pricing power. American Elements sits within the ultra-high-purity specialist segment where sub-ppm impurity detection capabilities filter competitive entry. These three anchors illustrate how geographic concentration, regulatory compliance, and technical capability stratify supplier positioning across the value chain.
| Leading Market Players |
|---|
| Weifang Dongfangsheng Chemical Co., Ltd. |
| Global Chemical Co., Ltd. |
| TIB Chemicals AG |
| Flaurea Chemicals |
| Vijaychem Industries |
| Zaclon LLC |
| Pan-Continental Chemical Co., Ltd. |
| Tianjin Nanping Chemical Co., Ltd. |
| American Elements |
| Others |
Value Chain & Pricing Dynamics
ICP-MS and coulometric Karl Fischer specialists concentrated in Germany and South Korea command wage premiums that widen spreads between battery-grade and flux-grade pricing tiers. This analytical chemistry scarcity in Shandong Province compresses margins for producers attempting REACH qualification without European laboratory partnerships.
Pricing Analysis
Input-cost pass-through from hydrochloric acid volatility dominates pricing dynamics for acid-route manufacturers. Three-tier pricing structure across battery-grade, flux-grade, and agricultural-grade levels separates qualified automotive suppliers from basic industrial offtakers. Cost compression in flux-grade material is intensifying because zinc bromide substitution erodes price floors in agricultural applications. Agricultural buyers exhibit highest price sensitivity, while automotive cell manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
REACH registration and MIIT GB standard compliance function as qualification gates that filter supplier eligibility for European and Chinese battery manufacturers respectively. Production concentrates in China, Germany, and India, with raw material dependencies spanning membrane-electrolysis zinc metal, hydrochloric acid, and specialized desiccant packaging. Single-source vulnerability runs through Shandong Province's anhydrous capacity cluster. Distribution feeds through long-term offtake contracts with automotive OEMs and spot transactions for agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where REACH registration costs in Europe create compliance moats that sustain premium capture against non-registered Chinese imports.
For Market Incumbents: To counter aqueous-grade substitution in price-sensitive agricultural segments, incumbents should deepen backward integration into membrane-electrolysis zinc metal processing and expand anhydrous sublimation capacity in Baden-Württemberg to serve German automotive qualification protocols. For New Entrants and Emerging Players: Capture white-space in Indian battery electrolyte compounding under PLI scheme incentives, targeting Gujarat industrial corridors with localized flux-grade supply to electronics assemblers expanding domestic manufacturing. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing REACH portfolios are the most active acquirers in this space, seeking bolt-on anhydrous capacity. Long-term viability hinges on carbon-intensity disclosure alignment across automotive supply chains. Watch for MIIT GB standard revisions tightening export specifications as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane-Electrolysis Zinc Metal | Automotive OEMs in Germany specify this feedstock route for sub-10 ppm heavy metal compliance. |
| REACH Dossier Expansion for Battery-Grade Volumes | ECHA registration above one tonne annually creates documented safety moats against import competition. |
| Anhydrous Sublimation Capacity Addition | Shandong producers upgrade drying infrastructure to maintain European electronics market access. |
| Long-term Supply Agreement with Automotive Tier Ones | Five-year contracts with fixed volume floors displace spot transactions in electrolyte supply chains. |
| Joint Venture with Indian Electrolyte Compounders | PLI scheme incentives attract localized production to serve Maharashtra and Gujarat battery hubs. |
Study Parameters
Coverage spans China, Germany, India, and the United States, with primary inputs from each territory combining interviews with plant managers at anhydrous production facilities, procurement leads at battery electrolyte compounders, technical R&D directors specializing in Lewis acid catalyst applications, and distribution channel partners serving agricultural micronutrient markets. Secondary validation draws from MIIT GB standard filings, ECHA REACH registration databases, EPA TSCA pre-manufacture notices, and customs trade data for zinc chloride import volumes. Bottom-up capacity assessments and top-down demand triangulation anchor value estimates.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions include grade tier (anhydrous, hexahydrate, aqueous solution), end-use industry (electronics, pharmaceuticals, agriculture), and regional production hub. CAGRs derive from regression against battery manufacturing capacity expansion, electronics assembly output, and agricultural micronutrient consumption trends. Forecast inputs incorporate automotive OEM electrolyte purity specifications and evolving carbon-intensity disclosure requirements.
Underlying measurement precision varies by segment; battery-grade volumes carry tighter precision than agricultural applications due to concentrated buyer transparency. Forecasts reflect assumptions about REACH enforcement continuity, chlor-alkali capacity utilization, and automotive cell manufacturing localization patterns. A model refresh is warranted upon material change in MIIT GB standard revision timelines or automotive supply chain carbon accounting protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
North America Carbon Black Market