
 Elemental Sulfur Market | 2026-2036
Elemental Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Elemental Sulfur Market Intelligence
The EU's REACH regulation is hardening market access for non-compliant sulfur producers by mandating extensive safety data. This increases the operational burden for smaller suppliers. Saudi Aramco leverages its vast oil refining capacity to maintain a dominant position in byproduct sulfur supply. Nutrien Ltd. specializes in downstream fertilizer production, creating captive demand for the element. China Petrochemical Corporation controls significant refining and chemical assets in Asia.
Elemental sulfur is a non-metallic chemical element, typically recovered as a byproduct of oil refining and natural gas processing with purities exceeding 99.5%. Its primary industrial use is as a raw material for producing sulfuric acid, a critical component in numerous chemical processes. Granular sulfur holds the largest market share due to its ease of handling and transportation for agricultural applications. The chemicals segment represents the core demand driver, while its use in rubber production offers a stable, albeit smaller, market niche.
Market operations are shaped by environmental regulations governing sulfur dioxide emissions, enforced by agencies like the U.S. EPA and China's MEE. Concurrently, the EU's ECHA oversees chemical safety standards under REACH, impacting import and handling protocols for sulfur products. Stakeholder success will depend on navigating the dual pressures of stringent environmental compliance and fluctuating supply dynamics from the energy sector.
Market Dynamics
The market's core dynamic is the interdependence between byproduct supply from the energy sector and concentrated demand from agriculture. This relationship subjects elemental sulfur pricing and availability to volatility from two often uncorrelated global industries, creating persistent structural uncertainty.
Growth Catalysts
- Phosphate Fertilizer Demand:The essential role of sulfur in producing phosphate fertilizers to enhance crop yields and improve food security remains the primary demand driver, particularly in regions with expanding agricultural sectors.
- Stringent Fuel Standards:Regulations like IMO 2020, which mandate low-sulfur fuels for shipping, increase the volume of sulfur recovered at oil refineries, expanding the available byproduct supply for industrial and agricultural consumers.
- Chinese Industrialization:China's vast industrial base, encompassing chemicals, metals, and manufacturing, combined with its significant agricultural needs, solidifies its position as the world's principal consumption hub for elemental sulfur.
Market Restraints
- Supply Volatility:As a byproduct of oil and gas processing, elemental sulfur supply is inelastic and dependent on hydrocarbon production levels, making it vulnerable to geopolitical events and energy market fluctuations.
- Regulatory Compliance Costs:The European Union's REACH regulation imposes significant data submission and registration costs, creating a high barrier to entry for smaller producers and exporters lacking extensive compliance resources.
- Logistics Intensity:The high cost and complexity of transporting and storing a bulk, low-value, and potentially hazardous commodity can limit market reach and make locally sourced alternatives more competitive in certain regions.
Strategic Opportunities
- Advanced Battery Technology:The development of next-generation energy storage, specifically lithium-sulfur (Li-S) batteries, presents a high-value, long-term opportunity for purified sulfur as a critical cathode material.
- Nutrient-Deficient Soils:Targeting agricultural markets in Sub-Saharan Africa and Southeast Asia, where soils are often sulfur-deficient, offers significant growth potential for specialized sulfur-enhanced fertilizers.
- Value-Added Sulfur Forms:Innovation in sulfur forming technologies to create dust-free, high-purity granules or specialized micronized sulfur products for niche industrial and agricultural applications can command premium pricing.
Industry Challenges
- Environmental Control Investment:Meeting strict sulfur dioxide (SO2) emission limits set by regulators like the U.S. EPA and China's MEE requires continuous, significant capital expenditure on scrubbers and recovery units at processing facilities.
- Handling and Logistics Safety:Managing the risks associated with sulfur handling, including dust explosion hazards and hydrogen sulfide gas exposure, necessitates specialized infrastructure, equipment, and extensive worker training across the supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elemental Sulfur Market |
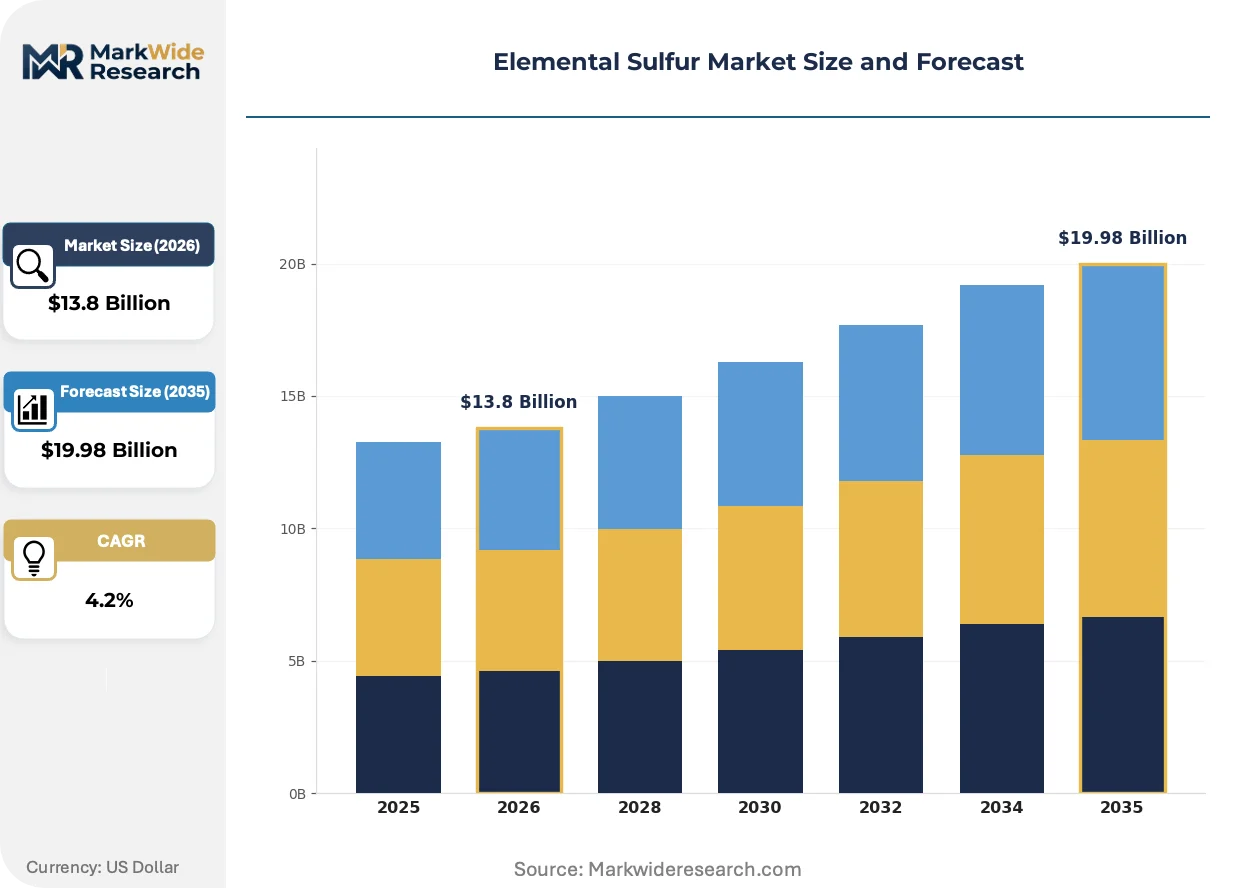
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Sulfur, Liquid Sulfur, Powdered Sulfur, Rollover Sulfur Application: Agriculture, Chemicals, Pharmaceuticals, Rubber Production End User: Chemical Manufacturers, Fertilizer Producers, Oil Refineries, Pulp and Paper Industry Distribution Channel: Direct Sales, Distributors, eCommerce, Retail Trade |
| Companies Covered | China Petrochemical Corporation, Valero, Saudi Aramco, Nutrien Ltd., Mosaic Company, Shell, Suncor Energy Inc., Georgia Gulf Sulfur Corporation, ADNOC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elemental Sulfur Market Strategic Shifts & Innovations
The evolution of the elemental sulfur market is defined by a push for greater value extraction from what is fundamentally a byproduct stream. This drive manifests in process innovations, responses to environmental policy, and shifts in agricultural purchasing behavior.
Advanced forming technologies convert molten sulfur into solid shapes like granules or pastilles. Agricultural and chemical producers are rapidly adopting these forms to mitigate dust hazards and streamline logistics. This technological shift is modularizing the supply chain, enabling more flexible, containerized shipping and reducing reliance on specialized bulk handling infrastructure.
Global mandates for low-sulfur transportation fuels, exemplified by the IMO 2020 standard, directly influence the supply side. These policies force oil refineries to invest in hydrodesulfurization units, which boosts the recovery of byproduct elemental sulfur. The oil and gas sector is most impacted, turning a waste management issue into a significant commodity stream that alters global trade flows.
A notable shift is occurring in agricultural procurement, where large farming cooperatives and agribusinesses now specify sulfur as a distinct component in soil nutrient programs. This disrupts the traditional model of selling sulfur primarily to large-scale sulfuric acid manufacturers. This pattern is most pronounced in North America and Europe, where precision agriculture drives demand for customized fertilizer blends.
Elemental Sulfur Market Segmentation
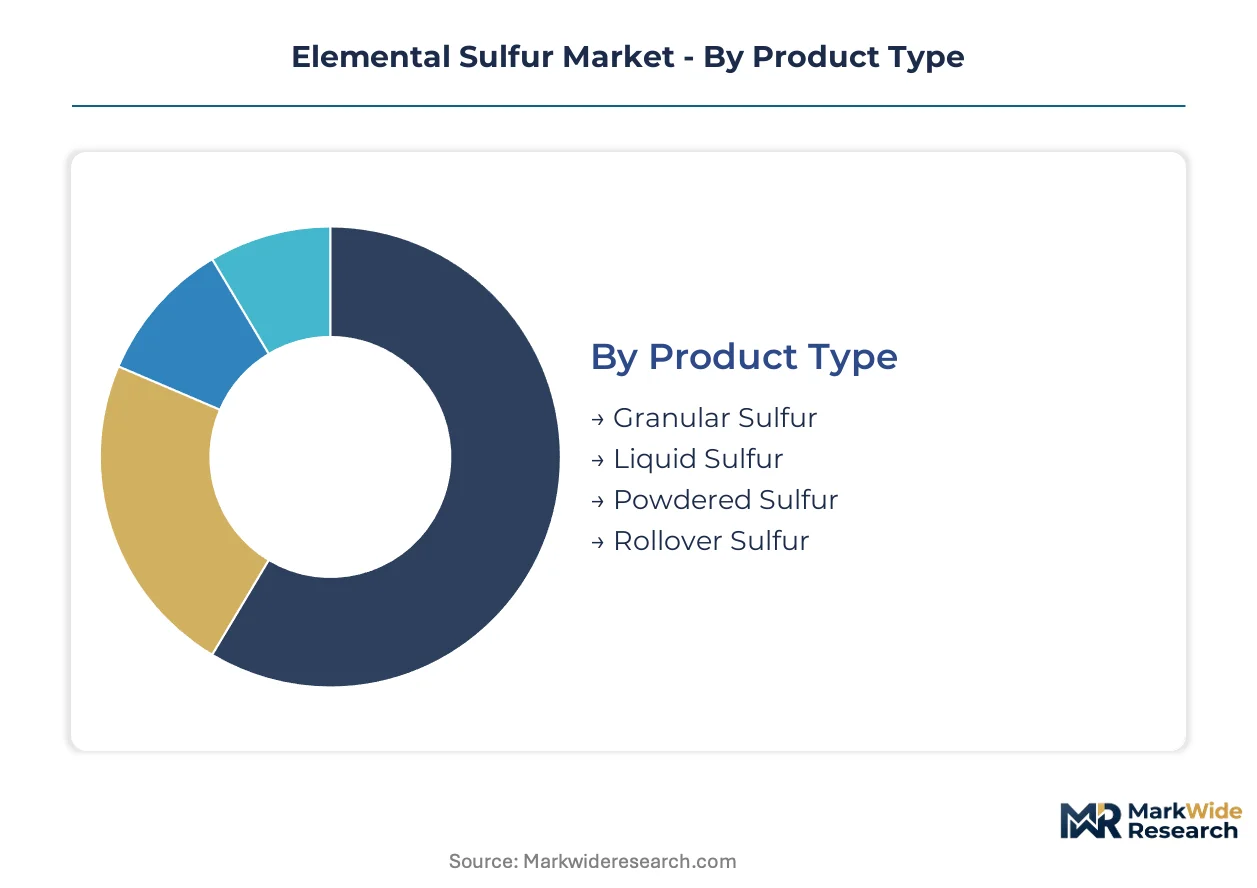
The elemental sulfur market segmentation provides a granular view of how this critical industrial commodity is categorized by its physical form, primary applications, and diverse end-user industries. This detailed breakdown clarifies the distinct demand drivers and supply chain dynamics influencing different market segments. Understanding these segments assists stakeholders in identifying specific growth pockets and operational challenges within the broader market.
Product Type:
Elemental sulfur product types range from directly usable forms to those requiring further processing for integration into industrial applications.
- Granular Sulfur:This solid form involves converting molten sulfur into uniform pellets, significantly reducing dust hazards and improving handling. Its ease of transportation and storage makes it the preferred form for large-scale agricultural applications in China.
- Liquid Sulfur:Molten sulfur, maintained at elevated temperatures, offers high purity and direct integration into sulfuric acid production processes. Chemical manufacturers in the United States utilize liquid sulfur for continuous process streams.
- Powdered Sulfur:Micronized sulfur finds specialized use in rubber vulcanization and certain agricultural fungicides, requiring fine particle size for efficacy.
- Rollover Sulfur:This term refers to sulfur that remains unsold from previous periods, impacting inventory levels and future supply availability for global markets.
Volume placements concentrate in Granular Sulfur; the faster expansion belongs to Liquid Sulfur.
Application:
Applications for elemental sulfur span from high-volume, cost-sensitive commodity production to specialized, higher-margin industrial processes.
- Agriculture:Sulfur is a critical nutrient for crop growth and a key raw material for phosphate fertilizer production, enhancing yields across vast farmlands. Demand is particularly strong in nutrient-deficient soils across Sub-Saharan Africa and Southeast Asia.
- Chemicals:This segment represents the largest industrial use, primarily for manufacturing sulfuric acid, a foundational chemical in numerous industrial processes. China's expansive industrial base drives significant chemicals sector demand.
- Pharmaceuticals:Elemental sulfur is used in some dermatological preparations and as a precursor in specific pharmaceutical synthesis routes, serving a niche, high-purity requirement.
- Rubber Production:Sulfur acts as a vulcanizing agent, cross-linking polymer chains to enhance rubber's durability and elasticity for tire and industrial product manufacturing.
The agriculture sector consumes the largest volumes, while pharmaceutical applications exhibit specialized demand profiles.
End User:
End-user segments for elemental sulfur are differentiated by their consumption scale and the specific purity requirements for their industrial processes.
- Chemical Manufacturers:These entities consume vast quantities of elemental sulfur to produce sulfuric acid, a versatile chemical used in metal processing, detergents, and water treatment. Saudi Aramco's byproduct sulfur often supplies these large-scale operations.
- Fertilizer Producers:Companies like Nutrien Ltd. convert elemental sulfur into phosphate fertilizers, directly addressing global food security needs by enriching agricultural soils. This end-user group forms a captive demand base for sulfur.
- Oil Refineries:While primarily sulfur suppliers, some refineries use elemental sulfur in alkylation processes or for specific in-house chemical syntheses.
- Pulp and Paper Industry:This industry utilizes sulfur compounds in the kraft pulping process to separate cellulose fibers, contributing to a stable, albeit smaller, demand stream.
Fertilizer producers and chemical manufacturers collectively account for the predominant share of elemental sulfur consumption.
Distribution Channel:
Elemental sulfur reaches its diverse customer base through channels ranging from direct industrial supply agreements to more fragmented retail networks.
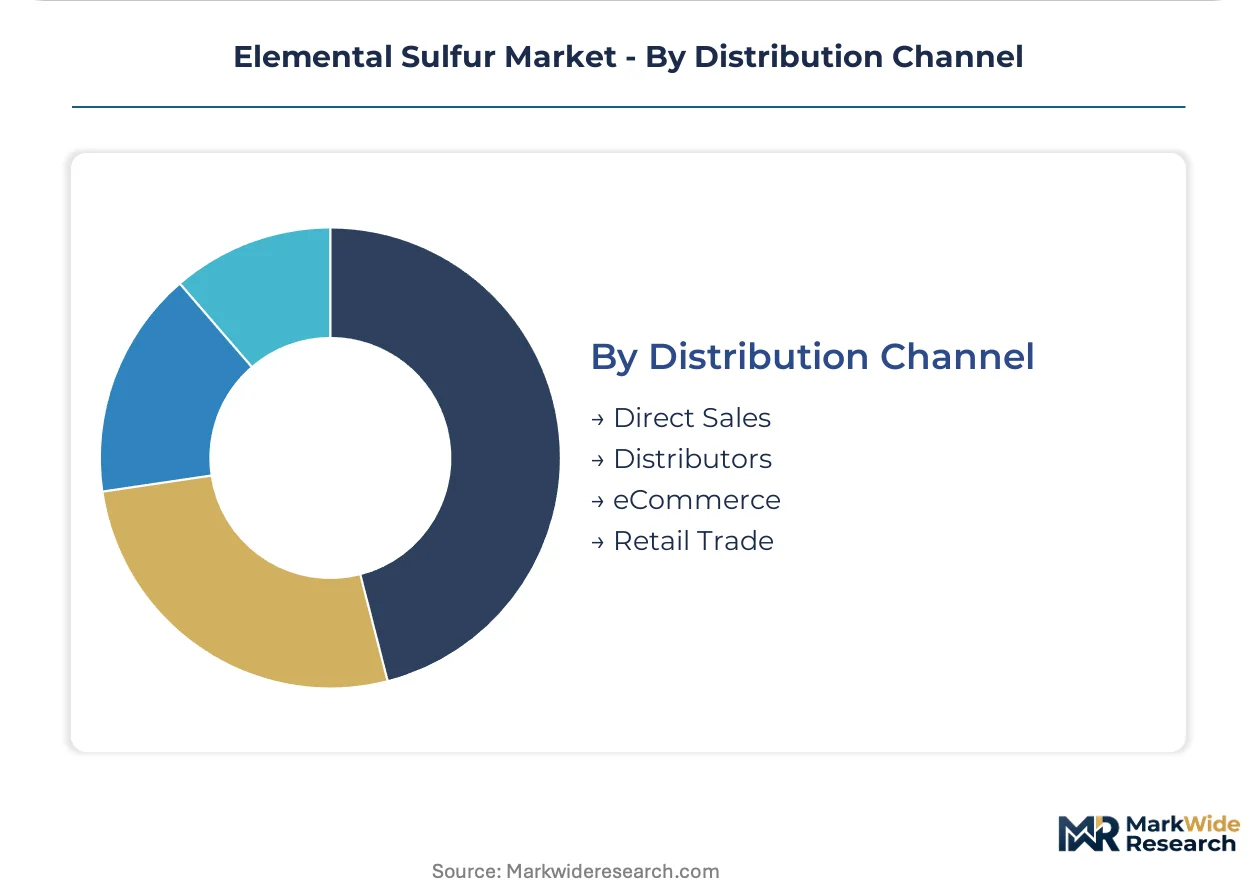
- Direct Sales:Large-volume contracts between major producers and industrial consumers, such as chemical giants or fertilizer companies, characterize this channel. This ensures consistent supply for continuous manufacturing operations in Europe.
- Distributors:These intermediaries manage logistics and supply smaller to medium-sized industrial clients, often providing inventory management and regional delivery services. Distributors serve diverse agricultural cooperatives in India.
- eCommerce:Online platforms facilitate procurement for specialized sulfur products or smaller batch orders, offering convenience for niche industrial buyers or research institutions.
- Retail Trade:Limited retail presence exists for small quantities of sulfur, typically for gardening, pest control, or specialized home applications through agricultural supply stores.
Direct sales channels dominate high-volume transactions, while distributors cater to fragmented regional demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental sulfur demand concentrates significantly in regions with robust agricultural and industrial sectors. China, with its vast agricultural needs and expansive chemical manufacturing base, anchors global consumption. Other key regions balance byproduct supply from energy sectors with diverse industrial applications and environmental compliance requirements.
China
China's expansive agricultural sector drives substantial demand for phosphate fertilizers. The Ministry of Ecology and Environment (MEE) enforces strict environmental regulations on industrial emissions. Chemical producers in the Yangtze River Delta utilize significant volumes for sulfuric acid manufacturing.
United States
The U.S. agriculture sector demands sulfur as a vital crop nutrient, alongside its use by chemical manufacturers. The U.S. Environmental Protection Agency (EPA) mandates stringent sulfur dioxide emission limits. Molten sulfur from Gulf Coast refineries supplies continuous process streams for chemical plants.
Saudi Arabia
Saudi Arabia represents a major supply hub for elemental sulfur, primarily from its extensive oil refining operations. The Kingdom's environmental policies prioritize resource utilization from hydrocarbon byproducts. Industrial zones like Jubail concentrate large-scale chemical manufacturing and export terminals.
India
India's agricultural sector exhibits strong demand for sulfur-enhanced fertilizers, especially for nutrient-deficient soils. Government initiatives promoting food security bolster fertilizer consumption across the country. Distributors in Maharashtra manage logistics for delivering sulfur to diverse agricultural cooperatives.
Germany
Germany's advanced chemical industry requires elemental sulfur for numerous manufacturing processes. The European Chemicals Agency (ECHA) oversees REACH compliance, impacting import and handling protocols. Chemical manufacturers in the Rhine-Ruhr region secure consistent supply for continuous operations.
Elemental Sulfur Market Key Industry Players
Saudi Arabian producers anchor one tier of elemental sulfur supply; North American specialists hold significant downstream processing capabilities. The market structure is tiered, with large-scale byproduct suppliers at the top and specialized downstream processors forming another segment. Strategic archetypes include integrated oil and gas majors, dedicated fertilizer producers, and regional chemical manufacturers. Capacity expansion in refining and strategic partnerships for distribution characterize competitive moves.
Among integrated oil and gas producers, Saudi Aramco exemplifies a dominant position in byproduct sulfur supply, leveraging its vast refining capacity. This company anchors a substantial portion of global sulfur availability. China Petrochemical Corporation, a Chinese entity, occupies a similar position, utilizing extensive refining and chemical assets to serve its domestic market and broader Asian demand. Nutrien Ltd., a Canadian company, sits within the fertilizer producer archetype, creating captive demand for elemental sulfur through its significant downstream operations and agricultural focus.
| Leading Market Players |
|---|
| China Petrochemical Corporation |
| Valero |
| Saudi Aramco |
| Nutrien Ltd. |
| Mosaic Company |
| Shell |
| Suncor Energy Inc. |
| Georgia Gulf Sulfur Corporation |
| ADNOC Group |
| Others |
Cost & Logistics Intelligence
Skilled personnel for hazardous material handling in Europe, where labor costs are higher, create distinct pricing tiers for specialized sulfur forms. This cost differential influences market access for various product types and end-user segments.
Pricing Analysis
High-volume commodity sulfur commands thin margins, while specialized, lower-volume forms achieve premium pricing. The market predominantly operates on commodity spot and contract-based long-term offtake models. Price differentiation stems from purity requirements and specialized forming technologies like pastilles. Pricing softness reflects fluctuating supply dynamics from the energy sector. Agricultural buyers exhibit high price sensitivity, contrasting with pharmaceutical users who prioritize purity over cost.
Supply Chain Analysis
Buyers often mandate dual-sourcing strategies to mitigate risks inherent in elemental sulfur supply from geopolitical events. Geographic supply concentrates heavily in Saudi Arabia, China, and the United States, driven by extensive oil and gas processing. The supply chain relies on crude oil and natural gas extraction as primary inputs. Commodity price volatility in the energy sector poses a significant structural risk. Distribution runs through direct sales for major industrial consumers and regional distributors for agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elemental sulfur market is becoming a consolidation play, as stringent environmental compliance costs force smaller, non-compliant producers to exit. This creates opportunities for larger, more resilient industry participants.
For Market Incumbents: Lock in long-term supply agreements with major agricultural and chemical off-takers to secure demand. Incumbents must also invest in advanced forming technologies to enhance product handling and logistics efficiency. This defends against margin pressure from fluctuating supply dynamics. Deepening vertical integration into downstream fertilizer production, as seen with Nutrien Ltd., provides captive demand and market stability.
For New Entrants and Emerging Players: A significant price-point gap exists between high-purity pharmaceutical-grade sulfur and bulk commodity forms. New entrants should target specialized sulfur-enhanced fertilizers for nutrient-deficient soils in Sub-Saharan Africa and Southeast Asia. This offers a white-space opportunity for value-added products. A focused go-to-market angle involves collaborating with local agricultural cooperatives to demonstrate yield improvements from customized fertilizer blends.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated fertilizer producers given the stable, growing demand for agricultural inputs. The elemental sulfur market exhibits long-term viability over the next decade, anchored by food security needs. Investors should target specialized chemical manufacturers with proprietary forming technologies or strong regional distribution networks. The signal to watch is the commercialization timeline and scaling of lithium-sulfur battery production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Saudi Aramco's refining capacity directly influences global byproduct sulfur supply. |
| Long-term Supply Agreement | Nutrien Ltd. secures consistent sulfur input for its phosphate fertilizer production. |
| Green Manufacturing Transition | Compliance with China's MEE SO2 emission limits requires significant capital expenditure. |
| Joint Venture | Regional distributors in India can enhance last-mile delivery to agricultural cooperatives. |
| Product Line Diversification | Elemental sulfur can become a critical cathode material for advanced battery technology. |
Research Approach
Document review covered customs trade data and regulatory filings from the U.S. EPA and China's MEE, complemented by interviews with industry stakeholders. Primary interviews included refinery operations managers, chemical procurement leads, and agricultural cooperative directors. This primary research was triangulated with secondary validation from company financial reports. Bottom-up and top-down approaches validated the data.
The quantitative model produced granular volume and value projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and regional production hubs. Compound annual growth rates were derived from historical trends and future demand forecasts. Key industry-specific inputs included crude oil production levels and agricultural fertilizer consumption rates.
Inputs from major refinery output reports and agricultural demand surveys were available through the study window; gaps in emerging battery technology adoption rates introduce uncertainty bands. Forecasts reflect documented assumptions. Deviation in global energy policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Propionic Acid Market