
 Sodium Ferrocyanide Market | 2026-2036
Sodium Ferrocyanide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Ferrocyanide Market Analytics
Technical service and formulation support is broadening what sodium ferrocyanide suppliers monetize beyond commodity tonnage. Evonik Industries AG leverages its specialty chemicals heritage to anchor premium-grade supply relationships with European pharmaceutical manufacturers. Gujarat Alkalies and Chemicals Ltd (GACL) sustains cost leadership through integrated chlor-alkali operations that feed captive cyanide chemistry. Hebei Chengxin competes on scale in industrial-grade powder, occupying the densest cluster of Chinese pigment and dye demand.
Sodium ferrocyanide, Na4Fe(CN)6·10H2O, is a yellow crystalline coordination compound produced via the reaction of ferrous salts with sodium cyanide in aqueous solution, serving primarily as an anti-caking agent, precursor to Prussian blue pigments, and intermediate in pharmaceutical synthesis. Industrial-grade material dominates volume due to its entrenched role in textile dye baths and electroplating formulations, while pharmaceutical-grade commands the densest margin pool as purity specifications tighten under pharmacopeial standards. The food-grade segment remains structurally constrained by regulatory caps on permissible cyanide complex residues, limiting expansion to markets with explicit additive approvals.
The US EPA regulates cyanide-bearing compounds under the Clean Water Act and Toxic Substances Control Act, shaping permissible discharge thresholds and facility siting decisions for domestic producers. REACH registration requirements in Europe compel full toxicological dossiers for ferrocyanide salts, elevating compliance costs for importers and favoring established registrants like Evonik. China's Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity benchmarks for cyanide-derived chemical production. Stakeholders must monitor evolving hazard classifications under the UN Globally Harmonized System, as reclassification would cascade into revised shipping restrictions, storage protocols, and end-use liability frameworks across jurisdictions.
Market Dynamics
China's Ministry of Ecology and Environment enforcement of dual carbon goals is forcing cyanide derivative producers toward closed-loop manufacturing systems, redrawing cost structures and supplier viability across the sodium ferrocyanide value chain.
Growth Catalysts
- Pharmaceutical-grade specifications:Tightening pharmacopeial purity standards in injectable iron therapies and diagnostic reagents is pulling demand toward higher-margin material. European and Indian formulators are expanding ferrocyanide offtake for these applications.
- REACH registration completion:Full toxicological dossier acceptance under EU chemicals regulation has stabilized import pathways for established registrants, reducing competitive friction from unregistered Asian suppliers.
- India's captive capacity buildout:Domestic chlor-alkali producers are integrating backward into ferrocyanide production to serve downstream dye and pigment operations, compressing import dependency.
Market Restraints
- Sodium cyanide feedstock volatility:Hydrogen cyanide pricing swings and transport security requirements for this highly toxic input create margin unpredictability for non-integrated producers.
- Food-grade regulatory caps:FSSAI in India and FDA in the United States impose strict residue limits on cyanide complex additives, structurally constraining expansion in anti-caking applications.
- Prussian blue substitution in pigments:Organic pigment chemistries and alternative inorganic blues are displacing ferrocyanide-derived Prussian blue in select coating applications.
Strategic Opportunities
- Battery-grade material qualification:Sodium iron ferrocyanide analogs for sodium-ion battery cathodes present a white-space application as cell manufacturers diversify beyond lithium chemistries.
- Closed-loop cyanide recovery systems:MEE enforcement in China is creating technology licensing demand for producers capable of near-zero discharge ferrocyanide manufacturing.
- Direct pharmaceutical contracting:Bypassing merchant chemical distributors to establish long-term supply agreements with European and North American API manufacturers secures volume visibility.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation for pharmaceutical-grade material requires 18-24 month validation cycles, delaying revenue recognition for new entrants.
- Specialized cyanide chemistry expertise:Ferrocyanide synthesis and safety engineering talent pools are thinning as veteran operators retire without sufficient replacement training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Ferrocyanide Market |
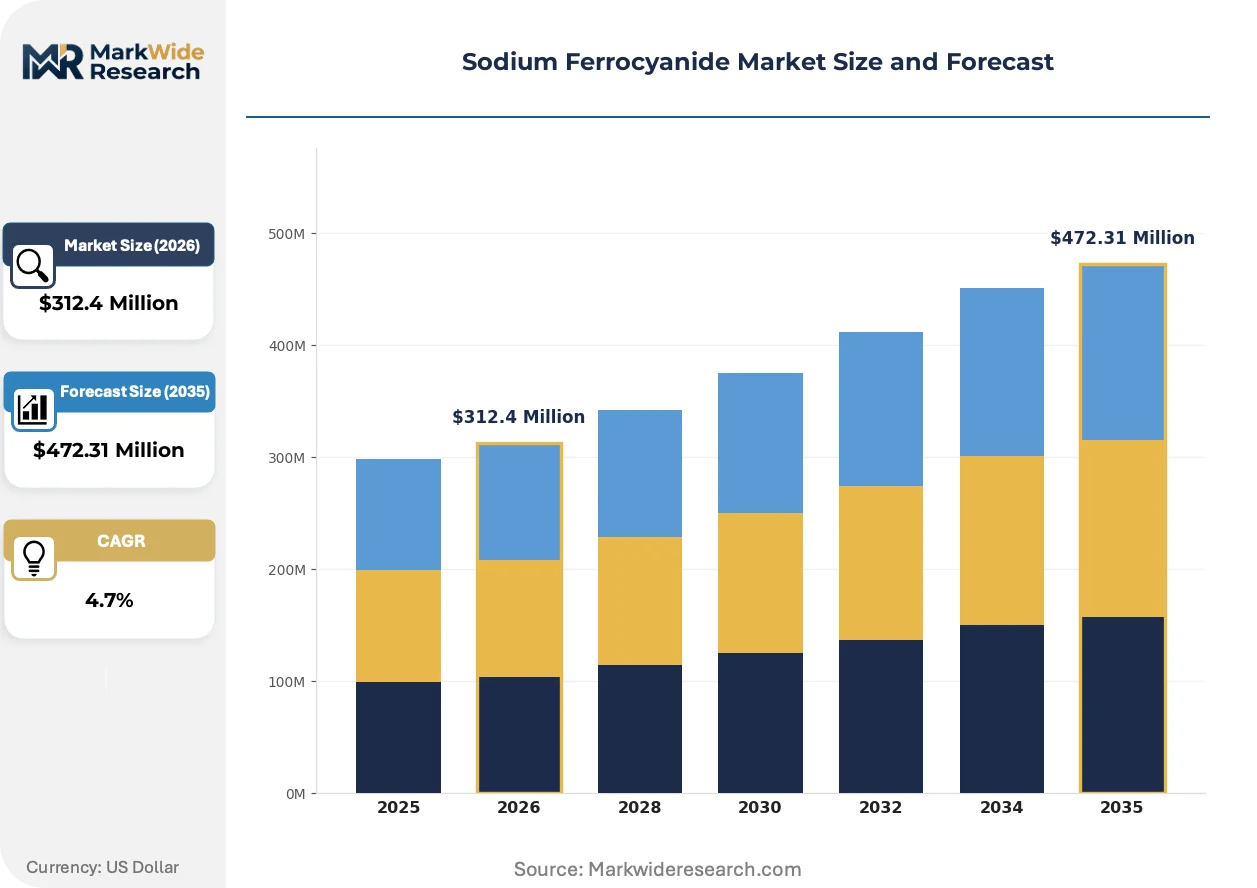
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Laboratory Grade Application: Dyes, Pigments, Electroplating, Pharmaceuticals End User: Chemical Manufacturers, Textile Industry, Food Industry, Pharmaceutical Companies Form: Granules, Powder, Liquid, Crystals |
| Companies Covered | Gujarat Alkalies and Chemicals Ltd (GACL), Evonik Industries AG, Ziguang Chemical, Changzhou Xudong, Sichuan Chemical, Hebei Chengxin, Hindusthan Chemicals Company, Tianjin Yuanyang Printing Materials, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Ferrocyanide Market Evolving Landscape
Continuous processing technology and regulatory data transparency requirements are compressing batch-cycle economics while elevating documentation burdens across the sodium ferrocyanide supply base.
Membrane filtration and crystallization automation is consolidating production economics for pharmaceutical-grade material. European and Indian API manufacturers are adopting these systems to meet pharmacopeial consistency requirements. The technology is compressing yield variation and reducing manual intervention, enabling smaller-scale producers to achieve certification thresholds previously reserved for integrated chemical majors.
REACH Article 33 supply chain communication obligations now extend to ferrocyanide salts in articles and mixtures, compelling downstream formulators to document cyanide complex concentrations. This regulatory friction is elevating compliance costs for importers and favoring established registrants with existing dossier infrastructure. Pigment and dye blenders in Germany and France are consolidating supplier lists to reduce documentation exposure.
Specification-driven procurement is displacing commodity spot purchasing among pharmaceutical and food-grade buyers. Long-term assay agreements with locked purity bands are replacing tonnage-based contracts, transferring quality verification burden upstream to producers. This behavioral shift is most visible in Swiss and Dutch chemical distribution channels serving European pharmaceutical manufacturers.
Sodium Ferrocyanide Market Segmentation
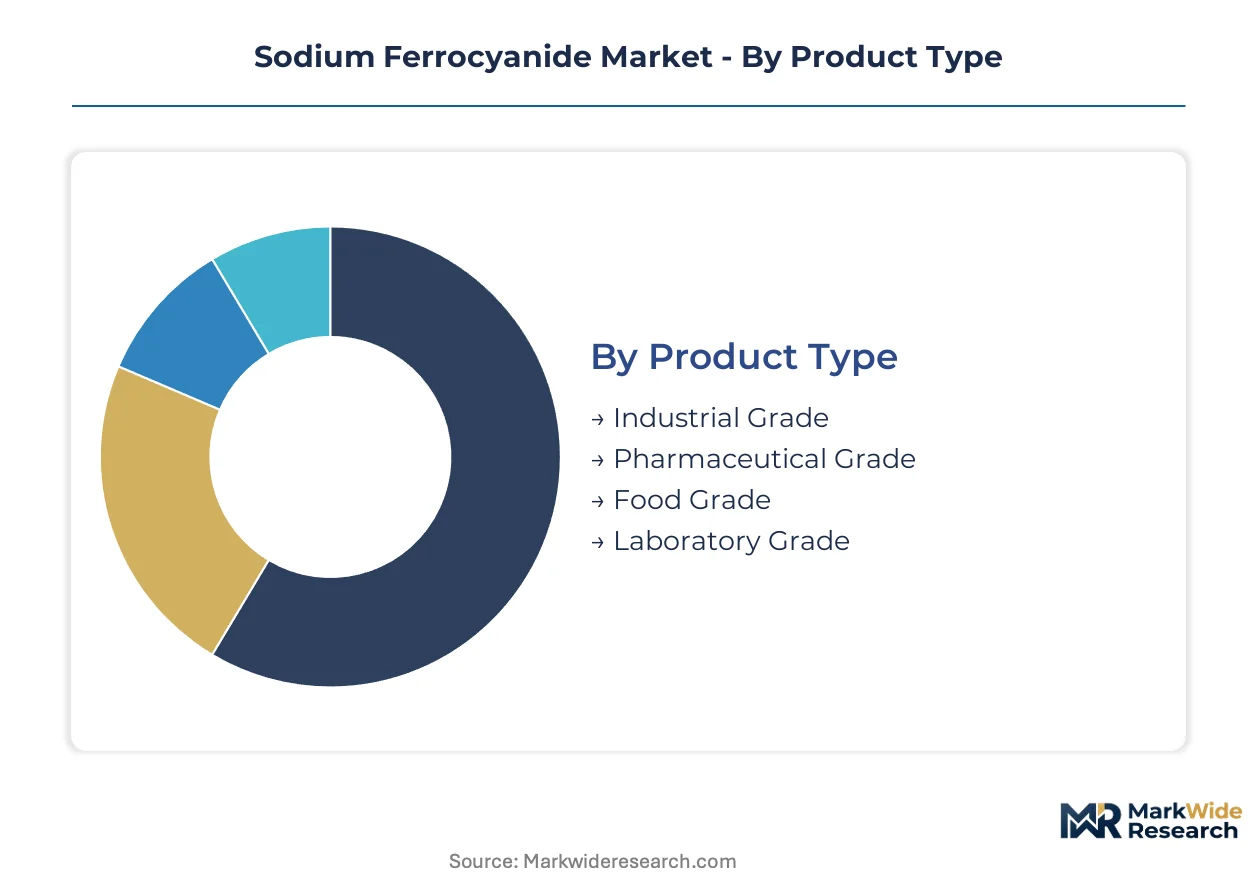
Sodium ferrocyanide segmentation reveals stark divergence in capital requirements, certification burdens, and margin profiles across purity tiers and end-use specifications. Pharmaceutical and food-grade segments demand specialized crystallization infrastructure and pharmacopeial documentation that industrial-grade producers rarely replicate.
Product Type:
Capital intensity peaks in pharmaceutical-grade production, where membrane filtration systems and cleanroom packaging infrastructure require multimillion-dollar investments that industrial-grade powder operations avoid entirely.
- Industrial Grade:Yellow crystalline material with 98-99% purity serves textile dye baths and electroplating formulations. Demand concentrates in China's Zhejiang and Jiangsu provinces, where pigment manufacturers absorb tonnage despite tightening MEE discharge regulations forcing plant retrofits.
- Pharmaceutical Grade:USP/EP-compliant material exceeding 99.5% purity with heavy metal specifications below 10 ppm. European API manufacturers in Switzerland and Germany are expanding offtake for injectable iron therapies, pulling supply toward dedicated GMP-certified facilities.
- Food Grade:FCC-compliant anti-caking agent with strict cyanide residue caps under FDA and FSSAI frameworks. Regulatory ceilings constrain volume expansion regardless of production economics.
- Laboratory Grade:ACS-certified reagent for analytical and research applications. University procurement channels and diagnostic reagent blenders in Japan and South Korea represent the primary demand nodes.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
Cost tier stratification separates commodity pigment applications from premium pharmaceutical intermediates, with electroplating formulations occupying a volatile middle ground sensitive to metal finishing cycles.
- Dyes:Ferrocyanide complexes stabilize vat dye baths for cotton and synthetic fiber coloration. Indian textile clusters in Surat and Tiruppur are integrating captive ferrocyanide capacity to reduce import exposure from Chinese suppliers.
- Pigments:Prussian blue precursor for coatings and printing inks. German and French automotive coating manufacturers are qualifying alternative inorganic blues, displacing ferrocyanide-derived material in select specifications.
- Electroplating:Brightener additive in zinc and cadmium plating baths. Japanese surface treatment specialists maintain steady offtake despite substitution pressure from organic brightener chemistries.
- Pharmaceuticals:Intermediate for iron supplementation APIs and diagnostic reagents. Swiss and Dutch chemical distributors are locking long-term assay agreements with producers capable of pharmacopeial documentation.
Pigment applications dominate current volume absorption; pharmaceutical intermediates are climbing the fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding locked purity bands and full supply chain documentation that commodity chemical manufacturers rarely provide.
- Chemical Manufacturers:Merchant producers and downstream derivative synthesizers. Integrated chlor-alkali operators in India are backward-integrating into captive ferrocyanide production to secure cyanide chemistry control.
- Textile Industry:Dye houses and finishing mills. Bangladesh and Vietnam garment exporters are expanding ferrocyanide consumption as regional dye capacity shifts from China.
- Food Industry:Salt processors and seasoning blenders. FSSAI residue monitoring in India and FDA enforcement in the United States create compliance friction that limits supplier qualification.
- Pharmaceutical Companies:API manufacturers and diagnostic reagent formulators. European manufacturers are consolidating supplier lists to reduce REACH Article 33 documentation exposure.
Chemical manufacturers command the largest share of current offtake; pharmaceutical companies are gaining share fastest.
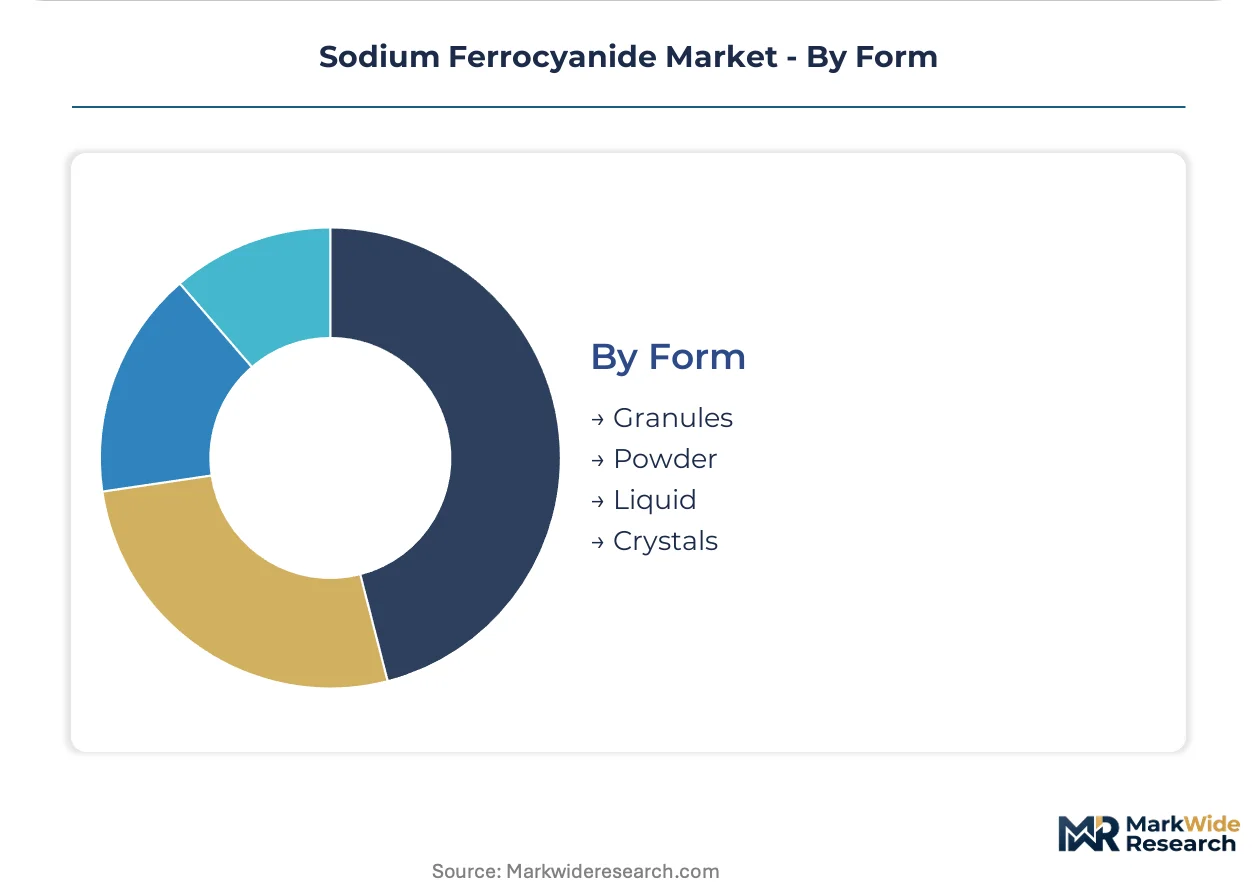
Form:
Supply concentration varies sharply by physical state, with liquid formulations requiring specialized tanker logistics that only integrated chemical majors reliably execute.
- Granules:Free-flowing agglomerated particles for automated dosing in textile and electroplating operations. German pigment compounders prefer granule flow properties for continuous processing lines.
- Powder:Fine-milled material for dye bath dissolution and laboratory preparation. Chinese industrial-grade producers compete primarily on powder tonnage scale.
- Liquid:Aqueous solutions for direct injection into electroplating baths and chemical synthesis. Evonik Industries AG anchors European liquid supply through dedicated tanker distribution networks.
- Crystals:Large-format prismatic crystals for pharmaceutical recrystallization feedstock. Swiss API manufacturers specify crystal morphology for downstream processing consistency.
Powder form carries the majority of current shipments; liquid formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of industrial-grade sodium ferrocyanide, yet consumption is dispersing toward India and Southeast Asia as downstream dye and pigment operations relocate. European pharmaceutical demand pulls premium-grade supply westward despite limited domestic production capacity.
China
Pigment manufacturers in Zhejiang and Jiangsu provinces absorb substantial industrial-grade tonnage for Prussian blue production. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity benchmarks for cyanide-derived chemical synthesis. Shandong Peninsula chlor-alkali complexes are retrofitting closed-loop systems to maintain operating permits under stricter discharge protocols.
India
Domestic textile dye houses in Surat and Tiruppur are expanding ferrocyanide consumption as garment finishing capacity shifts from Chinese competitors. FSSAI residue monitoring creates compliance friction for food-grade applications, limiting qualified suppliers. Gujarat Alkalies and Chemicals Ltd anchors captive production in the state's industrial corridor, feeding downstream dye and pigment operations.
Germany
European API manufacturers in Switzerland and Germany are locking long-term assay agreements for pharmaceutical-grade material. REACH registration requirements compel full toxicological dossiers for ferrocyanide salts, elevating compliance costs for importers. Evonik Industries AG maintains dedicated tanker distribution networks serving pharmaceutical formulators in the Rhine-Ruhr chemical cluster.
United States
Surface treatment specialists sustain steady electroplating-grade offtake despite substitution pressure from organic brightener chemistries. The EPA regulates cyanide-bearing compounds under the Clean Water Act, shaping permissible discharge thresholds for domestic producers. Midwest metal finishing operations concentrate demand in Ohio and Michigan manufacturing corridors.
Japan
Diagnostic reagent blenders and university procurement channels represent primary demand nodes for laboratory-grade material. METI industrial chemical frameworks govern cyanide complex handling and transport security requirements. Osaka-based surface treatment specialists maintain formulation consistency in zinc and cadmium plating applications.
Sodium Ferrocyanide Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across distinct purity tiers. Integrated chlor-alkali operators command feedstock cost advantages, while specialty chemical majors monetize formulation expertise and pharmacopeial documentation. Three archetypes dominate: backward-integrated commodity producers, GMP-certified pharmaceutical-grade specialists, and regional electroplating chemical distributors. Competitive moves center on captive cyanide chemistry integration and REACH dossier completion for European market access.
Among Indian integrated chemical producers, Gujarat Alkalies and Chemicals Ltd exemplifies the backward-integrated archetype through captive chlor-alkali operations. German specialty chemical majors represented by Evonik Industries AG occupy positions anchored by REACH registration infrastructure and pharmaceutical-grade certification. Chinese industrial-scale producers including Hebei Chengxin and Sichuan Chemical sit within the commodity powder segment, competing on tonnage scale for pigment and dye applications.
| Leading Market Players |
|---|
| Gujarat Alkalies and Chemicals Ltd (GACL) |
| Evonik Industries AG |
| Ziguang Chemical |
| Changzhou Xudong |
| Sichuan Chemical |
| Hebei Chengxin |
| Hindusthan Chemicals Company |
| Tianjin Yuanyang Printing Materials |
| UPL Limited |
| Others |
Value Network & Pricing Analysis
Sodium cyanide feedstock costs cascade through three distinct pricing tiers, with hydrogen cyanide volatility from Shandong chlor-alkali complexes compressing margins for non-integrated pharmaceutical-grade producers serving European API manufacturers.
Pricing Analysis
Margin tightening in industrial-grade powder reflects MEE-mandated retrofit costs passing through to Zhejiang pigment manufacturers. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-certified material commanding locked purity bands from commodity tonnage. Cost-down pressure on food-grade accelerates because FSSAI residue monitoring limits qualified supplier pools. Dye houses in Surat exhibit highest price sensitivity; Swiss API manufacturers show least.
Supply Chain Analysis
India's PLI scheme for specialty chemicals is redirecting ferrocyanide sourcing toward Gujarat-based captive chlor-alkali operations. Supply concentrates in China, India, and Germany, with hydrogen cyanide, ferrous sulfate, and sodium carbonate as critical inputs. Single-source vulnerability from Shandong Peninsula chlor-alkali concentration creates disruption exposure. Distribution runs through dedicated tanker networks for liquid formulations and bulk powder distributors for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cyanide chemistry expertise scarcity props pricing for qualified producers, with veteran operator retirements outpacing replacement training pipelines.
For Market Incumbents: Cement REACH dossier infrastructure to exclude unregistered Asian suppliers from European pharmaceutical channels. Deepen captive cyanide chemistry control through backward integration into chlor-alkali operations in Gujarat or Shandong. Organic pigment substitution in automotive coatings threatens Prussian blue volume; defend via long-term assay agreements with Swiss API manufacturers locking purity specifications. For New Entrants and Emerging Players: Enter via sodium-ion battery cathode material qualification, where sodium iron ferrocyanide analogs present white-space demand from cell manufacturers diversifying beyond lithium. Target pharmaceutical-grade production in India, where domestic API expansion outpaces qualified ferrocyanide supply. Pursue direct contracting with European formulators bypassing merchant chemical distributors. For Investors and Strategic Acquirers: Completion of USP validation cycles by Indian producers is the leading indicator that pharmaceutical-grade supply constraints will ease. Five-to-ten year viability favors integrated operators with captive cyanide chemistry and GMP-certified crystallization infrastructure. Monitor MEE enforcement intensity in Shandong as inflection signal for Chinese supply disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Gujarat Alkalies and Chemicals Ltd anchors cost leadership through captive cyanide feedstock control. |
| Pharmacopeial Certification Investment | USP and EP compliance documentation opens European API manufacturer channels to qualified entrants. |
| Closed-Loop Manufacturing Transition | MEE enforcement in China creates technology licensing demand for near-zero discharge systems. |
| Long-term Supply Agreement | Swiss and Dutch distributors lock assay agreements transferring quality verification burden upstream. |
| Battery-Grade Material Qualification | Sodium iron ferrocyanide analogs for sodium-ion cathodes diversify revenue beyond pigment applications. |
Research Methodology
Document review covered customs and trade data, SEC and Indian corporate filings, ECHA registration databases, and MEE discharge compliance records, complemented by interviews with chlor-alkali plant managers, pharmaceutical procurement leads at European API manufacturers, dye house technical directors in Surat and Tiruppur, and specialty chemical distribution channel partners. Bottom-up capacity and consumption estimates were triangulated against top-down trade flow analysis.
Segment-level value and volume trajectories were modeled across pharmaceutical, food, industrial, and laboratory grades; dyes, pigments, electroplating, and pharmaceutical applications; and powder, liquid, crystal, and granule formats. CAGRs were derived from regression against downstream demand drivers including textile production indices, API manufacturing expansion, and sodium-ion battery deployment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement intensity shifts, hydrogen cyanide supply disruptions, or pharmacopeial reclassification of ferrocyanide salts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Acetate Salt Market