
 Benzyl Acetate Market | 2026-2036
Benzyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Benzyl Acetate Market Outlook
Fragrance chemist shortages across European compounding facilities is unwinding near-term production schedules for high-purity benzyl acetate. LANXESS AG anchors its position through backward integration into toluene oxidation pathways. Symrise differentiates via captive jasmine-type fragrance portfolios that absorb specialty-grade volumes. Eastman Chemical Company leverages Tennessee-based manufacturing scale to serve North American flavor customers with food-grade specifications.
Benzyl acetate is an ester compound with the molecular formula C9H10O2, typically synthesized via Fischer esterification of benzyl alcohol and acetic acid or extracted from jasmine and other botanical sources; it functions primarily as a fragrance ingredient, flavoring agent, and industrial solvent across consumer and technical applications. The natural product type commands premium positioning in luxury fragrance formulations, while synthetic grades dominate volume throughput in mass-market cosmetics and household applications. Fragrance and flavoring applications together absorb the majority of output, with pharmaceutical-grade specifications representing a narrower but higher-margin demand pocket.
REACH registration requirements in Europe, FDA food additive regulations in the United States, and IFRA standards for fragrance materials collectively shape product specifications, testing protocols, and market access conditions for benzyl acetate suppliers. China's GB standards for food flavorants and cosmetic raw materials impose additional compositional thresholds on imports and domestic production alike. Stakeholders must monitor evolving biobased labeling requirements and green chemistry certification schemes as these frameworks increasingly influence procurement decisions across cosmetics and food end-use channels.
Market Dynamics
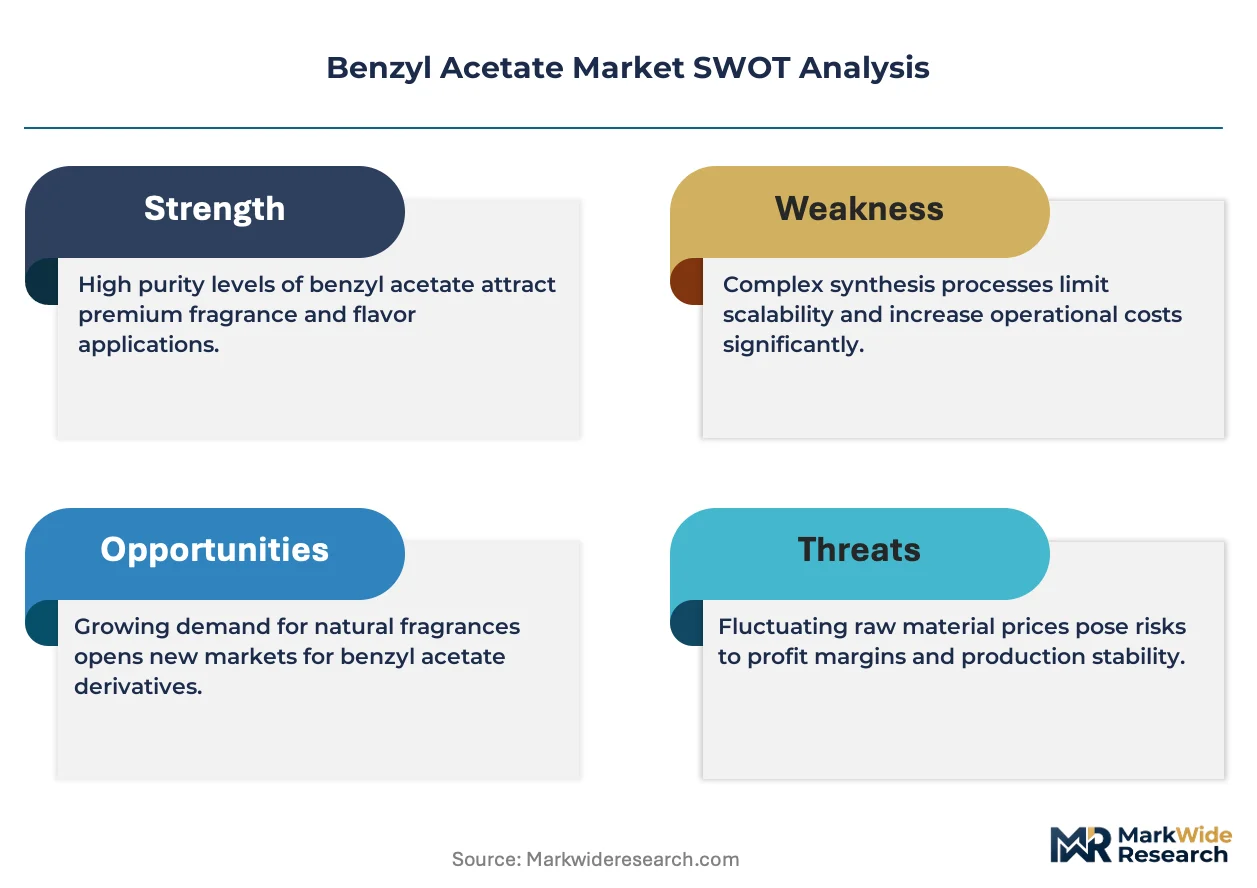
REACH compliance deadlines and tightening IFRA purity thresholds are compressing supplier margins while fragmenting procurement across certified and uncertified channels. Specialty fragrance houses now demand documentary traceability from benzyl alcohol feedstock through finished ester, reshaping qualification timelines.
Growth Catalysts
- Jasmine-type fragrance portfolios:Luxury perfume houses in France and Italy are expanding formulations requiring high-purity benzyl acetate as a signature top-note component.
- Fischer esterification process optimization:Continuous reactor designs are lowering energy intensity for synthetic grade production, improving cost competitiveness against natural extraction.
- GB standards alignment:China's cosmetic and food flavorant regulations are harmonizing with international purity benchmarks, easing export pathways for domestic manufacturers.
Market Restraints
- Toluene feedstock volatility:Oxidation pathway economics remain exposed to petrochemical price swings, compressing margin stability for backward-integrated producers.
- Jiangsu-Zhejiang supply concentration:Over half of Asia-Pacific manufacturing capacity clusters in two Chinese provinces, creating geographic risk exposure.
- Natural grade substitution ceiling:Botanical extraction yields cannot scale to meet mass-market fragrance volumes, capping premium segment expansion.
Strategic Opportunities
- Biobased certification schemes:EU Green Deal procurement preferences are creating first-mover advantage for producers with verified renewable carbon content.
- Pharmaceutical-grade specifications:Solvent applications in active pharmaceutical ingredient synthesis represent underdeveloped margin pools.
- Direct-to-compounder digital channels:Fragrance houses are bypassing traditional distributors for spot purchases of specialty grades.
Industry Challenges
- Fragrance chemist scarcity:European compounding facilities face recruitment gaps for high-purity quality control functions.
- REACH dossier maintenance costs:Registration update cycles and substance evaluation fees strain mid-tier supplier cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzyl Acetate Market |
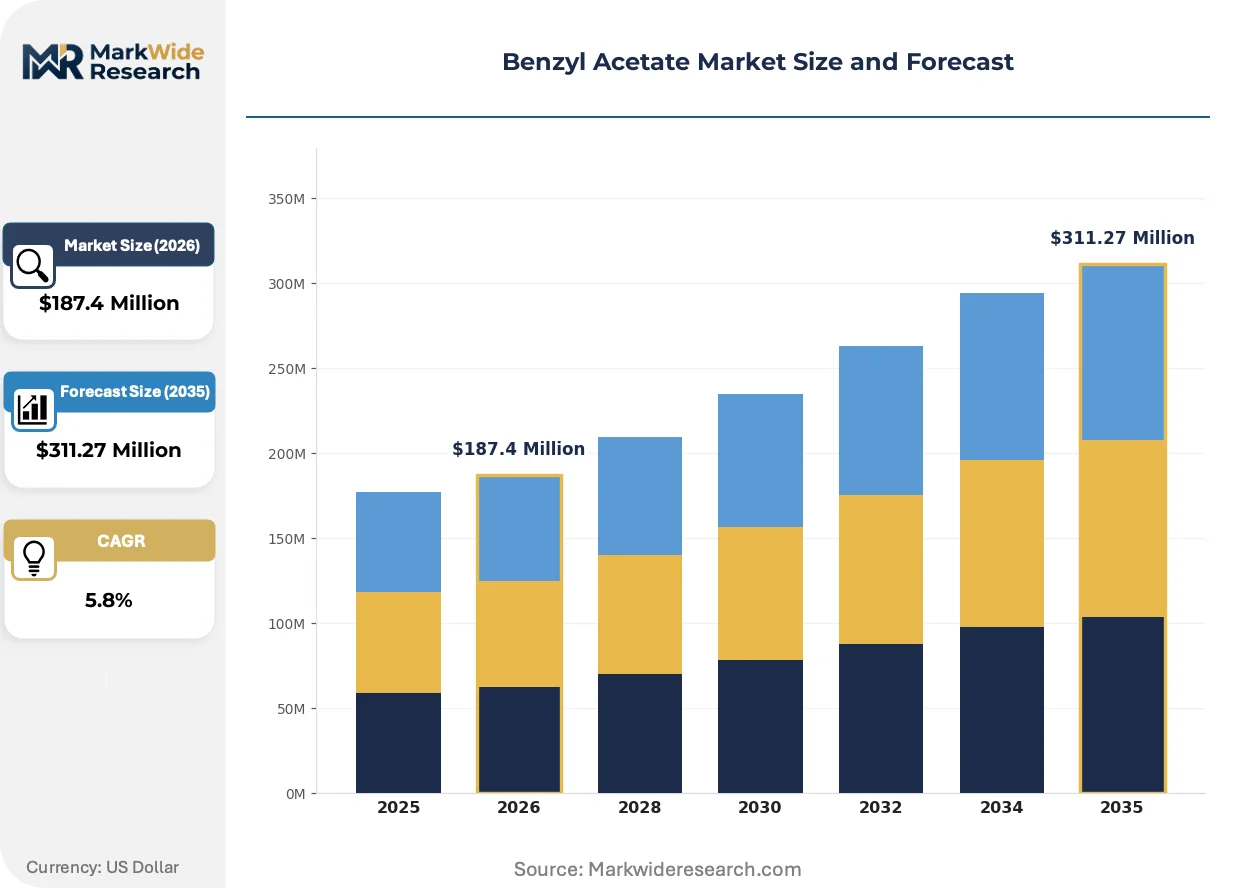
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Food Grade, Cosmetic Grade Application: Fragrance, Flavoring, Solvent, Industrial End User: Cosmetics, Food & Beverage, Pharmaceuticals, Household Packaging Type: Drums, Jerricans, Glass Bottles, Bulk Containers |
| Companies Covered | LANXESS AG, Symrise, Eastman Chemical Company, Royal DSM N.V., Merck KGaA, BASF SE, Givaudan, Arkema S.A., The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzyl Acetate Market Strategic Shifts
Biocatalytic esterification routes and carbon accounting transparency are restructuring how benzyl acetate qualifies for premium fragrance formulations. Regulatory digitization and buyer consolidation are simultaneously compressing supplier response windows.
Enzymatic esterification using immobilized lipase biocatalysts is supplanting traditional acid-catalyzed batch processes in specialty-grade production. Niche fragrance manufacturers in Switzerland and France are piloting these routes to secure EU Green Deal-compliant supply chains. The technology is enabling carbon footprint documentation that synthetic chemistry cannot replicate.
REACH substance evaluation under the 2023-2025 Community Rolling Action Plan is tightening impurity thresholds for cosmetic-grade benzyl acetate. ECHA's scrutiny of benzyl alcohol residuals is forcing reformulation of established supply specifications. German and Dutch fragrance compounders are front-loading testing budgets to preempt authorization risks.
Fragrance house procurement teams are consolidating supplier panels from twelve-vendor arrays to three preferred partnerships with full backward integration. This concentration is displacing spot-market trading for high-purity grades. The shift is most visible in Grasse and Geneva, where Givaudan and Firmenich operations have implemented sole-source policies for jasmine-type materials.
Benzyl Acetate Market Segmentation
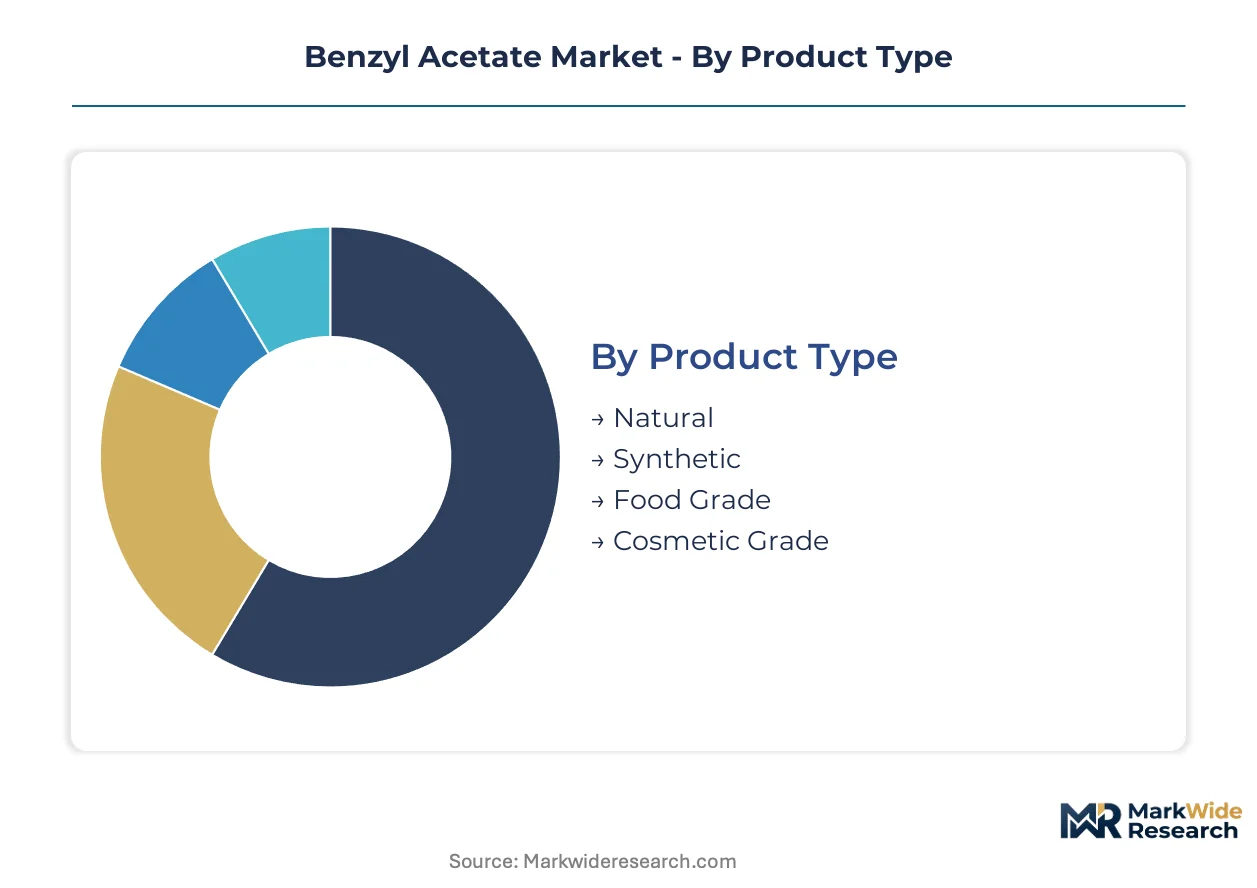
Benzyl acetate's value chain fragments across purity grades and application specifications that command divergent pricing and regulatory scrutiny. Substitution pressures from alternative esters and biobased solvents reshape which segments retain volume dominance versus margin protection.
Product Type:
Natural extraction routes face the most acute substitution threat from enzymatic biocatalysis and precision fermentation, while synthetic grades confront feedstock volatility and biobased certification demands.
- Natural:Derived from jasmine absolute and other botanical sources through solvent extraction or steam distillation; jasmine-type fragrance houses in Grasse and Geneva absorb specialty volumes for luxury perfume formulations where carbon-14 verification commands premium positioning.
- Synthetic:Manufactured via Fischer esterification of benzyl alcohol with acetic acid; continuous reactor designs in China's Jiangsu province are lowering energy intensity for mass-market cosmetics and household applications where cost competitiveness outweighs provenance claims.
- Food Grade:Meets FDA food additive specifications and FSSAI thresholds for flavoring applications; purification overhead restricts viable supplier pools.
- Cosmetic Grade:Complies with REACH registration and evolving IFRA impurity thresholds; ECHA scrutiny of benzyl alcohol residuals is tightening qualification timelines.
Synthetic grades anchor the volume base while natural extraction gains share at the steepest rate among fragrance houses with EU Green Deal procurement mandates.
Application:
Cost tier differentiation separates commodity solvent uses from formulation-critical fragrance applications where specification rigidity protects margin structures.
- Fragrance:Functions as a jasmine-type top-note component in fine perfumes; high-purity specifications demand documentary traceability from benzyl alcohol feedstock through finished ester, consolidating procurement around backward-integrated suppliers.
- Flavoring:Deployed in food and beverage formulations requiring FDA or GB standards compliance; taste threshold sensitivity limits viable substitution by alternative esters.
- Solvent:Technical-grade material for industrial cleaning and coating applications; price elasticity exposes volumes to hydrocarbon solvent competition.
- Industrial:Broad-spectrum uses spanning adhesives, inks, and plasticizers; specification heterogeneity fragments supplier relationships.
Fragrance applications concentrate margin capture while solvent uses expand most quickly in emerging manufacturing clusters seeking cost-efficient technical grades.
End User:
Customer type fragmentation across regulated industries creates divergent qualification burdens that favor suppliers with multi-certification capabilities.
- Cosmetics:Absorbs cosmetic-grade and high-purity synthetic volumes; REACH compliance and IFRA standards impose documentary requirements that strain mid-tier supplier cash flows.
- Food & Beverage:Food-grade specifications governed by FDA regulations and China's GB standards; flavor house consolidation in Jiangsu and Zhejiang provinces concentrates demand geography.
- Pharmaceuticals:Solvent applications in active pharmaceutical ingredient synthesis represent underdeveloped margin pools with pharmacopeial compliance requirements.
- Household:Mass-market air care and cleaning products; price sensitivity drives procurement toward synthetic grades with minimal certification overhead.
Cosmetics anchors the volume base while pharmaceuticals climbs the fastest as compounders seek solvent alternatives with documented impurity profiles.
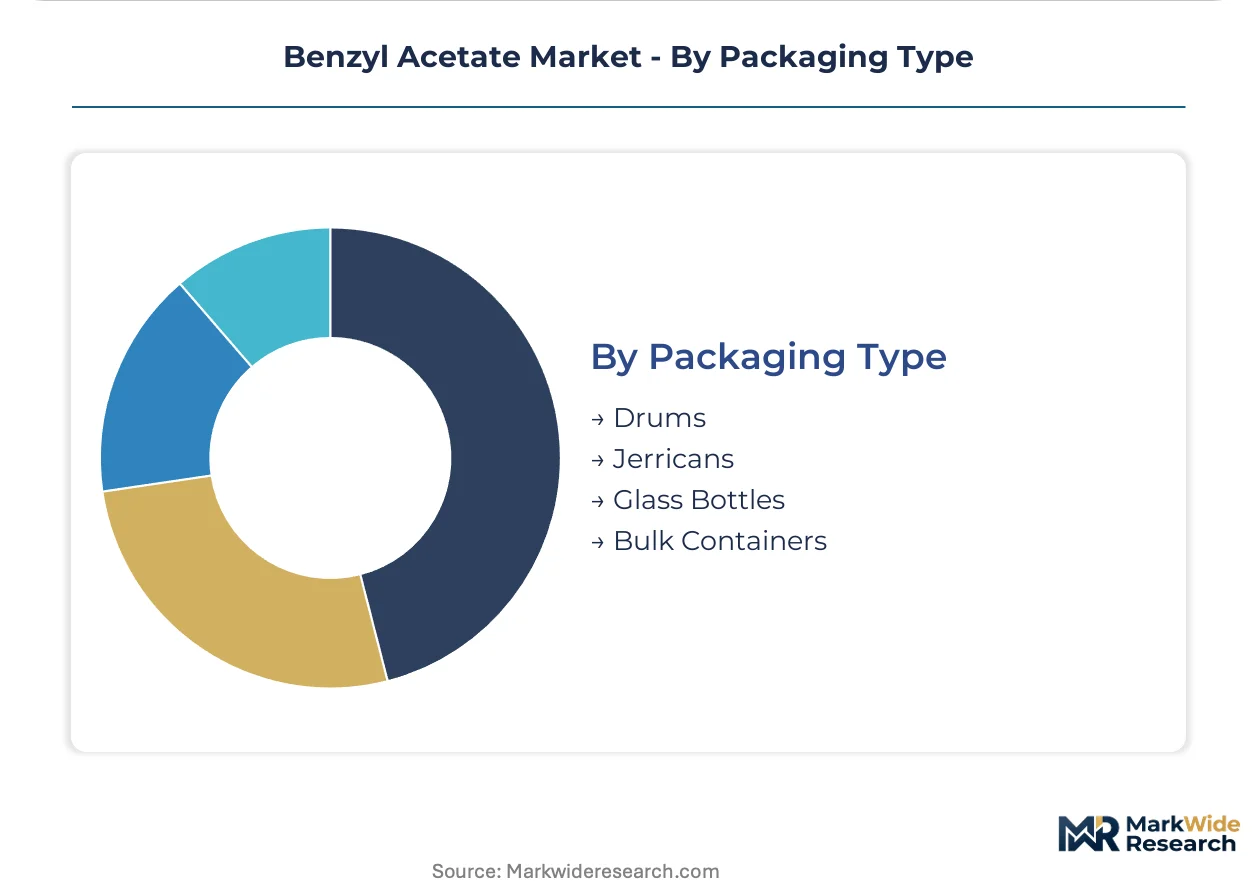
Packaging Type:
Supply concentration in drum and bulk formats reflects downstream manufacturing scale, while specialized packaging serves niche quality control requirements.
- Drums:Standard 200-liter steel containers for industrial and mid-volume cosmetic compounding; logistics efficiency favors regional filling operations near Zhejiang manufacturing clusters.
- Jerricans:20-30 liter plastic containers for specialty fragrance houses and small-batch flavor compounders; handling protocols prevent cross-contamination between grades.
- Glass Bottles:Amber or clear glass for analytical standards and pharmaceutical-grade material; inert surface properties protect against ester hydrolysis during storage.
- Bulk Containers:ISO tanks and flexitanks for large-volume synthetic grade shipments; backward-integrated producers leverage Tennessee and Jiangsu filling infrastructure.
Drum formats anchor the volume base while glass bottles gain share fastest in pharmaceutical and analytical segments where contamination control dominates procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with European fragrance houses prioritizing carbon-14 verified natural grades while Asian manufacturers drive synthetic volume throughput for mass-market cosmetics.
China
Jiangsu and Zhejiang provinces host consolidated flavor and fragrance manufacturing clusters that absorb the majority of regional benzyl acetate output. GB standards for cosmetic and food flavorant raw materials impose compositional thresholds that domestic producers must meet for both local sales and export qualification. Continuous reactor installations in Zhejiang's manufacturing corridors are lowering energy intensity for Fischer esterification-based synthetic grades.
Germany
LANXESS AG anchors European supply through backward integration into toluene oxidation pathways serving fragrance compounders. ECHA's REACH substance evaluation under the 2023-2025 Community Rolling Action Plan is tightening impurity thresholds for cosmetic-grade material, forcing reformulation of established specifications. Cologne and Düsseldorf-based fragrance houses are front-loading testing budgets to preempt authorization risks for benzyl alcohol residuals.
United States
Eastman Chemical Company leverages Tennessee-based manufacturing scale to serve North American flavor customers with food-grade specifications meeting FDA additive regulations. FDA food additive protocols and evolving biobased labeling requirements shape procurement decisions across cosmetics and food end-use channels. The Southeast chemical corridor provides integrated feedstock access for synthetic grade production.
France
Grasse-based luxury perfume houses expand formulations requiring high-purity benzyl acetate as a signature jasmine-type top-note component. ANSM and EU Green Deal procurement preferences create first-mover advantage for producers with verified renewable carbon content. Givaudan and Firmenich operations have implemented sole-source policies for jasmine-type materials, consolidating supplier panels.
Switzerland
Geneva-centered fragrance compounders pilot enzymatic esterification using immobilized lipase biocatalysts to secure EU Green Deal-compliant supply chains. Swissmedic oversight of pharmaceutical-grade specifications creates underdeveloped margin pools for solvent applications in active pharmaceutical ingredient synthesis. Niche fragrance manufacturers are enabling carbon footprint documentation that synthetic chemistry cannot replicate.
Benzyl Acetate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the benzyl acetate competitive structure. Backward-integrated chemical conglomerates control feedstock access and captive consumption through fragrance portfolios, while mid-tier ester specialists compete on qualification speed and certification flexibility. Three archetypes dominate: petrochemical-integrated majors with toluene oxidation assets, fragrance houses with captive jasmine-type formulations, and regional ester specialists serving spot markets. Consolidation is accelerating through supplier panel reduction from multi-vendor arrays to preferred partnerships, while enzymatic biocatalysis investments reshape specialty-grade qualification timelines.
Within the integrated major tier, LANXESS AG exemplifies the petrochemical-integrated archetype through its German headquarters and Aktiengesellschaft structure. Symrise occupies a position representing fragrance-house vertical integration, absorbing specialty-grade volumes into captive portfolios. Eastman Chemical Company anchors the North American scale-driven segment through its incorporated structure and Tennessee manufacturing presence. These three entities collectively illustrate how feedstock control, formulation capture, and geographic scale define competitive positioning in benzyl acetate supply.
| Leading Market Players |
|---|
| LANXESS AG |
| Symrise |
| Eastman Chemical Company |
| Royal DSM N.V. |
| Merck KGaA |
| BASF SE |
| Givaudan |
| Arkema S.A. |
| The Dow Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Continuous reactor scale economies in China's Zhejiang province compress unit costs for Fischer esterification output while simultaneously hardening price floors for natural extraction grades. This dual dynamic concentrates procurement leverage among backward-integrated majors serving fragrance houses with documentary traceability requirements.
Pricing Analysis
Long-term offtake contracts dominate procurement between backward-integrated producers and consolidated fragrance houses, while spot markets serve residual specialty-grade demand from small-batch compounders. Three-tier pricing structure across natural, cosmetic-grade synthetic, and technical-grade synthetic levels reflects purity certification and carbon-14 verification overhead. Cost compression in technical grades intensifies because hydrocarbon solvent substitution erodes volume premiums. Food and beverage flavor houses exhibit highest price sensitivity due to taste-threshold constraints limiting viable ester alternatives, whereas luxury perfume houses absorb premium positioning for carbon-verified natural grades.
Supply Chain Analysis
Strategic stockpiling of benzyl alcohol feedstock characterizes procurement behavior among European fragrance compounders confronting REACH evaluation uncertainty, while Asian manufacturers favor just-in-time benzene derivative sourcing. Manufacturing gravity centers on China, Germany, and the United States, with Jiangsu-Zhejiang clusters feeding mass-market cosmetic output. Toluene oxidation pathways for benzyl alcohol production draw from petrochemical feedstocks exposed to commodity price swings. Single-source vulnerability concentrates in jasmine absolute extraction for natural grades, where botanical yield constraints cannot scale to meet volume surges. Distribution runs through regional drum-filling operations proximate to Zhejiang manufacturing corridors, with bulk ISO tank shipments serving backward-integrated majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic biocatalysis and precision fermentation advances threaten synthetic-grade incumbents with renewable carbon substitution, demanding defensive repositioning across certification and feedstock control dimensions.
For Market Incumbents: Shield margin structures by deepening backward integration into toluene oxidation assets and accelerating enzymatic esterification pilot investments before EU Green Deal procurement mandates harden. Captive jasmine-type fragrance portfolios absorb specialty-grade volumes that biobased substitutes cannot yet replicate at scale. Certification maintenance for REACH dossiers and IFRA compliance represents the critical lever for supplier panel retention. For New Entrants and Emerging Players: Pharmaceutical-grade solvent specifications represent a service-layer gap where incumbents under-serve compounders seeking documented impurity profiles for active pharmaceutical ingredient synthesis. White-space concentration in Swiss and German pharmaceutical corridors offers penetrable entry points with pharmacopeial compliance as the go-to-market angle. Direct-to-compounder digital channels bypass distributor markups for spot specialty-grade purchases. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic biocatalysis specialists with carbon accounting infrastructure over conventional Fischer esterification assets facing feedstock volatility. Long-term viability across the projection horizon hinges on renewable carbon verification capabilities rather than petrochemical integration depth. The signal to watch is EU Green Deal procurement mandate expansion into mid-tier fragrance house supplier requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | LANXESS-style toluene oxidation control secures feedstock access against petrochemical price swings. |
| Enzymatic Biocatalysis Scale-Up | Immobilized lipase routes enable EU Green Deal carbon footprint documentation for premium fragrance qualification. |
| Pharmaceutical-Grade Certification | Pharmacopeial compliance opens underdeveloped solvent margins in Swiss and German API synthesis corridors. |
| Direct-to-Compounder Digital Channel | Bypassing traditional distributors captures spot specialty-grade demand from consolidating fragrance house procurement teams. |
| Long-term Supply Agreement | Sole-source policies at Givaudan and Firmenich operations lock in jasmine-type material volumes with documentary traceability. |
Study Parameters
A standing panel of fragrance chemists, cosmetic compounders, flavor house procurement leads, and benzyl alcohol plant managers provided ongoing calibration against secondary validation from customs trade data, ECHA registration databases, SEC 10-K chemical segment disclosures, and IFRA standards documentation. Primary fieldwork combined structured interviews with downstream formulation specialists and upstream synthesis engineers. Bottom-up grade-volume estimates triangulated against top-down end-use consumption models.
Consistency checks validated volume and value outputs against external benchmarks including regional chemical production indices and fragrance industry consumption surveys across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from slope-log regression of annualized consumption estimates, with benzyl alcohol feedstock price indices and REACH compliance cost trajectories as industry-specific forecast inputs.
Forecasts assume regulatory continuity in REACH, FDA food additive, and China's GB standards regimes; material policy shifts would require re-modeling. Specific risk factors include ECHA authorization listing for benzyl alcohol residuals, IFRA impurity threshold revisions, and biobased certification scheme adoption rates. Revision becomes warranted when enzymatic biocatalysis capacity crosses cost-parity thresholds with Fischer esterification at commercial scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Lactic Acid Market