
 Pneumatic Seal Market | 2026-2036
Pneumatic Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Seal Market Outlook
China is tilting pneumatic seal capacity toward high-volume polyurethane and fluoroelastomer production zones. Trelleborg Sealing Solutions leverages integrated compounding operations across Scandinavian facilities to sustain premium positioning. Freudenberg Sealing Technologies anchors its portfolio in perfluoroelastomer formulations for aerospace and semiconductor applications. SKF competes through bearing-seal system bundling that extends value capture beyond commodity seals.
A pneumatic seal is an elastomeric or thermoplastic component engineered to contain pressurized air or inert gas within dynamic assemblies, typically operating at pressures up to 10 bar and temperatures ranging from -40°C to 200°C depending on material grade; its primary purpose is preventing leakage in reciprocating or rotary pneumatic systems across factory automation, transportation, and energy infrastructure. Polyurethane rod seals dominate high-cycle industrial equipment due to abrasion resistance and cost efficiency in mass-produced cylinders. Fluoroelastomer O-rings command margin concentration in aerospace and oil & gas applications where chemical compatibility and thermal stability justify material premiums. Nitrile U-cups retain volume leadership in standard automotive and general pneumatics despite gradual displacement by advanced compounds in severe-service niches.
REACH in Europe restricts perfluorinated compound formulations, compelling reformulation investments from seal compounders serving EU machinery exporters. EPA ozone and SNAP regulations in the United States influence pneumatic system designs that indirectly specify seal temperature and chemical resistance thresholds. China's GB standards for pneumatic components, administered under SAMR oversight, mandate testing protocols that foreign suppliers must navigate for market access. Stakeholders should monitor divergence between EU fluoropolymer restrictions and China's dual carbon-driven efficiency standards, as misaligned regulatory timelines will fragment material qualification requirements and reshape supplier certification burdens.
Market Dynamics
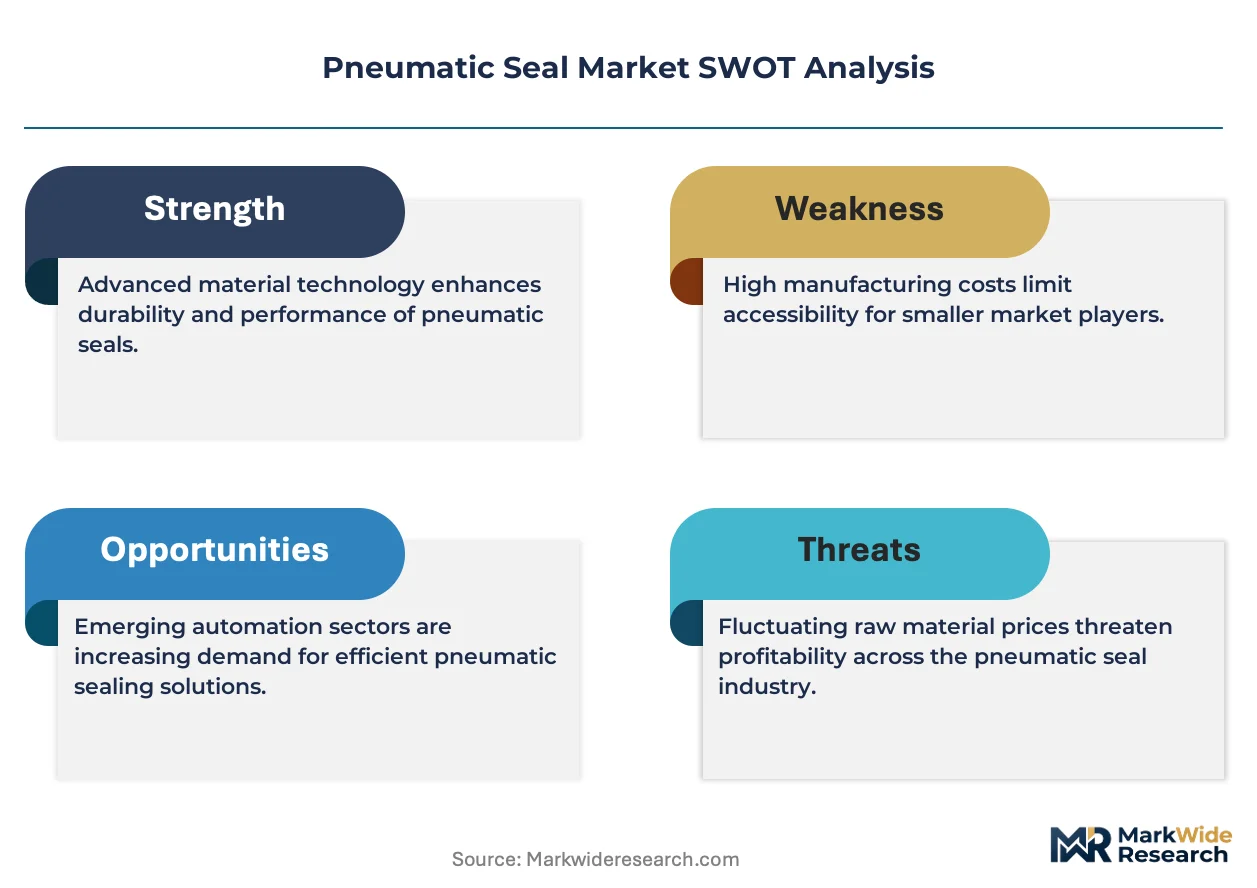
Fluoropolymer reformulation pressures under REACH are compressing margin structures for European compounders while simultaneously opening qualification windows for polyurethane and hydrogenated nitrile alternatives in high-cycle automation.
Growth Catalysts
- Factory automation densification:Automotive OEMs in Germany and China are specifying pneumatic seals rated for 10 million+ cycles in robotic welding lines, pulling demand toward advanced polyurethane formulations.
- REACH Article 57 authorization triggers:ECHA restrictions on perfluorinated substances are redirecting R&D budgets toward compliant fluoroelastomer alternatives, creating first-mover advantages for reformulation-ready suppliers.
- Semiconductor fab construction waves:Cleanroom-grade pneumatic systems in Arizona, Saxony, and Hsinchu require ultra-low outgassing seal specifications that command material premiums.
Market Restraints
- Fluorinated raw material concentration:Three Japanese chemical conglomerates control 70%+ of global FKM polymer supply, exposing seal compounders to allocation risk during semiconductor demand spikes.
- REACH testing cost escalation:Substance of Very High Concern registration dossiers now exceed €300,000 per formulation, freezing SME compounders out of EU machinery supply chains.
- Magnetic actuator substitution:Linear motor drives in precision positioning equipment are eliminating pneumatic cylinders entirely in lithography and metrology applications.
Strategic Opportunities
- Indian PLI scheme for industrial machinery:Domestic content requirements under the Production Linked Incentive program are forcing multinational OEMs to localize seal sourcing, opening qualification pathways for local compounders.
- Hydrogen infrastructure seal specifications:Compression and dispensing equipment for 700-bar hydrogen systems requires metal-detectable, explosive-decompression-resistant compounds not yet standardized.
- Digital twin integration:Seal-wear prediction algorithms embedded in pneumatic system IoT platforms are creating recurring revenue streams through predictive replacement scheduling.
Industry Challenges
- Compound formulation talent scarcity:Retiring polymer chemists with 20+ years of fluoroelastomer crosslinking expertise are not being replaced at equivalent depth, slowing new product development cycles.
- Multi-standard certification stacking:Simultaneous compliance with FDA 21 CFR 177.2600, EU 1935/2004, and China's GB 4806 is extending qualification timelines for food-contact pneumatic equipment by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Seal Market |
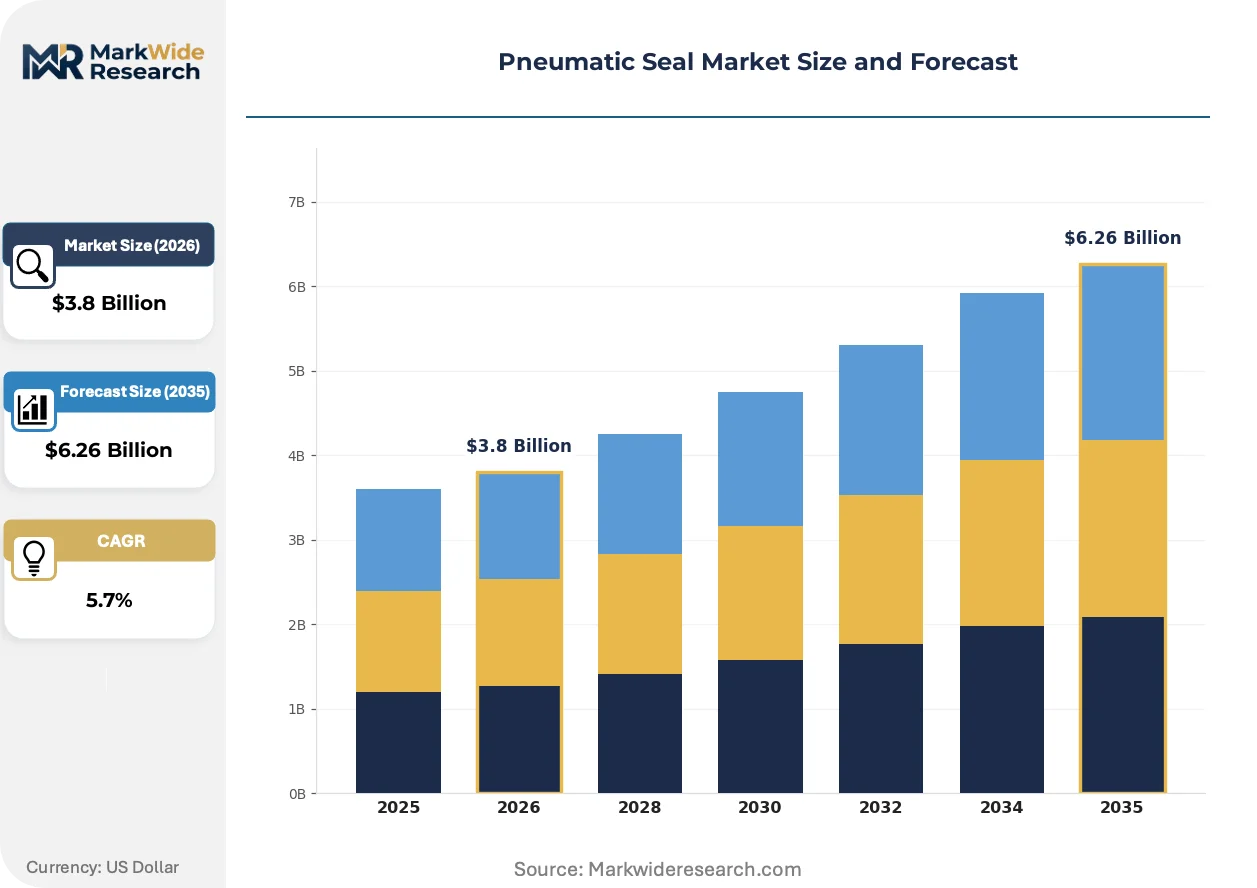
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Nitrile, Silicone, Polyurethane, Fluoroelastomer Product Type: O-Rings, Gaskets, U-Cups, Rod Seals End User: Aerospace, Automotive, Industrial Equipment, Oil & Gas Application: Pneumatic Cylinders, Compressors, Valves, Actuators |
| Companies Covered | Trelleborg Sealing Solutions, Freudenberg Sealing Technologies, SKF, Parker Hannifin, Hallite Seals International, All Seals Inc., Allied Metrics Seals & Fasteners, A.W. Chesterton, John Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Seal Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are converging to rewrite specification sheets across industrial pneumatics, with seal performance increasingly defined by compliance attributes rather than purely mechanical durability.
Thermoplastic polyurethane formulations with embedded fiber reinforcement are migrating from standard industrial cylinders into high-frequency packaging machinery operating above 5 Hz. Food and beverage OEMs in the Netherlands and Denmark are specifying these compounds for washdown environments where nitrile degradation previously mandated quarterly seal replacement. The shift is compressing aftermarket parts revenue for traditional elastomer suppliers while expanding TPU compounder addressable market.
REACH Annex XIV authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of aerospace-grade O-rings previously dependent on PTFE coatings. German seal houses are accelerating hydrogenated nitrile development programs to recover fuel system sealing performance without fluorinated backbone polymers. The aerospace and semiconductor segments are absorbing 15-25% material cost increases during the transition window.
Condition-based seal replacement contracts are displacing fixed-interval maintenance schedules in automotive assembly plants. Tier-1 pneumatic system integrators in Stuttgart and Shanghai are bundling seal-wear sensors with compressed air monitoring to unbundle hardware from service revenue. The model is most visible in battery electric vehicle body-in-white lines where unplanned downtime costs exceed €50,000 per hour.
Pneumatic Seal Market Segmentation
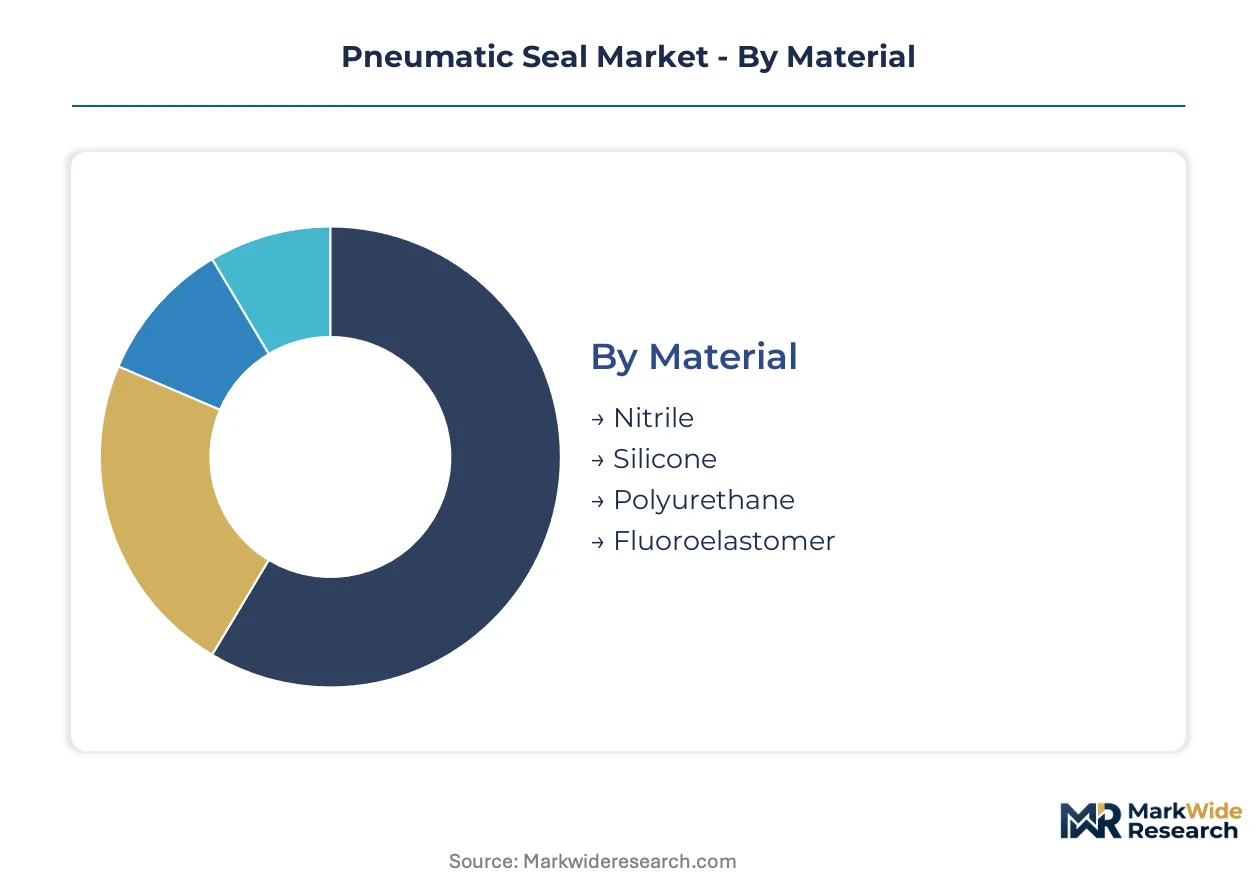
Material chemistry and product architecture determine performance ceilings in pneumatic seal specification. Procurement patterns diverge sharply between high-cycle automation and severe-service energy applications, fragmenting supplier strategies across incompatible technical requirements.
Material:
Cost tier stratification separates commodity elastomers from performance polymers commanding formulation premiums.
- Polyurethane:Thermoplastic formulations with embedded fiber reinforcement deliver abrasion resistance above 5 Hz cycling in packaging machinery. German automotive OEMs specify these compounds for robotic welding lines requiring 10 million+ cycle durability.
- Fluoroelastomer:Perfluorinated backbone polymers withstand temperatures to 200°C and aggressive chemical media in semiconductor fab cleanrooms. REACH Article 57 authorization triggers are forcing reformulation investments while aerospace and oil & gas segments absorb material cost premiums during transition.
- Nitrile:Standard acrylonitrile-butadiene compounds retain volume leadership in general pneumatics and legacy automotive applications despite gradual displacement in severe-service niches.
- Silicone:VMQ formulations serve food-contact and medical pneumatic equipment requiring FDA 21 CFR 177.2600 compliance and broad temperature flexibility.
Nitrile commands the established base. The steepest expansion runs through polyurethane as automation cycle rates intensify.
Product Type:
Application geometry dictates seal form factor selection across reciprocating versus static sealing interfaces.
- Rod Seals:Dynamic lip configurations contain pressurized air in reciprocating cylinder applications. Chinese production zones concentrate high-volume polyurethane rod seal capacity serving automated industrial equipment manufacturing.
- O-Rings:Circular cross-section elastomers provide static and dynamic sealing in valve bodies and actuator housings. Fluoroelastomer O-rings capture margin concentration in aerospace fuel systems and semiconductor gas distribution manifolds.
- U-Cups:Asymmetric lip profiles optimize bidirectional pressure containment in standard pneumatic cylinders. Nitrile U-cups dominate general industrial replacement demand.
- Gaskets:Static flange seals and custom-cut profiles address non-standard equipment interfaces in legacy machinery retrofit applications.
O-Rings anchor the installed base. Rod seals are gaining share fastest as factory automation densification accelerates.
End User:
Customer type segmentation reveals divergent qualification burdens and procurement power concentration.
- Industrial Equipment:Factory automation OEMs in Germany and China specify seals for 10 million+ cycle ratings. Trelleborg Sealing Solutions and SKF compete through integrated bearing-seal system bundling in this segment.
- Aerospace:Fuel system and flight control applications demand perfluoroelastomer formulations meeting SAE AMS specifications. REACH restrictions on fluorinated compounds are compressing margin structures during reformulation transitions.
- Automotive:Body-in-white pneumatic systems and powertrain assembly equipment drive high-volume demand. Condition-based replacement contracts are displacing fixed-interval maintenance schedules in Stuttgart and Shanghai assembly plants.
- Oil & Gas:Compression and process equipment requires explosive-decompression-resistant compounds in subsea and surface production systems.
Automotive anchors volume demand. Industrial equipment is climbing the fastest as automation investment intensifies.
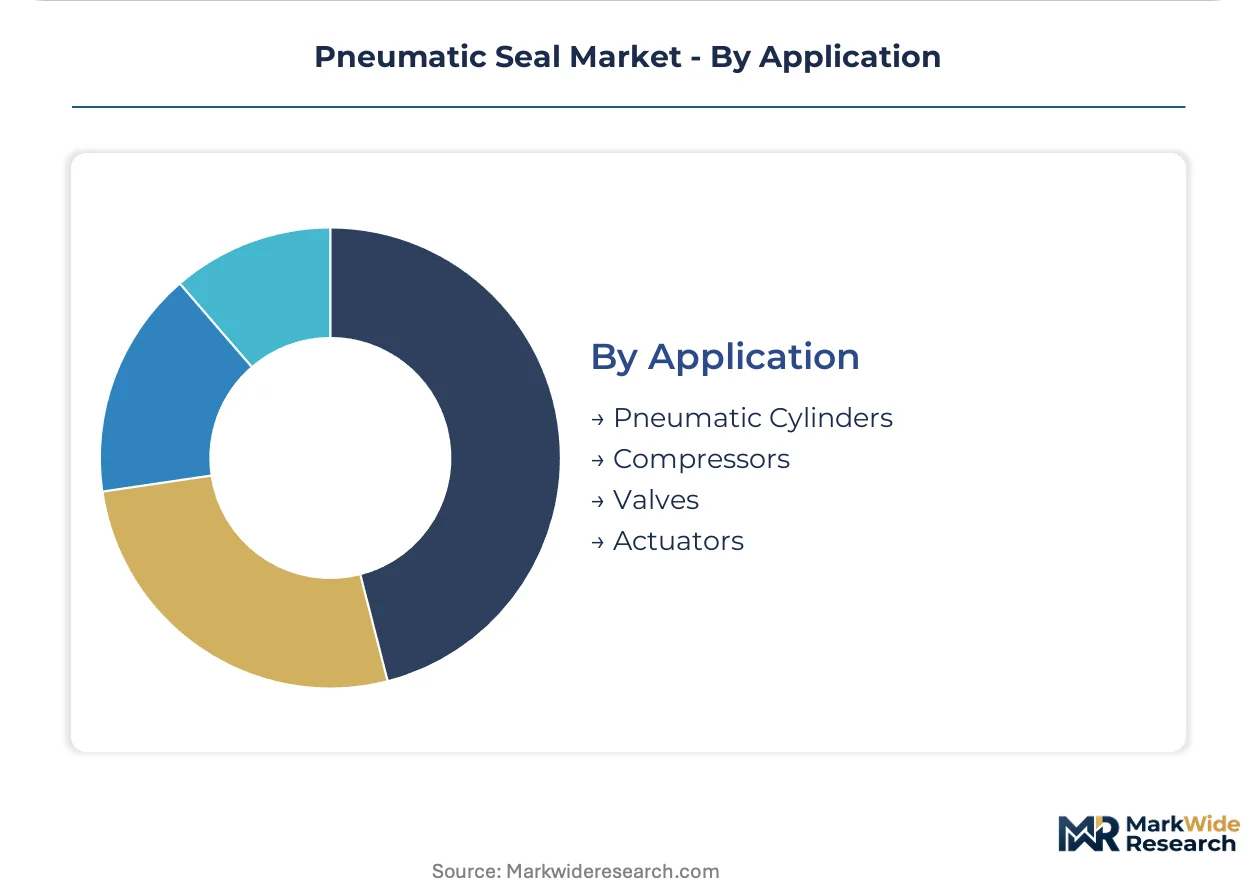
Application:
Equipment architecture determines seal duty cycle severity and replacement frequency economics.
- Pneumatic Cylinders:Linear actuators in robotic welding and material handling represent the highest-volume seal consumption point. Digital twin integration is creating predictive replacement revenue streams for system integrators.
- Valves:Directional control and pressure regulation equipment requires compact seal profiles in high-cycle switching applications. Cleanroom-grade specifications in Arizona and Saxony semiconductor fabs command material premiums.
- Actuators:Rotary and linear motion conversion equipment spans industrial automation and transportation applications. Magnetic actuator substitution is eliminating pneumatic cylinders entirely in precision lithography positioning.
- Compressors:Air generation equipment requires piston rings and valve plate seals in continuous-duty industrial installations.
Pneumatic cylinders dominate installed base. Valves are expanding most quickly as semiconductor fab construction waves accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. German automotive OEMs specify 10 million+ cycle seals for robotic welding lines. Chinese manufacturers prioritize high-volume polyurethane production for domestic automation equipment. US semiconductor fabs drive ultra-low outgassing specifications.
Germany
Automotive body-in-white automation in Stuttgart and Wolfsburg pulls demand toward advanced polyurethane rod seals. REACH Article 57 authorization triggers on perfluorinated substances are compressing margin structures for domestic compounders. The Baden-Württemberg industrial corridor hosts concentrated seal qualification activity for robotic welding applications.
China
Domestic automation equipment manufacturing is tilting capacity toward high-volume polyurethane and fluoroelastomer production zones. GB standards under SAMR oversight mandate testing protocols that foreign suppliers must navigate for market access. Yangtze River Delta manufacturing clusters are absorbing the bulk of localization requirements under efficiency-driven industrial policies.
United States
Semiconductor fab construction waves in Arizona and Texas require cleanroom-grade pneumatic systems with ultra-low outgassing seal specifications. EPA ozone and SNAP regulations influence pneumatic system designs that indirectly specify seal temperature thresholds. Phoenix and Austin metro areas are commanding material premiums for advanced compounds.
Japan
Three chemical conglomerates control the majority of global FKM polymer supply, exposing seal compounders to allocation risk during semiconductor demand spikes. METI industrial standards shape qualification requirements for precision automation equipment. Nagoya and Osaka manufacturing belts concentrate fluoroelastomer formulation expertise.
India
Domestic content requirements under the PLI scheme for industrial machinery are forcing multinational OEMs to localize seal sourcing. BIS certification protocols extend qualification timelines for foreign suppliers entering the market. Maharashtra and Gujarat industrial corridors are opening qualification pathways for local compounders.
Pneumatic Seal Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Premium formulation expertise clusters among Scandinavian and German compounders with integrated material science operations. High-volume production gravitates toward Asian manufacturing zones with captive polymer supply. Three strategic archetypes dominate: integrated material-compounders, bearing-system bundlers, and specialized seal houses. M&A activity targets reformulation-ready assets for REACH compliance. Capacity expansion concentrates in polyurethane feedstock zones serving automation OEMs.
Among European integrated compounders, Trelleborg Sealing Solutions and Freudenberg Sealing Technologies exemplify the premium-tier archetype through captive material operations. SKF occupies a position on the system-bundling vector, extending value capture beyond commodity seals through bearing-seal integration. These three anchors represent distinct competitive positions: formulation-led premium positioning, integrated manufacturing scale, and motion-system bundling respectively.
| Leading Market Players |
|---|
| Trelleborg Sealing Solutions |
| Freudenberg Sealing Technologies |
| SKF |
| Parker Hannifin |
| Hallite Seals International |
| All Seals Inc. |
| Allied Metrics Seals & Fasteners |
| A.W. Chesterton |
| John Crane |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries polyurethane feedstock and compounded elastomer shipments that expose pneumatic seal pricing to container rate volatility and bunker fuel surcharges. This logistics cost layer amplifies the spread between Asian manufacturing-origin seals and European compounder-finished products, compressing margins for distributors caught between fixed contract pricing and floating freight exposure.
Pricing Analysis
Geographic price spreads between Chinese-origin polyurethane rod seals and German-manufactured fluoroelastomer formulations now exceed material cost differentials by a factor reflecting certification overhead and REACH compliance investment. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade perfluoroelastomer O-rings from industrial polyurethane U-cups and commodity nitrile replacements. Pricing pressure stems from REACH testing cost escalation freezing SME compounders out of EU machinery supply chains. Automotive OEM procurement teams exhibit highest price sensitivity in high-volume body-in-white applications, while semiconductor fab operators absorb material premiums for ultra-low outgassing specifications without volume negotiation leverage.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for pneumatic seal distributors serving North American automation OEMs. Manufacturing gravity centers on China for high-volume polyurethane extrusion, Germany for precision fluoroelastomer compounding, and Japan for FKM polymer feedstock. Raw material dependencies include isocyanates for TPU formulations, fluorinated monomers controlled by three Japanese chemical conglomerates, and specialty curatives for aerospace-grade compounds. Single-source vulnerability concentrates in FKM polymer allocation during semiconductor demand spikes. Distribution runs through authorized distributor networks for specification-grade seals and direct OEM contracts for high-volume automotive supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumatic seal market rewards compounders possessing decades of fluoroelastomer crosslinking expertise that retiring polymer chemists are not replacing at equivalent depth. This capability gap creates asymmetric returns for stakeholders who secure formulation talent or acquire reformulation-ready assets ahead of REACH authorization deadlines.
For Market Incumbents: Pre-empt magnetic actuator substitution in precision positioning equipment by accelerating digital twin integration for predictive seal replacement contracts. Secure backward integration into hydrogenated nitrile feedstock to reduce fluoropolymer reformulation cost exposure under ECHA restrictions. Anchor premium positioning through captive compounding operations that REACH-compliant competitors cannot replicate without €300,000+ substance registration investments.
For New Entrants and Emerging Players: Build out qualification pathways under India's PLI scheme for industrial machinery before multinational OEMs complete localized supplier onboarding. Target pneumatic valve applications in semiconductor fab construction waves where cleanroom-grade specifications command material premiums and incumbent capacity is allocation-constrained. Lead with metal-detectable, explosive-decompression-resistant compounds for 700-bar hydrogen infrastructure where standards remain unsettled.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned seal divisions lacking REACH reformulation investment commitment. Long-term viability hinges on compounders with demonstrated ECHA authorization navigation and hydrogen economy specification development. Watch for FKM polymer allocation announcements from Japanese chemical conglomerates as early signals of margin compression or qualification window opening for alternative elastomer suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Reformulation Investment | ECHA Article 57 compliance creates first-mover advantage for authorization-ready fluoroelastomer alternatives. |
| Hydrogen Infrastructure Qualification | 700-bar compression equipment specifications open addressable market before standards crystallize. |
| Digital Twin Integration | Predictive replacement algorithms embedded in IoT platforms generate recurring service revenue streams. |
| Indian PLI Localization | Domestic content requirements force multinational OEMs to qualify local compounders under BIS protocols. |
| Backward Integration into TPU Feedstock | Captive isocyanate supply secures margin control for high-cycle automation seal production. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and polymer chemists at compounder facilities; and secondary validation through customs trade data, SEC filings of listed seal manufacturers, ECHA substance registration databases, and SAMR GB standard documentation. Bottom-up triangulation against top-down market sizing cross-checked volume assumptions across material chemistry, product architecture, and end-use application segments.
Forecast inputs included factory automation densification rates, semiconductor fab construction pipelines, and REACH authorization timeline scenarios across the projection horizon. Segmentation modeling spanned material grade tier, product geometry, end-use industry, application duty cycle severity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from magnetic actuators and hydrogen infrastructure buildout assumptions.
Practitioners should monitor ECHA authorization list updates, FKM polymer allocation announcements from Japanese suppliers, and magnetic actuator penetration rates in lithography equipment for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Global Specialty Zeolites Market