
 Nickel Carbonate Market | 2026-2036
Nickel Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Carbonate Market Outlook
The capital-intensity gap between integrated miners and merchant chemical producers is collapsing as battery-grade specifications tighten. Norilsk Nickel leverages its Arctic ore base to sustain captive carbonate output. Umicore anchors European supply through hydrometallurgical refining competence. Jinchuan Group dominates Chinese battery precursor integration with in-house carbonate capacity.
Nickel carbonate is a basic nickel salt with the formula NiCO₃, typically produced through precipitation from nickel sulfate solutions using sodium carbonate and requiring controlled pH between 7.5 and 8.5 to achieve battery-grade purity above 99.5% Ni content; it serves primarily as a precursor for nickel oxide, nickel powder, and directly for lithium-ion battery cathode materials. High purity nickel carbonate commands the strongest margin pool as cathode makers reject low-grade material, while coated nickel carbonate grows fastest among product variants for its enhanced flow properties in automated battery lines. Battery production applications absorb the dominant volume share, though pigment production retains stable offtake from ceramic and glass manufacturers.
China's SAMR enforces GB/T standards for battery material purity, while the EU Battery Regulation through ECHA mandates carbon footprint disclosure and recycled content thresholds that reshape import eligibility. Indonesia's downstream processing rules through its mineral export ban framework force carbonate production localization rather than raw ore shipment. Stakeholders must monitor how divergent purity certifications across these jurisdictions fragment procurement strategies and capital allocation.
Market Dynamics
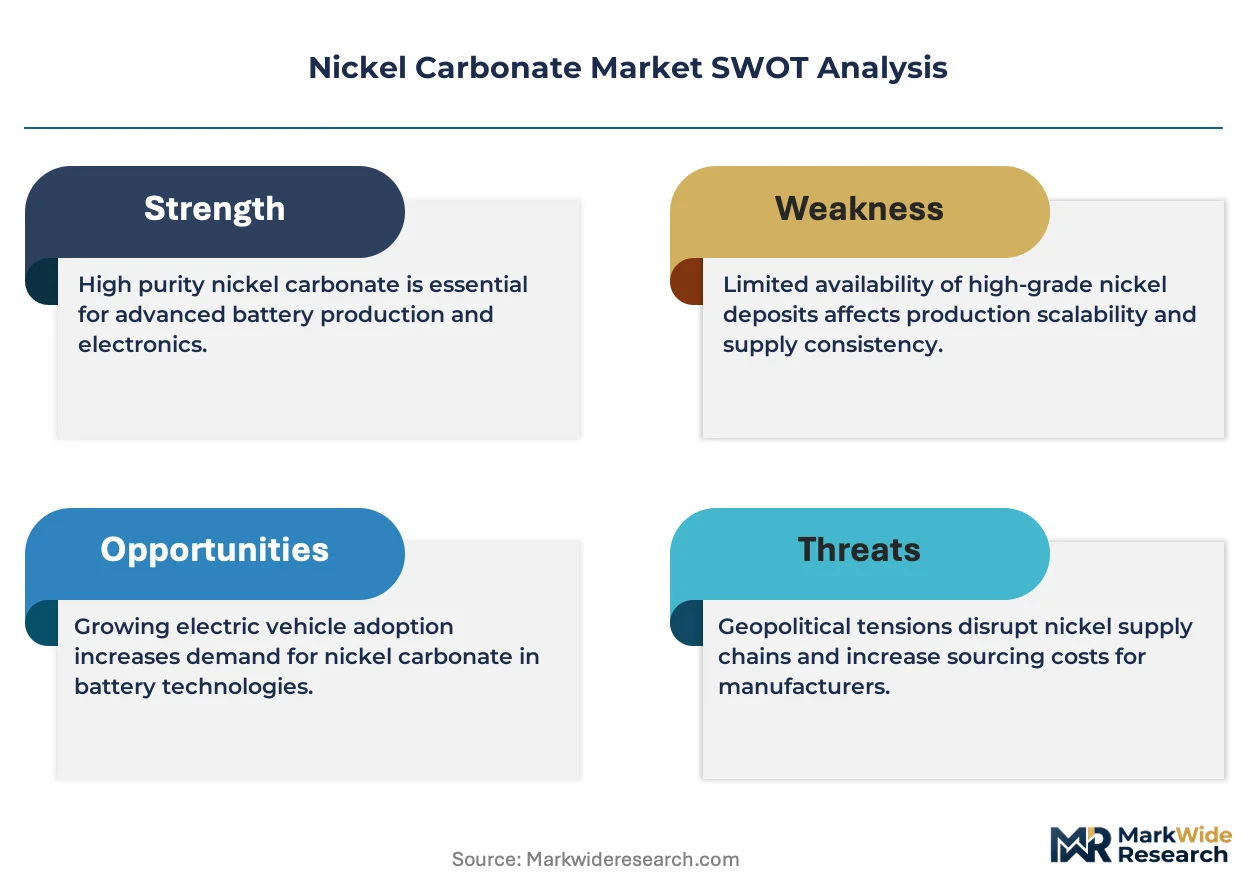
Battery-grade purity specifications are collapsing the historical margin gap between integrated miners and merchant chemical producers, forcing capital reallocation toward hydrometallurgical refining capacity in nickel processing corridors.
Growth Catalysts
- EV cathode precursor demand:Battery manufacturers are scaling procurement of high-purity nickel carbonate for lithium-ion cathode materials as electric vehicle production expands.
- Indonesia's downstream processing mandates:The mineral export ban framework forces carbonate production localization rather than raw ore shipment, anchoring regional capacity buildout.
- China's GB/T purity standards:SAMR-enforced battery material specifications tighten procurement criteria, pushing producers toward 99.5% plus Ni content material.
Market Restraints
- Sulfuric acid price volatility:Hydrometallurgical refining relies on concentrated acid for nickel sulfate intermediate production, exposing margin compression during energy price spikes.
- Arctic ore supply concentration:High-grade laterite and sulfide deposits cluster in geographically remote jurisdictions with concentrated rail and port infrastructure.
- HPAL technical complexity:High-pressure acid leaching for laterite processing demands precise temperature and pressure control, limiting operational replication.
Strategic Opportunities
- Coated nickel carbonate variants:Enhanced flow properties for automated battery cathode lines represent the fastest-growing product category by application.
- EU Battery Regulation recycled content thresholds:ECHA-mandated carbon footprint disclosure and recycling quotas reshape import eligibility for non-European producers.
- Second-life battery material recovery:Hydrometallurgical circuits are adapting to process end-of-life cathode scrap into battery-grade carbonate feedstock.
Industry Challenges
- HPAL engineering talent scarcity:Specialized process design and commissioning expertise for high-pressure acid leaching facilities commands premium compensation.
- Battery-grade certification timelines:Cathode maker qualification protocols require 12-18 month validation cycles before volume procurement approval.
- Legacy rotary kiln integration:Existing nickel oxide producers face retrofit complexity when adding carbonate precipitation circuits to established calcination lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Carbonate Market |
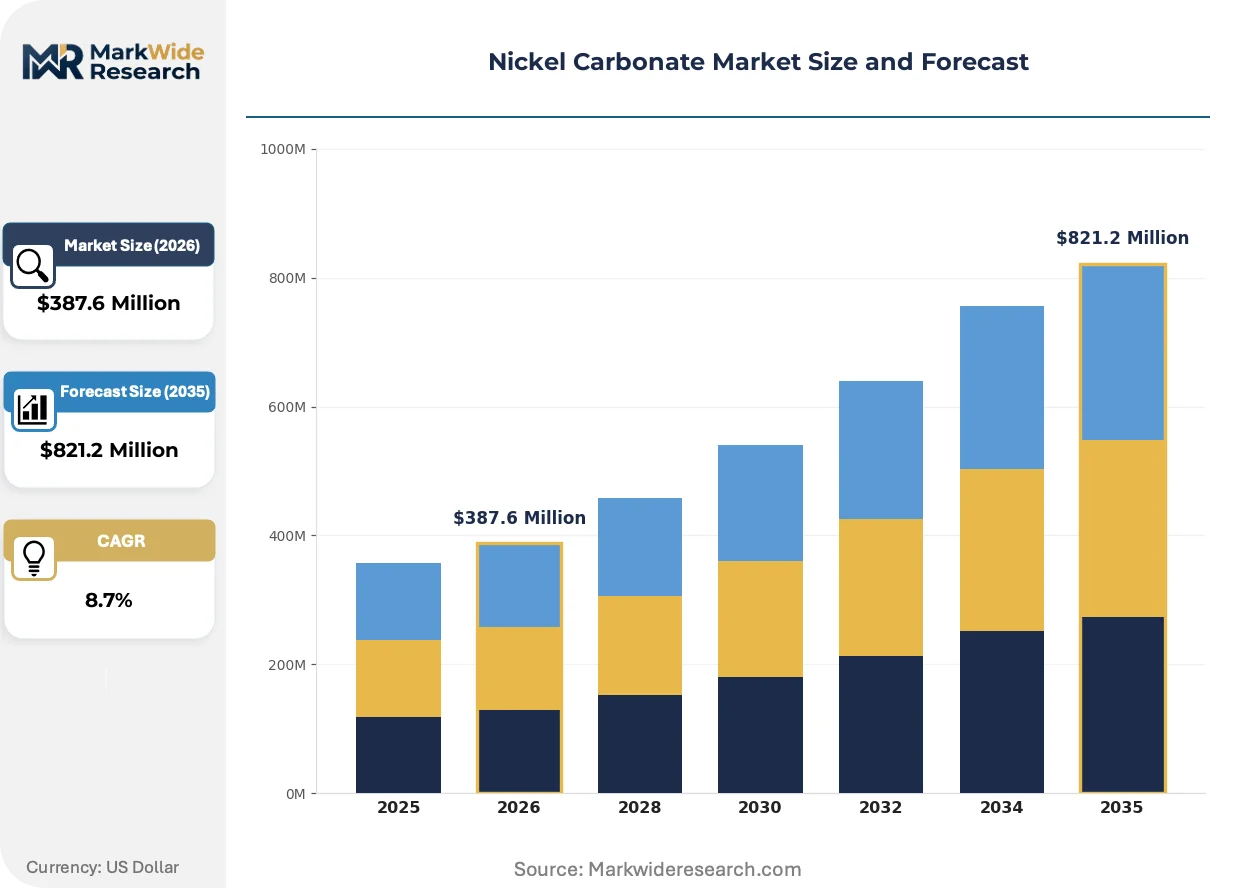
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity Nickel Carbonate, Low Purity Nickel Carbonate, Coated Nickel Carbonate, Granulated Nickel Carbonate Application: Battery Production, Chemicals Manufacturing, Pigment Production, Catalysts End User: Electronics, Automotive, Aerospace, Renewable Energy Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Seido Chemical, Norilsk Nickel, Umicore, Fairsky Industrial, Xingzhong New Material, Eramet, Mechema, Aqua Metals, Jinchuan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Carbonate Market Strategic Shifts
Refining technology is fragmenting the traditional integrated-miner advantage, while regulatory carbon-accounting requirements and procurement centralization reshape competitive positioning across the value chain.
Continuous precipitation technology is fragmenting batch-process economics in battery-grade nickel carbonate production. Chinese cathode makers are adopting automated pH-controlled crystallization systems at scale. This process intensification is fragmenting the historical cost advantage of large-batch sulfide-based refiners.
REACH-compliant carbon footprint disclosure through ECHA is mandating scope-three emissions accounting for battery material imports. European cathode producers now require supply-chain documentation from mine to carbonate. Indonesian and Congolese processors are responding by installing on-site renewable generation to satisfy EU Battery Regulation eligibility.
Long-term offtake contracting is displacing spot-market procurement for battery-grade material. Korean and Japanese cathode manufacturers are locking five-year supply agreements directly with Indonesian HPAL operators. This channel consolidation is most visible in binding pre-financing structures for greenfield refining projects.
Nickel Carbonate Market Segmentation
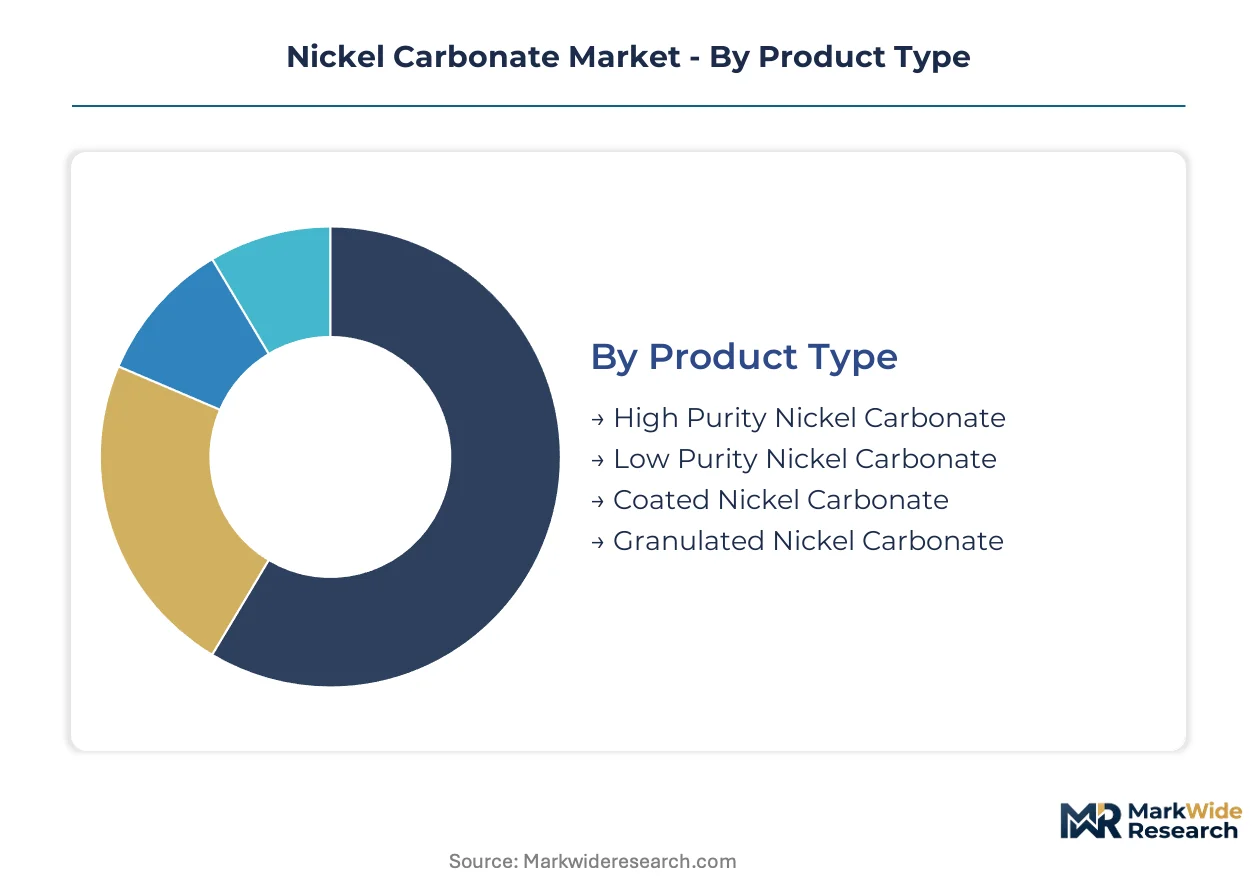
Segmentation in the nickel carbonate market reveals how purity grades and application specifications fragment procurement strategies. Battery-grade certification requirements from SAMR and ECHA create tiered demand pools that reshape pricing and supply allocation across product categories.
Product Type:
Regulatory differentiation between battery-grade and industrial-grade material splits the product landscape into distinct compliance tiers, with purity thresholds enforced through national certification regimes.
- High Purity Nickel Carbonate:Material exceeding 99.5% Ni content meets GB/T standards for lithium-ion cathode precursors. Chinese and Indonesian HPAL operators concentrate output here to satisfy SAMR-mandated battery material specifications.
- Coated Nickel Carbonate:Surface-treated variants with enhanced flow properties enable automated dosing in high-throughput cathode production lines. Korean and Japanese battery makers are scaling procurement of this format as manufacturing automation accelerates.
- Low Purity Nickel Carbonate:Industrial-grade material serves ceramic pigment and catalyst applications where battery-grade certification is not required.
- Granulated Nickel Carbonate:Dense particle morphology reduces dust generation during handling and transport for chemical processing operations.
High purity nickel carbonate handles the majority of throughput; coated nickel carbonate is the fastest mover on share.
Application:
Cost tier differentiation separates battery-grade material commanding premium pricing from industrial applications absorbing commodity-grade supply.
- Battery Production:Cathode precursor demand absorbs the dominant volume share as EV manufacturing scales. Chinese, Indonesian, and Congolese processing corridors anchor supply for this segment.
- Pigment Production:Ceramic and glass manufacturers maintain stable offtake for colorant applications, though this segment operates outside battery-grade certification requirements.
- Chemicals Manufacturing:Nickel carbonate serves as feedstock for nickel oxide, nickel powder, and specialty salt production.
- Catalysts:Petrochemical and hydrogenation processes utilize nickel carbonate-derived materials for catalytic applications.
Battery production commands the dominant revenue pool; pigment production provides the most stable demand baseline through economic cycles.
End User:
Customer type concentration in automotive and electronics channels drives long-term contracting behavior and direct procurement relationships.
- Automotive:EV manufacturers and tier-one battery suppliers lock multi-year offtake agreements with integrated carbonate producers. Korean and Japanese cathode makers are binding five-year supply structures with Indonesian HPAL operators.
- Electronics:Consumer battery and electronic component manufacturers require consistent high-purity supply for portable power applications.
- Renewable Energy:Grid-scale battery storage projects are emerging as a demand segment with distinct volume and specification requirements.
- Aerospace:Specialized coating and catalyst applications utilize nickel carbonate for high-performance material formulations.
Automotive channels dominate volume concentration; renewable energy is expanding most quickly as utility-scale storage deployment accelerates.
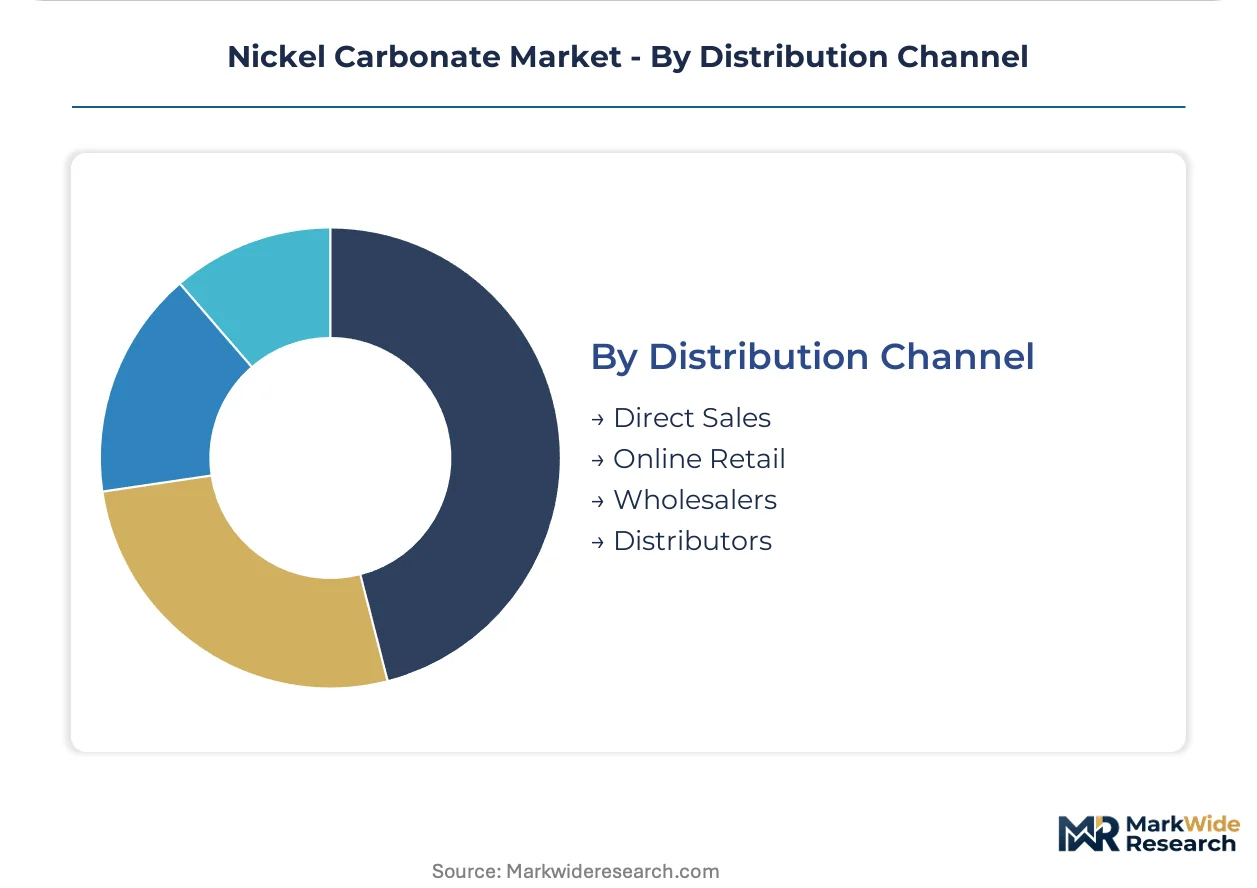
Distribution Channel:
Supply concentration in integrated producer-cathode maker relationships is displacing traditional merchant distribution for battery-grade material.
- Direct Sales:Long-term offtake contracts between HPAL operators and cathode manufacturers bypass intermediaries. This channel captures the majority of battery-grade volume as procurement centralizes.
- Distributors:Regional chemical distributors serve industrial-grade applications in pigments and catalysts where specification requirements permit fragmented sourcing.
- Wholesalers:Bulk material handlers aggregate smaller industrial orders for ceramic and glass manufacturing customers.
- Online Retail:Digital platforms facilitate spot procurement for laboratory and research-scale quantities.
Direct sales handles the majority of throughput; distributor channels are gaining share fastest in industrial-grade segments as merchant chemical producers seek market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates Chinese battery-grade carbonate from Indonesian HPAL output, with the former commanding premiums through SAMR-certified purity while the latter competes on scale under downstream processing mandates.
China
Domestic cathode precursor demand absorbs the dominant volume share as EV manufacturing scales across the Yangtze River Delta. SAMR enforces GB/T standards for battery material purity, tightening procurement criteria toward 99.5% plus Ni content. Jinchuan Group anchors supply integration through in-house carbonate capacity in Gansu province.
Indonesia
Mineral export ban frameworks force carbonate production localization rather than raw ore shipment, anchoring regional HPAL capacity buildout. The country's downstream processing rules reshape capital allocation toward integrated refining. Morowali Industrial Park concentrates hydrometallurgical operations as Korean and Japanese cathode makers lock five-year offtake structures.
Democratic Republic of Congo
Cobalt-nickel laterite deposits feed hydrometallurgical circuits serving battery supply chains. The country's mineral export regulations favor in-country refining over raw concentrate shipment. Lualaba province hosts processing corridors where integrated operators precipitate carbonate for regional precursor supply.
United States
Domestic battery manufacturing investments under the Inflation Reduction Act reshape carbonate procurement eligibility through critical mineral sourcing requirements. EPA and state-level environmental permitting govern hydrometallurgical facility development. The Great Lakes region concentrates legacy nickel refining infrastructure adapting to battery-grade specifications.
Finland
Norilsk Nickel leverages its Arctic ore base to sustain captive carbonate output serving European cathode makers. REACH-compliant carbon footprint disclosure through ECHA mandates scope-three emissions accounting for battery material imports. Harjavalta refinery anchors Nordic hydrometallurgical capacity with direct precursor supply relationships.
Nickel Carbonate Market Competitive Environment
Concentration sits with integrated mining-chemical conglomerates and specialized hydrometallurgical refiners. The competitive structure fragments across three tiers: diversified miners with captive carbonate output, merchant chemical producers serving industrial applications, and emerging HPAL operators in Indonesian processing corridors. Strategic moves center on backward integration into nickel sulfate intermediates and long-term offtake contracting with cathode manufacturers.
Among diversified mining conglomerates, Norilsk Nickel and Jinchuan Group exemplify integrated archetypes with captive carbonate capacity anchored to ore bases. Umicore represents the specialized hydrometallurgical refiner model, leveraging European regulatory compliance competence. These three occupy distinct competitive positions: Arctic ore-based integration, Chinese domestic precursor supply, and REACH-certified European refining.
| Leading Market Players |
|---|
| Seido Chemical |
| Norilsk Nickel |
| Umicore |
| Fairsky Industrial |
| Xingzhong New Material |
| Eramet |
| Mechema |
| Aqua Metals |
| Jinchuan Group |
| Others |
Value Chain & Pricing Dynamics
GB/T certification from SAMR gates both supplier qualification and price differentiation in battery-grade nickel carbonate, creating a bifurcated market where certified Chinese producers command premiums while uncertified Indonesian HPAL output competes on volume under downstream processing mandates.
Pricing Analysis
Configured-to-order pricing for coated nickel carbonate variants carries a substantial premium over standard high-purity material. Contract-based long-term offtake dominates battery-grade procurement, with price differentiation driven by SAMR certification status and cathode maker validation timelines. Cost compression in industrial-grade tiers intensifies as merchant chemical producers absorb sulfuric acid volatility. Pigment manufacturers exhibit highest price sensitivity; automotive cathode makers prioritize supply security over unit economics.
Supply Chain Analysis
Strategic stockpiling of nickel sulfate intermediates prevails among HPAL operators hedging against sulfuric acid price spikes. Supply concentrates in Indonesia, China, and the Democratic Republic of Congo as mineral export bans force in-country refining. Raw material flows draw from laterite ore deposits, concentrated acid supplies, and sodium carbonate reagents. Single-source vulnerability runs through Arctic sulfide concentrate routes. Distribution runs through direct sales channels binding HPAL operators to Korean and Japanese cathode manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery material procurement platforms are consolidating around cathode maker-HPAL operator interoperability, with ECHA carbon footprint disclosure and SAMR purity standards creating ecosystem lock-in effects that reshape competitive moats.
For Market Incumbents: Fortify backward integration into nickel sulfate intermediates to secure margin capture as merchant chemical producers face HPAL technical complexity barriers. Expand captive carbonate capacity in Indonesian processing corridors before downstream processing mandates saturate regional land and power access. Prioritize SAMR certification maintenance as emerging HPAL operators challenge qualification timelines.
For New Entrants and Emerging Players: ECHA REACH fast-track certification for carbon footprint disclosure opens procurement eligibility with European cathode makers seeking scope-three compliance. Target industrial-grade pigment applications as the most penetrable segment, where battery-grade certification requirements do not apply. Pursue joint venture structures with established HPAL engineering firms to overcome technical commissioning barriers.
For Investors and Strategic Acquirers: EU Battery Regulation recycled content thresholds reshape the acquisition landscape toward hydrometallurgical operators with end-of-life cathode processing adaptation. Five-to-ten year viability favors integrated miners with captive ore bases over merchant refiners exposed to input volatility. Monitor Indonesian downstream processing permit issuance velocity as the inflection signal for regional capacity saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Capacity Expansion | Indonesian downstream mandates force localization of carbonate production rather than raw ore export. |
| Backward Integration into Nickel Sulfate | Jinchuan Group and Norilsk Nickel secure margin capture through captive intermediate supply. |
| Long-term Offtake Agreement | Korean and Japanese cathode makers bind five-year structures with Morowali Industrial Park operators. |
| Coated Product Line Introduction | Surface-treated variants enable automated dosing in high-throughput battery manufacturing lines. |
| Joint Venture with Engineering Specialist | HPAL technical complexity scarcity commands premium partnerships for facility commissioning. |
Study Parameters
Operator-level perspectives from HPAL plant managers, cathode maker procurement leads, hydrometallurgical engineering specialists, and SAMR certification auditors anchored the qualitative base. Secondary validation drew from customs trade data, SEC filings of integrated mining conglomerates, ECHA REACH registration databases, and Indonesian mineral export permit records. Bottom-up capacity assessments triangulated against top-down demand modeling from EV production forecasts.
Sensitivity analysis tested forecast outputs across purity grade segmentation, regional processing corridor development pace, and cathode chemistry evolution. The analytical framework modeled volume and value across product type, application tier, end-user industry, and distribution channel dimensions throughout the projection horizon. CAGRs derived from installed HPAL capacity ramps, cathode precursor demand curves, and regulatory compliance timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EV penetration and intact mineral export ban frameworks; material deviation would warrant model refresh. Revision becomes warranted when Indonesian downstream processing permit issuance velocity or ECHA carbon threshold enforcement intensity crosses material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Refined Wax Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Global Bulk Ferroalloys Market