
 Asia-Pacific Bitumen Market | 2026-2036
Asia-Pacific Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bitumen Market Insights
The gap between premium polymer-modified bitumen and commodity penetration-grade supply is expanding across the Asia-Pacific region. Shell Plc leverages its integrated refinery network to sustain differentiated product lines in Australia and Southeast Asia. Indian Oil Corporation anchors domestic supply through its Gujarat and Bihar refineries, while JXTG Nippon Oil & Energy Corporation competes on specialized maritime-grade formulations for port infrastructure.
Bitumen comprises the heaviest fraction of crude oil distillation, with softening points typically ranging from 35°C to 70°C depending on grade and intended service temperature; refiners blend vacuum residue with lighter cutters or synthetic polymers to achieve target rheological properties for specific paving or waterproofing duties. Polymer Modified Bitumen commands disproportionate margin pools as highway agencies specify elastomer-enhanced binders for high-traffic corridors, while emulsion grades capture maintenance-cycle volume across tropical climates where hot-mix logistics prove costly. Road Construction remains the dominant end-use industry, though waterproofing applications in India's coastal megacities are gaining specification share.
India's BIS paving standards, Australia's Austroads binder specifications, and Japan's JIS A 1204 testing protocols collectively shape product certification requirements and import eligibility across the region. Contractors in Indonesia and Vietnam now face heightened scrutiny on rutting resistance and fatigue performance, filtering market access toward suppliers with accredited laboratory networks. Stakeholders must track how national infrastructure budgets align with evolving binder-grade mandates to anticipate procurement shifts.
Market Dynamics
Polymer-modified binder specifications are bifurcating procurement pools across Southeast Asian highway agencies, compressing margins for unmodified penetration-grade suppliers while elevating technical certification barriers to contract eligibility.
Growth Catalysts
- Trans-Java Toll Road Expansion:Indonesia's 1,800-kilometer expressway network extension absorbs bulk bitumen volumes for multi-lane pavement structures requiring high-performance binders.
- BIS Paving-Grade Tightening:India's Bureau of Indian Standards elevated rutting-resistance thresholds, redirecting contractor specifications toward elastomer-enhanced formulations.
- Port-Access Corridor Development:Maritime-grade bitumen demand concentrates in Vietnam and the Philippines where container terminal expansions specify high-softening-point binders for heavy-vehicle loading zones.
Market Restraints
- Crude Residue Supply Concentration:Vacuum residue availability tightens as regional refineries prioritize lighter distillate yields, concentrating heavy fraction supply among integrated producers with coking flexibility.
- Polymer Additive Cost Volatility:Styrene-butadiene-styrene block copolymer prices fluctuate with petrochemical feedstock cycles, compressing formulation margins for modified binder specialists.
- Cold-Mix Emulsion Substitution:Bitumen emulsion technologies for tropical maintenance cycles displace hot-mix volumes in Indonesia's secondary road rehabilitation programs.
Strategic Opportunities
- Waterproofing Specification Penetration:Coastal megacities in India and Bangladesh are specifying polymer-modified bitumen membranes for building envelope applications beyond traditional road construction.
- Recycled Asphalt Pavement Mandates:Australia's Austroads framework incentivizes reclaimed binder integration, creating demand for rejuvenating agent technologies compatible with aged asphalt stockpiles.
- Direct Refinery-Contractor Procurement:Large infrastructure consortia in Thailand and Malaysia are bypassing distributor tiers through volume offtake agreements with integrated suppliers.
Industry Challenges
- Accredited Laboratory Network Requirements:Indonesia's highway agency now mandates JIS A 1204-equivalent testing documentation for import eligibility, forcing smaller traders to outsource certification.
- Hot-Mix Logistics Constraints:Tropical climate conditions limit haul distances for temperature-sensitive binders, requiring distributed storage infrastructure that strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bitumen Market |
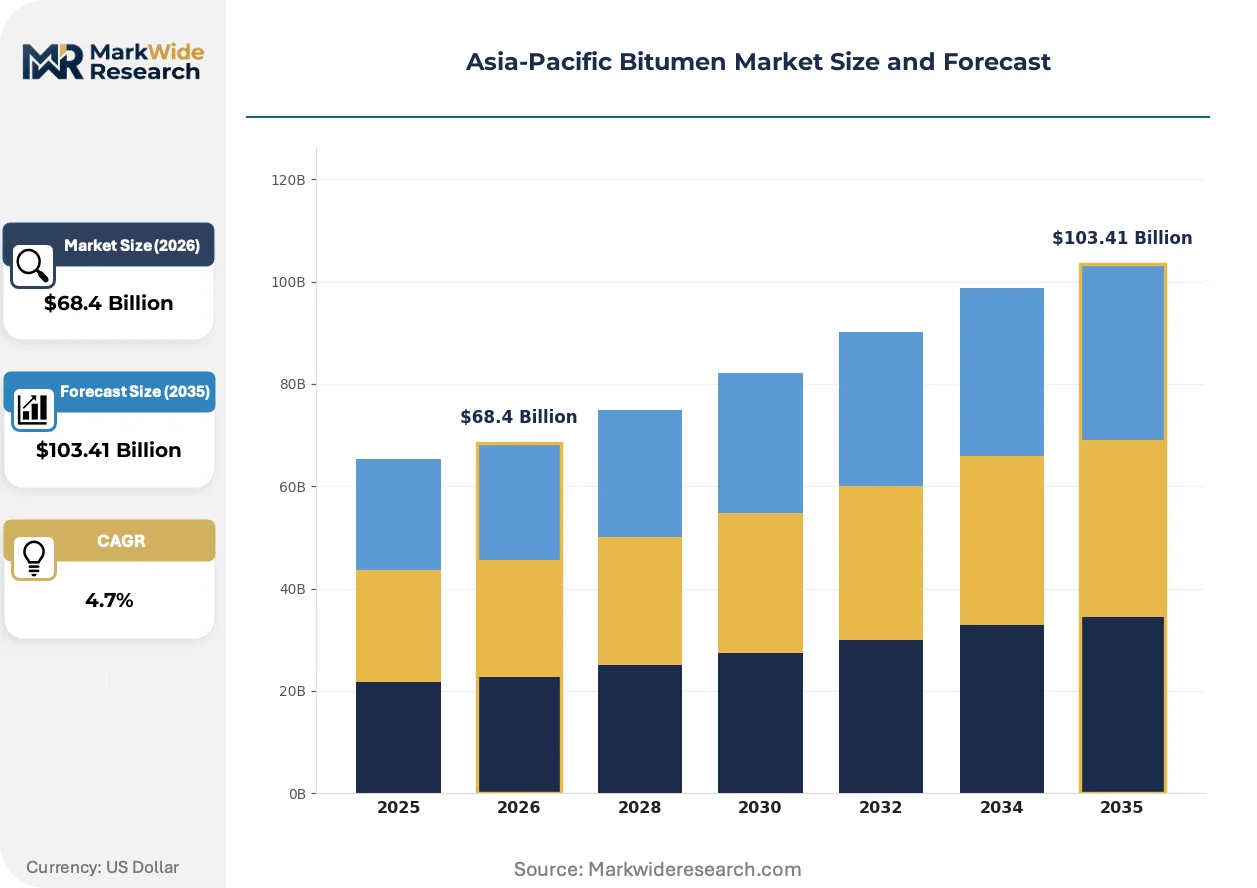
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penetration Grade, Emulsion, Polymer Modified Bitumen, Cutback Bitumen End Use Industry: Road Construction, Waterproofing, Roofing, Paving Application: Infrastructure, Maintenance, Residential, Industrial Sales Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | China Petroleum & Chemical Corporation, Shell Plc, BP PLC, Exxon Mobil Corporation, JXTG Nippon Oil & Energy Corporation, Indian Oil Corporation, TotalEnergies SE, PetroChina Company Limited, Nynas AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bitumen Market Trends and Innovations
Binder formulation science is converging with performance-based contracting models across Asia-Pacific highway procurement, compressing specification cycles and elevating rheological testing requirements for supplier qualification.
Crumb rubber modified bitumen is integrating recycled tire-derived polymers into high-traffic corridor specifications. Thailand's Department of Highways now mandates rubberized binder content for expressway surface layers. The technology is integrating waste stream valorization with pavement durability extension, creating captive feedstock advantages for suppliers with tire shredding partnerships.
India's BIS paving standards now incorporate multiple stress creep recovery testing protocols adopted from Strategic Highway Research Program methodologies. Contractors must demonstrate binder elastic recovery percentages under standardized loading cycles. State highway agencies in Maharashtra and Tamil Nadu have phased in these requirements for national highway tenders, filtering supplier pools toward accredited laboratories.
Performance-based maintenance contracts are displacing unit-price procurement for arterial road networks. Australian state road authorities now compensate contractors on international roughness index outcomes rather than tonnage delivered. This reconfiguration concentrates contract awards toward integrated suppliers with in-house paving capabilities and pavement management system expertise.
Asia-Pacific Bitumen Market Segmentation
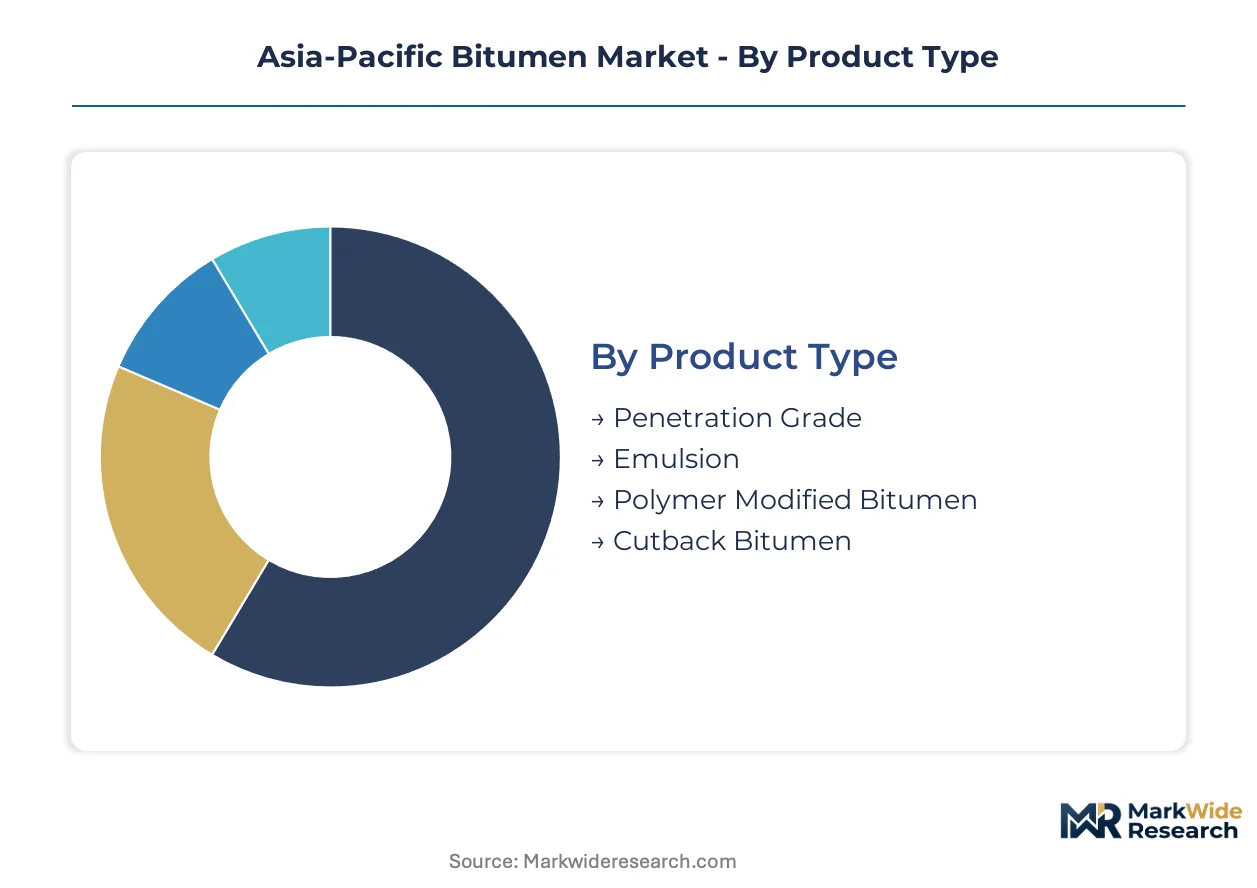
Asia-Pacific bitumen procurement splits across performance tiers, end-use specifications, and channel structures that determine margin capture. Contractors in Indonesia, India, and Vietnam face divergent specification regimes that reshape supplier positioning across each segment boundary.
Product Type:
Buyers select grades based on traffic loading, climate exposure, and agency certification requirements rather than price alone.
- Polymer Modified Bitumen:Elastomer-enhanced formulations incorporate styrene-butadiene-styrene or crumb rubber to achieve superior rutting resistance and fatigue performance. India's Maharashtra and Tamil Nadu state highway agencies now mandate polymer modification for national highway tenders, compressing eligibility to accredited laboratories.
- Penetration Grade:Conventional vacuum residue binders remain the volume foundation for secondary roads and rural networks across Southeast Asia. Indonesia's Trans-Java Toll Road extension still absorbs substantial penetration-grade volumes for base and binder courses where traffic loading permits.
- Emulsion:Water-based dispersions enable cold-mix applications in tropical maintenance cycles where hot-mix logistics face haul-distance constraints.
- Cutback Bitumen:Solvent-reduced formulations serve remote paving sites lacking hot-mix plant infrastructure, particularly in the Philippines and eastern Indonesia.
Penetration Grade leads on scale; Polymer Modified Bitumen leads on momentum.
End Use Industry:
Application durability requirements determine formulation complexity and certification depth.
- Road Construction:Expressway agencies in Thailand, Vietnam, and Indonesia specify performance-graded binders with multiple stress creep recovery thresholds. Australia's Austroads framework now incentivizes reclaimed binder integration, creating parallel demand for rejuvenating agent compatibility.
- Waterproofing:Polymer-modified membranes penetrate building envelope specifications in India's coastal megacities and Bangladesh's deltaic urban centers, extending bitumen demand beyond traditional paving.
- Roofing:Oxidized bitumen sheets serve industrial and commercial building stock across Australia's eastern seaboard and Japan's manufacturing belts.
- Paving:Airport runways and container terminals in Vietnam and the Philippines specify high-softening-point maritime-grade formulations for heavy-vehicle loading zones.
Road Construction dominates volume contribution; Waterproofing demonstrates the steepest expansion trajectory.
Application:
Project scale and procurement modality separate volume commitments from spot-market transactions.
- Infrastructure:Multi-lane expressways, port-access corridors, and airport expansions concentrate bulk offtake through tender-based procurement with extended performance warranties.
- Maintenance:Resurfacing and rehabilitation programs across Indonesia's secondary road network displace hot-mix volumes toward emulsion-based cold-mix technologies.
- Residential:Driveway and private road paving in Australia's suburban corridors generates dispersed demand through distributor channels.
- Industrial:Warehouse flooring and yard paving in Thailand's Eastern Economic Corridor absorbs specialized binder grades with chemical resistance properties.
Infrastructure commands contract value; Maintenance expands most quickly.
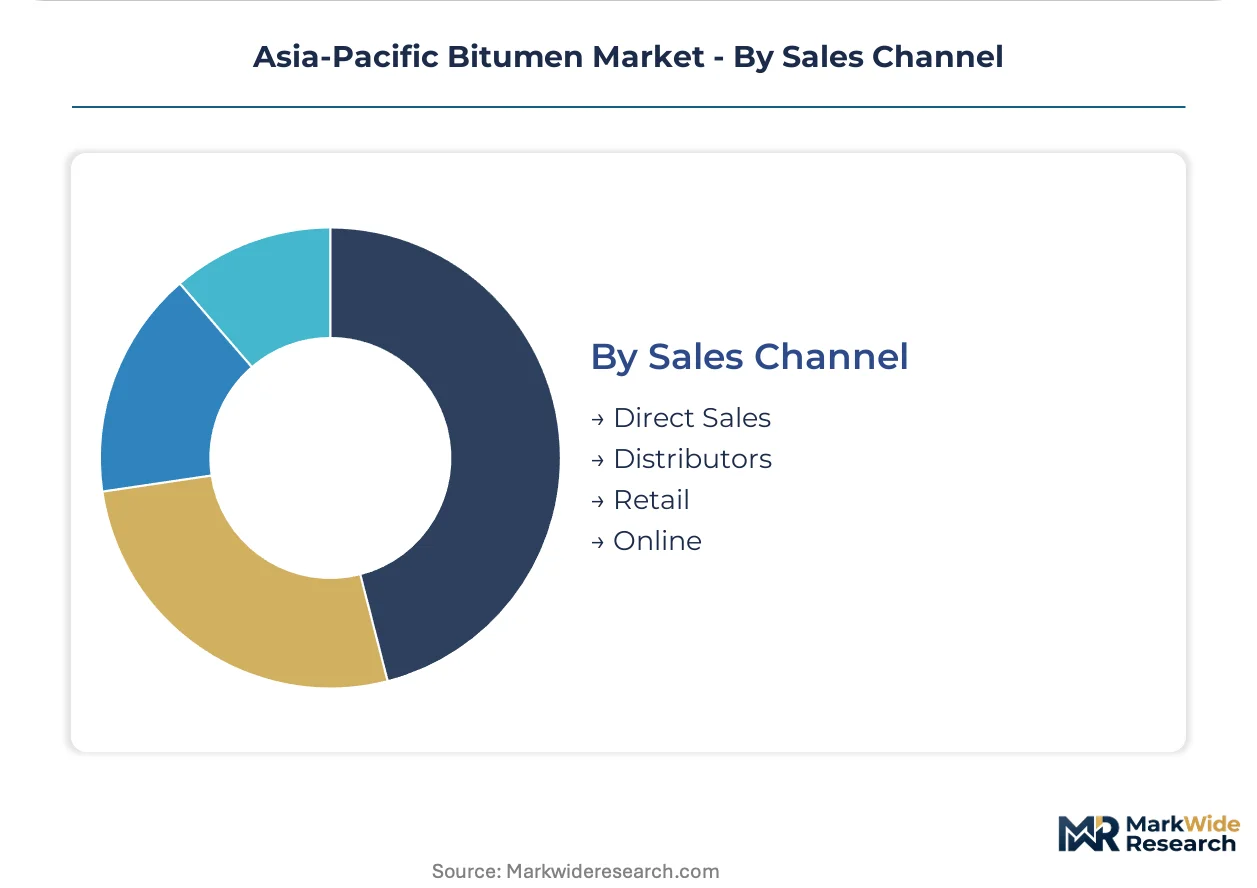
Sales Channel:
Volume scale and technical service requirements determine channel selection.
- Direct Sales:Integrated refiners in Australia and Thailand negotiate volume offtake agreements with large infrastructure consortia, bypassing distributor margins.
- Distributors:Regional traders manage storage infrastructure and logistics for dispersed contractors across Indonesia's archipelago and India's state-level markets.
- Retail:Bagged and drum-packaged bitumen serves small-scale waterproofing and maintenance contractors through construction material yards.
- Online:Digital procurement platforms emerge for standardized emulsion and cutback grades in India's fragmented contractor base.
Distributors retain volume leadership; Direct Sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refinery engineers and paving technologists concentrate in Asia-Pacific's integrated petrochemical corridors, anchoring formulation expertise near heavy crude processing hubs and major highway agency procurement centers.
Indonesia
The Trans-Java Toll Road extension and port-access corridor developments absorb substantial polymer-modified and penetration-grade volumes. The country's national highway agency mandates JIS A 1204-equivalent testing documentation for import eligibility, tightening supplier certification requirements. Java's northern coastal industrial belt hosts the densest concentration of storage terminals serving Jakarta-Surabaya expressway construction.
India
National highway tenders in Maharashtra and Tamil Nadu now require elastomer-enhanced binders under elevated BIS rutting-resistance thresholds. The Bureau of Indian Standards incorporated multiple stress creep recovery testing protocols from Strategic Highway Research Program methodologies. Gujarat's Koyali refinery complex and Bihar's Barauni facility anchor domestic supply chains for contractor procurement.
Thailand
The Department of Highways mandates crumb rubber modified bitumen content for expressway surface layers, integrating recycled tire-derived polymers into high-traffic corridor specifications. Austroads-aligned performance-based contracting models now compensate contractors on international roughness index outcomes. The Eastern Economic Corridor's industrial yard paving generates specialized demand for chemically resistant binder grades.
Australia
State road authorities have displaced unit-price procurement with performance-based maintenance contracts tied to pavement condition metrics. The Austroads framework incentivizes reclaimed binder integration through recycled asphalt pavement mandates. New South Wales and Victoria host the primary laboratory accreditation networks qualifying suppliers for arterial network tenders.
Vietnam
Container terminal expansions in Hai Phong and Ba Ria-Vung Tau specify high-softening-point maritime-grade formulations for heavy-vehicle loading zones. National transport infrastructure programs prioritize multi-lane expressway development connecting northern manufacturing belts with central port facilities. Ho Chi Minh City's peripheral industrial zones concentrate waterproofing membrane demand for commercial building envelopes.
Asia-Pacific Bitumen Market Competitive Landscape
Capital-heavy integrated refiners compete with specialized blending operations across Asia-Pacific bitumen supply chains. The market structure concentrates around state-owned petroleum corporations with captive vacuum residue streams and regional traders managing distributed storage infrastructure. Three archetypes dominate: integrated refiners with backward control into crude distillation, polymer modification specialists with accredited laboratory networks, and distributor-traders bridging logistics gaps across archipelagic geographies. Competitive positioning hardens through direct refinery-contractor offtake agreements and certification capacity investments.
Among integrated state-owned suppliers, China Petroleum & Chemical Corporation and PetroChina Company Limited exemplify the scale-driven archetype with refinery-anchored supply positions. Shell Plc occupies a differentiated tier through polymer-modified formulation capabilities and laboratory accreditation depth. Indian Oil Corporation represents the national champion model with domestic refinery coverage and BIS-compliant certification infrastructure. These three anchors illustrate how geographic coverage, regulatory compliance capacity, and integration depth separate procurement eligibility tiers across national highway agency tenders.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Shell Plc |
| BP PLC |
| Exxon Mobil Corporation |
| JXTG Nippon Oil & Energy Corporation |
| Indian Oil Corporation |
| TotalEnergies SE |
| PetroChina Company Limited |
| Nynas AB |
| Others |
Pricing and Supply Chain Analysis
Backward integration into vacuum residue streams anchors pricing power for state-owned refiners across the Asia-Pacific bitumen market, while fragmented distributor networks struggle to pass through polymer additive cost swings to price-sensitive rural contractors.
Pricing Analysis
Bundled technical certification and laboratory testing services separate integrated refiner pricing from unbundled commodity spot trading. Contract-based long-term offtake agreements dominate infrastructure procurement, with price differentiation driven by BIS compliance grade and volume scale. Cost compression in penetration-grade supply is intensifying because Indonesian distributors face margin pressure from cold-mix emulsion substitution. Rural secondary road contractors exhibit highest price sensitivity; expressway consortia with direct refinery relationships show lowest.
Supply Chain Analysis
Accredited laboratory qualification requirements now gate import eligibility, concentrating supply among integrated producers with JIS A 1204-equivalent certification infrastructure. Manufacturing gravity centers on India, Indonesia, and Thailand, with vacuum residue feedstock drawing from Gujarat's Koyali complex and Bihar's Barauni facility. Styrene-butadiene-styrene polymer supply rests on petrochemical feedstock cycles, creating single-source vulnerability for modified binder specialists. Distribution runs through regional traders managing archipelagic storage terminals across Indonesia and state-level distributor networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific bitumen market functions as a regulatory compounder where India's BIS rutting-resistance threshold elevation and Indonesia's JIS A 1204 import mandates continuously restructure procurement eligibility tiers.
For Market Incumbents: Acquire accredited laboratory networks to defend against certification-barrier escalation. Indian Oil Corporation and Shell Plc should expand BIS-compliant testing infrastructure in Maharashtra and Tamil Nadu to preempt state highway agency tender filtering. Backward integration into crumb rubber feedstock partnerships insulates against SBS price volatility threatening modified binder margins. For New Entrants and Emerging Players: Small-scale waterproofing contractors in India's coastal megacities represent an underserved buyer archetype with limited penetration-grade supplier attention. Emulsion-based cold-mix technologies for Indonesia's secondary road rehabilitation programs offer the most penetrable application segment. A go-to-market angle anchored on distributed storage infrastructure and tropical climate logistics expertise bypasses integrated refiner dominance. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor-traders with archipelagic terminal networks because Indonesia's import certification mandates are forcing consolidation among smaller traders lacking JIS A 1204-equivalent documentation. Platform viability extends through the medium-term horizon as performance-based contracting displaces unit-price procurement. The signal to watch is Australian state road authority adoption of international roughness index compensation models spreading across Southeast Asian highway agencies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive SBS or crumb rubber supply stabilizes modified binder margins against petrochemical volatility. |
| Accredited Laboratory Network Expansion | BIS and JIS A 1204 certification infrastructure filters tender eligibility toward compliant suppliers. |
| Direct Refinery-Contractor Offtake Agreements | Volume commitments with Thai and Malaysian infrastructure consortia bypass distributor margin layers. |
| Cold-Mix Emulsion Technology Deployment | Tropical maintenance cycle applications in Indonesia displace hot-mix logistics constraints. |
| Waterproofing Specification Penetration | Polymer-modified membrane demand in Mumbai and Dhaka extends bitumen beyond road construction. |
Research Methodology
Coverage spans India, Indonesia, Thailand, Australia, and Vietnam, with primary inputs from each market's refinery operations, highway agency procurement officers, and distributor logistics managers. Secondary validation drew from BIS paving standard documentation, Austroads framework publications, customs trade data for vacuum residue movements, and SEC filings from integrated petroleum corporations. Bottom-up volume modeling across polymer modified, penetration-grade, emulsion, and cutback product tiers triangulated against top-down refinery capacity assessments.
Granularity extended to product type, end-use industry, application scale, and sales channel dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves responding to national infrastructure budget trajectories and binder-grade mandate evolution. Forecast inputs incorporated Trans-Java Toll Road extension phasing, Maharashtra and Tamil Nadu state highway tender specifications, and Thailand's crumb rubber mandate implementation pace.
Underlying measurement precision varies by segment; polymer modified bitumen carries tighter precision than penetration-grade given specification standardization, while waterproofing application forecasting exhibits wider confidence intervals due to building code adoption variability. Forecasts reflect assumptions on crude residue availability and polymer additive cost trajectories. Deviation in Indonesian import certification enforcement stringency or Indian state-level BIS adoption timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
North America Calcium Chloride Market