
 Ruminant Feed Additive Market | 2026-2036
Ruminant Feed Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Ruminant Feed Additive Market Insights
The EU Green Deal is consolidating demand around methane-inhibiting feed additives across European dairy supply chains. Cargill, Incorporated leverages its integrated supply chain to pre-mix precision additives at regional compounding facilities. DSM anchors its position through proprietary 3-NOP compounds that suppress enteric fermentation in lactating herds. BASF SE competes on synthetic vitamin stability across variable forage conditions.
Ruminant feed additives comprise biologically active compounds including probiotics, enzymes, and vitamins formulated to optimize rumen fermentation efficiency, nutrient absorption, and animal metabolic performance. Probiotics and enzymes dominate current value pools as livestock operators phase out antibiotic growth promoters under tightening residue standards. The natural ingredient source segment captures expanding margin pools as export-oriented dairies in Oceania and North America pursue non-GMO and organic certification premiums. Synthetic vitamins still occupy volume leadership in cost-sensitive beef finishing operations across South Asia and Sub-Saharan Africa.
The European Food Safety Authority (EFSA) evaluates novel feed additives under Regulation (EC) No 1831/2003, while the FDA's Center for Veterinary Medicine governs food animal feed ingredients in the United States. China's Ministry of Agriculture and Rural Affairs (MARA) mandates registration and safety documentation for imported feed additives, creating compliance barriers for non-domestic suppliers. Brazil's Ministry of Agriculture, Livestock and Food Supply (MAPA) enforces additive labeling and maximum inclusion rates that diverge from OECD guidelines. Stakeholders must monitor divergent national residue limits and approval timelines when allocating R&D portfolios across regulatory jurisdictions.
Market Dynamics
EU Green Deal methane reduction mandates are compressing formulation timelines across European dairy supply chains while forcing additive suppliers to revalidate efficacy claims under stricter EFSA scrutiny. This regulatory pressure is cascading into procurement specifications for export-oriented herds in Oceania and North America.
Growth Catalysts
- 3-NOP compounds:These enteric fermentation inhibitors are displacing ionophores in lactating dairy rations as residue standards tighten across EU member states.
- Brazilian beef export modernization:Feedlot operators in Mato Grosso and Goiás are adopting precision mineral premixes to meet international carcass certification requirements.
- Antibiotic growth promoter phase-out:Probiotic and enzyme formulations are capturing volume formerly held by sub-therapeutic antibiotics under FDA Guidance for Industry #213.
Market Restraints
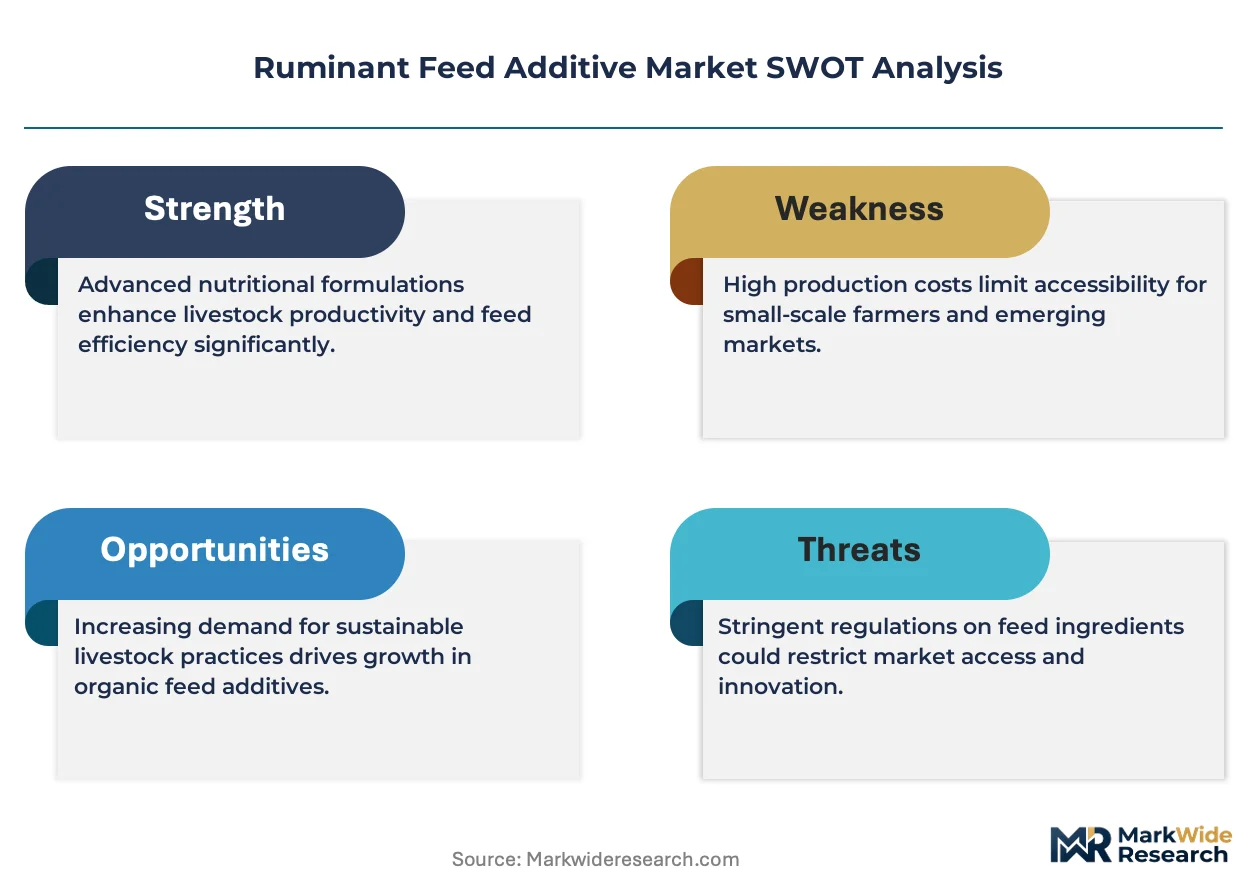
- Feed-grade vitamin price volatility:Synthetic vitamin A and E precursors fluctuate with petrochemical feedstock costs, compressing margins for standard premix suppliers.
- Chinese registration barriers:MARA's extended safety documentation requirements delay market entry by 18-24 months for novel microbial strains.
- Silage inoculant substitution:Homofermentative bacteria face displacement from chemical preservatives in cost-sensitive South Asian operations.
Strategic Opportunities
- Carbon credit monetization:Methane-reducing additives qualify for offset protocols in California's LCFS and voluntary registries, creating new revenue streams for dairy cooperatives.
- Precision delivery systems:Bolus and transponder-fed individual animal dosing is penetrating high-genetic-value herds in the Netherlands and Denmark.
- Organic certification premiums:Non-synthetic mineral and botanical additive demand is accelerating in Oceania's pasture-based systems targeting EU retail channels.
Industry Challenges
- Rumen microbiome modeling expertise:Formulation teams lack computational biology capacity to validate next-generation microbial interventions at commercial scale.
- Multi-jurisdiction residue harmonization:Divergent national MRLs for novel compounds force parallel safety studies, inflating development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ruminant Feed Additive Market |
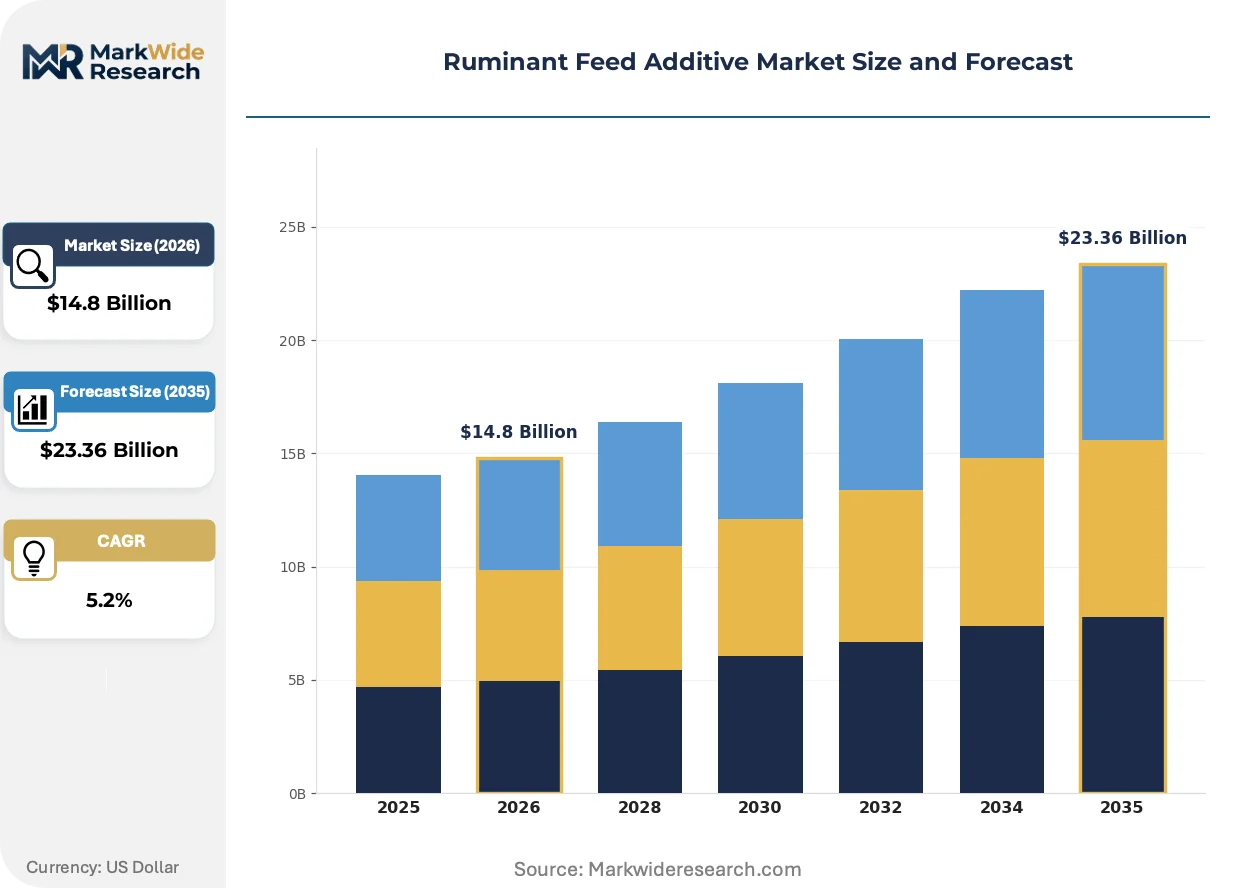
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Enzymes, Antibiotics, Vitamins Ingredient Source: Natural, Synthetic, Fermented, Feed By-Products Application: Dairy, Beef, Lamb, Poultry Form: Liquid, Powder, Granule, Tablet |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland, Alltech, Inc., DSM, Evonik Industries, Kemin Industries, BASF SE, International Flavors & Fragrances, Novus International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ruminant Feed Additive Market Trends and Innovations
Livestock nutrition is pivoting from bulk commodity premixes toward precision-formulated bioactives that modulate specific metabolic pathways. This shift is compressing traditional vitamin-mineral portfolios while opening specialized efficacy segments.
Microencapsulated butyrate and tributyrin formulations are expanding into transition dairy cow management, where producers seek alternatives to propylene glycol for ketosis prevention. Large integrated dairies in Wisconsin and the Netherlands are piloting these compounds during the 21-day pre-fresh window. The technology is expanding into heifer development programs as growth-performance claims receive independent validation.
EFSA's 2023 updated guidance on environmental risk assessment for feed additives now requires extended fate studies for compounds excreted in manure. Additive suppliers must demonstrate no adverse effects on soil microbiota or aquatic ecosystems. Dairy nutritionists in Germany and France are reformulating around copper and zinc limits that now fall below previous national standards.
Consolidated dairy cooperatives are unbundling additive procurement from compound feed contracts, establishing direct relationships with specialty ingredient suppliers. This disintermediation bypasses traditional feed mill markups but transfers formulation liability to on-farm nutrition teams. The pattern is most pronounced in 500-plus cow operations across the US Upper Midwest and Victoria, Australia.
Ruminant Feed Additive Market Segmentation
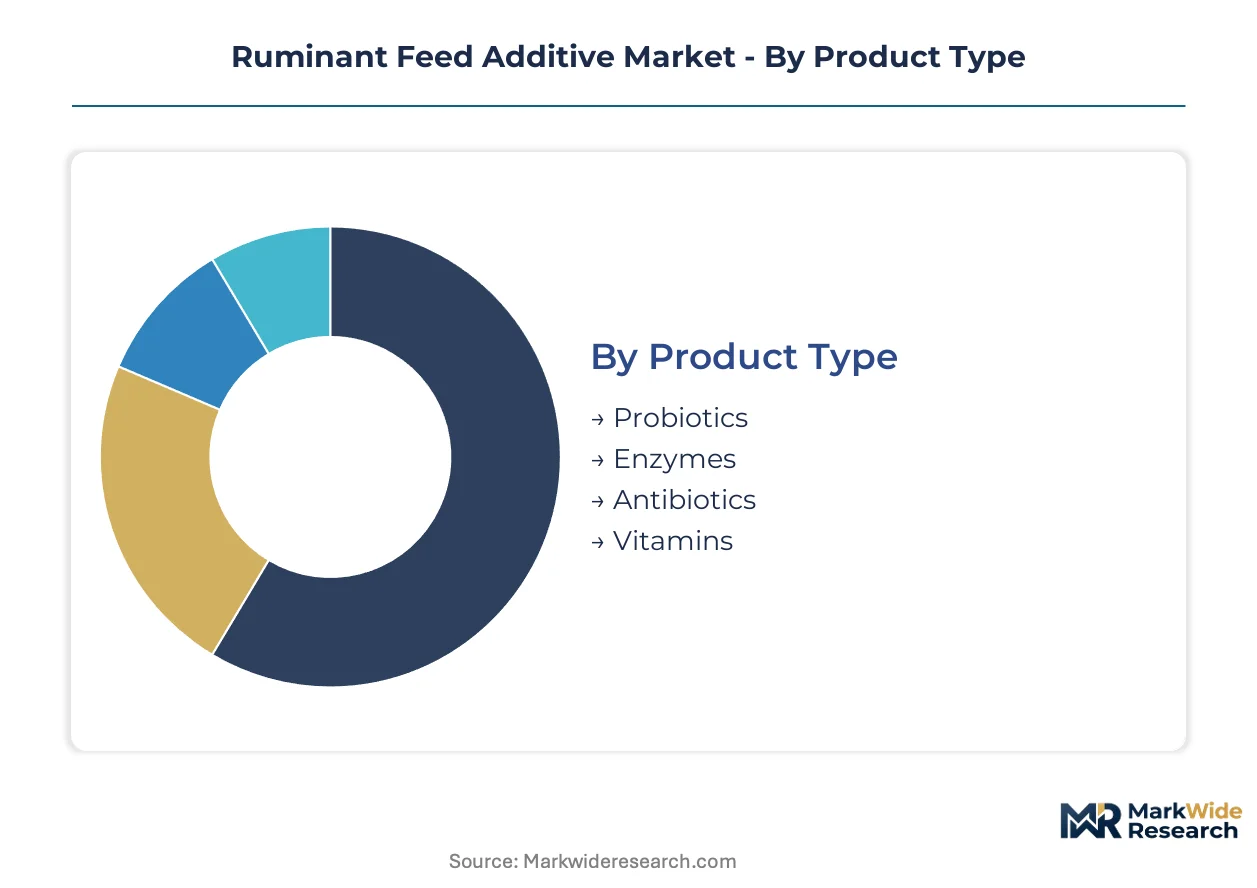
Ruminant feed additive segmentation reveals divergent margin structures across functional categories. Product type and ingredient source classifications determine formulation complexity, regulatory pathway length, and end-use pricing power.
Product Type:
Volume leadership sits with commodity-grade nutritional additives, while premium capture concentrates in fermentation-modulating bioactives.
- Probiotics:Live microbial cultures including Lactobacillus and Bacillus strains colonize the rumen epithelium to stabilize pH and outcompete pathogenic bacteria. Demand concentrates in transition dairy cow management across Wisconsin and the Netherlands as producers seek alternatives to antibiotic-dependent protocols. Probiotic formulations command premium pricing where residue-free certification opens EU retail channel access.
- Enzymes:Cellulase, xylanase, and amylase preparations break down structural carbohydrates and starch fractions that rumen microbiota cannot efficiently process. Beef feedlot operators in Brazil's Mato Grosso state deploy these additives to improve feed conversion ratios on high-fiber roughage diets. Enzyme suppliers compete on thermostability across pelleting temperature variations.
- Antibiotics:Ionophores and polypeptide growth promoters face phased withdrawal under FDA Guidance for Industry #213 and parallel EU restrictions.
- Vitamins:Synthetic A, D, and E premixes remain volume staples in cost-sensitive South Asian and Sub-Saharan operations.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Probiotics.
Ingredient Source:
Certification premiums are restructuring procurement specifications across export-oriented supply chains.
- Natural:Botanical extracts, marine-derived compounds, and non-synthetic mineral complexes qualify for organic and non-GMO certification protocols. Oceania pasture-based dairies targeting EU retail channels absorb price premiums for additive systems that maintain organic integrity across the full ration. Natural source additives face supply constraints from weather-dependent raw material harvests.
- Synthetic:Chemically synthesized vitamins, amino acids, and mineral salts dominate volume in price-sensitive beef finishing and smallholder dairy contexts. Synthetic production achieves batch-to-batch consistency that natural extraction cannot replicate, supporting inclusion rate precision in automated feed mill operations. Petrochemical feedstock cost volatility compresses margins for standard premix suppliers.
- Fermented:Microbial biomass cultivated on defined substrates yields concentrated protein and bioactive metabolite preparations.
- Feed By-Products:Distillers grains, oilseed meals, and processing residues provide carriers and partial nutrient contributions in integrated operations.
Mature deployment sits with Synthetic. Newer deployment is concentrated in Natural.
Application:
Species-specific digestive physiology dictates formulation requirements and dosing protocols.
- Dairy:Lactating herd nutrition demands precision additives that modulate energy partitioning between milk synthesis and body condition. Methane-inhibiting compounds including 3-NOP derivatives penetrate this segment fastest under EU Green Deal compliance pressure. Dairy cooperatives in Denmark and the Netherlands pilot individual animal dosing systems for high-genetic-value cows.
- Beef:Feedlot finishing programs prioritize growth promotion and carcass quality optimization within compressed timeframes. Brazilian operators modernizing for export certification drive demand for precision mineral premixes that meet international residue standards. Beef applications tolerate higher inclusion rates of synthetic additives than dairy due to shorter production cycles.
- Lamb:Seasonal breeding patterns and smaller flock sizes create fragmented demand with limited formulation standardization.
- Poultry:Monogastric digestive systems require entirely different additive categories than ruminant-focused products.
Mature deployment sits with Beef. Newer deployment is concentrated in Dairy.
Form:
Physical presentation determines handling characteristics, stability windows, and on-farm labor requirements.
- Powder:Fine-particle premixes integrate uniformly into total mixed rations and compound feeds through standard mill equipment. Powder forms dominate bulk commodity additive distribution where automated inclusion systems operate at large feed mills. Moisture sensitivity limits shelf life in tropical storage conditions without climate-controlled warehousing.
- Liquid:Aqueous suspensions and emulsions enable post-pelleting application and drinking water medication pathways. Liquid delivery systems penetrate integrated operations with dedicated mixing and pumping infrastructure for direct-to-trough administration. Tank cleaning protocols between batches add operational complexity that smaller operations avoid.
- Granule:Agglomerated particles reduce dust generation and improve flowability in mechanical handling systems.
- Tablet:Compressed bolus formulations enable individual animal dosing in high-value breeding stock and pharmaceutical-grade interventions.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of ruminant feed additives concentrates in industrial clusters across Germany, the United States, and the Netherlands, while consumption gravity shifts toward Brazil and India as these countries expand commercial herd sizes and modernize nutrition protocols.
United States
Dairy cooperatives in Wisconsin and California drive demand for methane-inhibiting formulations as processors face Scope 3 emissions reporting pressure from retail buyers. The FDA's Center for Veterinary Medicine enforces residue standards under Guidance for Industry #213, accelerating ionophore displacement. Large integrated operations in the Upper Midwest pilot precision bolus delivery systems for transition cow management.
Brazil
Feedlot operators in Mato Grosso and Goiás states adopt precision mineral premixes to meet international carcass certification requirements for export markets. MAPA enforces additive labeling and maximum inclusion rates that diverge from OECD guidelines, creating compliance complexity for imported formulations. Modernization investments concentrate in the Center-West region where beef export capacity expansion reshapes procurement specifications.
Germany
Dairy nutritionists in Lower Saxony and Bavaria reformulate around copper and zinc limits under EFSA's 2023 updated environmental risk assessment guidance. The EU Green Deal's methane reduction targets compress formulation timelines while forcing revalidation of efficacy claims. Precision delivery system pilots operate in high-genetic-value herds across the Netherlands border region.
China
Commercial dairy herds in Hebei and Shandong provinces drive volume demand for probiotic formulations as antibiotic growth promoters phase out under MARA enforcement. The Ministry of Agriculture and Rural Affairs mandates registration and safety documentation for imported feed additives, delaying market entry by 18-24 months for novel microbial strains. Domestic compound feed mills in the Yangtze River Delta integrate local fermentation-derived additives.
Netherlands
Pasture-based dairies targeting EU retail channels absorb price premiums for organic-certified additive systems. EFSA scrutiny under Regulation (EC) No 1831/2003 shapes product development pipelines for suppliers serving the Benelux cluster. Individual animal dosing technology penetrates high-genetic-value herds in Friesland and Gelderland provinces.
Ruminant Feed Additive Market Competitive Landscape
The competitive structure tilts toward integrated nutrition conglomerates with captive supply chains and regional compounding infrastructure. Three archetypes dominate: diversified agricultural processors with backward integration into ingredient sourcing, specialty chemical manufacturers with synthetic vitamin stability expertise, and microbial technology specialists with proprietary strain libraries. Competitive moves concentrate on portfolio diversification into methane-inhibiting compounds and geographic expansion through local registration partnerships.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland exemplify supply chain control through regional pre-mixing facilities. DSM anchors the specialty chemical segment with proprietary fermentation-derived compounds. Among microbial technology specialists, Alltech, Inc. occupies a position emphasizing live culture formulations for residue-free certification markets.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland |
| Alltech, Inc. |
| DSM |
| Evonik Industries |
| Kemin Industries |
| BASF SE |
| International Flavors & Fragrances |
| Novus International |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal methane reduction mandates gate qualified supply and premium-tier pricing access, restricting high-value formulation partnerships to additive suppliers with validated 3-NOP efficacy data and EFSA-compliant environmental risk documentation. Dairy cooperatives in Denmark and the Netherlands absorb price premiums for certified methane-inhibiting compounds that unlock carbon credit monetization pathways under California's LCFS and voluntary registries.
Pricing Analysis
Yield-linked pricing anchors value capture for fermentation-modulating bioactives, with 3-NOP compounds commanding premiums tied to measured enteric methane reduction in lactating herds. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified natural additives from synthetic vitamin premixes and commodity mineral blends. Cost compression in standard premix tiers is intensifying because petrochemical feedstock volatility squeezes synthetic vitamin A and E precursor margins. Smallholder beef operations across South Asia exhibit highest price sensitivity, while export-oriented Oceania dairies targeting EU retail channels show lowest.
Supply Chain Analysis
Unused additive recovery and reformulation flows remain underdeveloped, though precision delivery system pilots in the Netherlands generate bolus return data for dosage optimization. Production gravity centers on Germany, the United States, and the Netherlands for fermentation-derived compounds and synthetic vitamin stability expertise, while Brazil and India concentrate growth in consumption. Raw material dependencies rest on petrochemical feedstocks for synthetic vitamins, defined microbial substrates for probiotic cultivation, and weather-dependent botanical harvests for natural extracts. Single-source vulnerability in Chinese-registered microbial strains creates supply risk for probiotic formulations. Distribution runs through regional compounding facilities operated by integrated nutrition conglomerates, with direct procurement bypassing traditional feed mill markups in large dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ruminant feed additive sector sits in a technology-transition phase, with methane-inhibiting 3-NOP compounds displacing legacy ionophore growth promoters under tightening residue standards across EU member states and FDA-enforced protocols.
For Market Incumbents: Anticipate accelerated ionophore displacement by securing proprietary 3-NOP strain libraries and EFSA pre-submission pathways before 2025 regulatory deadlines compress formulation timelines. Backward integration into microbial fermentation capacity in the Netherlands and Germany defends margin position against specialty chemical competitors lacking captive biomanufacturing infrastructure. Certification investment in organic and non-GMO protocols locks in Oceania dairy cooperative procurement specifications. For New Entrants and Emerging Players: Mid-scale Brazilian feedlot operators modernizing for export certification represent the most penetrable buyer archetype, with precision mineral premix demand outpacing established supplier capacity in Mato Grosso and Goiás states. White-space concentration in individual animal dosing technology for high-genetic-value herds offers entry through precision bolus partnerships with Dutch and Danish dairy cooperatives. Direct technical service relationships with on-farm nutrition teams bypass entrenched feed mill distribution. For Investors and Strategic Acquirers: EFSA's 2023 updated environmental risk assessment guidance is the leading indicator that copper and zinc limit compliance will drive consolidation among mineral premix suppliers lacking reformulation expertise. Long-term viability favors microbial technology specialists with validated strain libraries and multi-jurisdiction registration capabilities over commodity vitamin blenders facing petrochemical margin compression. Monitor MARA registration approval timelines for novel microbial strains as early signals of competitive positioning shifts in China's commercial dairy herd expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Library Acquisition | DSM and Alltech anchor positions through exclusive 3-NOP and live culture collections that block competitor formulation access. |
| EFSA Pre-Submission Pathway Investment | Early engagement with updated environmental risk guidance accelerates approval timelines for manure fate studies. |
| Regional Compounding Facility Expansion | Cargill's Wisconsin and Netherlands sites enable just-in-time precision premix delivery to large integrated dairies. |
| Carbon Credit Protocol Registration | California LCFS and voluntary registry qualification opens new revenue streams for methane-reducing additive suppliers. |
| Direct Procurement Channel Development | Disintermediation from compound feed contracts transfers formulation liability but captures feed mill markup value. |
Research Methodology
Multi-period observation of EFSA registration timelines, MARA approval delays, and carbon credit protocol adoption rates anchored the trend analysis, supplemented by interviews with dairy nutritionists, feed mill procurement managers, probiotic R&D directors, and compound feed regulatory affairs leads. Primary fieldwork across Wisconsin, the Netherlands, and São Paulo state triangulated against secondary validation from FDA Guidance for Industry #213 implementation reports, EU Green Deal methane target documentation, customs trade data for vitamin precursor imports, and SEC filings from listed nutrition conglomerates. Bottom-up segmentation modeling integrated with top-down macroeconomic drivers produced convergent estimates.
Segment-weighting across product type, ingredient source, application species, and physical form dimensions determined value allocation within the analytical framework. CAGRs derived from logistic adoption curves for methane-inhibiting compounds and linear extrapolation for mature vitamin premix categories across the projection horizon. Industry-specific inputs included enteric methane measurement validation studies, silage inoculant substitution elasticities in South Asian markets, and precision delivery system penetration rates in high-genetic-value herds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement stringency, Chinese MARA registration pathway reforms, and petrochemical feedstock cost trajectories. Practitioners should monitor EFSA environmental risk assessment precedent decisions, California LCFS protocol amendments, and Brazilian MAPA labeling harmonization proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tackifier Market
Additives
Asia-Pacific Water Enhancer Market
Additives
United States Betaine Market
Additives
China Feed Additives Market
Additives
Calcium Tartrate Market
Additives
Asia Pacific Plastic Additives Market
Additives
Glacial Acetic Acid Market
Additives
Octane Improver Fuel Additives Market
Additives
Extruded Inclusions Market
Additives
Global Pearlizing Agent Market
Additives
Global Mold Release Agents Market
Additives
Cosmetic Grade Color Additives Market
Additives
Anti-Foaming Agent Market
Additives
Global Matting Agents Market
Additives
Refining Additives Market
Additives
Lactic Acid Ester Market