
 Alpha Hydroxy Acid Market | 2026-2036
Alpha Hydroxy Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Hydroxy Acid Market Analysis
Software-defined formulation customization is broadening what ingredient suppliers sell beyond bulk acids to calibrated pH-buffered systems. BASF SE leverages its integrated care chemicals portfolio to anchor supply relationships with multinational skincare brands. Evonik Industries AG differentiates through biotechnology-derived lactic acid with tighter chirality control. Croda International Plc specializes in mildness-optimized delivery systems that extend acid efficacy without irritation penalties.
Alpha hydroxy acids comprise a class of organic carboxylic acids where a hydroxyl group occupies the alpha position relative to the carboxyl carbon, with glycolic acid representing the smallest member at 76 daltons and highest epidermal penetration rate. These compounds function primarily as keratolytic agents that disrupt corneocyte cohesion by chelating calcium ions in desmosomal junctions, enabling commercial applications in chemical exfoliation and cell turnover acceleration. Glycolic acid leads product type demand due to its established clinical validation and versatile concentration ranging from consumer-grade 8% to professional 70% peels, while mandelic acid represents the fastest-growing variant owing to its larger molecular structure reducing irritation incidence in sensitive-skin segments. Application demand clusters in skin care where margin pools concentrate in professional-channel peels, though anti-aging serums for individual consumers expand through direct-to-dermatologist distribution models.
The U.S. FDA governs alpha hydroxy acid concentration thresholds in cosmetic versus drug classifications, while the EU's REACH regulation mandates full supply-chain substance registration and safety dossier submission. ISO 16128 natural origin indexing creates compliance complexity for petrochemical-derived glycolic acid versus fermentation-sourced lactic acid alternatives. Stakeholders must monitor evolving classification boundaries between cosmetic and pharmaceutical claims as regulators scrutinize anti-aging efficacy assertions.
Market Dynamics
Formulation chemistry is pivoting toward pH-calibrated delivery systems as brands compete on irritation-free efficacy claims. The EU's tightening REACH substance dossier requirements force suppliers to revalidate legacy glycolic acid sourcing.
Growth Catalysts
- Professional peel protocols:Dermatology clinics in the United States expand high-concentration acid services as medical-aesthetic convergence accelerates patient throughput.
- REACH registration completion:Full supply-chain substance transparency under EU chemical law enables market access for compliant fermentation-derived lactic acid variants.
- Biotechnology process maturation:Chirality-controlled biosynthesis reduces manufacturing impurity profiles, unlocking pharmaceutical-grade acid specifications.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived glycolic acid faces margin compression when naphtha prices spike, squeezing non-integrated formulators.
- Concentration threshold enforcement:The US FDA's cosmetic-drug classification boundary at 10% free acid creates formulation ceiling constraints for consumer retail channels.
- Natural origin certification complexity:ISO 16128 indexing disadvantages synthetic glycolic acid against fermentation-sourced alternatives in clean-beauty positioning.
Strategic Opportunities
- Sensitive-skin segmentation:Mandelic acid's larger molecular structure enables expansion into rosacea-prone and post-procedure demographics previously excluded from acid therapy.
- Direct-to-dermatologist distribution:Bypassing traditional retail through clinician-dispensed protocols captures margin pools in medical-aesthetic convergence.
- Dual carbon policy alignment:China's SAMR green manufacturing incentives favor biotechnology-derived acid production with verified carbon intensity reductions.
Industry Challenges
- Formulation stability expertise:pH buffering and oxidation control require specialized cosmetic chemists in short supply across mid-tier contract manufacturers.
- Clinical substantiation timelines:Anti-aging efficacy claims demand IRB-approved studies extending 12-18 months before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Hydroxy Acid Market |
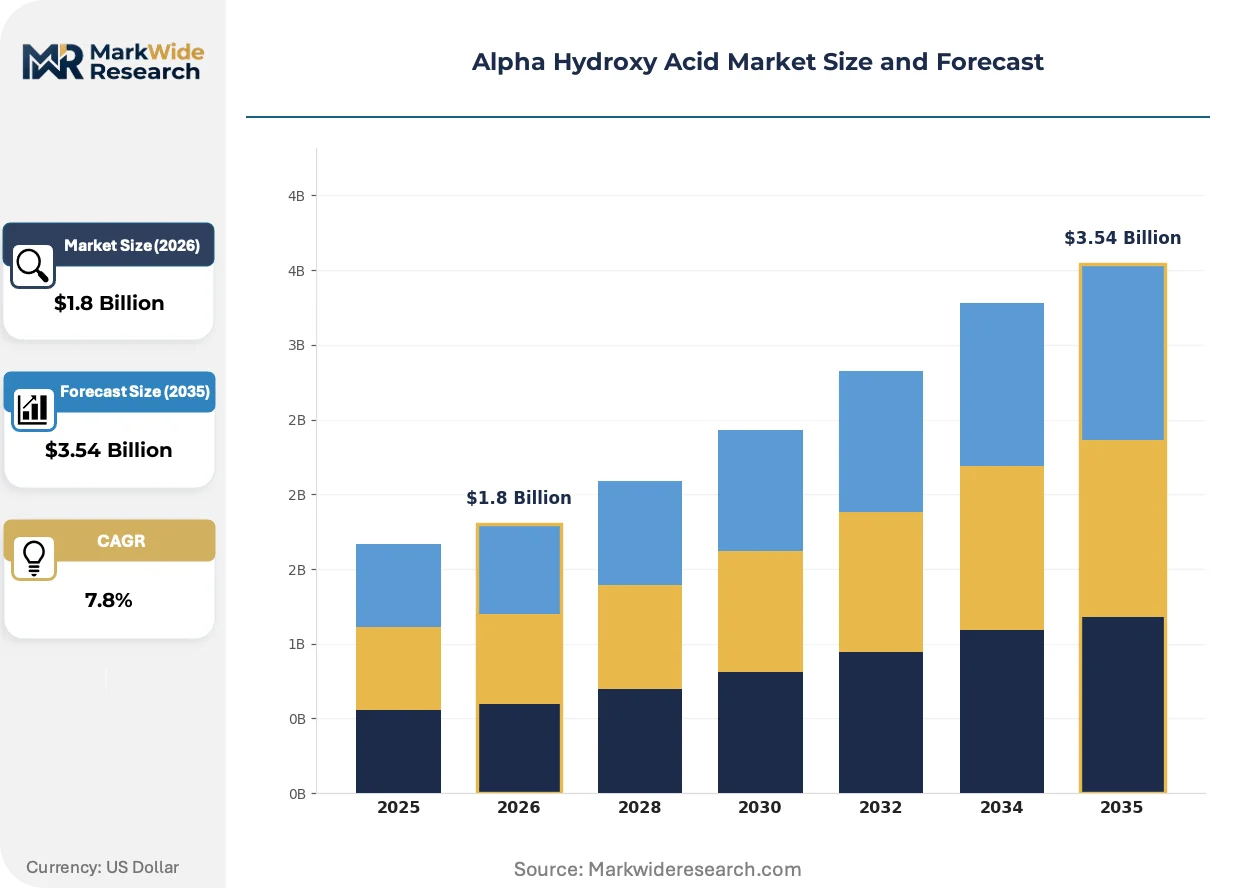
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycolic Acid, Lactic Acid, Citric Acid, Mandelic Acid Application: Skin Care, Hair Care, Anti-Aging, Exfoliation End User: Individual Consumers, Dermatologists, Estheticians, Spas Distribution Channel: Online Retail, Specialty Stores, Drugstores, Supermarkets |
| Companies Covered | BASF SE, The Dow Chemical Company, Evonik Industries AG, Croda International Plc, Cargill, Corbion, Parchem, Ava Chemicals, Jungbunzlauer Suisse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Hydroxy Acid Market Emerging Trajectories
Encapsulation technology is redefining how acids reach target skin layers without surface irritation. Formulators now compete on delivery precision rather than raw concentration metrics.
Microsphere encapsulation systems are absorbing acid molecules into biodegradable polymer shells that rupture at specific pH thresholds. Premium skincare brands in South Korea deploy these systems for overnight renewal products. This architecture is absorbing market share from traditional free-acid serums by eliminating the neutralization step consumers dislike.
The EU's F-Gas Regulation phase-down is pressuring solvent-based acid purification processes toward aqueous alternatives. Manufacturers serving European cosmetic brands must retrofit extraction equipment by 2027. Professional peel suppliers with German manufacturing footprints face the steepest compliance capital requirements.
Subscription-based replenishment programs are replacing episodic retail purchases for at-home acid treatments. Direct-to-consumer brands bypass Sephora and Ulta shelf negotiations entirely. This channel migration concentrates most visibly in millennial and Gen-Z demographics across coastal United States metropolitan markets.
Alpha Hydroxy Acid Market Segmentation
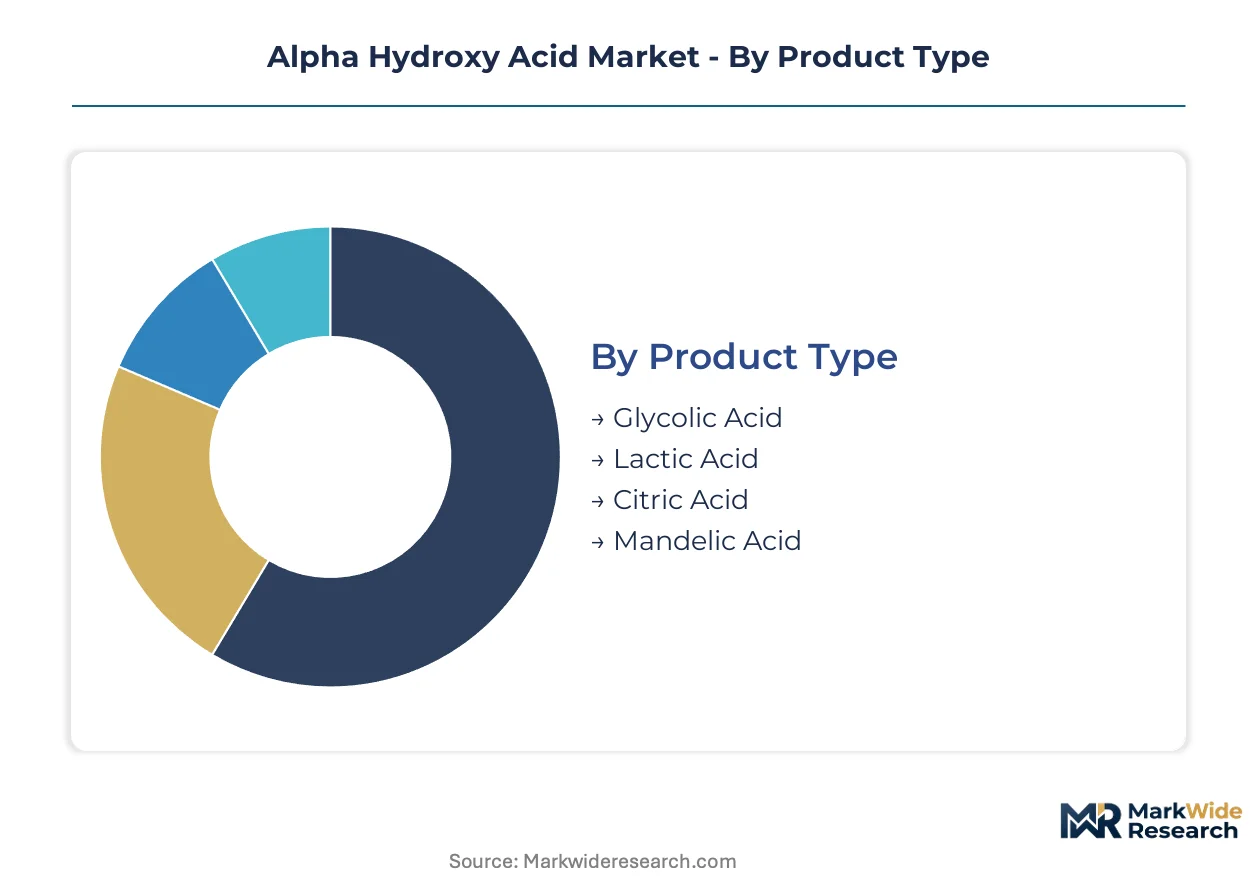
Alpha hydroxy acid suppliers calibrate formulation specifications and channel strategies against distinct performance requirements across molecular variants and professional versus consumer use cases. Segmentation discipline separates commodity glycolic acid volume plays from premium-positioned mandelic acid specialty applications.
Product Type:
Standalone acid molecules dominate commodity supply contracts, while buffered systems and chirality-controlled variants embed into finished formulation partnerships with multinational skincare brands.
- Glycolic Acid:The smallest AHA at 76 daltons penetrates epidermis fastest, enabling concentration gradients from consumer-grade 8% to professional 70% peels. Demand concentrates in United States dermatology clinics where medical-aesthetic convergence accelerates high-concentration service throughput.
- Lactic Acid:Fermentation-derived variants with tighter chirality control from biotechnology processes satisfy ISO 16128 natural origin indexing. Procurement runs through EU cosmetic brands seeking REACH-compliant supply chain transparency for clean-beauty positioning.
- Citric Acid:Food-grade crossover sourcing from industrial fermentation creates cost advantages in mass-market exfoliation products.
- Mandelic Acid:Larger 152-dalton structure reduces irritation incidence in rosacea-prone demographics.
Volume placements concentrate in Glycolic Acid; the faster expansion belongs to Mandelic Acid.
Application:
Professional-channel peels command margin premiums against retail serums, while hair care applications remain underpenetrated relative to skin-directed formulations.
- Skin Care:Chemical exfoliation protocols disrupt corneocyte cohesion through calcium chelation at desmosomal junctions. Revenue pools concentrate in professional peels dispensed through United States dermatologist offices, though direct-to-consumer anti-aging serums expand through subscription replenishment models.
- Anti-Aging:Efficacy claims trigger FDA cosmetic-drug classification scrutiny at 10% free acid threshold, forcing formulation ceiling constraints. Clinical substantiation timelines extend 12-18 months for IRB-approved studies before regulatory submission.
- Exfoliation:Encapsulation technology in South Korean overnight products eliminates consumer-disliked neutralization steps.
- Hair Care:Scalp renewal applications lag skin care penetration despite similar keratolytic mechanisms.
Margin capture concentrates in Anti-Aging; the steepest volume climb tracks Exfoliation.
End User:
Dispensing authority determines concentration access and regulatory pathway, with clinician-gated protocols bypassing retail channel constraints.
- Dermatologists:Medical licensure unlocks high-concentration acid services above FDA cosmetic thresholds. United States clinic networks expand patient throughput through standardized peel protocols.
- Individual Consumers:Self-directed application limits concentration exposure to 10% free acid under FDA classification boundaries. Coastal United States metropolitan millennials and Gen-Z demographics drive subscription-based replenishment migration away from Sephora and Ulta shelf negotiations.
- Estheticians:State-licensed practice scope varies across United States jurisdictions.
- Spas:Wellness positioning favors milder mandelic acid protocols for post-procedure recovery positioning.
Prescription authority concentrates in Dermatologists; the fastest share gain belongs to Individual Consumers.
Distribution Channel:
Channel selection dictates pricing architecture and formulation concentration ceiling through regulatory exposure and consumer education requirements.
- Online Retail:Direct-to-consumer brands bypass traditional retail margin extraction entirely. Subscription programs concentrate in millennial and Gen-Z demographics across coastal United States metropolitan markets.
- Specialty Stores:Sephora and Ulta shelf negotiations require clean-beauty certification compliance including ISO 16128 natural origin indexing.
- Drugstores:Mass-market positioning favors glycolic acid at concentration floors below FDA drug classification thresholds.
- Supermarkets:Food-retail adjacency enables citric acid crossover products with food-grade sourcing economics.
Transaction velocity concentrates in Online Retail; the tightest margin compression hits Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of alpha hydroxy acids clusters in Germany and China where integrated chemical complexes achieve feedstock efficiencies, while consumption concentrates in the United States where dermatology clinic networks drive professional-grade demand.
United States
Dermatology clinics in California and New York Metro expand high-concentration peel protocols as medical-aesthetic convergence accelerates patient throughput. The FDA's cosmetic-drug classification boundary at 10% free acid concentration shapes formulation strategies for retail versus professional channels. Houston and Chicago manufacturing clusters supply pH-buffered delivery systems to national skincare brands.
Germany
REACH substance dossier requirements under ECHA oversight force suppliers to revalidate legacy glycolic acid sourcing and fermentation-derived alternatives. The F-Gas Regulation phase-down pressures solvent-based purification processes toward aqueous extraction by 2027. BASF SE's Ludwigshafen complex anchors European supply relationships with multinational cosmetic formulators.
China
SAMR green manufacturing incentives favor biotechnology-derived lactic acid production with verified carbon intensity reductions under dual carbon policy frameworks. Yangtze River Delta chemical parks concentrate fermentation capacity expansion. Shanghai and Hangzhou formulation houses serve domestic skincare brands targeting clean-beauty positioning with ISO 16128 natural origin indexing.
South Korea
Seoul Capital Area beauty brands deploy microsphere encapsulation systems for overnight renewal products, absorbing market share from traditional free-acid serums. MFDS cosmetic safety assessments govern acid concentration thresholds in consumer applications. Busan-Ulsan industrial corridors manufacture biodegradable polymer shells for pH-triggered delivery architectures.
India
Maharashtra and Gujarat fermentation facilities scale lactic acid output for export to EU cosmetic brands seeking REACH-compliant supply chain transparency. CDSCO oversight of cosmetic-drug boundaries influences domestic formulation ceilings. Mumbai and Ahmedabad contract manufacturers develop mildness-optimized delivery systems for sensitive-skin market expansion.
Alpha Hydroxy Acid Market Vendor Landscape
Top-tier vendors anchor integrated care chemicals portfolios, while specialized biotech fermentation houses occupy differentiated positions. The vendor base stratifies across multinational chemical conglomerates, dedicated cosmetic ingredient suppliers, and regional fermentation specialists. Three archetypes dominate: pH-buffered system integrators, chirality-controlled biosynthesis specialists, and natural-origin certification optimizers. Capacity expansion in fermentation-derived lactic acid and strategic partnerships for encapsulation technology represent the dominant competitive moves.
Among European chemical conglomerates, BASF SE, Evonik Industries AG, and Croda International Plc exemplify distinct strategic positioning within the tiered competitive structure. BASF SE represents the integrated portfolio archetype spanning feedstock through finished formulation partnerships. Evonik Industries AG occupies the biotechnology specialization position with chirality-controlled production capabilities. Croda International Plc anchors the mildness-optimized delivery systems segment where irritation-free efficacy claims command premium positioning.
| Leading Market Players |
|---|
| BASF SE |
| The Dow Chemical Company |
| Evonik Industries AG |
| Croda International Plc |
| Cargill |
| Corbion |
| Parchem |
| Ava Chemicals |
| Jungbunzlauer Suisse AG |
| Others |
Supply Flow & Price Mechanics
Captive fermentation capacity in Yangtze River Delta chemical parks anchors both supply security and pricing power for biotechnology-derived lactic acid suppliers serving EU cosmetic brands. BASF SE's Ludwigshafen complex demonstrates how backward integration into petrochemical feedstocks insulates glycolic acid producers from naphtha volatility while enabling premium positioning for pH-buffered delivery systems.
Pricing Analysis
Cost-down pressure on synthetic glycolic acid accelerates because ISO 16128 natural origin indexing disadvantages petrochemical-derived variants against fermentation-sourced alternatives. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade acid specifications separates premium chirality-controlled biosynthesis from standard commodity output. Price differentiation rests on REACH dossier completeness and carbon intensity verification under China's dual carbon policy. Individual consumers through subscription channels exhibit lowest price sensitivity; mass-market drugstore buyers face tightest margin compression.
Supply Chain Analysis
REACH registration completion gates European market access for fermentation-derived lactic acid variants from India and China. Raw material dependencies center on corn-derived dextrose for fermentation, naphtha feedstocks for petrochemical synthesis, and specialized polymer resins for microsphere encapsulation. Single-source vulnerability concentrates in German solvent-based purification equipment facing F-Gas Regulation retrofit deadlines. Distribution runs through direct-to-dermatologist protocols capturing margin pools above retail channel ceilings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alpha Hydroxy Acid Market is consolidating as REACH dossier requirements and F-Gas Regulation compliance costs force sub-scale fermentation houses toward acquisition or exit. Regulatory capital intensity favors integrated chemical conglomerates over standalone acid suppliers lacking captive biotechnology capacity.
For Market Incumbents: Acquire encapsulation technology specialists to secure pH-triggered delivery architectures before South Korean beauty brands dominate overnight renewal positioning. BASF SE and Evonik Industries AG should expand chirality-controlled fermentation capacity in Yangtze River Delta parks to capture SAMR green manufacturing incentives. Defensive consolidation must preempt emerging biotech fermentation houses from achieving pharmaceutical-grade acid specifications through CRISPR-optimized strain development. For New Entrants and Emerging Players: REACH registration completion in Germany opens a window for Indian lactic acid exporters with verified supply chain transparency to penetrate EU cosmetic brand procurement. Hair care scalp renewal applications remain underpenetrated relative to skin-directed formulations and offer white-space expansion without confronting entrenched dermatology clinic networks. A direct-to-dermatologist distribution partnership bypasses Sephora and Ulta shelf negotiation barriers entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated care chemicals conglomerates seeking biotechnology fermentation capabilities. Long-term viability requires carbon intensity verification under tightening EU and Chinese environmental frameworks. Watch for SAMR enforcement of dual carbon policy as the inflection signal determining which fermentation houses secure domestic Chinese brand relationships versus export-only positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive biotechnology production secures ISO 16128 natural origin indexing for EU clean-beauty positioning. |
| Encapsulation Technology Acquisition | Microsphere delivery systems from Busan-Ulsan corridors eliminate consumer-disliked neutralization steps. |
| REACH Dossier Completion | Full supply chain substance transparency under ECHA oversight unlocks German cosmetic brand procurement. |
| Direct-to-Dermatologist Channel Development | Clinician-dispensed protocols capture margin pools above FDA 10% cosmetic threshold constraints. |
| Green Manufacturing Certification | Verified carbon intensity reductions under China's dual carbon policy attract SAMR incentive alignment. |
Methodological Framework
Document review covered customs and trade data, SEC 10-K filings, and ECHA REACH registration databases, complemented by interviews with cosmetic formulation chemists, dermatology clinic procurement managers, and biotechnology fermentation plant directors. Primary fieldwork validated secondary findings through structured discussions with supply chain executives at multinational skincare brands and technical R&D directors at German chemical complexes. Bottom-up acid volume estimates triangulated against top-down market sizing from production capacity announcements.
Segment-level outputs across molecular variant, application use case, and dispensing authority dimensions were generated through the analytical framework. CAGRs were derived from regression analysis against dermatology clinic expansion rates and subscription program adoption curves. Chirality control technology maturation and encapsulation system penetration served as industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for solvent-free aqueous purification would alter the outlook for German manufacturing competitiveness. Forecasts reflect assumptions regarding REACH enforcement consistency and SAMR dual carbon policy implementation pace. A model refresh is warranted upon material change in FDA cosmetic-drug classification boundary interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
Hydrogen Cyanide Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Global Hydrofluoric Acid Market