
 Saudi Arabia Methanol Market | 2026-2036
Saudi Arabia Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Methanol Market Insights
Market Context with Strategic Players
Jubail Industrial City's petrochemical complex is repositioning Saudi Arabia as a methanol export hub with integrated feedstock advantages. Saudi Basic Industries Corporation leverages its scale across ammonia-to-methanol value chains. Sipchem anchors downstream derivative production at the same coastal location. Sahara International Petrochemical Company competes through its standalone methanol capacity serving Asian contract buyers.
Technical Definition and Structural Segments
Methanol is a light, volatile alcohol (CH₃OH) produced primarily via steam methane reforming of natural gas followed by catalytic synthesis, serving as a foundational building block for formaldehyde, acetic acid, and methyl tert-butyl ether production. The chemical feedstock segment dominates volume offtake as Saudi crackers consume methanol for olefin and derivative manufacturing. Fuel-grade methanol represents the fastest-expanding category amid marine and road transport decarbonization trials. Solvent applications occupy stable demand from paints and coatings formulators across the GCC.
Regulatory Frame and Forward-Looking Close
The SFDA oversees methanol handling safety in industrial and consumer-facing applications, while SASO enforces product quality specifications for domestic trade and export certification. These bodies shape market access by mandating purity thresholds and labeling protocols that filter out non-compliant imports. The Saudi Vision 2030 industrial localization targets are redirecting methanol derivative investments toward domestic manufacturing rather than raw material export. Stakeholders must monitor how carbon intensity benchmarks from the Saudi Green Initiative reshape feedstock sourcing decisions and plant retrofit requirements.
Market Dynamics
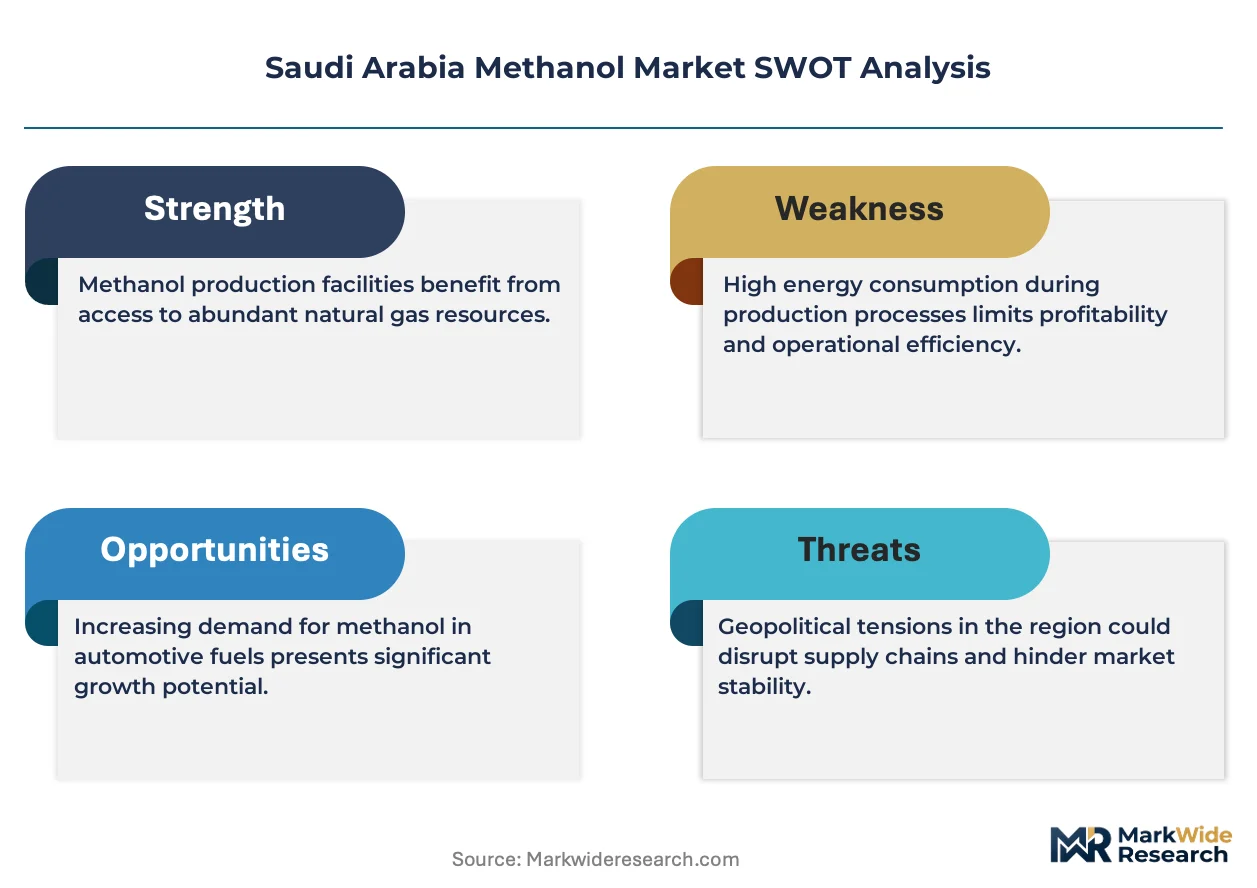
Jubail Industrial City's integrated petrochemical cluster is concentrating methanol production capacity and derivative offtake, creating a self-reinforcing supply hub that locks in feedstock cost advantages for producers serving both domestic formulators and Asian export markets.
Growth Catalysts
- Saudi Green Initiative carbon benchmarks:The national decarbonization framework is mandating lower-carbon intensity for industrial feedstocks, pulling methanol into fuel-blending trials and marine bunker fuel formulations.
- Formaldehyde derivative demand:Construction sector resins and wood panel binders consume rising methanol volumes as Saudi Vision 2030 infrastructure projects accelerate.
- Eastern Province industrial clustering:Proximity of crackers, ammonia plants, and methanol units within Jubail enables pipeline-linked feedstock sharing that compresses logistics costs.
Market Restraints
- Natural gas price volatility:Steam methane reforming feedstock costs fluctuate with domestic gas allocation policies, squeezing margin predictability for standalone producers.
- Chinese methanol self-sufficiency:Coal-to-methanol capacity expansion in Shanxi and Inner Mongolia is displacing Middle Eastern import volumes in Asian spot markets.
- SFDA handling protocols:Stringent safety documentation for methanol transport and storage adds compliance overhead for distributors serving scattered industrial zones.
Strategic Opportunities
- Marine fuel bunkering at King Fahd Industrial Port:IMO 2020 sulfur caps and EU carbon border adjustments are positioning Saudi methanol as a low-sulfur bunker fuel alternative for Red Sea shipping lanes.
- Methyl tert-butyl ether for Asian gasoline blending:Refinery upgrade delays in India and Southeast Asia are sustaining import demand for octane boosters manufactured from Saudi methanol.
- Carbon capture integration:CCUS retrofits at existing reforming units can generate certified low-carbon methanol streams commanding premiums under EU CBAM and Japanese fuel regulations.
Industry Challenges
- Specialized catalyst procurement:Copper-zinc-alumina synthesis catalyst replacement cycles depend on limited German and Japanese suppliers, extending turnaround timelines.
- SFDA-SASO dual compliance:Industrial chemical purity standards and export certification requirements operate on separate review tracks, delaying product release for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Methanol Market |
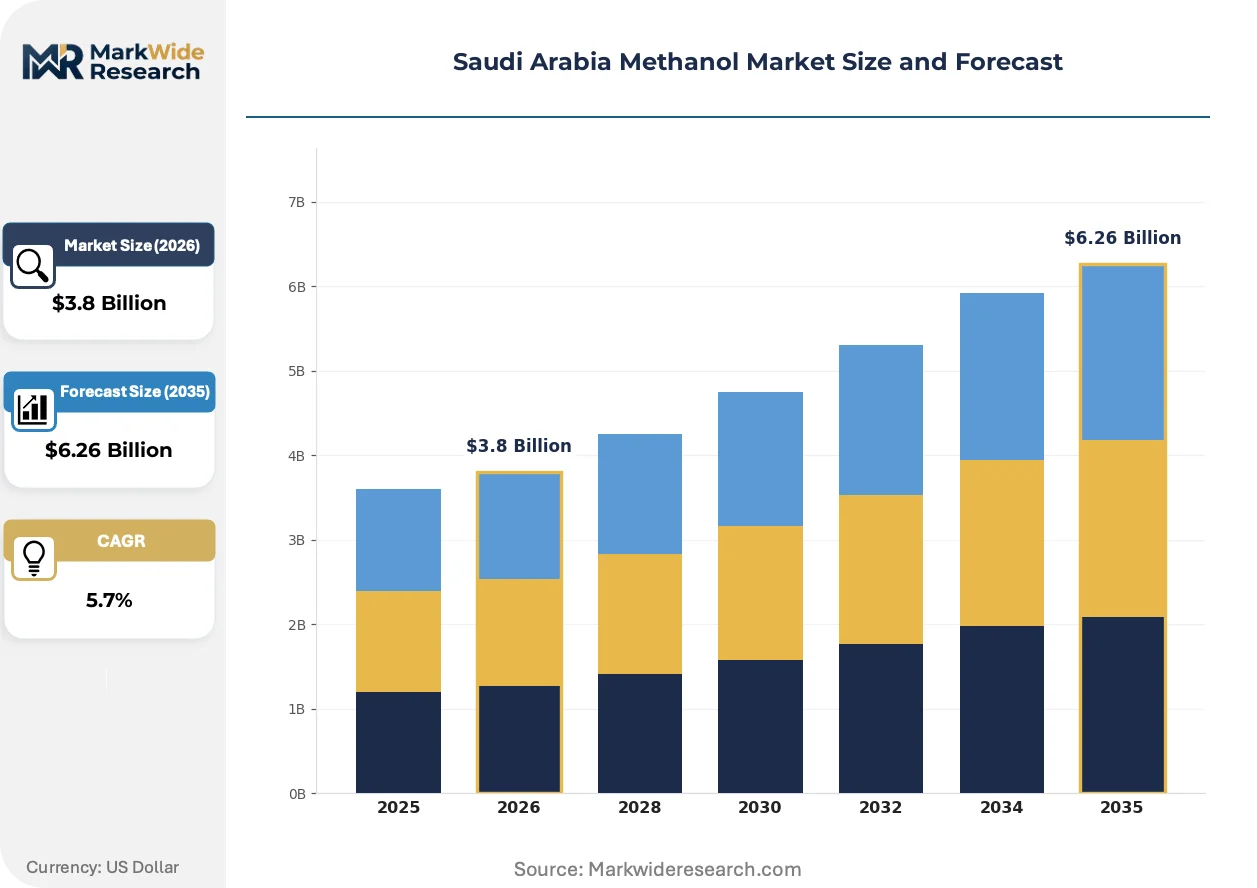
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel, Chemical Feedstock, Solvent, Raw Material Application: Plastics, Paints, Fertilizers, Automotive End User: Manufacturers, Refineries, Research Institutions, Distributors Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retailers |
| Companies Covered | Saudi Methanol Company, Methanol Chemicals Company, International Methanol Company, Sahara International Petrochemical Company, Saudi Basic Industries Corporation, Gulf Petrochemical Industries Company, Sipchem, Chemanol, AR-RAZI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Methanol Market Trends and Innovations
Electrification of syngas production and tightening carbon accounting standards are reshaping how Saudi methanol producers configure reforming assets and certify product streams for differentiated markets.
Small-scale modular reforming is electrifying distributed methanol production economics. These containerized units enable on-site fuel synthesis for remote industrial facilities and mining operations. Off-grid ammonia and methanol co-production pilots in Tabuk and Neom are validating this architecture. The technology is electrifying captive supply models that bypass pipeline infrastructure entirely.
SASO's updated chemical product quality regulations now mandate traceable purity documentation for all methanol destined for domestic industrial use. The framework requires third-party laboratory certification and digital labeling protocols that filter out non-compliant imports. Fuel-grade methanol blenders face the steepest compliance ramp as they adapt to both SASO specifications and SFDA safety handling rules.
Buyers in the paints and coatings sector are consolidating solvent procurement around certified low-aromatic methanol streams. Long-term supply agreements with fixed purity bands are displacing spot market purchases for large formulators. This preference shift is most visible in Jeddah and Riyadh industrial zones where multinational coatings producers operate blending facilities.
Saudi Arabia Methanol Market Segmentation
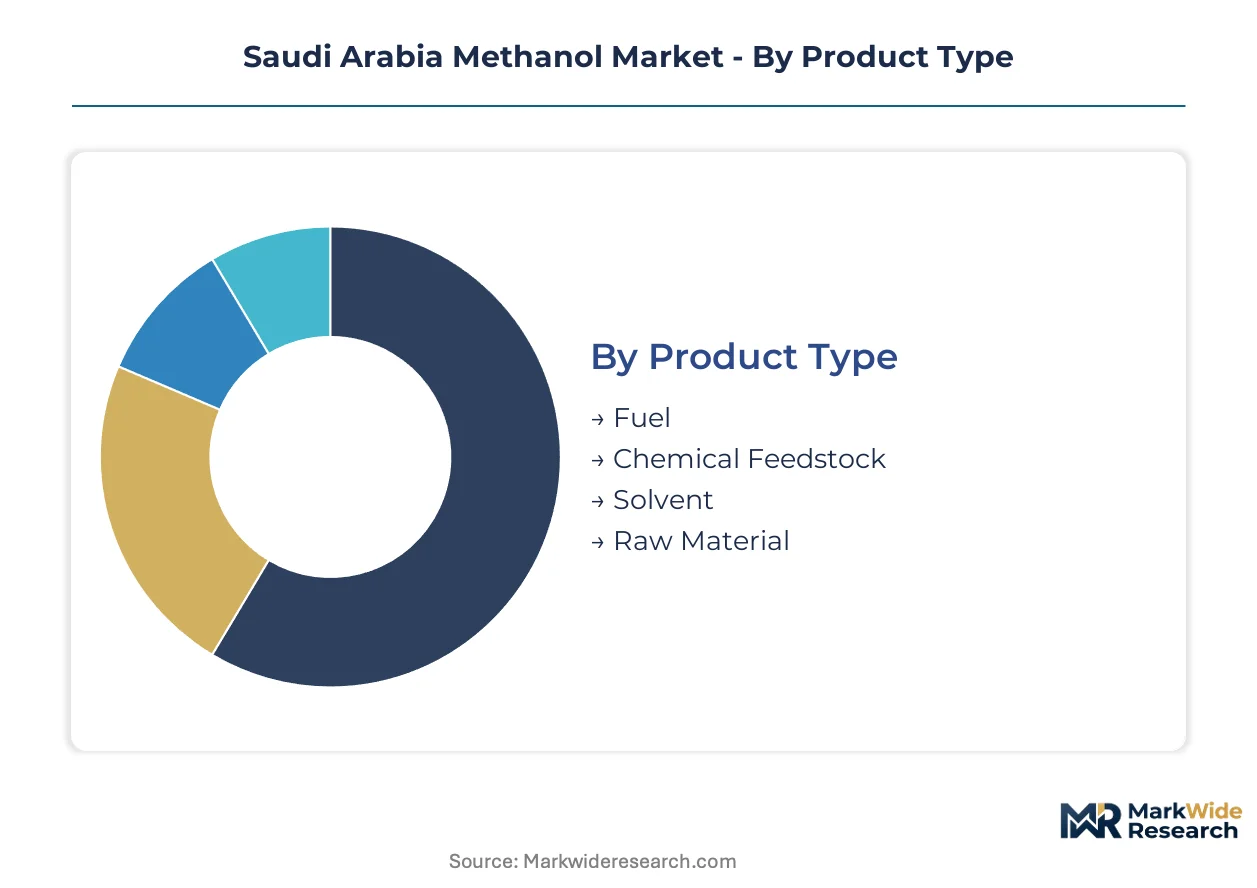
Saudi methanol buyers segment procurement by purity grade and delivery mode, with Jubail-based manufacturers commanding volume through pipeline-linked contracts while scattered inland users rely on trucked deliveries with stricter SFDA documentation.
Product Type:
Reform cycle timing and catalyst replacement schedules drive purchasing patterns across product grades, with fuel-specification buyers upgrading formulations ahead of marine decarbonization deadlines.
- Fuel:Low-sulfur methanol blends for marine bunkering and automotive fuel trials. Demand concentrates at King Fahd Industrial Port as Red Sea shipping operators trial methanol dual-fuel engines ahead of EU carbon border adjustments.
- Chemical Feedstock:High-purity streams for formaldehyde, acetic acid, and methyl tert-butyl ether synthesis. Eastern Province crackers consume the largest volumes through pipeline interconnections that eliminate tanker logistics.
- Solvent:Technical-grade methanol for paints, coatings, and industrial cleaning applications. Riyadh and Jeddah formulators source through distributors with SASO-certified purity documentation.
- Raw Material:Unrefined methanol for downstream derivative manufacturing and re-export processing. Smaller Tabuk and Neom projects test modular reforming units for captive supply.
Chemical feedstock sits at the top of the volume ranking, with fuel climbing the fastest.
Application:
Cost tier segmentation separates commodity-grade buyers from premium-specification users, with construction-linked applications commanding higher purity premiums than bulk industrial offtake.
- Plastics:Methanol-to-olefins feedstock for polyethylene and polypropylene production. Jubail petrochemical complexes integrate this stream with ammonia and methanol units for margin compression.
- Paints:Solvent-grade methanol for alkyd resin and coating formulation. Multinational producers in Jeddah industrial zones specify low-aromatic certified streams under long-term supply agreements.
- Fertilizers:Formaldehyde-derived urea resins and slow-release coating applications. Domestic agrochemical manufacturers source through direct sales contracts with Sahara International Petrochemical Company.
- Automotive:Fuel blending trials and windshield washer fluid formulations. Saudi manufacturers test methanol-gasoline blends under SFDA safety protocols for domestic fleet certification.
Plastics commands the largest application share, with automotive expanding most quickly.
End User:
Customer type segmentation distinguishes between integrated producers with captive methanol consumption and merchant buyers dependent on spot market flexibility.
- Manufacturers:Petrochemical and derivative producers with dedicated methanol consumption. Sipchem and SABIC affiliates in Jubail operate pipeline-linked supply that minimizes inventory carrying costs.
- Refineries:Fuel blending and octane enhancement operations. Domestic refiners trial methanol-methyl tert-butyl ether integration for gasoline pool upgrading.
- Research Institutions:KAUST and national labs testing carbon capture utilization and storage integration with methanol synthesis. Pilot programs in Neom validate electrified reforming architectures.
- Distributors:Wholesalers serving scattered industrial zones with trucked deliveries. SFDA transport documentation requirements compress margins for non-Jubail supply routes.
Manufacturers dominate end-user procurement, with research institutions gaining share fastest.
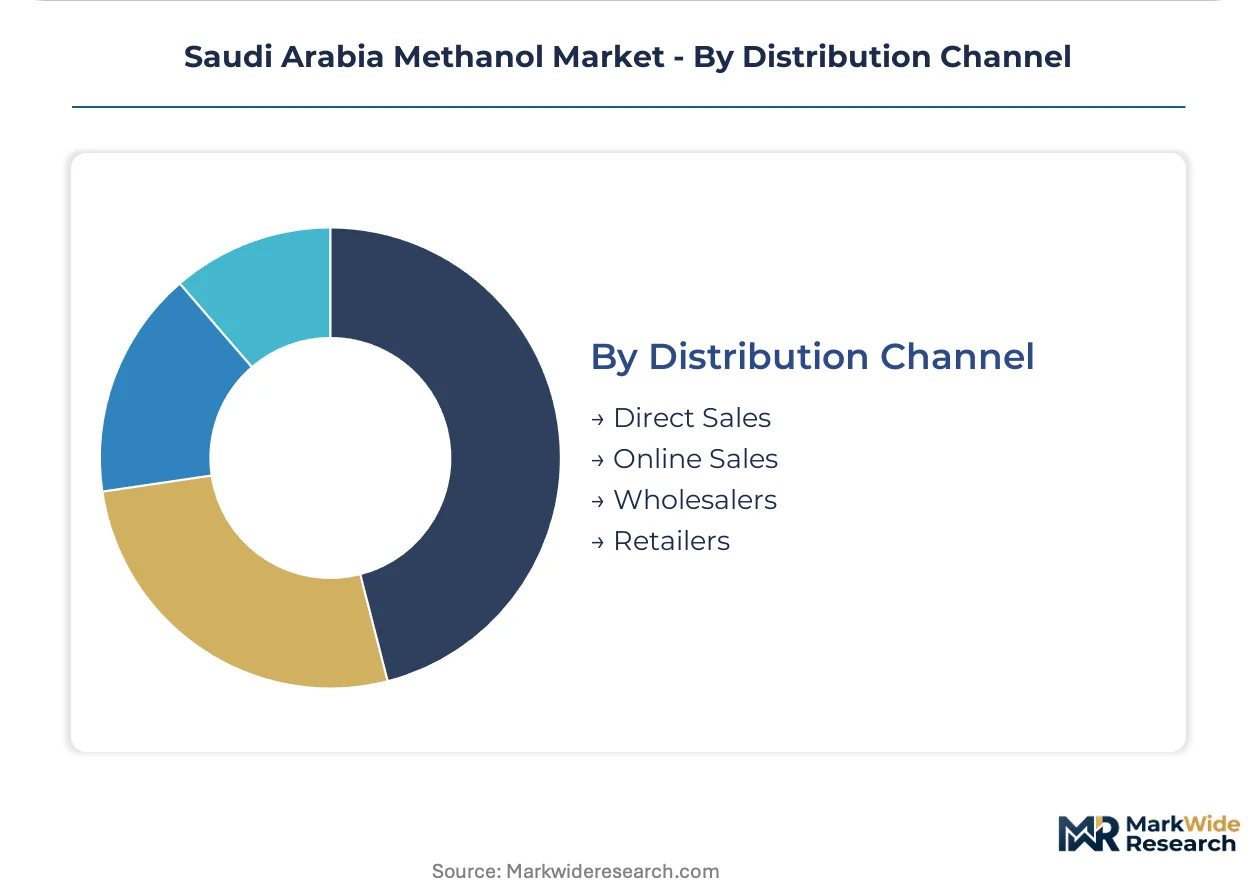
Distribution Channel:
Supply concentration patterns favor direct pipeline delivery for high-volume Eastern Province users while fragmented inland demand routes through intermediaries.
- Direct Sales:Pipeline-linked contracts between Jubail producers and adjacent derivative manufacturers. These arrangements lock in feedstock cost advantages through integrated site logistics.
- Online Sales:Digital procurement platforms for technical-grade and solvent applications. Smaller formulators in Riyadh and Dammam use certified vendor portals with SASO traceability documentation.
- Wholesalers:Regional distributors serving construction and coatings sectors with batched deliveries. Inventory pooling reduces per-unit transport costs for scattered inland buyers.
- Retailers:Packaged methanol for automotive aftermarket and laboratory supply. Limited volume segment constrained by SFDA retail handling permits and storage regulations.
Direct sales anchor channel volume, with online sales expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is pulling methanol production toward jurisdictions with lower carbon-compliance costs and integrated feedstock access. Saudi Arabia captures this advantage through subsidized natural gas allocations and streamlined SFDA-SASO certification pathways that compress time-to-market for export-bound producers.
Eastern Province
Jubail Industrial City's petrochemical cluster anchors national methanol output through pipeline-linked reforming units and ammonia co-production facilities. The Saudi Green Initiative's carbon intensity benchmarks are accelerating CCUS retrofit investments at existing steam methane reforming plants. King Fahd Industrial Port enables direct marine bunkering trials for Red Sea shipping operators testing methanol dual-fuel engines.
Riyadh
Inland solvent demand from paints and coatings formulators concentrates procurement around SASO-certified purity documentation and digital traceability platforms. The central region's construction sector resins consumption is climbing as Vision 2030 infrastructure projects accelerate formaldehyde derivative offtake. Distributors serving scattered industrial zones face compressed margins from SFDA transport documentation requirements.
Western Region
Jeddah's coatings manufacturing base is consolidating solvent procurement around long-term supply agreements with fixed low-aromatic purity bands. Multinational formulators specify certified methanol streams under contractual arrangements that displace spot market purchases. The port city's logistics infrastructure supports re-export processing for African and Red Sea markets.
NEOM Northwest
Tabuk and Neom pilot projects are validating small-scale modular reforming architectures for off-grid ammonia and methanol co-production. Electrified syngas production trials are testing containerized units that bypass pipeline infrastructure entirely. KAUST research partnerships are integrating carbon capture utilization with methanol synthesis for certified low-carbon product streams.
Saudi Arabia Methanol Market Competitive Landscape
Jubail-based producers anchor one tier through integrated feedstock advantages and pipeline-linked logistics; standalone specialists in coastal locations hold contract positions with Asian buyers. Market structure concentrates around ammonia-to-methanol value chain integration and export-oriented capacity configurations. Two strategic archetypes dominate: state-affiliated petrochemical conglomerates with captive natural gas allocations, and merchant producers serving spot and contract offtake in marine fuel and solvent applications. Competitive moves center on CCUS retrofit investments for carbon-certified product differentiation and marine bunkering infrastructure partnerships at King Fahd Industrial Port.
Within the integrated conglomerate tier, Saudi Basic Industries Corporation and Sipchem exemplify scale-driven positioning through Jubail-based pipeline interconnections and derivative manufacturing integration. Sahara International Petrochemical Company occupies a standalone merchant position serving Asian contract buyers through direct export arrangements. These three producers represent the dominant competitive configurations in the national market.
| Leading Market Players |
|---|
| Saudi Methanol Company |
| Methanol Chemicals Company |
| International Methanol Company |
| Sahara International Petrochemical Company |
| Saudi Basic Industries Corporation |
| Gulf Petrochemical Industries Company |
| Sipchem |
| Chemanol |
| AR-RAZI |
| Others |
Pricing and Supply Chain Analysis
Henry Hub natural gas futures cascades through Saudi methanol production economics, compressing margins for standalone reforming units while integrated Jubail producers capture feedstock cost advantages that stratify pricing across chemical-grade, fuel-grade, and solvent-grade tiers.
Pricing Analysis
Distributor margins for trucked methanol deliveries to Riyadh and Jeddah industrial zones run 12-18 percent above pipeline-linked direct sales, reflecting SFDA documentation burdens and fragmented inland demand. Three-tier pricing structure across fuel-specification, chemical-feedstock, and technical-solvent grades separates buyers by purity certification and volume scale. Pricing pressure stems from Chinese coal-to-methanol capacity expansion displacing Middle Eastern spot volumes in Asian markets. Small formulators in scattered construction and coatings applications exhibit highest price sensitivity, while Jubail-integrated derivative manufacturers lock in long-term offtake with minimal spot exposure.
Supply Chain Analysis
Regional distribution centers at Dammam and Jeddah anchor hub-and-spoke patterns radiating to inland industrial zones, with King Fahd Industrial Port enabling direct marine bunkering bypassing warehousing layers entirely. Production concentrates in Saudi Arabia, Qatar, and Iran, with Jubail's integrated cluster commanding regional volume leadership. Copper-zinc-alumina synthesis catalysts draw from limited German and Japanese suppliers, creating single-source vulnerability for turnaround scheduling. Distribution runs through pipeline-linked direct sales for Eastern Province crackers, while trucked wholesaler networks serve fragmented solvent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's methanol market reads as a late-cycle quality story where construction sector formaldehyde derivative demand and marine fuel decarbonization specifications pull procurement toward certified low-carbon and low-aromatic premium grades.
For Market Incumbents: To counter Chinese coal-to-methanol price competition in Asian spot markets, SABIC and Sipchem should accelerate CCUS retrofit investments at Jubail reforming units to capture EU CBAM-compliant product premiums, while tightening pipeline-linked contract structures that lock in Eastern Province derivative manufacturers through integrated site logistics. For New Entrants and Emerging Players: Enter via modular electrified reforming architectures targeting Neom and Tabuk off-grid ammonia co-production pilots, where captive supply models bypass Jubail's pipeline infrastructure entirely and Saudi Green Initiative carbon benchmarks create first-mover positioning for certified low-carbon methanol streams. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone merchant producers lack integrated feedstock access and face margin compression from natural gas allocation volatility, suggesting long-term viability favors ammonia-to-methanol value chain integration; watch for SFDA-SASO dual compliance delays as signal of operational friction in acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| CCUS Retrofit at Reforming Units | Enables EU CBAM-compliant methanol certification for premium marine fuel contracts. |
| Pipeline-Linked Long-Term Supply Agreement | Locks Eastern Province derivative manufacturers into integrated Jubail site economics. |
| Modular Electrified Reforming Deployment | Validates off-grid ammonia co-production for Neom's carbon-neutral industrial zone. |
| Marine Bunkering Infrastructure Partnership | Positions King Fahd Industrial Port as Red Sea methanol dual-fuel hub. |
| Backward Integration into Catalyst Supply | Reduces turnaround dependency on German and Japanese copper-zinc-alumina suppliers. |
Research Methodology
Multiple input streams — executive interviews with petrochemical plant managers and downstream procurement leads, customs and trade flow databases, and SEC 10-K filings from listed producers — were reconciled through bottom-up capacity modeling and top-down demand validation across the analysis window.
Historical production and offtake patterns were cross-referenced against panel inputs from industry stakeholders to construct segmentation models across grade tier, end-use industry, and regional production hub dimensions, with CAGRs derived from trend extrapolation moderated by feedstock cost and regulatory scenario inputs.
Inputs from SFDA regulatory filings and SASO certification records were available through the study window; gaps in real-time spot pricing transparency introduce uncertainty bands around short-term volatility assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Monochlorobenzene Market
Solvents
Butane Market
Solvents
Green Solvents Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Nitroglycerin Market
Solvents
Natural Distillates Market
Solvents
India High Purity Solvents Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Global Tert-Butanol Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
Hydrofluoroether Market
Solvents
Chlorobenzene Market
Solvents
Global Bio Solvents Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Hexylene Glycol Market