
 Global Semiconductor Grade Nitric Acid Market | 2026-2036
Global Semiconductor Grade Nitric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Grade Nitric Acid Market Outlook
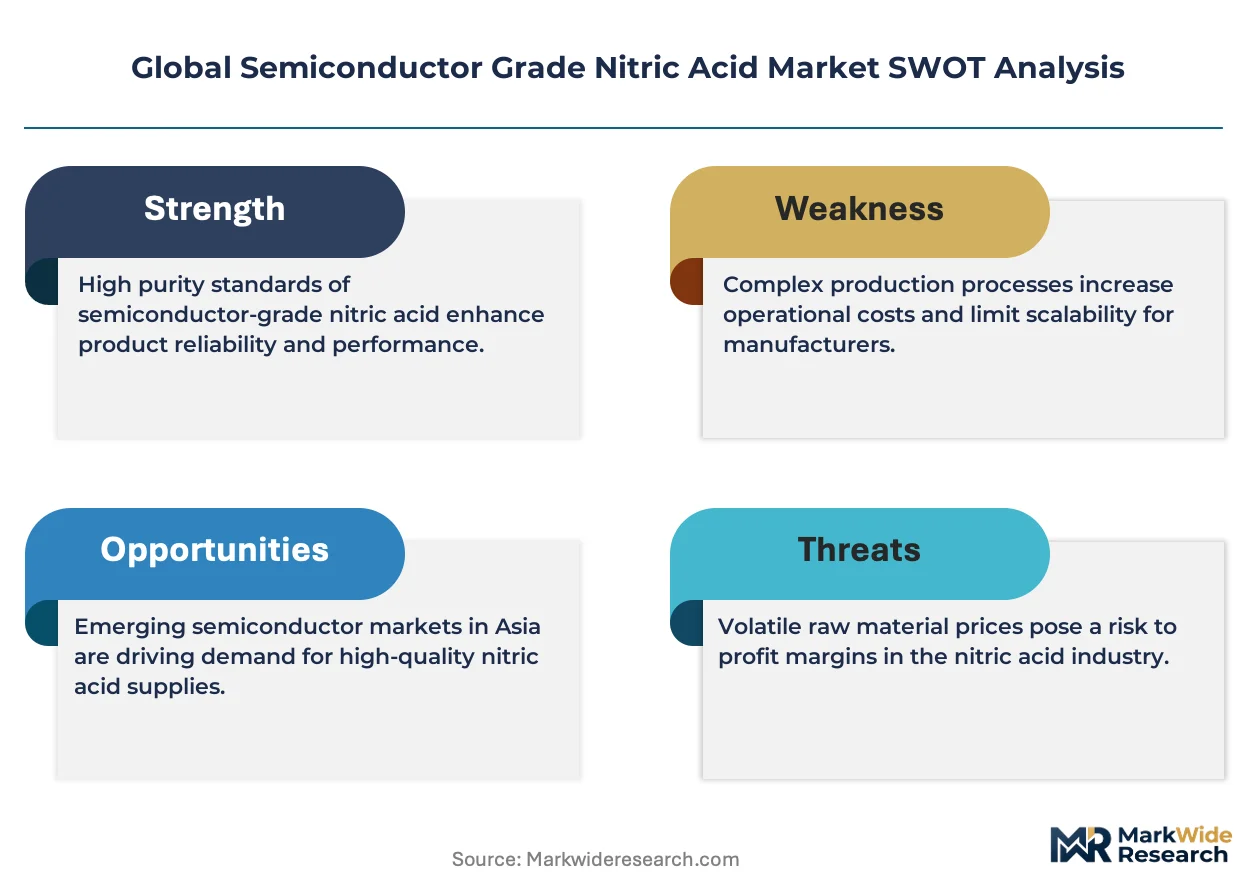
Advanced lithography node migration below 7nm is fragmenting traditional wet chemical supply chains into purity-tiered sub-networks. Air Products anchors North American on-site delivery infrastructure for captive acid regeneration at major fab complexes. Fujifilm dominates Japan's ultra-pure chemical ecosystem through backward integration into purification technology and proprietary packaging protocols. Columbus Chemical Industries specializes in reagent-grade formulations for R&D-intensive foundry pilot lines.
Semiconductor grade nitric acid denotes high-purity HNO3 with metallic impurity levels below 100 parts per trillion, produced via sub-boiling distillation and controlled environment packaging to prevent particulate contamination during silicon wafer cleaning and etching. Electronics grade purity commands the dominant volume position across etching applications where trace metal tolerance directly determines chip yield. Ultra-pure formulations represent the fastest-expanding margin pool as 3nm and below nodes impose stricter ionic contamination ceilings. Bulk container logistics still occupies the majority of shipment value, though on-site delivery modes are displacing traditional drum supply at greenfield fab campuses.
EPA hazardous waste regulations in the United States and REACH chemical registration in Europe impose divergent compliance burdens on cross-border acid suppliers, with REACH's Substance of Very High Concern screening adding documentation costs that favor regional purification assets. China's GB standards for electronic chemicals and Japan's JIS specifications create additional technical barriers that fragment global product specifications. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's Scope 3 emissions tracking reshape the cost calculus of long-distance ultra-pure chemical distribution.
Market Dynamics
Advanced node migration below 5nm is fragmenting wet chemical supply chains into purity-tiered sub-networks, forcing acid suppliers to co-locate purification assets adjacent to leading-edge fab clusters or risk exclusion from qualification programs.
Growth Catalysts
- EU Chips Act reshoring incentives:European subsidies for domestic semiconductor fabrication are expanding captive demand for ultra-pure acid regeneration infrastructure within the region's emerging fab complexes.
- Sub-boiling distillation maturation:Purification technology advances are lowering metallic impurity thresholds below 10 parts per trillion, enabling qualification at 3nm and 2nm process nodes.
- Taiwan-South Korea fab concentration:Foundry clustering in Hsinchu and Pyeongtaek generates dense demand corridors that justify on-site acid delivery investments by chemical suppliers.
Market Restraints
- High-purity quartz supply concentration:Sub-boiling distillation equipment depends on synthetic quartz crucibles sourced from a limited supplier base, creating bottleneck vulnerability.
- REACH Substance of Very High Concern screening:ECHA documentation requirements for nitric acid derivatives add compliance costs that disadvantage smaller purification operations without dedicated regulatory staff.
- Fluorinated solvent substitution threat:Dry etching chemistries using fluorinated gases are displacing wet nitric acid steps in certain memory device fabrication sequences.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme subsidies for domestic chip fabrication create greenfield demand for acid qualification programs without incumbent supplier lock-in.
- On-site regeneration service models:Chemical management contracts that include spent acid recovery and re-purification are displacing traditional drum supply at new fab campuses.
- Packaging protocol convergence:Proprietary fluoropolymer container standards from Japan are creating technology licensing revenue streams for purification specialists.
Industry Challenges
- Metrology technician scarcity:ICP-MS and TXRF analytical capabilities for parts-per-trillion impurity verification remain concentrated among a limited pool of qualified laboratory personnel.
- Fab qualification timeline compression:New acid suppliers face 18-24 month validation cycles at leading-edge foundries, extending cash conversion periods and straining working capital.
- Cross-border hazardous material logistics:Divergent EPA and ADR transport classifications create routing complexity for multi-regional purification networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Grade Nitric Acid Market |
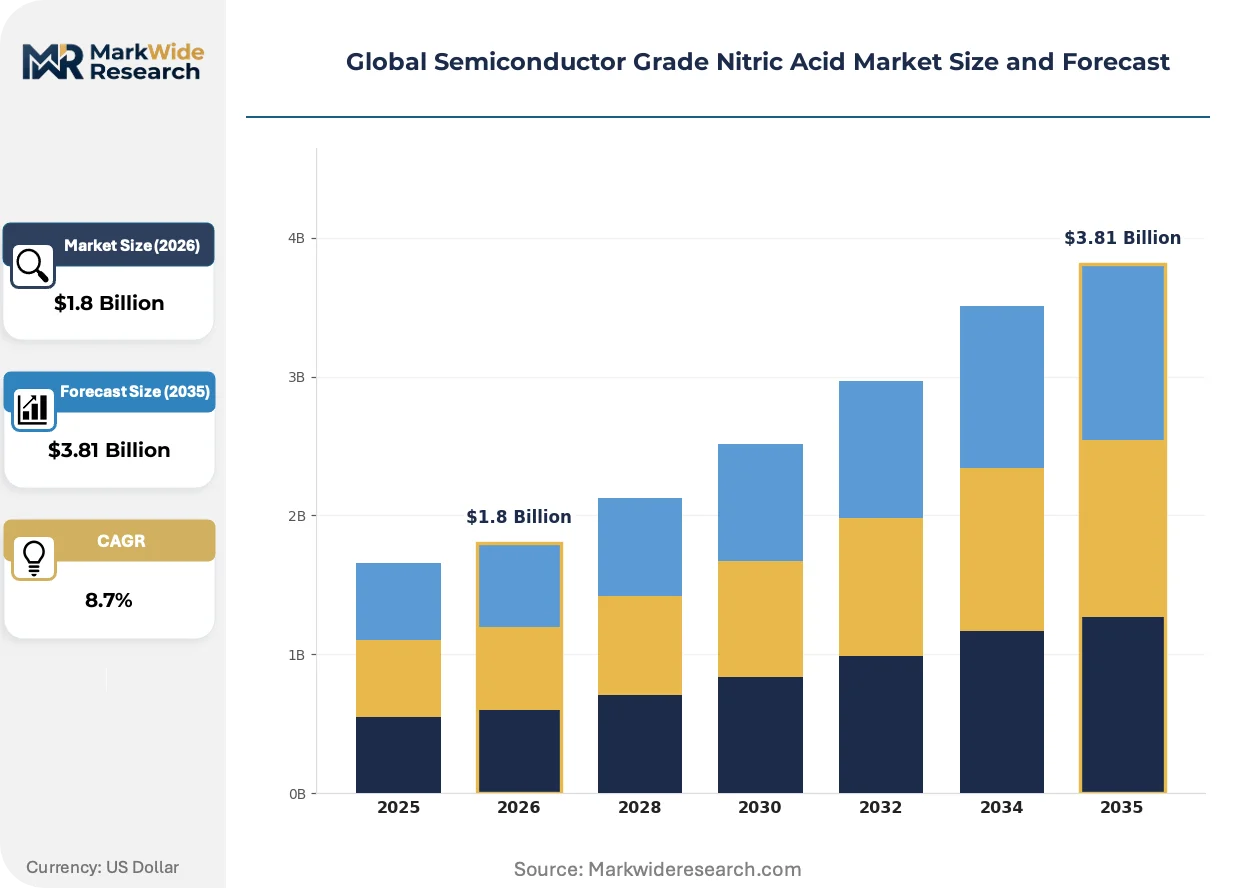
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Etching, Cleaning, Oxidation, Surface Treatment Purity Grade: Electronics Grade, Ultra-Pure, Reagent Grade, Laboratory Grade Packaging Type: Bulk Containers, Drums, Totes, Bottles Delivery Mode: On-site Delivery, Direct Supply, Managed Services, Third-Party Logistics |
| Companies Covered | Hubbard-Hall, Air Products, Columbus Chemical Industries, Transene Company, Alliance Chemical, High Purity Products, Fujifilm, DGR Industrial Products, Lab Alley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Grade Nitric Acid Market Strategic Shifts
Digital twin implementations are compressing process development timelines for acid purification systems, while regulatory emissions tracking and buyer consolidation are restructuring supplier-fab commercial relationships.
Point-of-use filtration systems with real-time particle monitoring are virtualizing final purification steps that previously required centralized distillation facilities. Memory and logic foundries in Taiwan and South Korea are deploying these modular units at 300mm wet bench stations. The technology is virtualizing geographic constraints on acid supply by enabling lower-purity bulk shipments with terminal conditioning.
REACH's Scope 3 emissions disclosure requirements are mandating cradle-to-gate carbon accounting for electronic chemicals sold into European fabs. Suppliers must now document energy consumption across sub-boiling distillation, packaging, and logistics stages. Ultra-purification operations with renewable energy procurement are capturing preferential supplier status at EU-based semiconductor manufacturing facilities.
Consolidated procurement consortia among foundry operators are unbundling acid supply from equipment maintenance contracts. Leading memory manufacturers in South Korea now negotiate chemical supply separately from wet bench service agreements, reversing prior bundled arrangements. This pattern is most visible at Pyeongtaek and Yongin complexes where annual chemical volumes justify direct supplier relationships.
Global Semiconductor Grade Nitric Acid Market Segmentation
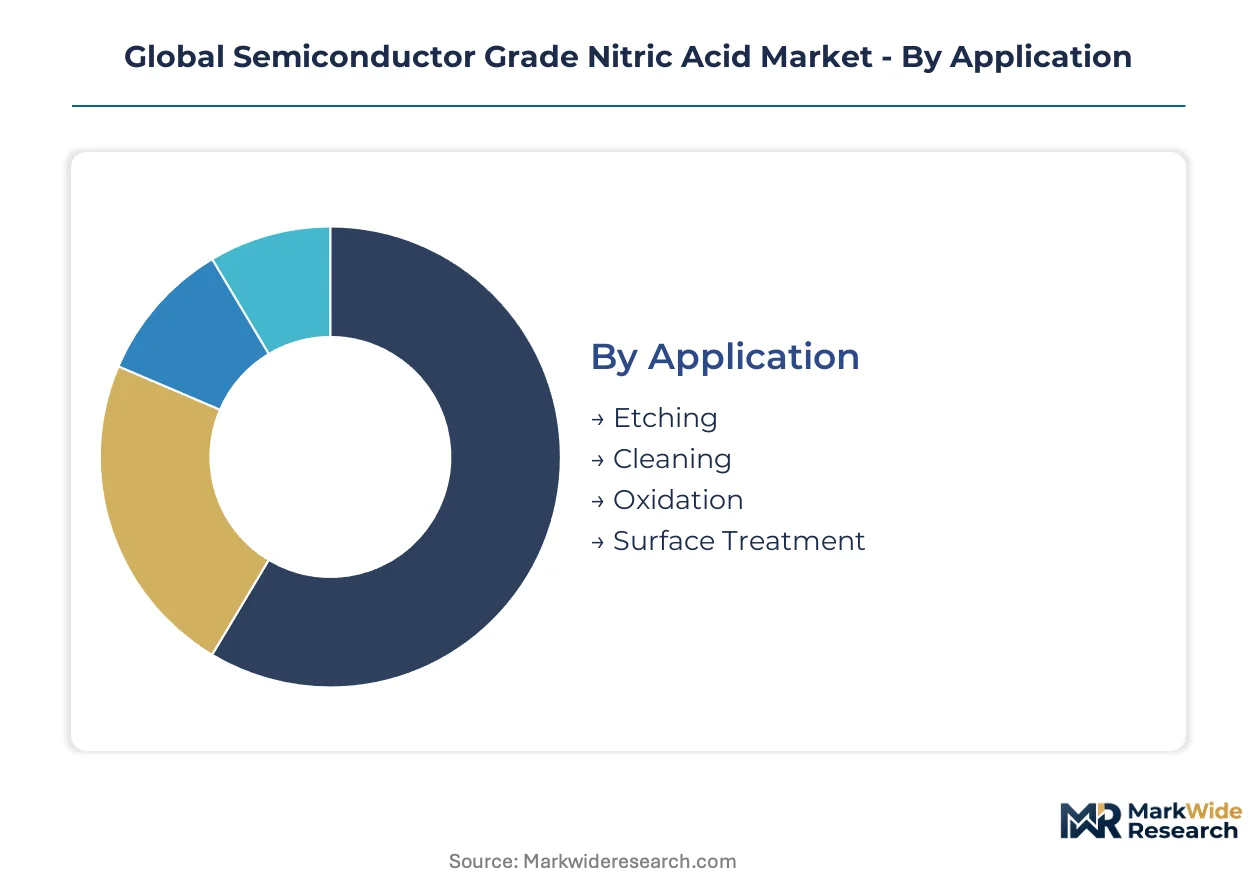
Semiconductor grade nitric acid supply chains fragment across purity thresholds, packaging protocols, and delivery modalities that each impose distinct qualification burdens on suppliers. Process node migration below 5nm is forcing foundries to unbundle these dimensions rather than accept one-size-fits-all chemical specifications.
Application:
Application dimension captures how process chemistry requirements vary across wafer fabrication stages, with each step imposing distinct contamination tolerances and consumption volumes.
- Etching:High-volume consumption at 3nm and 2nm nodes demands metallic impurity thresholds below 10 parts per trillion for gate stack definition. Taiwan and South Korea foundries concentrate demand where fluorinated gas substitution threats remain weakest in logic device fabrication.
- Cleaning:Critical pre-diffusion and post-CMP steps require controlled particle counts in addition to ionic purity. Samsung Foundry and TSMC qualification programs prioritize cleaning chemistry suppliers with point-of-use filtration integration.
- Oxidation:Silicon dioxide growth acceleration uses nitric acid as oxidant in wet thermal processes. Memory manufacturers in Pyeongtaek drive specification tightening for oxidation-grade formulations.
- Surface Treatment:Pre-deposition surface preparation commands lower purity tiers than etching but requires tighter particulate control. R&D-intensive pilot lines at Columbus Chemical Industries anchor this segment.
Etching holds installed capacity. Cleaning is rotating up the share rankings.
Purity Grade:
Purity tier stratification reflects the economic trade-off between distillation energy costs and yield sensitivity at successive lithography nodes.
- Electronics Grade:Metallic impurities below 100 parts per trillion serve mature node fabrication above 28nm. Bulk consumption volumes concentrate in China and Southeast Asia where cost sensitivity dominates supplier selection.
- Ultra-Pure:Sub-10 parts per trillion specifications enable 3nm and below qualification through sub-boiling distillation maturation. Air Products anchors North American captive supply for this tier.
- Reagent Grade:Analytical-grade formulations support metrology calibration and process development. Foundry pilot lines at leading R&D centers absorb this segment's limited volume.
- Laboratory Grade:Lowest purity tier serves academic research and non-critical testing applications outside commercial wafer fabrication.
Electronics Grade holds installed capacity. Ultra-Pure is climbing the fastest as node migration accelerates.
Packaging Type:
Packaging configuration determines contamination risk exposure during transport and storage, with fluoropolymer material specifications varying by purity tier.
- Bulk Containers:Stainless steel ISO tanks with proprietary fluoropolymer linings serve high-volume fabs with dedicated unloading infrastructure. Taiwan's Hsinchu Science Park clusters generate dense demand corridors for this format.
- Drums:Traditional 200-liter fluoropolymer-lined drums retain share at smaller fabs and process development facilities without bulk handling systems. REACH packaging waste regulations in Europe are compressing drum reuse cycles.
- Totes:Intermediate bulk containers bridge drum and tanker economics for mid-scale consumers. South Korean memory manufacturers are standardizing tote specifications across Pyeongtaek and Yongin complexes.
- Bottles:Small-volume fluoropolymer bottles serve laboratory and pilot line applications with stringent lot traceability requirements.
Bulk Containers hold installed capacity. Totes are gaining share fastest as fab scale sweet spots shift.
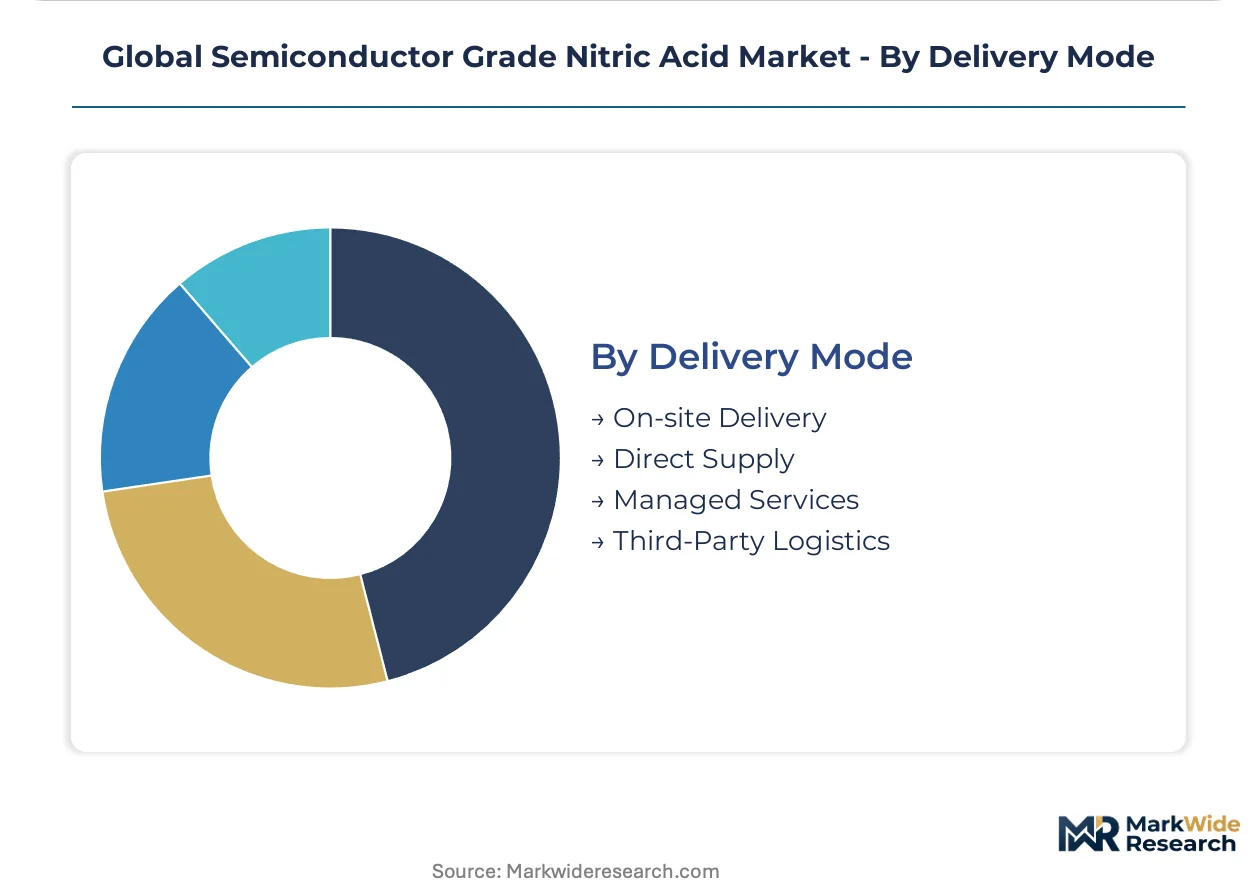
Delivery Mode:
Delivery modality captures the service intensity gradient from commodity chemical supply to integrated chemical management contracts.
- On-site Delivery:Direct pipeline or dedicated tanker supply with real-time purity monitoring eliminates transport contamination risk. Greenfield fab campuses in India and the United States are mandating this mode in initial procurement specifications.
- Direct Supply:Manufacturer-to-fab shipment without distributor intermediaries preserves lot traceability for critical process chemistries. Fujifilm's backward integration into purification technology supports direct supply dominance in Japan.
- Managed Services:Chemical management contracts bundle supply with spent acid recovery and re-purification. EU Chips Act reshoring incentives are expanding captive regeneration infrastructure under this model.
- Third-Party Logistics:Specialized hazardous material carriers with ADR and EPA certification handle cross-border movements where on-site infrastructure is uneconomical.
Direct Supply holds installed capacity. Managed Services is expanding most quickly as circular economy mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese purification specialists export ultra-pure formulations to Taiwan's foundry clusters, while South Korean chemical managers regenerate spent acid for captive memory fabrication. This trade-flow pattern concentrates high-value supply chain control in East Asian industrial corridors.
United States
On-site delivery infrastructure expansion at greenfield fab campuses in Arizona and Texas drives demand for captive acid regeneration systems. EPA hazardous waste regulations under RCRA impose stringent spent acid handling protocols that favor regional purification assets. Intel's manufacturing expansion in Chandler and Samsung Foundry's Taylor complex anchor North American demand concentration.
Taiwan
TSMC's advanced node migration below 3nm at Hsinchu Science Park generates the world's densest demand corridor for sub-10 parts per trillion nitric acid specifications. The island's GB standards alignment with mainland Chinese technical barriers creates cross-strait specification fragmentation. Taichung's emerging fab cluster is mandating fluoropolymer-lined bulk container standards that diverge from legacy drum protocols.
South Korea
Samsung Foundry and SK Hynix memory manufacturing at Pyeongtaek and Yongin complexes drive specification tightening for oxidation-grade formulations. MFDS chemical registration requirements add documentation burdens that disadvantage non-Korean purification operations. Busan-Ulsan's chemical logistics hub is consolidating hazardous material transport certification for cross-border acid movements.
Japan
Fujifilm's backward integration into purification technology and proprietary packaging protocols dominates the domestic ultra-pure chemical ecosystem. METI's JIS specifications for electronic chemicals create technical barriers that fragment global product standards. Kyushu's silicon island concentration supports captive acid supply for legacy node memory fabrication.
China
Domestic GB standards for electronic chemicals and dual carbon goals reshape cost calculus for long-distance ultra-pure chemical distribution. Yangtze River Delta fab clusters in Shanghai and Wuxi concentrate mature node demand where cost sensitivity dominates supplier selection. SMIC's expansion in Beijing-Tianjin-Hebei is driving localization mandates for critical wet chemicals.
Global Semiconductor Grade Nitric Acid Market Competitive Environment
Channel-controlling players compete with product-specialist players across purity-tiered sub-networks that fragment as process nodes migrate below 5nm. The vendor base organizes around purification technology ownership, packaging protocol control, and on-site service delivery capabilities. Three strategic archetypes dominate: integrated gas and chemical suppliers with captive infrastructure, specialized ultra-pure chemical purifiers with proprietary distillation assets, and regional reagent-grade formulators serving R&D-intensive pilot lines. Competitive moves concentrate on co-location partnerships with leading-edge fabs and technology licensing of fluoropolymer container standards.
Within the integrated infrastructure tier, Air Products anchors North American on-site delivery capabilities through direct pipeline supply arrangements at major fab complexes. Fujifilm occupies a central position in Japan's ultra-pure chemical ecosystem, exemplifying backward integration into purification technology and proprietary packaging protocols. Columbus Chemical Industries represents the specialized reagent-grade segment, serving foundry pilot lines with analytical-grade formulations for process development. These three players illustrate how geographic concentration of demand shapes competitive positioning across distinct service intensity levels.
| Leading Market Players |
|---|
| Hubbard-Hall |
| Air Products |
| Columbus Chemical Industries |
| Transene Company |
| Alliance Chemical |
| High Purity Products |
| Fujifilm |
| DGR Industrial Products |
| Lab Alley |
| Others |
Value Chain & Pricing Dynamics
Busan-Ulsan hazardous material corridors anchor freight cost dynamics for ultra-pure nitric acid movements between South Korean purification assets and Taiwan's Hsinchu foundry cluster, concentrating supply-side pricing power among carriers with dual EPA-ADR certification while downstream buyers face tiered price differentiation based on purity thresholds and delivery modality commitments.
Pricing Analysis
Node-generation pricing gaps separate mature 28nm-plus specifications from sub-10 parts per trillion ultra-pure tiers required at 3nm and below. Three-tier pricing structure across premium, standard, and economy levels reflects distillation energy intensity and fluoropolymer packaging protocol investments. Cost compression in electronics-grade tiers is intensifying because Chinese GB-standard suppliers are expanding mature-node capacity. Memory manufacturers in Pyeongtaek exhibit lowest price sensitivity due to yield-critical cleaning chemistry requirements, while Southeast Asian packaging houses absorb maximum cost pressure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for qualified suppliers serving TSMC and Samsung Foundry qualification programs, compressing working capital for smaller purification operations. Taiwan, South Korea, and the United States concentrate sub-boiling distillation capacity. Synthetic quartz crucibles, fluoropolymer container liners, and renewable energy procurement for Scope 3 compliance anchor input dependencies. Single-source vulnerability in high-purity quartz supply creates structural risk exposure. Distribution runs through on-site pipeline delivery at greenfield campuses and direct tanker supply at established fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sub-10 parts per trillion metrology capability scarcity constrains supplier qualification velocity, with ICP-MS and TXRF analytical talent pools concentrated among a limited cohort of laboratory specialists across Taiwan, Japan, and South Korea.
For Market Incumbents: Harden fluoropolymer packaging protocol control through proprietary container standard licensing to capture technology royalties from emerging India fabs. Expand captive regeneration infrastructure adjacent to Arizona and Texas greenfield campuses before qualification windows close. Defend against dry etching chemistry substitution by embedding point-of-use filtration systems into long-term chemical management contracts. For New Entrants and Emerging Players: India's PLI-subsidized semiconductor manufacturing zones offer the most penetrable geography for acid qualification programs without incumbent supplier lock-in. Target oxidation-grade formulations for memory pilot lines as a beachhead before advancing to etching-grade ultra-pure specifications. Pursue joint qualification partnerships with European chemical management service providers seeking regional purification assets under EU Chips Act reshoring mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial gas parents seeking to monetize captive semiconductor chemical assets. Five-to-ten year viability hinges on purification technology ownership rather than distribution relationships. Monitor ECHA Substance of Very High Concern screening acceleration as an inflection signal for regulatory-driven consolidation among sub-scale European operators.| Strategic Initiative | Industry Significance |
|---|---|
| On-site Regeneration Infrastructure | Captive acid recovery at Arizona greenfield campuses reduces transport contamination risk and Scope 3 emissions exposure under EPA tracking. |
| Fluoropolymer Container Licensing | Proprietary packaging protocol royalties from Japan create technology revenue streams independent of volume-based chemical sales. |
| Sub-boiling Distillation Scale-up | Capacity additions at Pyeongtaek-adjacent facilities serve Samsung Foundry and SK Hynix oxidation-grade specification tightening. |
| Renewable Energy Procurement | Green power sourcing for distillation operations secures preferential supplier status under EU Green Deal Scope 3 disclosure requirements. |
| Metrology Capability Acquisition | ICP-MS and TXRF laboratory assets accelerate qualification timelines for new entrants facing 18-24 month foundry validation cycles. |
Study Parameters
Initial hypotheses were tested against primary input from wet chemical procurement directors, sub-boiling distillation plant managers, ICP-MS laboratory supervisors, and fluoropolymer packaging engineers and refined through secondary validation against customs trade data, SEMI industry reports, SEC 10-K chemical segment disclosures, and ECHA REACH registration databases. Bottom-up consumption estimates from individual fab qualification programs were triangulated against top-down purity-grade production capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across purity grade tiers, application chemistry requirements, packaging format specifications, and regional production hub configurations. CAGRs were derived from node migration timelines and foundry capacity expansion announcements. Forecast inputs incorporated sub-boiling distillation technology maturation curves and EU Chips Act subsidy disbursement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported purification ventures or accelerated dry etching substitution in memory fabrication would shift outcomes. Macroeconomic contraction in semiconductor capital expenditure, ECHA regulatory acceleration beyond current SVHC screening timelines, or breakthroughs in point-of-use filtration technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Cyclamate Market