
 Ammonium Dichromate Market | 2026-2036
Ammonium Dichromate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Dichromate Market Analysis
A capital-intensity divergence between integrated chromite processors and reagent distributors is reorganizing competitive tiers in ammonium dichromate supply. LANXESS AG leverages captive chromium chemical infrastructure to sustain cost discipline across European production. American Elements competes through specialized high-purity synthesis protocols for laboratory and electronics clients. Chengdu HuaXia Chemical Reagent Co anchors Asia-Pacific supply through regional distribution density and technical grade volume positioning.
Ammonium dichromate is an inorganic salt with the formula (NH₄)₂Cr₂O₇, existing as orange-red crystals that decompose thermally to chromium(III) oxide, nitrogen, and water at approximately 180°C; manufacturers produce it via reaction of chromic acid with ammonia solution for applications requiring controlled oxidation, pyrotechnic initiation, or photographic sensitization. Crystalline product types dominate volume due to handling stability and precise dosing in catalyst bed configurations, while powder grades command margin premiums in analytical reagent specifications where particle uniformity determines titration reliability. Application demand concentrates in pigments and dyes where chromium-based colorants retain irreplaceable performance in certain corrosion-resistant coatings, though catalyst end-use is gaining share as chemical processors seek oxidation promoters with defined thermal decomposition profiles.
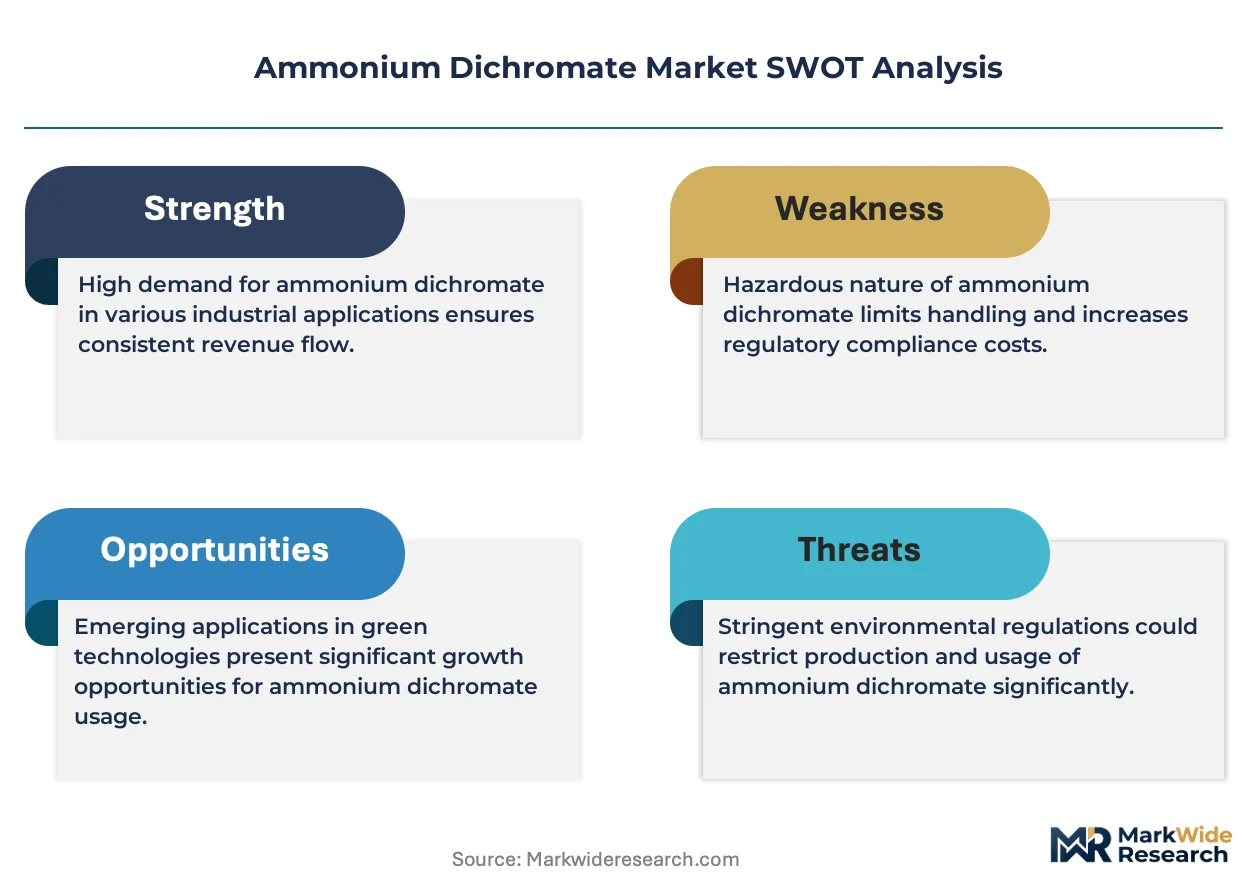
Regulatory frameworks including REACH in Europe, EPA hazardous substance designations in the United States, and BIS chemical safety standards in India collectively restrict hexavalent chromium compound handling, transportation thresholds, and occupational exposure limits, thereby elevating compliance costs and favoring suppliers with certified environmental management systems. OSHA permissible exposure limits and EU CLP carcinogen classification further constrain downstream formulation flexibility, pushing textile and coatings buyers toward certified technical grade material with documented impurity profiles. Stakeholders must monitor evolving substitution economics as trivalent chromium alternatives and organic oxidation catalysts advance in performance parity, while tracking which regional enforcement regimes tighten discharge or import licensing requirements first.
Market Dynamics
REACH restrictions on hexavalent chromium compounds are forcing European formulators to requalify supply chains around certified technical grades with documented impurity profiles, while Indian textile processors scale crystalline-grade procurement for oxidation catalyst beds.
Growth Catalysts
- Catalyst Bed Expansion:Chemical processors in India are installing ammonium dichromate oxidation promoters in continuous flow reactors for specialty intermediate synthesis.
- REACH Compliance Premium:EU manufacturers are sourcing certified technical grades with full material safety data documentation to maintain downstream formulation licenses under ECHA oversight.
- Pyrotechnic Demand Stability:Defense and aerospace ignition system suppliers retain ammonium dichromate for thermal initiation sequences where decomposition temperature precision remains non-substitutable.
Market Restraints
- Chromite Supply Concentration:Integrated processors in Kazakhstan and South Africa control metallurgical-grade chromite feedstock, constraining merchant dichromate producers.
- Substitution Economics:Sodium persulfate and peracetic acid systems are displacing ammonium dichromate in textile bleaching sequences where color fastness requirements permit.
- OSHA Exposure Limits:US permissible exposure thresholds for hexavalent chromium compounds elevate occupational safety infrastructure costs above organic oxidizer alternatives.
Strategic Opportunities
- High-Purity Laboratory Segments:Electronics and semiconductor analytical labs in Japan are qualifying ultra-low trace-metal grades for wafer contamination testing protocols.
- BIS Certification Pathways:Indian specialty chemical exporters are pursuing Bureau of Indian Standards chemical safety certifications to access EU and Middle East import channels.
- Photographic Sensitization Niche:Fine art and archival printing workshops in Germany and France sustain demand for ammonium dichromate in carbon transfer and gum bichromate processes.
Industry Challenges
- Hazardous Materials Handling Certification:Logistics providers must maintain ADR and IMDG code compliance for hexavalent chromium compound transport, constraining carrier availability and elevating freight rates.
- Legacy Equipment Retrofit Costs:Indian and Southeast Asian textile dye houses face capital requirements for exhaust ventilation and wastewater chromium recovery systems to meet discharge limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Dichromate Market |
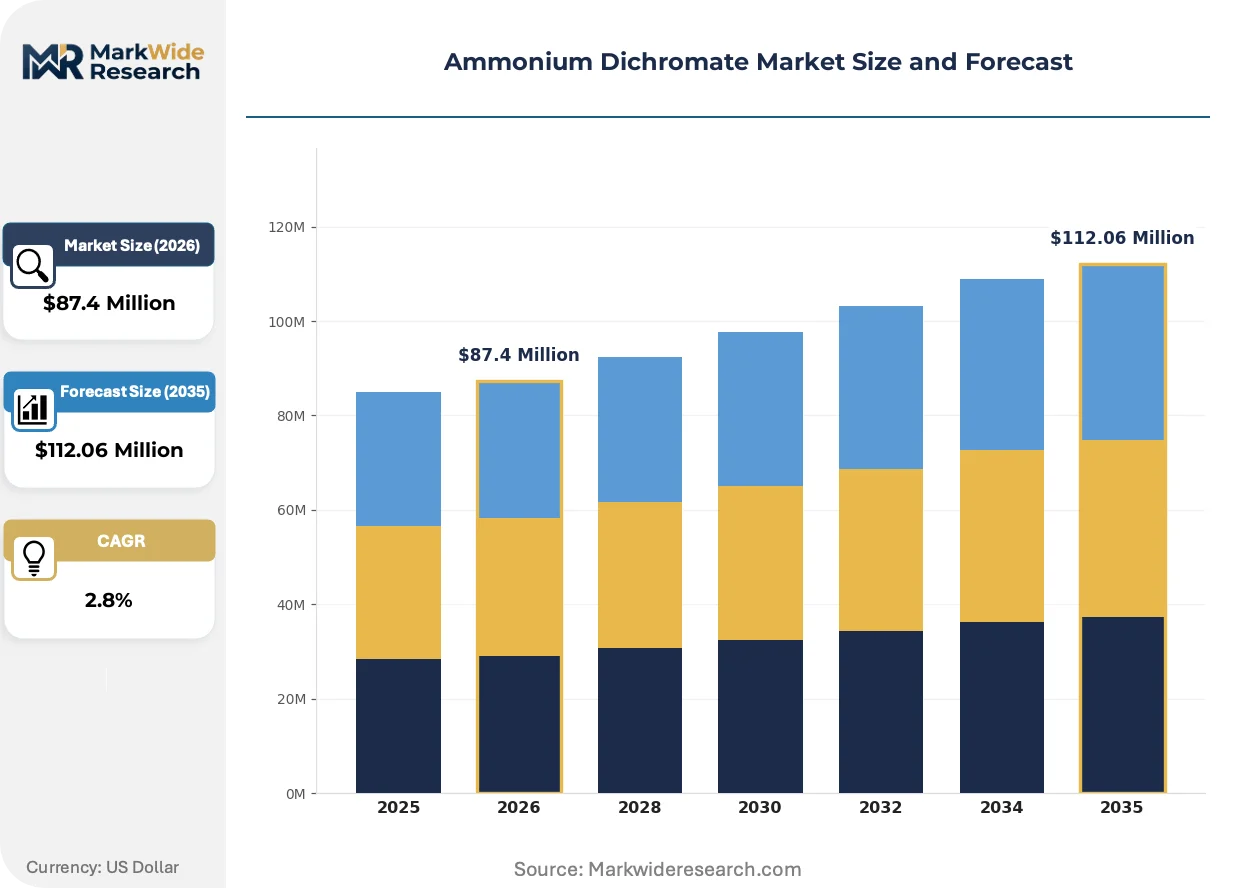
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $112.06 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Granular, Powder, Liquid Application: Catalysts, Dyes, Pigments, Analytical Reagents End Use Industry: Textiles, Chemicals, Coatings, Laboratories Purity Grade: High Purity, Technical Grade, Standard Grade, Others |
| Companies Covered | LANXESS AG, American Elements, BASF SE, Thermo Fisher Scientific Inc., Merck KGaA, Chengdu HuaXia Chemical Reagent Co, Elementis plc, Spectrum Chemical Manufacturing Corporation, Avantor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Dichromate Market Emerging Trajectories
Controlled thermal decomposition profiles are becoming the primary specification differentiator as chemical processors seek oxidation promoters with predictable reaction kinetics, while regulatory pressure accelerates documentation requirements across supply tiers.
Encapsulated ammonium dichromate formulations with polymer coating barriers are decomposing at engineered temperature thresholds in pyrotechnic ignition sequences. Defense contractors in the United States and Israel are qualifying these stabilized grades for munitions initiation systems where moisture resistance and precise burn rates determine reliability. The technology is decomposing traditional powder-grade specifications by enabling extended shelf life and reduced handling precautions in field deployment scenarios.
EU CLP carcinogen classification for hexavalent chromium compounds is mandating downstream hazard communication revisions and safety data sheet reissuance across coatings and pigment supply chains. German and Dutch formulators are reformulating corrosion-resistant primers to minimize dichromate content while retaining salt-spray performance. Pigment manufacturers serving marine and industrial coating end-uses are most affected, with several pursuing trivalent chromium passivation layers as interim compliance pathways.
Direct procurement relationships between Indian textile processors and crystalline-grade producers are compressing distributor margins and accelerating certificate-of-analysis verification cycles. Mumbai and Surat dye house clusters are negotiating annual volume contracts with BIS-certified suppliers, bypassing traditional reagent distributors. This channel consolidation is most visible in Gujarat and Maharashtra states, where integrated chemical parks enable just-in-time delivery and technical service proximity.
Ammonium Dichromate Market Segmentation
Segmentation in ammonium dichromate supply reveals how regulatory pressure and application-specific performance requirements fragment procurement strategies across purity tiers and physical forms. Buyers in REACH-regulated jurisdictions face entirely different qualification protocols than those in emerging chemical processing clusters.
Product Type:
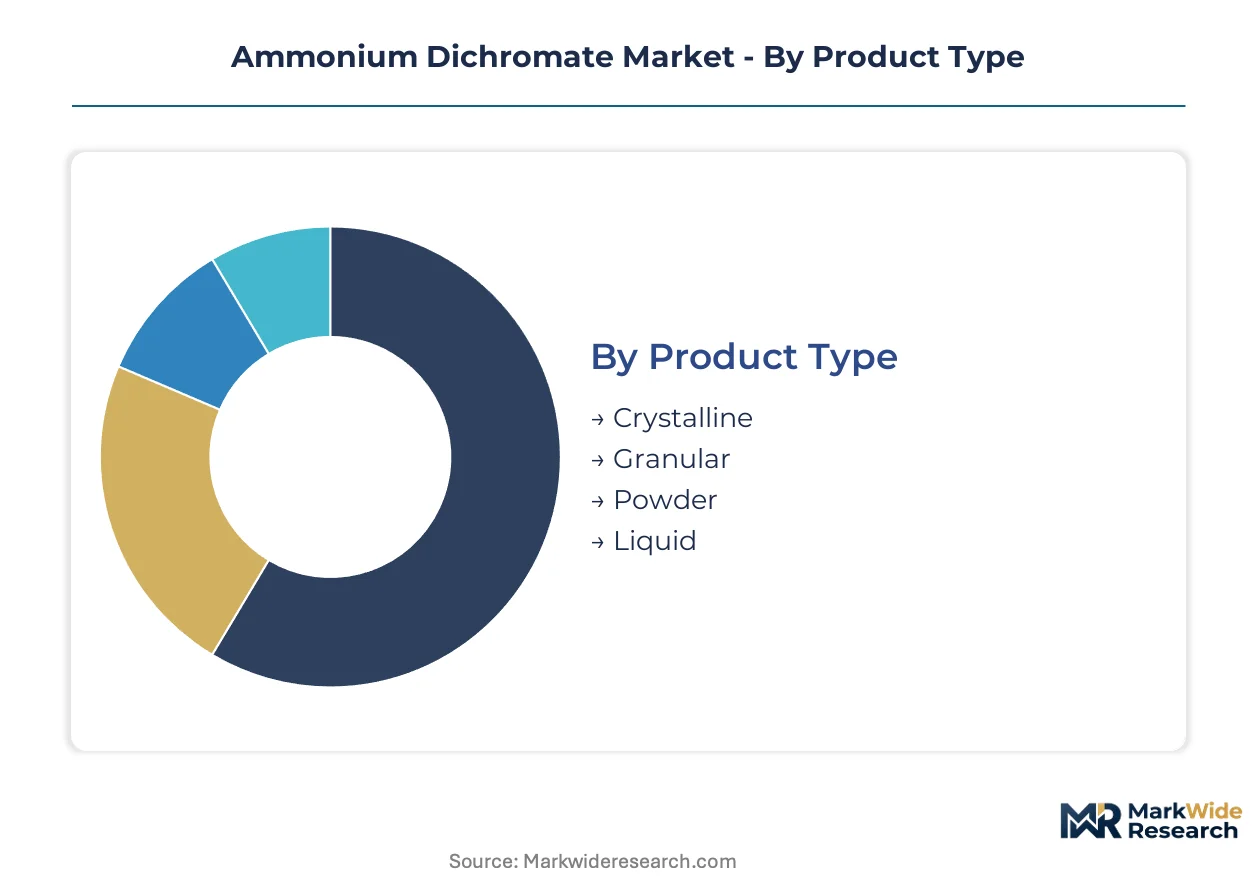
REACH documentation requirements and OSHA handling thresholds create divergent demand profiles across physical forms, with crystalline grades commanding premium certification overhead while powder forms face tighter occupational exposure constraints.
- Crystalline:Orange-red monoclinic crystals with defined particle geometry enable precise dosing in fixed-bed catalyst configurations. Indian chemical processors in Gujarat and Maharashtra are scaling annual volume contracts for crystalline supply to feed continuous oxidation reactors in specialty intermediate synthesis.
- Powder:Finely divided material with high surface-area-to-mass ratios accelerates dissolution kinetics in analytical titration protocols. Laboratory and electronics testing facilities in Japan are qualifying ultra-low trace-metal powder grades for semiconductor wafer contamination analysis, though OSHA permissible exposure limits elevate handling infrastructure costs above crystalline alternatives.
- Granular:Intermediate particle sizing balances flow characteristics with dissolution control for pyrotechnic blending operations.
- Liquid:Aqueous solution formulations eliminate dust exposure hazards in textile dye house applications where BIS discharge monitoring applies.
Established volume favors crystalline; emerging adoption favors powder.
Application:
Cost tier differentiation separates commodity oxidation processes from premium analytical specifications, with catalyst applications absorbing volume at standard margins while reagent segments sustain price premiums through documentation intensity.
- Catalysts:Thermal decomposition at engineered temperature thresholds provides controlled oxidation in continuous flow reactors. Mumbai and Surat textile clusters are installing ammonium dichromate promoter beds for bleaching sequences where sodium persulfate substitution economics remain unfavorable.
- Analytical Reagents:Standardized titration reliability demands documented impurity profiles and batch-to-batch consistency. German and French fine art workshops sustain niche demand for photographic sensitization in carbon transfer and gum bichromate archival processes.
- Dyes:Chromium-based colorants retain irreplaceable performance in certain corrosion-resistant coating formulations despite EU CLP carcinogen classification pressures.
- Pigments:Salt-spray performance requirements in marine and industrial primers drive continued incorporation despite reformulation trends toward trivalent chromium passivation layers.
Margin concentration sits with analytical reagents; volume concentration sits with catalysts.
End Use Industry:
Customer type fragmentation separates integrated chemical processors from distributed laboratory buyers, with textile and coatings sectors driving tonnage while laboratory segments sustain specification premiums through certificate-of-analysis verification cycles.
- Chemicals:Integrated specialty intermediate manufacturers operate continuous oxidation systems requiring just-in-time crystalline delivery from BIS-certified suppliers. Direct procurement relationships are compressing traditional distributor margins in Indian chemical parks.
- Textiles:Dye house clusters face capital requirements for exhaust ventilation and wastewater chromium recovery systems to meet discharge limits, with legacy equipment retrofit costs constraining smaller processors.
- Coatings:Marine and industrial primer formulators navigate EU CLP hazard communication revisions while minimizing dichromate content.
- Laboratories:Electronics and semiconductor analytical facilities in Japan qualify ultra-low trace-metal specifications for contamination testing protocols.
Procurement scale favors chemicals; specification intensity favors laboratories.
Purity Grade:
Supply concentration around certified technical grades reflects how REACH and BIS documentation requirements have consolidated procurement around suppliers with verified environmental management systems.
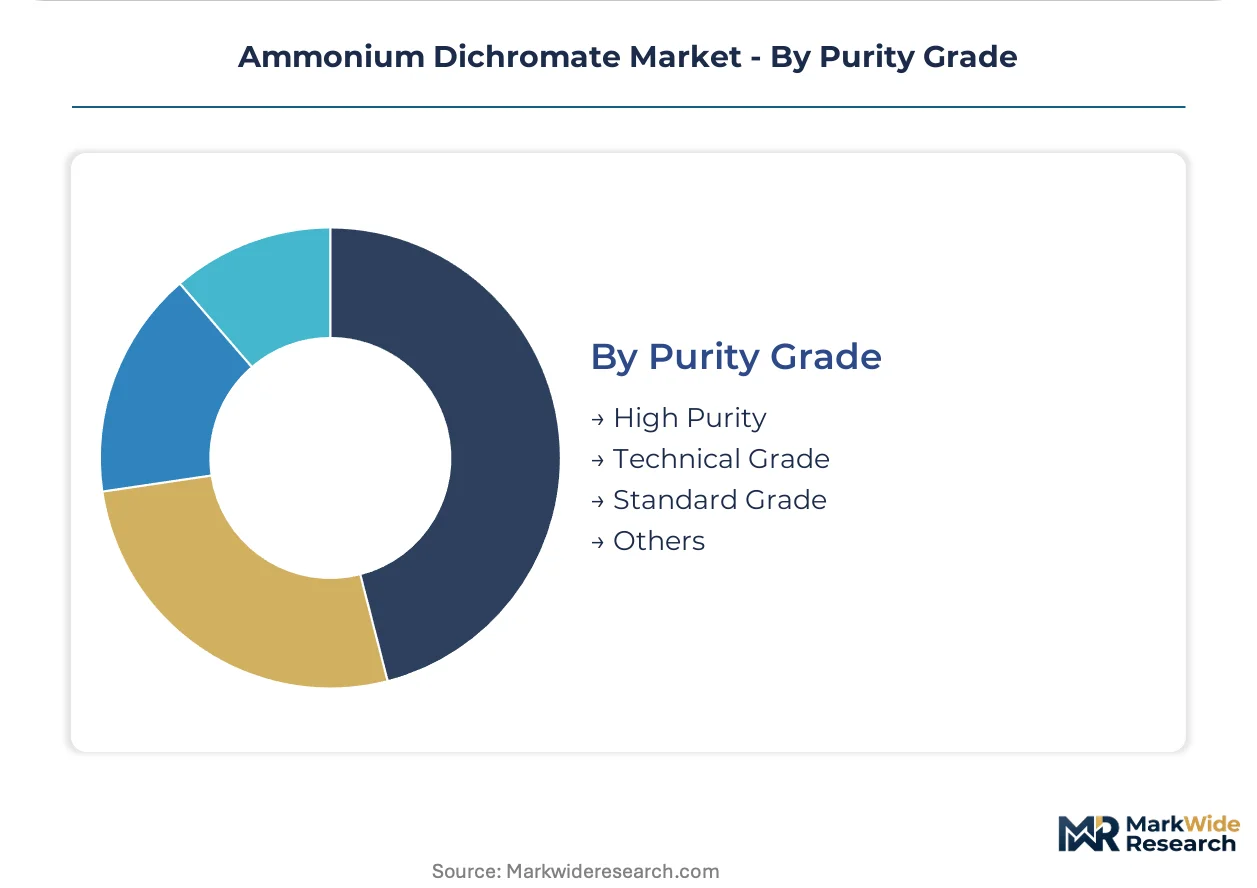
- Technical Grade:Documented impurity profiles and full material safety data enable downstream formulation licenses under ECHA oversight. EU manufacturers are requalifying supply chains around certified technical grades as REACH restrictions on hexavalent chromium compounds tighten.
- High Purity:Ultra-low trace-metal specifications serve electronics and semiconductor wafer testing where particle uniformity determines analytical reliability. Japanese electronics labs are qualifying these grades for contamination protocol compliance.
- Standard Grade:Baseline specifications satisfy pyrotechnic and general oxidation applications where decomposition temperature precision matters more than impurity minimization.
- Others:Custom purity specifications serve defense and aerospace ignition system suppliers with moisture-resistant encapsulated formulations.
Regulatory compliance favors technical grade; performance differentiation favors high purity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ammonium dichromate track divergent regulatory stringency, with REACH-regulated markets sourcing certified technical grades while Indian processors absorb crystalline volumes for domestic catalyst installation.
India
Mumbai and Surat textile clusters are scaling crystalline-grade procurement for oxidation catalyst beds in continuous bleaching reactors. BIS chemical safety standards constrain discharge thresholds, forcing Gujarat dye houses to retrofit wastewater chromium recovery systems. Maharashtra chemical parks enable direct procurement relationships that bypass traditional reagent distributors.
Germany
Fine art workshops in Berlin and Cologne sustain niche demand for photographic sensitization in carbon transfer and gum bichromate archival processes. EU CLP carcinogen classification mandates hazard communication revisions across coatings supply chains. BASF and LANXESS leverage captive chromium chemical infrastructure in the Rhine-Ruhr industrial corridor to maintain downstream formulation licenses under ECHA oversight.
United States
Defense contractors in Arizona and Utah qualify encapsulated ammonium dichromate grades for munitions ignition systems where moisture resistance determines field reliability. OSHA permissible exposure limits for hexavalent chromium elevate occupational safety infrastructure costs above organic oxidizer alternatives. EPA hazardous substance designations restrict transportation thresholds for pyrotechnic material handlers.
Japan
Electronics and semiconductor analytical labs in Tokyo and Osaka are qualifying ultra-low trace-metal powder grades for wafer contamination testing protocols. METI industrial chemical guidelines align with international standards for high-purity reagent documentation. Kanto region facilities absorb premium pricing for certificate-of-analysis verification cycles that satisfy export qualification requirements.
China
Specialty chemical processors in the Yangtze River Delta install ammonium dichromate oxidation promoters for pharmaceutical intermediate synthesis where thermal decomposition precision matters. MEE environmental discharge monitoring tightens chromium recovery mandates for chemical park operators. Zhejiang and Jiangsu provinces concentrate merchant dichromate consumption among integrated specialty intermediate manufacturers.
Ammonium Dichromate Market Vendor Landscape
Concentration sits with integrated chromite processors and specialized reagent distributors. The vendor base separates into captive chromium chemical producers, high-purity synthesis specialists, and regional technical grade distributors. Strategic moves center on REACH compliance certification and direct procurement relationship formation with Indian textile clusters.
Among German-based chemical conglomerates, LANXESS AG and BASF SE exemplify integrated chromite processor archetypes with captive feedstock infrastructure. American Elements occupies a position within the high-purity synthesis specialist tier serving laboratory and electronics specifications. Chengdu HuaXia Chemical Reagent Co represents regional technical grade distributors anchoring Asia-Pacific supply through distribution density.
| Leading Market Players |
|---|
| LANXESS AG |
| American Elements |
| BASF SE |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Chengdu HuaXia Chemical Reagent Co |
| Elementis plc |
| Spectrum Chemical Manufacturing Corporation |
| Avantor, Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles among Indian textile processors compress crystalline-grade procurement windows and amplify spot-market volatility for certified technical grades. This lead-time compression concentrates pricing power with BIS-certified suppliers capable of just-in-time delivery, while REACH documentation requirements elevate certification premiums across European supply tiers.
Pricing Analysis
Configured-to-order pricing for encapsulated pyrotechnic grades commands spreads exceeding standard crystalline benchmarks due to moisture-resistant polymer barrier engineering and defense contractor qualification protocols. Three-tier pricing structure across high-purity laboratory, certified technical, and standard industrial levels segments buyers by documentation intensity and application criticality. Cost compression in standard-grade volumes intensifies as direct procurement relationships between Mumbai dye houses and Gujarat producers bypass distributor markups. Textile processors exhibit highest price sensitivity due to sodium persulfate substitution economics, while defense contractors absorb premium pricing for decomposition precision.
Supply Chain Analysis
Kazakhstan and South Africa anchor metallurgical-grade chromite feedstock production, constraining merchant dichromate processors without captive mining infrastructure. Ammonium dichromate manufacture draws from chromite ore, sodium dichromate intermediates, and ammonia solution inputs. Single-source vulnerability concentrates in chromite supply, where integrated processors control feedstock access and dictate merchant pricing. Distribution runs through certified chemical distributors for REACH-regulated markets, while direct procurement dominates Indian chemical park clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Indian textile clusters consolidating crystalline-grade procurement through annual volume contracts, fragmenting traditional distributor influence across Asia-Pacific supply tiers.
For Market Incumbents: Shield REACH-compliant certification portfolios against trivalent chromium substitution advances by deepening analytical reagent documentation capabilities. Prioritize BIS certification investment to maintain access to Mumbai and Surat dye house direct procurement relationships. Vertical integration into chromite processing insulates margin structures from Kazakhstan feedstock pricing volatility. For New Entrants and Emerging Players: Lead with high-purity powder grades targeting Japanese electronics laboratories qualifying ultra-low trace-metal specifications for semiconductor contamination protocols. The photographic sensitization niche in German fine art workshops offers penetrable white-space with limited incumbent specialization. Pursue METI-aligned documentation pathways to satisfy Kanto region certificate-of-analysis requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH enforcement stringency and BIS certification proliferation favor suppliers with verified environmental management systems over commodity processors. Target acquisition archetypes include captive chromium chemical producers with downstream formulation licenses and regional technical grade distributors with Indian chemical park proximity. Monitor ECHA substance restriction proposals as inflection indicators for substitution acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Processing | Captive feedstock access insulates LANXESS and BASF from Kazakhstan supply concentration. |
| BIS Certification Investment | Bureau of Indian Standards compliance unlocks direct procurement channels with Gujarat textile clusters. |
| Encapsulated Formulation Development | Polymer barrier engineering addresses moisture resistance requirements for US defense contractors. |
| High-Purity Synthesis Scale-Up | Ultra-low trace-metal production serves Japanese semiconductor contamination testing protocols. |
| Direct Procurement Relationship Formation | Annual volume contracts with Maharashtra chemical parks compress traditional distributor margins. |
Methodological Framework
Desk research of customs trade databases, ECHA substance registration filings, and Bureau of Indian Standards certification records preceded structured interviews with specialty chemical procurement leads, textile dye house operations managers, pyrotechnic formulation engineers, and laboratory reagent distributors. Primary fieldwork combined plant-level capacity assessments with downstream qualification protocol analysis. Secondary validation drew from SEC 10-K chemical segment disclosures, Cefic industry reports, and Indian chemical park development authority publications. Bottom-up volume modeling triangulated against top-down chromite consumption estimates.
Variance decomposition across purity grade, physical form, end-use industry, and regional regulatory cluster dimensions shaped the analytical framework. Segment-level CAGRs derived from elasticity-adjusted demand projections and supply-side capacity constraints. Forecast inputs incorporated REACH restriction timelines, BIS enforcement intensity, and substitution technology performance benchmarks throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable chromite supply concentration, or linear substitution economics would require recalibration. Forecasts reflect assumptions regarding regulatory trajectory and feedstock availability. Recalibration cycles align with material shifts in ECHA substance restriction proposals and Indian chemical park capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Barite Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Methanesulfonic Acid Market