
 Lignin Waste Market | 2026-2036
Lignin Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Lignin Waste Market Foresight
The capital-intensity divergence between integrated pulp-to-lignin operators and standalone biorefinery ventures is unwinding competitive stability across the value chain. Borregaard leverages its Norwegian wood-chemical heritage to sustain captive kraft lignin output with minimal feedstock risk. Stora Enso anchors Nordic supply through mill-integrated biorefinery investments, while Ingevity Corporation competes from a specialty chemicals position in North American automotive binders.
Lignin waste comprises the amorphous phenolic polymer residue isolated from lignocellulosic biomass during pulping or biorefinery operations, typically containing 60–70% carbon, 5–6% hydrogen, and variable methoxyl content depending on extraction severity; its primary commercial purpose centers on replacing fossil-derived phenols, aromatic hydrocarbons, and polyols across adhesive, carbon fiber, and bioplastic formulations. Modified lignin and lignin derivatives capture expanding margin pools as chemical functionalization unlocks higher-value polyurethane and epoxy applications beyond commodity dispersant uses. Natural lignin from kraft and sulfite pulping dominates volume throughput, while synthetic lignin from enzymatic or organosolv routes occupies emerging niches demanding lower sulfur and ash contamination for bioplastics compounding.
The EU Green Deal and REACH framework restrict petrochemical aromatic inputs, directly elevating lignin qualification requirements for construction adhesives and automotive composites entering European supply chains. EPA renewable fuel standard pathways and USDA bio-preferred procurement criteria reinforce North American offtake for certified biobased content in building materials. Stakeholders must monitor evolving ASTM and ISO standardization for lignin-derived carbon fiber precursors, as specification harmonization will determine which producers achieve qualification for aerospace and automotive tier-one supply contracts.
Market Dynamics
The EU Green Deal's binding substitution mandates for petroleum-derived aromatics are forcing lignin qualification protocols to tighten across construction adhesives and automotive composites entering European supply chains. This regulatory compression is restructuring competitive entry barriers.
Growth Catalysts
- REACH aromatic restrictions:The EU chemical framework elevates bio-based binder qualification requirements, directly expanding addressable volume for kraft lignin in plywood and particleboard resins.
- Automotive lightweighting:Carbon fiber precursor demand from EV battery enclosures and structural components pulls lignin-derived PAN alternatives into tier-one supplier qualification pipelines.
- Pulp mill clustering:Nordic and German kraft capacity concentration enables integrated biorefinery economics that standalone ventures cannot replicate.
Market Restraints
- Feedstock sulfur variability:Kraft lignin's residual sulfur content limits qualification for high-purity bioplastics compounding, constraining addressable share of polyol substitution markets.
- Enzymatic route cost structure:Synthetic lignin from organosolv and enzymatic extraction carries 40-60% higher processing overhead versus kraft recovery, pricing it out of commodity dispersant applications.
- Carbon fiber precursor standardization:Absent harmonized ASTM and ISO specifications for lignin-based pitch, aerospace qualification timelines extend unpredictably.
Strategic Opportunities
- USDA BioPreferred procurement:Federal purchasing mandates for certified biobased content in building materials create guaranteed offtake channels for domestic lignin suppliers.
- Polyurethane foam formulations:Modified lignin polyols are penetrating rigid insulation and automotive seating applications where petrochemical aromatic polyols face carbon accounting pressure.
- India PLI scheme alignment:Chemical sector production-linked incentives for bio-based feedstocks could anchor South Asian lignin valorization infrastructure around Maharashtra and Gujarat pulp clusters.
Industry Challenges
- Process analytical chemistry talent:Lignin functionalization R&D requires scarce expertise in phenolic polymer characterization and reproducible batch-to-batch quality control.
- Biorefinery capex intensity:Front-end fractionation and purification equipment for food-grade lignin specifications demands 18-24 month deployment timelines with limited project finance availability.
- Legacy adhesive formulation lock-in:Construction chemical customers maintain decades-old phenol-formaldehyde recipes, requiring extensive co-development cycles to validate lignin substitution ratios without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignin Waste Market |
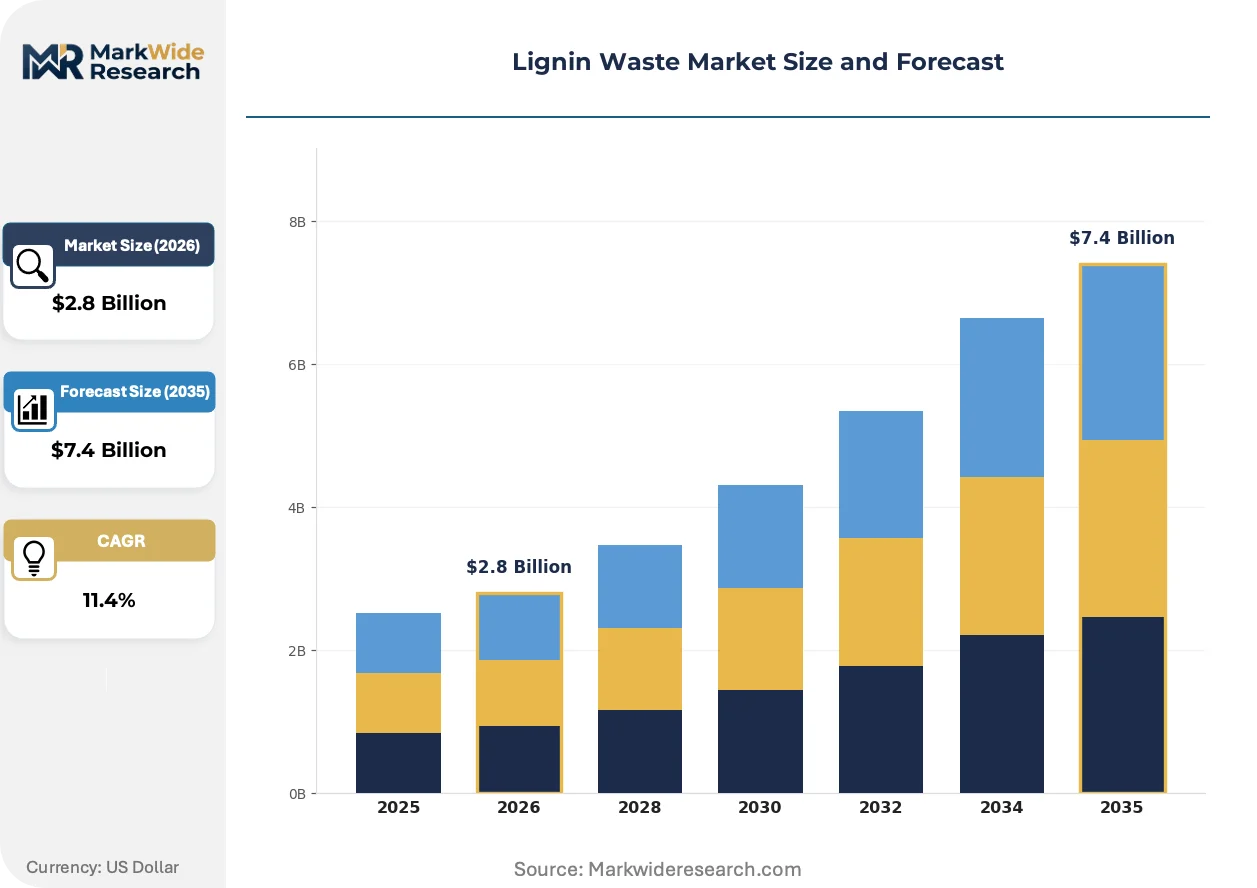
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
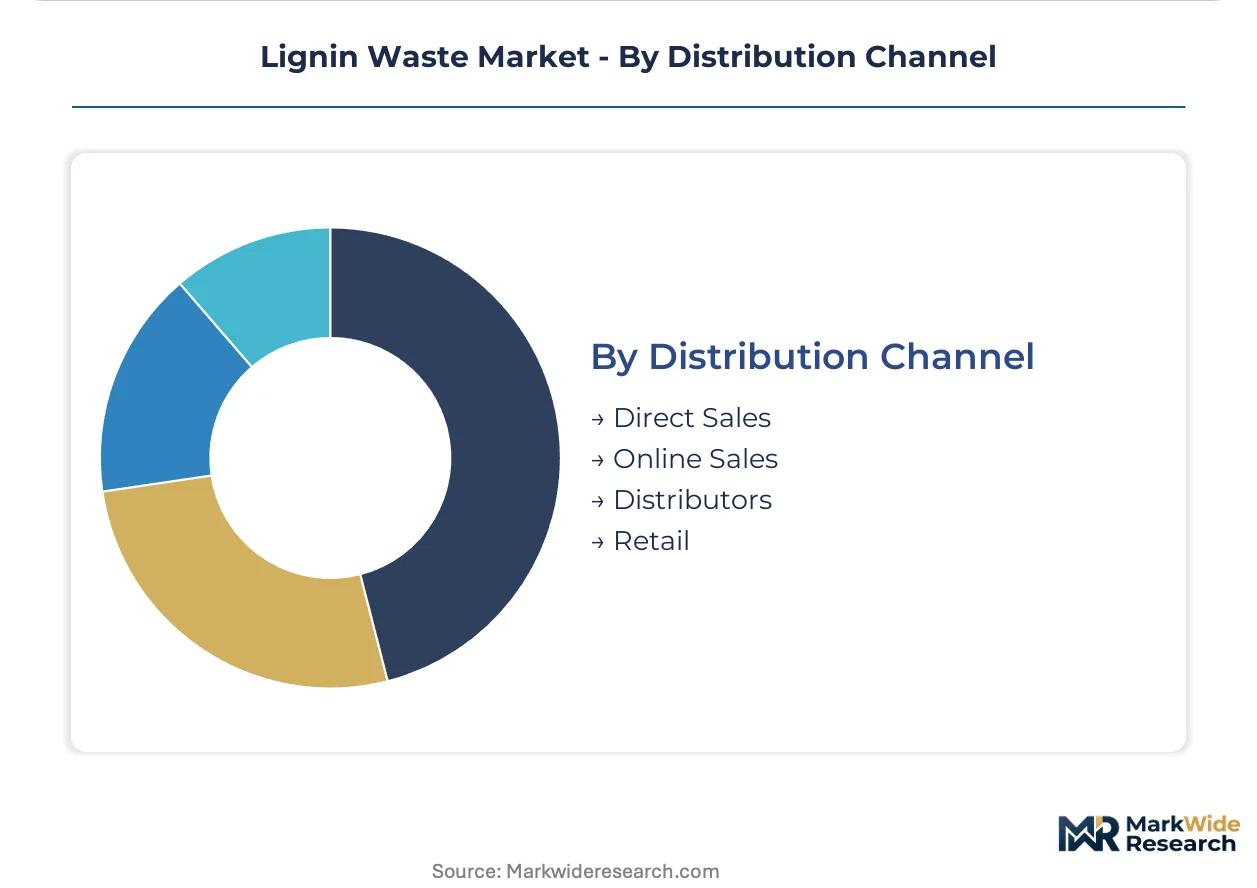
| Segmentation | Product Type: Natural Lignin, Synthetic Lignin, Modified Lignin, Lignin Derivatives Application: Adhesives, Bioplastics, Construction Materials, Animal Feed End User: Agriculture, Construction, Automotive, Chemical Industry Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Borregaard, Domtar Corporation, Stora Enso, Ingevity Corporation, Sappi, Rayonier Advanced Materials, WestRock Company, Nippon Paper Industries Co., Ltd., Dallas Group of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignin Waste Market Shifts & Advancements
Process intensification and molecular characterization advances are splitting the lignin value chain into distinct quality tiers, with implications for which producers capture carbon fiber precursor margins versus commodity chemical offtake.
Organosolv extraction technology is bifurcating the market into sulfur-free lignin streams suitable for bioplastics compounding and traditional kraft lignin locked into lower-value dispersant and binder applications. Automotive composite manufacturers in Germany and Japan are qualifying organosolv grades for carbon fiber precursor production at pilot scale, while construction adhesive formulators absorb kraft volumes for phenol substitution. This quality stratification is compressing margins for unintegrated kraft operators unable to fund fractionation upgrades.
The EU F-Gas Regulation and REACH authorization procedures are accelerating substitution timelines for petrochemical aromatic inputs in polyurethane and epoxy formulations. Industrial adhesive producers face 2027-2030 phase-out deadlines for certain phenol derivatives, forcing reformulation partnerships with lignin suppliers capable of consistent methoxyl content and molecular weight distribution. German construction chemical leaders are front-loading qualification spend to secure approved supplier status before authorization cliffs.
Automotive OEMs are consolidating carbon fiber procurement around vertically integrated material suppliers capable of certifying lifecycle carbon intensity from feedstock to component. This buyer concentration is displacing spot-market lignin pitch transactions in favor of multi-year tolling agreements with pulp-integrated biorefineries. The shift is most visible in Bavaria and Baden-Württemberg, where Mercedes-Benz and BMW supplier parks sit within 200 kilometers of Schwarzheide and Halle chemical processing infrastructure.
Lignin Waste Market Segmentation

Lignin waste segmentation reflects divergent margin capture between commodity kraft recovery and high-purity functionalized grades. Quality tier stratification determines which producers access carbon fiber precursor premiums versus dispersant and binder commodity pools.
Product Type:
Margin concentration shifts toward sulfur-free and chemically modified grades as bioplastics compounding specifications tighten.
- Natural Lignin:Recovered through kraft and sulfite pulping with 60–70% carbon content and variable residual sulfur. German plywood and particleboard formulators absorb volumes for phenol-formaldehyde substitution under EU Green Deal aromatic restrictions.
- Modified Lignin:Functionalized through hydroxymethylation or phenolation to achieve reactive hydroxyl groups for polyurethane and epoxy systems. Automotive seating and rigid insulation producers in Baden-Württemberg are qualifying modified polyols for carbon accounting compliance.
- Synthetic Lignin:Enzymatic or organosolv routes yield low-ash, low-sulfur streams for bioplastics compounding. Premium pricing reflects 40–60% processing overhead versus kraft recovery.
- Lignin Derivatives:Further processed into dispersants, binders, and surfactants for construction and agricultural chemicals. Volume throughput concentrates in Nordic pulp mill clusters.
The dominant share belongs to Natural Lignin, while Modified Lignin is closing the gap fastest.
Application:
End-use profitability splits between reformulation-mandated construction chemicals and emerging automotive composite qualification pipelines.
- Adhesives:Phenol substitution in plywood, particleboard, and engineered wood products. REACH authorization deadlines for petrochemical aromatics are forcing German construction chemical leaders into front-loaded supplier qualification spend.
- Bioplastics:Compounding into polyhydroxyalkanoates and polylactic acid blends. Organosolv lignin grades from Schwarzheide processing infrastructure are penetrating packaging films requiring food-contact compliance.
- Construction Materials:Cement additives, concrete plasticizers, and asphalt modifiers. Kraft lignin dispersants face margin compression from unintegrated operators unable to fund fractionation upgrades.
- Animal Feed:Binder and pelletizing aid applications in compound feed manufacturing. Regulatory approval variability across national veterinary authorities constrains geographic expansion.
Adhesives commands volume leadership, though Bioplastics exhibits the steepest expansion trajectory as sulfur-free specifications proliferate.
End User:
Customer concentration patterns favor construction and automotive sectors with binding sustainability procurement mandates.
- Construction:Wood panel manufacturers and engineered timber producers driving phenol-formaldehyde reformulation. EU F-Gas Regulation and REACH phase-out deadlines compress substitution timelines.
- Automotive:Tier-one suppliers qualifying lignin-derived carbon fiber precursors for EV battery enclosures and structural lightweighting. Bavarian OEM supplier parks within 200 kilometers of chemical processing infrastructure anchor demand geography.
- Chemical Industry:Polyol and aromatic intermediate producers seeking bio-based feedstock alternatives. Consistent methoxyl content and molecular weight distribution requirements filter supplier qualification.
- Agriculture:Fertilizer coating, pesticide dispersion, and soil amendment applications. Price sensitivity limits penetration to commodity lignin grades with minimal functionalization.
Construction retains the largest installed base, yet Automotive is gaining share fastest through multi-year tolling agreements with pulp-integrated biorefineries.
Distribution Channel:
Channel economics favor direct relationships for specification-grade material while distributors handle commodity volumes.
- Direct Sales:Multi-year supply agreements between integrated biorefineries and automotive tier-one suppliers. Lifecycle carbon intensity certification requirements displace spot-market transactions.
- Distributors:Regional chemical distributors stocking kraft lignin for construction adhesive formulators. Inventory pooling reduces working capital burden for smaller plywood and particleboard producers.
- Online Sales:Sample procurement and small-volume orders for R&D qualification. Limited to laboratory-scale quantities pending specification validation.
- Retail:Minimal penetration; agricultural binder applications through farm supply cooperatives represent niche volume.
Direct Sales captures premium-tier transactions, while Distributors handles commodity volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit low price elasticity for sulfur-free organosolv grades, while Indian and Brazilian construction formulators remain highly sensitive to kraft lignin feedstock costs. This demand-elasticity contrast shapes regional investment priorities across the value chain.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are qualifying lignin-derived carbon fiber precursors for EV battery enclosures under EU Green Deal mandates. REACH aromatic restrictions compress substitution timelines for phenol-formaldehyde adhesives. The Schwarzheide and Halle chemical processing clusters anchor integrated biorefinery economics with pulp mill proximity.
United States
USDA BioPreferred procurement mandates drive federal building material offtake for certified biobased content. EPA renewable fuel standard pathways reinforce lignin qualification for construction adhesive applications. Southern pulp mill corridors in Georgia and Alabama enable kraft lignin recovery at scale for domestic dispersant markets.
Japan
METI carbon neutrality roadmaps accelerate automotive lightweighting material substitution from petroleum-based precursors. JIS standardization efforts for lignin-derived carbon fiber precursors are advancing through tier-one supplier qualification pipelines. The Chubu/Nagoya industrial zone concentrates chemical processing infrastructure for organosolv lignin purification.
India
Chemical sector PLI scheme incentives could anchor bio-based feedstock infrastructure around Maharashtra and Gujarat pulp clusters. Price-sensitive construction adhesive formulators prioritize low-cost kraft lignin for phenol substitution in plywood manufacturing. Domestic veterinary approval variability constrains animal feed binder expansion across state regulatory boundaries.
Sweden
Nordic kraft pulp capacity concentration enables mill-integrated biorefinery investments with minimal feedstock logistics overhead. EU F-Gas Regulation phase-out deadlines force reformulation partnerships for rigid insulation polyols. Stora Enso's biorefinery assets in central Sweden exemplify captive lignin valorization at industrial scale.
Lignin Waste Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the lignin waste value chain. Integrated pulp-to-lignin operators command feedstock security and scale economies, while standalone biorefinery ventures compete on sulfur-free purity and functionalization expertise. The market structure splits between Nordic wood-chemical heritage groups, North American specialty chemical positioned players, and Asian pulp-integrated conglomerates. Dominant competitive moves include backward integration into captive pulp supply and multi-year tolling agreements with automotive tier-one suppliers.
Among Nordic wood-chemical specialists, Borregaard and Stora Enso occupy positions defined by mill-integrated biorefinery assets and minimal feedstock risk exposure. Ingevity Corporation represents the North American specialty chemicals archetype competing from a formulated binders position rather than upstream lignin recovery. These three companies exemplify the strategic divergence between pulp-originated cost leadership and downstream functionalization margin capture.
| Leading Market Players |
|---|
| Borregaard |
| Domtar Corporation |
| Stora Enso |
| Ingevity Corporation |
| Sappi |
| Rayonier Advanced Materials |
| WestRock Company |
| Nippon Paper Industries Co., Ltd. |
| Dallas Group of America |
| Others |
Supply & Pricing Matrix
Mill-integrated biorefinery scale in Germany and Sweden compresses unit recovery costs below standalone organosolv ventures, establishing price floors that unintegrated kraft operators cannot match. This concentration of captive pulp-to-lignin capacity simultaneously elevates sulfur-free grade premiums and erodes commodity dispersant margins.
Pricing Analysis
Long-term tolling agreements with automotive tier-one suppliers anchor lifetime value beyond spot transactions. Three-tier pricing structure across premium organosolv, standard modified kraft, and economy unprocessed grades reflects sulfur content and methoxyl consistency. Cost compression in commodity kraft dispersants intensifies as Nordic pulp mill clusters expand recovery capacity. Construction adhesive formulators in India exhibit highest price sensitivity, while German automotive OEMs accept premiums for REACH-compliant carbon fiber precursors.
Supply Chain Analysis
Germany, Sweden, and the United States anchor lignin waste supply through kraft pulp mill concentration and integrated biorefinery investments. Feedstock draws from softwood and hardwood pulping operations, with sulfur recovery systems and fractionation equipment as critical processing inputs. Single-source vulnerability runs through Schwarzheide and Halle chemical clusters for high-purity organosolv grades. Distribution runs through direct sales for specification-grade automotive offtake and regional distributors for construction adhesive commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenolic polymer functionalization expertise functions as the binding constraint on margin capture, with batch-to-batch quality control capability separating qualified suppliers from commodity players.
For Market Incumbents: Shield margin position by deepening backward integration into captive pulp supply in Nordic mill clusters and accelerating REACH pre-registration for modified lignin polyols before authorization cliffs. Organosolv purity upgrades represent the critical defensive lever against sulfur-free grade substitution. For New Entrants and Emerging Players: Anchor in Maharashtra and Gujarat pulp corridors under India's PLI scheme alignment for bio-based feedstocks, targeting price-sensitive construction adhesive formulators with unprocessed kraft lignin. USDA BioPreferred certification offers the most penetrable qualification pathway for federal procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pulp-integrated biorefineries with multi-year automotive tolling agreements. Long-term viability centers on sulfur-free fractionation capability and methoxyl content consistency. Watch ASTM/ISO harmonization timelines for lignin-derived carbon fiber precursors as inflection signal for aerospace qualification ramps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Supply | Borregaard and Stora Enso leverage Norwegian and Swedish wood-chemical heritage to eliminate feedstock price volatility. |
| REACH Pre-Registration for Modified Polyols | German construction chemical leaders secure approved supplier status before EU F-Gas Regulation phase-out deadlines. |
| Organosolv Purity Upgrade Investment | Automotive OEMs in Bavaria qualify sulfur-free grades for EV battery enclosure carbon fiber precursors. |
| USDA BioPreferred Certification | Federal procurement mandates guarantee offtake channels for domestic lignin suppliers in building materials. |
| Multi-Year Tolling Agreement with Tier-One Suppliers | Lifecycle carbon intensity certification displaces spot-market transactions in favor of supply security. |
Research Methodology
Cross-validation between executive interviews at biorefinery operators and trade data from chemical customs records anchors the qualitative findings. Primary discussions with pulp mill managers, construction adhesive procurement leads, automotive tier-one supplier sustainability officers, and phenolic polymer R&D directors combined with secondary validation through SEC filings, Cefic industry reports, and EPA renewable fuel standard pathway documentation. Bottom-up capacity assessments and top-down end-use demand estimates complete the triangulation.
Sensitivity analysis across sulfur content thresholds, methoxyl distribution variability, and automotive qualification timeline scenarios tests forecast robustness. Segmentation modeling spans product type tiers, application profitability profiles, end-user concentration patterns, and regional regulatory clusters. CAGRs derive from installed biorefinery capacity expansion schedules and substitution elasticity assumptions for petrochemical aromatic inputs. Carbon intensity accounting standards and REACH authorization cliff calendars function as key forecast inputs.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and pulp mill capacity utilization assumptions; material deviation in automotive lightweighting adoption or biorefinery project finance availability would warrant model refresh. Recalibration cycles align with material shifts in ASTM/ISO standardization progress and PLI scheme disbursement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
India Lime Market