
 Palmitic Acid Market | 2026-2036
Palmitic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Palmitic Acid Market Outlook
Multi-source procurement from Southeast Asian oleochemical clusters is expanding as personal care and food additive buyers diversify away from single-origin palm oil dependence. Wilmar International leverages integrated plantation-to-oleochemical infrastructure across Indonesia and Malaysia. IOI Oleochemicals anchors its position through specialized flake and powder production for European cosmetic formulators. KLK Oleo competes on backward integration into Malaysian palm oil milling.
Palmitic acid is a saturated C16 fatty acid derived primarily from palm oil through fractional distillation and hydrolysis, typically achieving 95-98% purity for industrial grades and higher specifications for pharmaceutical and cosmetic applications. It functions as a surfactant precursor, emulsifier base, and hardness agent across formulations. The powder and flakes product types dominate current volume flows, with powder grades capturing margin pools in pharmaceutical and nutraceutical channels where compounding precision commands premium positioning. Liquid formats serve industrial alkyd resin and lubricant applications where bulk handling economics outweigh purification costs. The cosmetics and food additives application segments exhibit the strongest structural pull, driven by clean-label emulsifier substitution and plant-based formulation trends across European and North American personal care markets.
REACH registration requirements in Europe and FDA food contact substance notifications in the United States enforce chain-of-custody documentation and residual solvent limits that elevate compliance costs for non-integrated traders. Indonesia's national standards body and Malaysia's Department of Standards administer halal certification and sustainability criteria that increasingly determine market access for Southeast Asian exports. Stakeholders must monitor emerging deforestation-free supply chain mandates and their interaction with existing purity specifications to anticipate procurement qualification shifts.
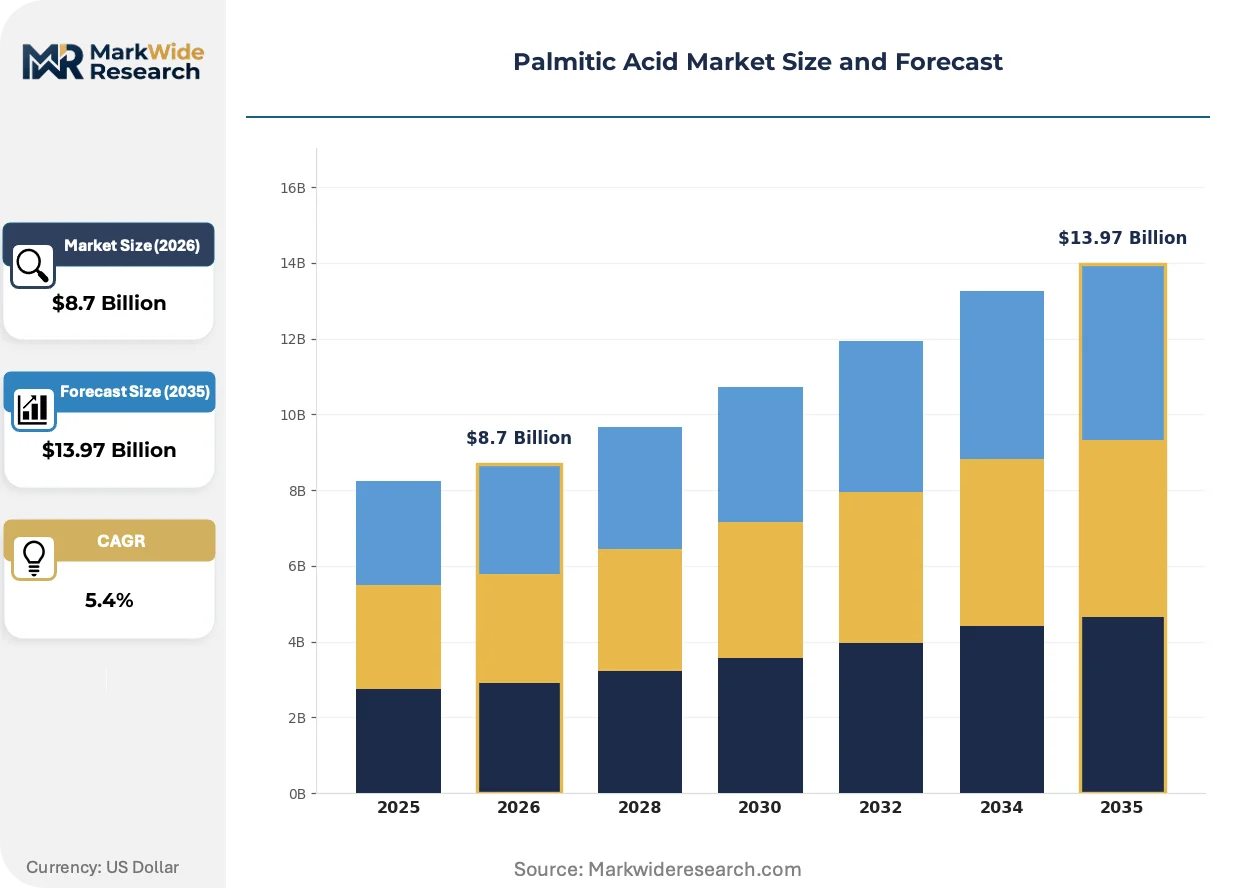
Market Dynamics
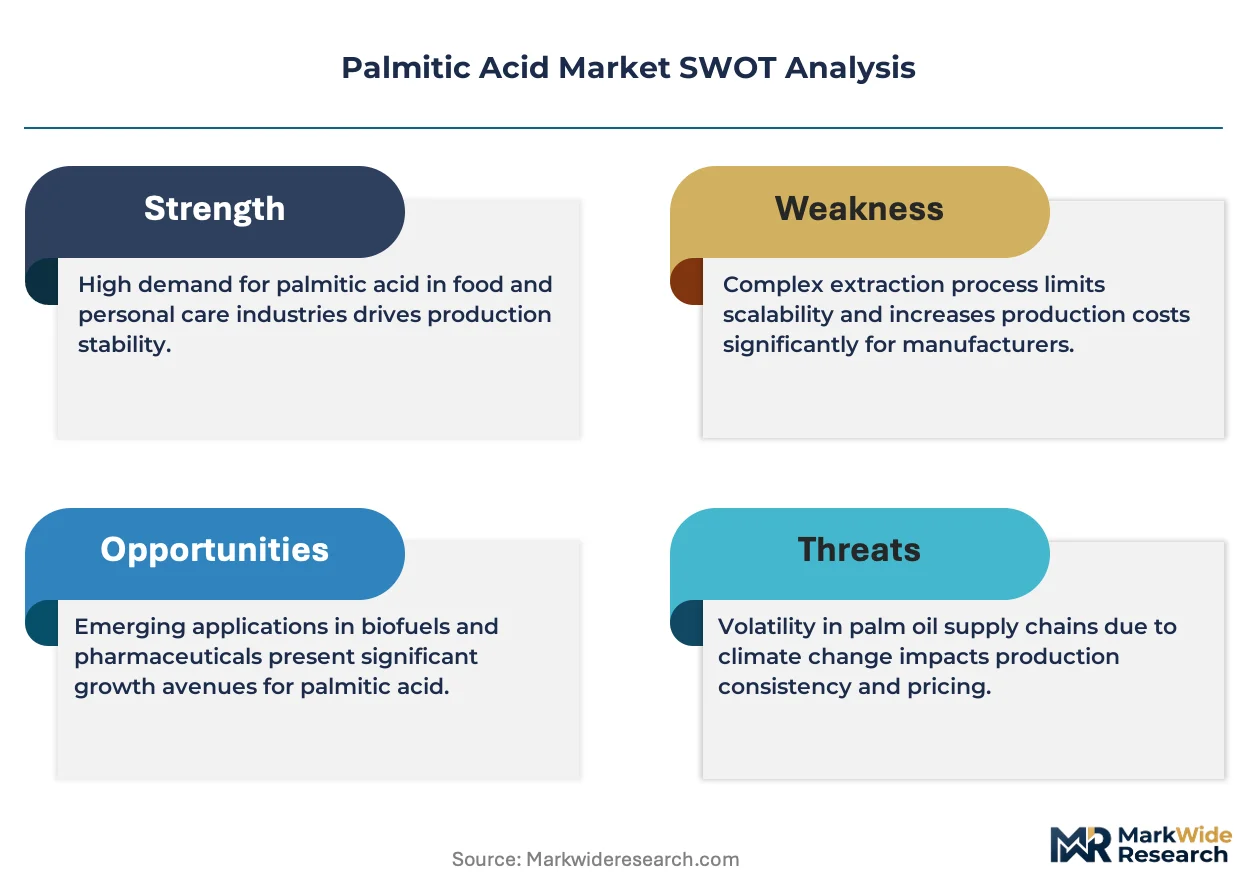
Integrated oleochemical clusters in Indonesia and Malaysia are consolidating captive palm oil processing, compressing margins for non-integrated traders while elevating purity specifications demanded by European cosmetic formulators under REACH compliance.
Growth Catalysts
- Clean-label emulsifier substitution:European and North American personal care brands are reformulating away from petrochemical surfactants toward plant-based palmitic acid derivatives in flake and powder grades.
- REACH registration requirements:Chain-of-custody documentation mandates in Europe are filtering out speculative traders and rewarding integrated producers with certified sustainability credentials.
- Halal certification expansion:Indonesia's national standards body and Malaysia's Department of Standards are extending halal criteria to cosmetic-grade supply chains, opening access to Muslim-majority consumer markets.
Market Restraints
- Crude palm oil price volatility:Input cost swings at Malaysian and Indonesian plantation gates transmit directly to fatty acid fractionation economics, squeezing working capital for non-hedged processors.
- Single-origin supply concentration:Over 80% of global palm oil production concentrates in Indonesia and Malaysia, creating geographic risk exposure for buyers seeking deforestation-free certification.
- Stearic acid substitution in lubricants:Industrial alkyd resin formulators are blending higher stearic content to modify hardness profiles, compressing palmitic acid volume in metalworking applications.
Strategic Opportunities
- Indian pharmaceutical compounding:CDSCO-registered drug manufacturers are qualifying high-purity powder grades for tablet lubricant and sustained-release matrix applications, creating a premium channel outside saturated cosmetics.
- EU Green Deal bio-based mandates:Renewable content thresholds in packaging and personal care are accelerating demand for mass-balance certified palmitic acid with segregated supply chain documentation.
- Direct-to-formulator digital platforms:Specialty chemical distributors are building e-procurement portals that bypass traditional oleochemical traders, capturing margin through technical service bundling.
Industry Challenges
- Fractionation technician scarcity:Malaysian and Indonesian oleochemical plants face recruitment gaps for process engineers skilled in molecular distillation and crystallization optimization.
- Deforestation-free audit complexity:Satellite-based supply chain verification systems require multi-year traceability data that many smallholder-linked mills cannot yet provide, delaying certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palmitic Acid Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Granules, Liquid Application: Cosmetics, Pharmaceuticals, Food Additives, Animal Feed End User: Food & Beverage, Personal Care, Industrial, Nutraceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | IOI Oleochemicals, Emery Oleochemicals, Wilmar International, BASF SE, AkzoNobel, KLK Oleo, VVF Ltd, ADM, Musim Mas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palmitic Acid Market Strategic Shifts
Fractionation technology advances and regulatory transparency mandates are compressing the gap between industrial-grade commodity supply and pharmaceutical-grade purity requirements, reshaping how buyers qualify suppliers.
Enzymatic interesterification is expanding into cosmetic-grade palmitic acid production, enabling lower-temperature processing that preserves color and odor specifications. European personal care formulators are adopting enzymatically refined grades for sensitive-skin emulsions. This technology is expanding into premium positioning previously captured by synthetic C16 alternatives.
REACH registration requirements are tightening residual solvent limits and elevating analytical documentation burdens for imported cosmetic-grade material. European formulators are consolidating supplier lists to integrated producers with in-house analytical capabilities. Pharmaceutical and nutraceutical applications face the steepest compliance cost escalation.
Buyers are consolidating annual contracts around integrated Southeast Asian producers with captive plantation supply, displacing spot-market purchasing through Singapore trading houses. Large personal care multinationals are embedding sustainability auditors directly into supplier qualification. This pattern is most visible in German and French cosmetic manufacturing clusters.
Palmitic Acid Market Segmentation
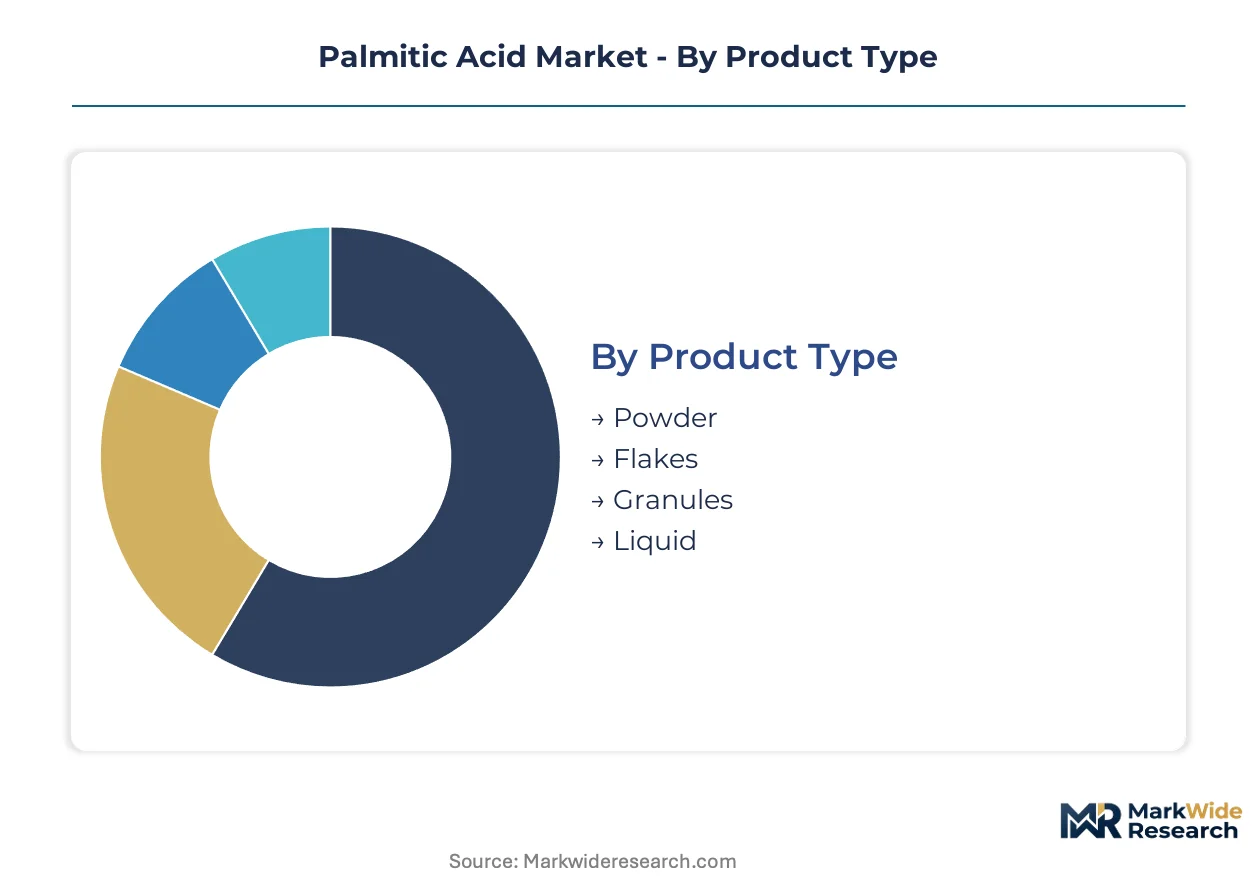
Palmitic acid segmentation tracks the tension between purification economics and formulation specificity. Powder and flake grades command distinct margin pools based on residual solvent limits and particle size distribution, while application-driven demand splits between cosmetic emulsifier precision and industrial bulk handling.
Product Type:
Fractionation technology separates grades by crystallization behavior and downstream handling requirements.
- Powder:Spray-dried or milled material achieves sub-100 micron particle size for pharmaceutical tablet lubricants and cosmetic compounding. CDSCO-registered Indian drug manufacturers qualify this grade for sustained-release matrix applications where flowability and compression uniformity are critical.
- Flakes:Solidified prills or cast flakes dominate Southeast Asian personal care manufacturing. Indonesian and Malaysian emulsifier producers specify flake-grade material for melt-processing into glyceryl stearates and sorbitan esters, with REACH-compliant documentation filtering supplier pools.
- Granules:Intermediate particle size bridges powder flowability and flake handling density for regional compounders.
- Liquid:Unfractionated or minimally refined C16 stream serves alkyd resin and lubricant applications where thermal stability outweighs odor and color specifications.
Mature deployment sits with Flakes. Newer deployment is concentrated in Powder.
Application:
Regulatory stringency and formulation complexity split demand across purity tiers.
- Cosmetics:Emulsifier base for creams, lotions, and color cosmetics requires low iodine value and peroxide specifications. European formulators under ECHA guidance are consolidating supplier lists to integrated producers with mass-balance certification.
- Pharmaceuticals:Excipient-grade material for tablet lubricants and suppository bases demands USP-NF or EP compliance with residual solvent documentation. The steepest expansion trajectory sits here as generic drug manufacturing shifts to India and Southeast Asia.
- Food Additives:E570 additive status in EU and GRAS recognition in US markets drive emulsifier demand for bakery and confectionery.
- Animal Feed:Energy-dense fat source for ruminant and poultry rations competes on cost per metabolizable energy unit.
Established volume anchors in Food Additives. Premium positioning is migrating toward Pharmaceuticals.
End User:
Customer technical capability and procurement scale determine grade qualification pathways.
- Food & Beverage:Multinational manufacturers specify mass-balance certified material for clean-label emulsifier claims.
- Personal Care:European and North American brands embed sustainability auditors into supplier qualification, favoring integrated Indonesian and Malaysian producers.
- Industrial:Alkyd resin and metalworking fluid formulators prioritize bulk handling economics over purification.
- Nutraceuticals:Softgel and lipid-based drug delivery systems require low-trans, low-oxidation specifications.
Procurement consolidation is most advanced in Personal Care. Technical qualification barriers are highest in Nutraceuticals.
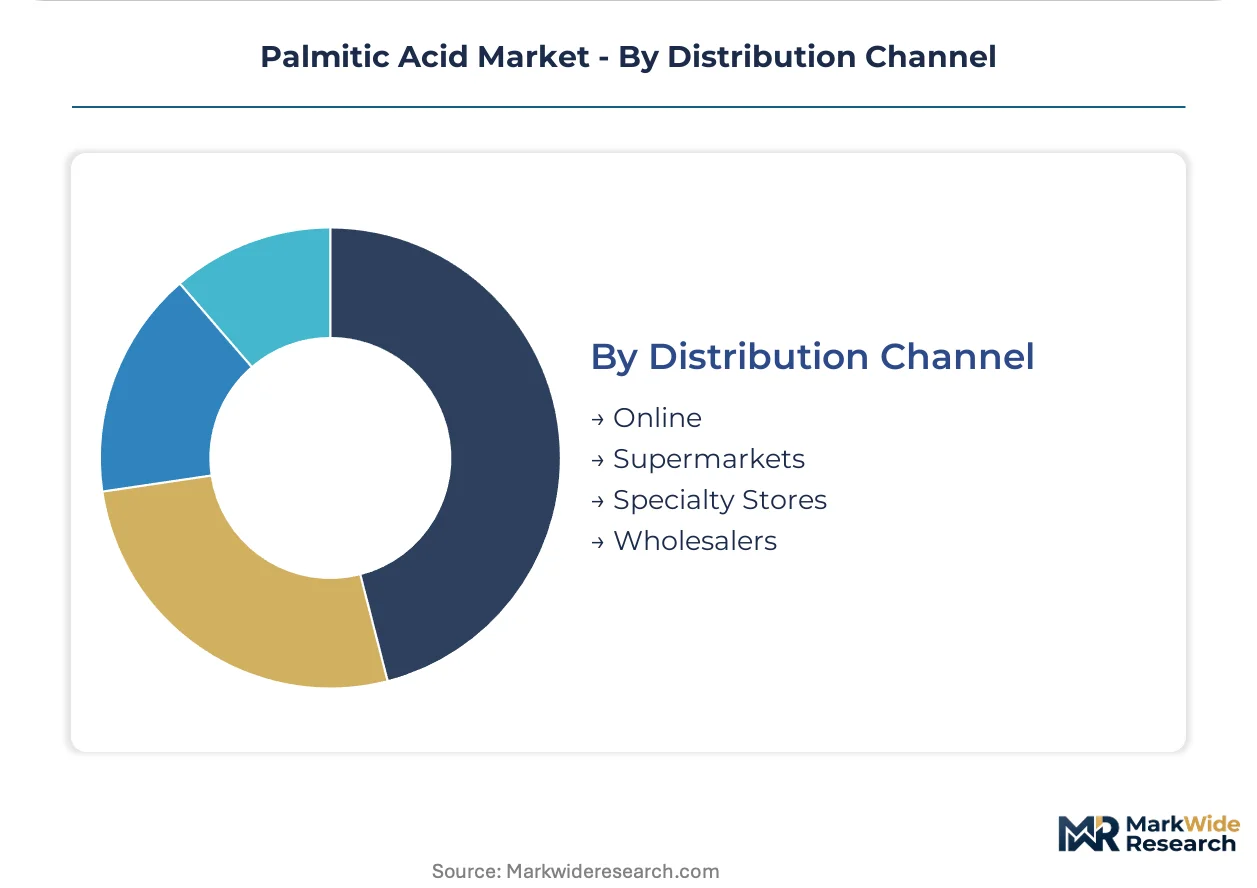
Distribution Channel:
Channel selection tracks order size, technical service requirements, and geographic proximity to oleochemical clusters.
- Online:Specialty chemical distributors are building e-procurement portals that bypass Singapore trading houses for mid-volume personal care compounders.
- Supermarkets:Limited to consumer-facing fatty acid derivatives rather than industrial-grade material.
- Specialty Stores:Regional chemical distributors serve small-batch cosmetic formulators with technical service bundling.
- Wholesalers:Traditional oleochemical traders aggregate spot-market volumes for industrial buyers with limited specification requirements.
Channel leverage concentrates in Wholesalers. Digital displacement is accelerating in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian and Malaysian palm oil plantations supply over 80% of global feedstock for palmitic acid fractionation, concentrating downstream oleochemical processing in Southeast Asian industrial corridors.
Indonesia
Personal care manufacturers in Jakarta and Surabaya drive flake-grade consumption for emulsifier production. The national standards body administers halal certification extensions to cosmetic-grade supply chains. Dumai and Belawan oleochemical clusters deepen captive processing of plantation-origin crude palm oil.
Malaysia
European cosmetic formulators source powder-grade material from Port Klang and Kuantan processing hubs. The Department of Standards enforces sustainability criteria that determine export market access. Klang Valley integrated producers consolidate backward integration into palm oil milling operations.
China
Domestic alkyd resin manufacturers absorb liquid-grade volumes for industrial coating applications. Evolving GB standards under SAMR reshape purity specifications for imported cosmetic-grade supply. Guangdong and Jiangsu oleochemical processors expand fractional distillation capacity for pharmaceutical-grade output.
India
CDSCO-registered drug manufacturers qualify high-purity powder grades for tablet lubricant applications. FSSAI oversight of food additive specifications constrains import channel qualification. Mumbai and Ahmedabad specialty chemical distributors build direct-to-formulator procurement portals.
Germany
Personal care multinationals in North Rhine-Westphalia embed sustainability auditors into supplier qualification workflows. ECHA administers REACH registration requirements that filter speculative traders from cosmetic-grade supply chains. Cologne and Düsseldorf cosmetic manufacturing clusters consolidate annual contracts around mass-balance certified Southeast Asian producers.
Palmitic Acid Market Competitive Environment
Capacity expansion dominates the current landscape as integrated Southeast Asian producers scale fractional distillation and crystallization infrastructure. The vendor base separates into plantation-linked oleochemical majors, European specialty chemical houses, and regional trading intermediaries. Three archetypes prevail: backward-integrated plantation processors, purity-focused pharmaceutical-grade specialists, and commodity-scale industrial suppliers. Geographic expansion and sustainability certification acquisition represent the two most visible competitive moves.
Within the plantation-integrated tier, Wilmar International and KLK Oleo exemplify the archetype of captive feedstock control. IOI Oleochemicals occupies a position representing specialized flake and powder production for regulated European markets. These three anchors illustrate how supplier consolidation rewards integrated infrastructure over trading-dependent models.
| Leading Market Players |
|---|
| IOI Oleochemicals |
| Emery Oleochemicals |
| Wilmar International |
| BASF SE |
| AkzoNobel |
| KLK Oleo |
| VVF Ltd |
| ADM |
| Musim Mas |
| Others |
Value Chain & Pricing Dynamics
Family-owned plantation conglomerates across Indonesia and Malaysia anchor feedstock ownership, translating captive crude palm oil supply into pricing discipline that resists spot-market volatility while compressing margins for non-integrated traders dependent on open-market procurement.
Pricing Analysis
Warranty and certification bundling separates integrated producers from speculative traders. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels reflects purity specifications and documentation depth. Cost compression in flake-grade supply is intensifying because Indonesian oleochemical clusters are expanding captive fractionation capacity. Industrial alkyd resin formulators exhibit the highest price sensitivity, while European cosmetic manufacturers prioritize mass-balance certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian plantation supply, which feeds over 80 percent of global palmitic acid fractionation. The chain draws from crude palm oil, specialized crystallization equipment, and analytical testing services. Commodity price volatility at plantation gates creates working capital stress for non-hedged processors. Distribution runs through Singapore trading houses for spot volumes and direct annual contracts for qualified personal care multinationals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration requirements erect a documentation barrier that filters speculative traders and rewards integrated producers with in-house analytical capabilities.
For Market Incumbents: Acquire satellite-based traceability systems to preempt deforestation-free audit demands from European cosmetic formulators. Expand enzymatic interesterification capacity in Dumai and Belawan clusters to capture premium positioning in sensitive-skin emulsions. Stearic acid substitution in metalworking fluids threatens volume; counter by embedding technical service teams directly into Indian pharmaceutical compounders. For New Entrants and Emerging Players: Enzymatic refining technology offers a technology-first wedge against established fractional distillation incumbents. Target CDSCO-registered Indian drug manufacturers seeking high-purity powder grades for tablet lubricant applications, a segment where qualification timelines deter commodity traders. Lead with direct-to-formulator digital platforms that bundle technical documentation and bypass Singapore trading intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor Malaysian mid-cap oleochemical specialists with partial backward integration into palm oil milling. Long-term viability hinges on sustainability certification acquisition ahead of EU Green Deal bio-based mandate enforcement. Watch for satellite-verification system deployment rates among smallholder-linked mills as the inflection indicator for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Milling | Klang Valley producers secure captive feedstock supply against crude palm oil price swings at plantation gates. |
| Enzymatic Interesterification Capacity Buildout | Lower-temperature processing preserves color and odor specifications for European sensitive-skin emulsion formulators. |
| Mass-Balance Certification Acquisition | Segregated supply chain documentation satisfies EU Green Deal renewable content thresholds in personal care. |
| Direct-to-Formulator Digital Platform Launch | E-procurement portals bypass Singapore trading houses and capture margin through technical service bundling. |
| Indian Pharmaceutical Qualification Program | CDSCO-registered drug manufacturers create premium powder-grade demand outside saturated cosmetics channels. |
Study Parameters
Independent corroboration across plant managers at Indonesian and Malaysian oleochemical facilities, procurement leads at European personal care multinationals, and distribution channel partners in Singapore underwrites the qualitative findings. Secondary validation draws from REACH registration databases, Malaysian Department of Standards sustainability criteria filings, and customs trade data for fatty acid fractionation equipment imports. Bottom-up volume estimates from individual production facilities triangulate against top-down demand aggregation across cosmetic, pharmaceutical, and food additive end-uses.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchor the forecast window across the analysis window. The analytical framework models grade tier, end-use industry, and regional production hub as primary segmentation dimensions. CAGRs derive from elasticity-adjusted demand projections incorporating crude palm oil price trajectory assumptions and regulatory compliance cost escalations.
Several conditions sit outside the modeled scope, including sudden deforestation-free mandate acceleration, breakthrough synthetic C16 alternatives, and geopolitical disruption to Malacca Strait logistics corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Barite Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Barium Sulphate Market