
 Electronic Batio3 Powder Market | 2026-2036
Electronic Batio3 Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Batio3 Powder Market Insights
Particle size distribution tolerances in multilayer ceramic capacitors is narrowing below 100 nanometers for dielectric layers, forcing powder suppliers to retool synthesis and classification equipment. Sakai Chemical leverages hydrothermal reactor networks across Osaka Prefecture to sustain consistent nano powder output. Nippon Chemical anchors its position through captive control over barium carbonate precursor supply. Fuji Titanium competes on spray-dried granule morphology optimized for thin-film tape casting.
Electronic BaTiO3 powder is a perovskite-structured ceramic material synthesized via solid-state reaction, hydrothermal processing, or oxalate co-precipitation, with dielectric constants exceeding 1,000 and Curie points near 120°C enabling ferroelectric phase transitions. Manufacturers engineer particle sizes from sub-100 nm for MLCC dielectrics to micron-scale grades for piezoelectric actuator substrates. Nano powder commands the steepest technical qualification barriers and tightest supplier lists among capacitor OEMs. Capacitor applications absorb the dominant volume share, though piezoelectric device grades in automotive injection systems are expanding fastest on precision fuel efficiency mandates. Bulk powder for conventional ceramic substrates remains a mature margin pool with limited differentiation.
Japan's METI enforces JIS standards on electronic ceramic powder purity and trace metal limits, while China's SAMR administers GB standards governing titanate powder specifications for domestic MLCC supply chains. REACH registration requirements in Europe constrain raw material sourcing flexibility for exporters serving EMA-regulated medical device capacitor applications. Stakeholders must monitor evolving halogen-free dielectric mandates and RoHS recast timelines to anticipate reformulation requirements and qualification cycles.
Market Dynamics
Nano-grade powder qualification barriers are consolidating supplier relationships around hydrothermal synthesis mastery, as MLCC dielectric layer thickness requirements compress below 100 nanometers and capacitor OEMs reduce approved vendor lists to single-digit counts.
Growth Catalysts
- Water-based synthesis methods:China's MEE emissions standards and dual carbon goals are forcing domestic producers to abandon solid-state reaction processes. This regulatory pressure is accelerating technical upgrades toward lower-carbon hydrothermal production.
- Piezoelectric actuator substrates:Automotive fuel injection systems demand micron-scale BaTiO3 grades with precise grain morphology. Precision fuel efficiency mandates in passenger vehicle powertrains are pulling volume into this application category.
- Kansai industrial corridor concentration:Osaka Prefecture hosts integrated precursor-to-powder refining networks. Proximity of barium carbonate processing to hydrothermal reactor clusters reduces logistics friction for nano-grade output.
Market Restraints
- Barium carbonate supply concentration:Captive control over carbonate precursor supply by integrated Japanese producers limits independent powder manufacturers' margin flexibility and input security.
- REACH registration complexity:European ECHA requirements for titanate powder exports constrain raw material sourcing flexibility for medical device capacitor applications serving EMA-regulated markets.
- Particle size distribution tolerances:Sub-100 nanometer dielectric layer specifications create yield losses in classification equipment, compressing effective production rates for qualified powder output.
Strategic Opportunities
- Halogen-free dielectric mandates:RoHS recast timelines in European markets are forcing reformulation cycles. Suppliers with pre-qualified halogen-free nano grades capture accelerated qualification windows.
- Spray-dried granule morphology optimization:Thin-film tape casting processes for next-generation MLCC stacks reward specialized granule engineering. Differentiation through morphology control bypasses direct particle size competition.
- India's electronics manufacturing incentives:PLI scheme support for domestic MLCC assembly is creating demand for qualified powder supply within South Asian production corridors.
Industry Challenges
- Hydrothermal reactor scale-up capex:Continuous-flow reactor networks for consistent nano powder output demand capital commitments exceeding mid-tier producer balance sheet capacity.
- JIS-GB standard divergence:Japan's METI purity specifications and China's SAMR titanate powder standards create dual qualification burdens for suppliers serving both supply chains.
- Ferroelectric phase transition calibration:Curie point consistency near 120°C requires precise stoichiometric control across batch scales, demanding specialized process engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Batio3 Powder Market |
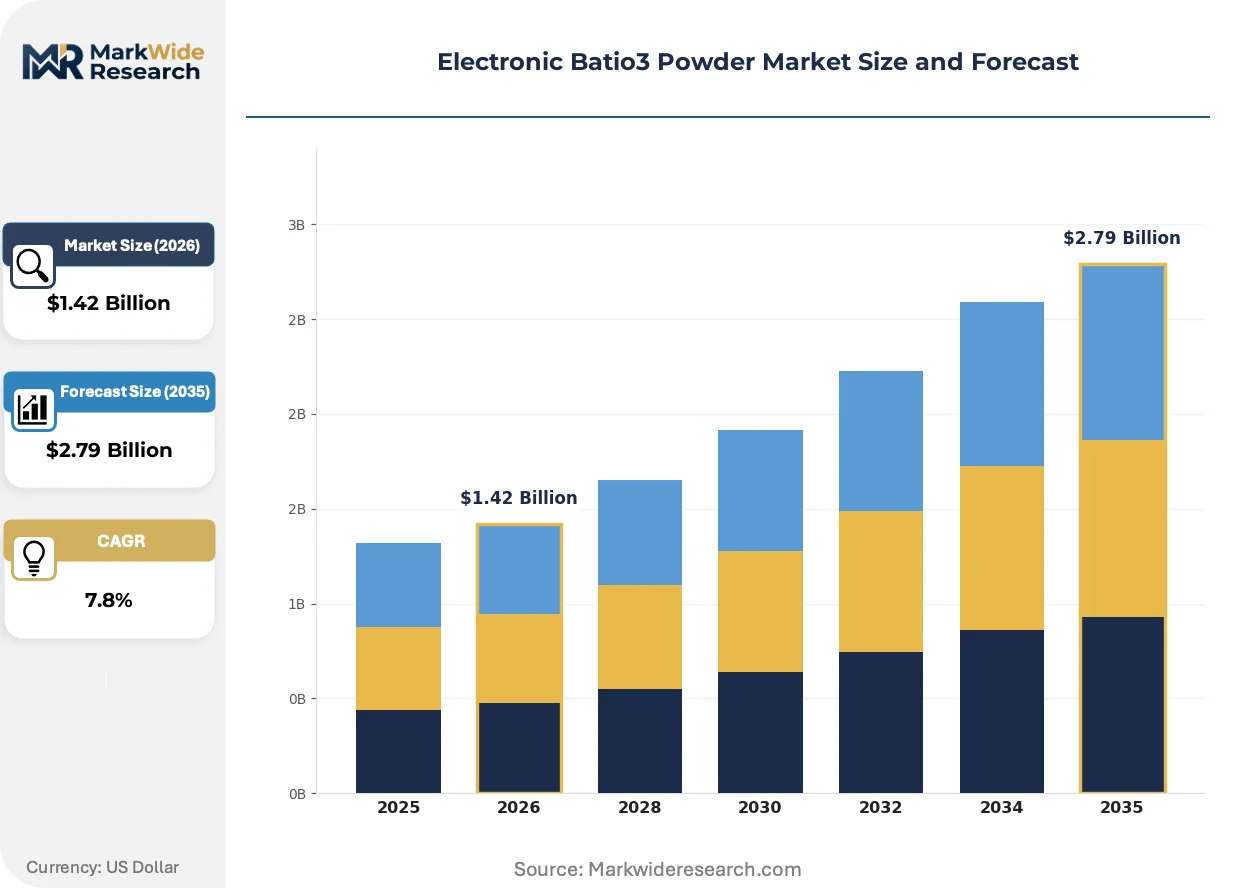
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Powder, Nano Powder, Bulk Powder, Coated Powder End User: Electronics, Automotive, Aerospace, Telecommunications Application: Capacitors, Piezoelectric Devices, Sensors, Dielectric Materials Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Sakai Chemical, Nippon Chemical, Fuji Titanium, KYORITSU, Ferro, Shandong Sinocera, Guangdong Fenghua, KCM Corporation, Murata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Batio3 Powder Market Trends and Innovations
Continuous hydrothermal synthesis is displacing batch reactor dominance in premium powder production, while regulatory chemistry restrictions and buyer consolidation are rewriting supplier qualification protocols across East Asian supply chains.
Oxalate co-precipitation routes with in-line calcination control are rendering obsolete traditional solid-state reaction methods for sub-200 nanometer grades. MLCC manufacturers in Japan and South Korea are adopting these flow-chemistry systems for dielectric layer feedstock. The technology is compressing acceptable supplier lists to firms with continuous-process engineering capabilities.
REACH registration requirements for titanate substances are tightening raw material traceability obligations for European market access. ECHA documentation demands now extend through barium source mining records for medical device capacitor applications. German and French capacitor assemblers are consolidating procurement around pre-registered suppliers to avoid qualification delays.
Direct mill-to-OEM supply contracts are displacing traditional distributor-mediated powder sales for high-volume MLCC producers. Samsung Electro-Mechanics and TDK Corporation now specify locked annual volumes with qualified Japanese powder suppliers. This channel compression is most visible in Korea's Gyeonggi-do cluster, where capacitor headquarters proximity enables just-in-time powder delivery schedules.
Electronic Batio3 Powder Market Segmentation
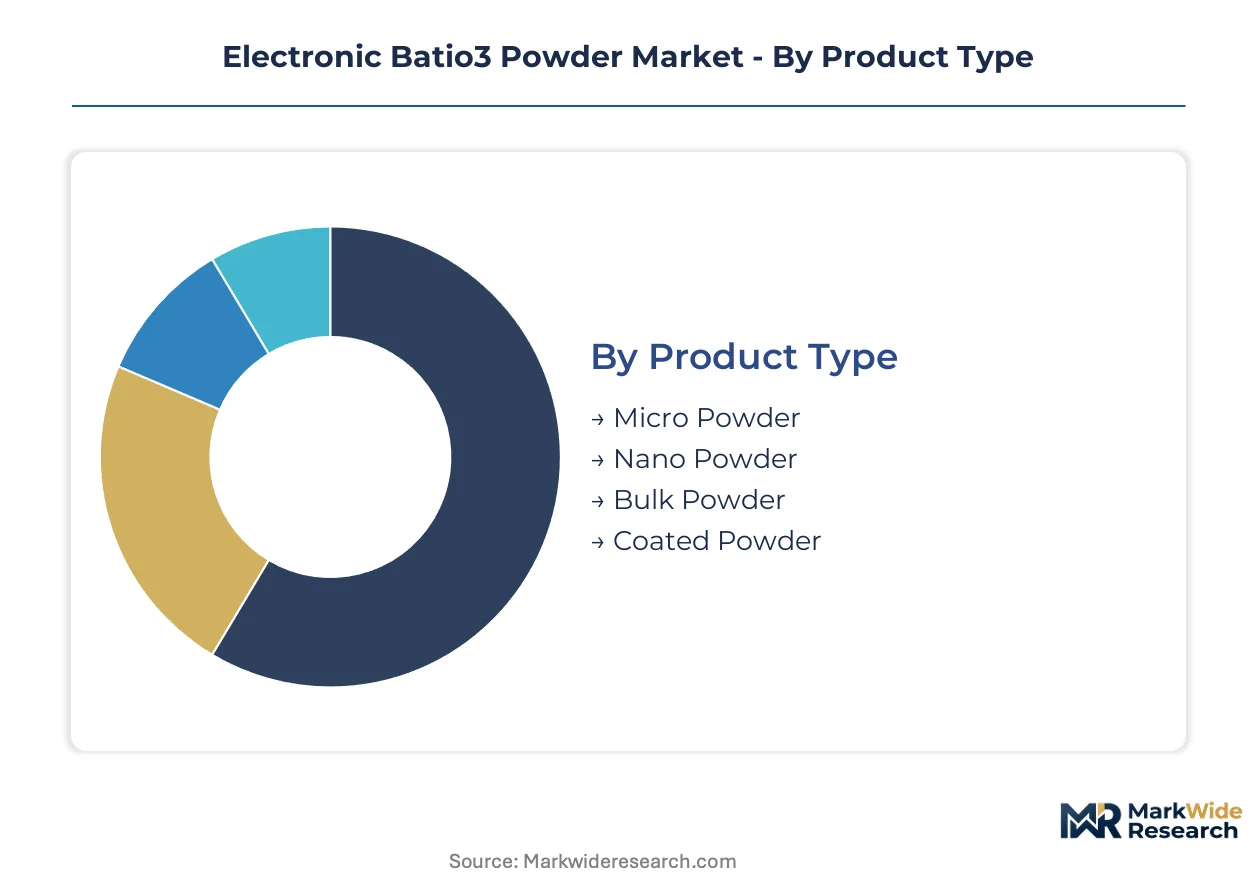
Electronic BaTiO3 powder segmentation reveals how technical specifications cascade into distinct supply chain configurations. Each dimension—particle size, end-use, application, and channel—carries unique qualification burdens and margin structures that reshape procurement relationships.
Product Type:
After-sales technical support intensity varies sharply across powder grades, with nano formulations demanding continuous process engineering collaboration while bulk grades operate on transactional specifications.
- Nano Powder:Sub-100 nanometer particle sizes engineered for multilayer ceramic capacitor dielectrics. Hydrothermal synthesis mastery determines supplier qualification status. Japan's Kansai corridor concentrates demand as MLCC layer thickness requirements compress below 100 nanometers and OEMs slash approved vendor lists to single-digit counts.
- Micro Powder:Intermediate particle distributions spanning 100-500 nanometers serving precision ceramic substrates. Automotive piezoelectric actuator manufacturers in Germany and Japan specify tight grain morphology controls. Precision fuel efficiency mandates in passenger vehicle powertrains are pulling volume into this category.
- Bulk Powder:Micron-scale grades for conventional ceramic substrates with mature margin structures.
- Coated Powder:Surface-modified particles for enhanced dispersion in tape casting slurries.
By volume, bulk powder leads. By growth pace, nano powder is ahead.
End User:
Customer technical sophistication and procurement scale create divergent service models across end-use sectors.
- Electronics:Multilayer ceramic capacitor manufacturers dominate procurement volumes. Samsung Electro-Mechanics and TDK Corporation now specify locked annual volumes with qualified Japanese suppliers. Direct mill-to-OEM contracts are displacing traditional distributor-mediated sales for high-volume MLCC producers.
- Automotive:Piezoelectric fuel injection systems demand micron-scale grades with precise grain morphology. Tier-1 suppliers in Germany's Baden-Württemberg cluster and Japan's Aichi Prefecture coordinate just-in-time powder delivery schedules.
- Aerospace:Specialized grades for high-reliability capacitors in avionics systems.
- Telecommunications:Base station and network infrastructure ceramic components.
Electronics commands the largest revenue pool. Automotive applications are climbing the fastest on electrification mandates.
Application:
Functional performance requirements stratify powder specifications across device categories.
- Capacitors:Dielectric layer feedstock absorbing dominant volume share. Continuous hydrothermal synthesis is displacing batch reactor dominance as MLCC manufacturers adopt flow-chemistry systems. The technology compresses acceptable supplier lists to firms with continuous-process engineering capabilities.
- Piezoelectric Devices:Automotive injection systems and precision positioning equipment. REACH registration requirements constrain raw material sourcing flexibility for European medical device applications.
- Sensors:Pressure and acceleration sensing ceramics.
- Dielectric Materials:General-purpose insulating ceramic substrates.
Capacitors anchor current revenue. Piezoelectric devices are gaining share fastest on automotive demand.
Distribution Channel:
Channel structure reflects the technical qualification intensity of powder grades and customer consolidation patterns.
- Direct Sales:Locked annual volume contracts with qualified suppliers. Samsung Electro-Mechanics and TDK Corporation specify just-in-time delivery schedules from Japan's Kansai corridor. Channel compression is most visible in Korea's Gyeonggi-do cluster where capacitor headquarters proximity enables tight coordination.
- Distributors:Remain relevant for mid-tier capacitor assemblers and smaller piezoelectric device manufacturers.
- Online Retail:Limited to research-grade quantities and specialty formulations.
- Wholesalers:Bulk powder for conventional ceramic substrate manufacturers.
Direct sales capture premium-grade volumes. Distributors retain position in mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multilayer ceramic capacitor manufacturers concentrate procurement decisions in East Asian industrial corridors, where powder synthesis expertise clusters near precursor supply networks and OEM assembly hubs. Buyers in Japan, South Korea, and coastal China dominate technical qualification workflows, while automotive tier-1 suppliers in Germany and emerging electronics assemblers in India reshape regional demand trajectories.
Japan
MLCC dielectric layer miniaturization below 100 nanometers drives nano-grade powder procurement from Osaka Prefecture's hydrothermal reactor networks. METI enforces JIS purity standards that constrain supplier qualification lists to single-digit counts. Sakai Chemical and Nippon Chemical anchor concentrated refining operations across the Kansai industrial corridor, leveraging captive barium carbonate precursor control.
China
Domestic MLCC assembly expansion pulls volume toward water-based synthesis methods as MEE emissions standards tighten. SAMR-administered GB specifications govern titanate powder for domestic supply chains. Shandong and Guangdong provinces host production upgrades abandoning solid-state reaction processes in favor of lower-carbon hydrothermal systems aligned with dual carbon goals.
South Korea
Samsung Electro-Mechanics and capacitor OEMs in Gyeonggi-do specify locked annual powder volumes with qualified Japanese suppliers. Direct mill-to-OEM contracts displace distributor-mediated sales for high-volume producers. Proximity to Japan's Kansai corridor enables just-in-time delivery schedules that compress inventory holding requirements.
Germany
Automotive piezoelectric fuel injection systems demand micron-scale grades with precise grain morphology from Baden-Württemberg tier-1 suppliers. REACH registration requirements through ECHA constrain raw material sourcing flexibility for medical device capacitor applications serving EMA-regulated markets. RoHS recast timelines force reformulation cycles among capacitor assemblers.
India
PLI scheme incentives for domestic MLCC assembly create demand for qualified powder supply within South Asian production corridors. Electronics manufacturing clusters in Maharashtra and Karnataka attract component assembly investment. Procurement patterns remain distributor-mediated as direct supplier relationships await technical qualification completion.
Electronic Batio3 Powder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where hydrothermal synthesis mastery determines premium-tier access. The supplier base compresses around continuous-flow reactor capabilities as MLCC OEMs slash approved vendor lists. Three archetypes dominate: integrated precursor-to-powder refiners, continuous-process technology specialists, and regional batch-process suppliers serving mature applications. Competitive moves center on backward integration into barium carbonate supply and spray-dried granule morphology optimization for thin-film tape casting differentiation.
Among Japanese integrated producers, Sakai Chemical exemplifies the hydrothermal synthesis archetype through Osaka Prefecture reactor network concentration, while Nippon Chemical represents captive precursor control strategies. Fuji Titanium occupies a position emphasizing granule engineering specialization. Chinese producers including Shandong Sinocera and Guangdong Fenghua sit within the regional scale-driven tier, navigating GB standard compliance and water-based synthesis transitions. KYORITSU and KCM Corporation anchor mid-market positioning, with Ferro representing Western market access capabilities through REACH registration infrastructure.
| Leading Market Players |
|---|
| Sakai Chemical |
| Nippon Chemical |
| Fuji Titanium |
| KYORITSU |
| Ferro |
| Shandong Sinocera |
| Guangdong Fenghua |
| KCM Corporation |
| Murata |
| Others |
Pricing and Supply Chain Analysis
Barium carbonate supply concentration in East Asia determines both the premium-to-economy powder pricing spread and the geographic clustering of qualified suppliers around captive precursor networks. Single-source dependency on integrated Japanese refiners compresses margin flexibility for independent powder manufacturers while reinforcing direct mill-to-OEM contract structures.
Pricing Analysis
Cost-plus contracts with barium carbonate indexation dominate long-term supply agreements between Kansai corridor producers and Korean capacitor OEMs. Three-tier pricing structure across nano, micro, and bulk grades reflects hydrothermal synthesis qualification intensity and JIS purity certification requirements. Pricing pressure stems from yield losses in sub-100 nanometer classification equipment, compressing effective production rates. Mid-tier capacitor assemblers exhibit highest price sensitivity, while Samsung Electro-Mechanics and TDK Corporation absorb premium tiers for locked volume security.
Supply Chain Analysis
Export-control regimes on continuous-flow hydrothermal reactor technology limit equipment flows to Chinese producers attempting water-based synthesis upgrades. Supply concentrates in Japan, South Korea, and coastal China, with Osaka Prefecture reactor networks feeding Gyeonggi-do assembly clusters. Raw material dependencies center on barium carbonate precursors, titanium dioxide feedstock, and specialized calcination equipment. Single-source vulnerability runs through captive carbonate control by integrated Japanese refiners. Distribution runs through direct mill-to-OEM contracts for premium grades, with distributors retaining mid-market relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as MLCC dielectric miniaturization below 100 nanometers splits demand between hydrothermal synthesis masters and emerging water-based producers in China.
For Market Incumbents: Insulate qualified supplier status by deepening captive barium carbonate control and accelerating continuous-flow reactor capacity additions in Osaka Prefecture. Defend against Chinese water-based synthesis upgrades by pre-qualifying halogen-free nano grades ahead of RoHS recast timelines. Certification investment in dual JIS-GB compliance maintains access to both supply chains as standards diverge. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing clusters represent the most penetrable entry point for qualified powder supply awaiting technical completion. Mid-tier automotive piezoelectric actuator manufacturers in Germany's Baden-Württemberg cluster offer secondary white-space as REACH registration complexity constrains incumbent flexibility. Go-to-market angle: distributor-mediated technical qualification support bridging direct mill-to-OEM gaps. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors continuous-process technology specialists over batch-process regional suppliers. Long-term viability across the next decade rests on hydrothermal synthesis mastery and backward integration into carbonate precursor supply. Acquisition target archetype: Japanese mid-tier producers with reactor network assets and JIS certification infrastructure. Signal to watch: Chinese domestic MLCC assembler qualification completion rates as inflection indicator for regional supply chain rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barium Carbonate | Captive precursor supply secures margin control against Sakai Chemical and Nippon Chemical concentration. |
| Continuous Hydrothermal Reactor Scale-Up | Flow-chemistry mastery determines MLCC OEM qualification status as vendor lists compress. |
| Halogen-Free Grade Pre-Qualification | RoHS recast compliance captures accelerated European capacitor reformulation windows. |
| Dual JIS-GB Certification Investment | METI and SAMR standard divergence creates dual qualification burden for cross-border suppliers. |
| Direct Mill-to-OEM Contract Expansion | Samsung Electro-Mechanics and TDK Corporation procurement patterns displace distributor channels. |
Research Methodology
Cross-validation between primary interviews with powder plant managers, MLCC procurement leads at Korean capacitor OEMs, and hydrothermal reactor engineering specialists anchors the qualitative findings. Secondary validation draws from customs trade data, METI JIS standard filings, SAMR GB specification documents, and SEC 10-K disclosures from listed materials suppliers. Bottom-up capacity modeling and top-down demand triangulation from MLCC dielectric layer thickness roadmaps reconcile volume estimates.
Calibration against historical nano powder qualification timelines and water-based synthesis adoption curves in Shandong and Guangdong provinces informs the projection framework. Segmentation dimensions span particle size tier, end-use industry, application function, and distribution channel structure across the analysis window. CAGR derivation rests on MLCC layer compression trajectories, automotive piezoelectric actuator penetration rates, and regional production cluster expansion under India's PLI scheme.
Practitioners should monitor Chinese domestic MLCC assembler technical qualification completion, REACH registration timeline extensions for titanate substances, and hydrothermal reactor equipment export control enforcement for early signals. Forecasts reflect assumptions on water-based synthesis yield improvement rates and JIS-GB standard harmonization progress. Material shifts in barium carbonate supply concentration or MEE emissions standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Potassium Chlorate Market