
 North America Paraffin Wax and Emulsions Market | 2026-2036
North America Paraffin Wax and Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paraffin Wax and Emulsions Market Intelligence
Multi-source procurement among coating manufacturers is restructuring supply relationships across the North American paraffin value chain. The International Group, Inc. leverages its integrated refining footprint to secure consistent slack wax feedstock for downstream emulsion production. Clariant competes through specialty wax formulations tailored to pharmaceutical and personal care grades. Dominion Chemical Company anchors regional distribution networks serving mid-Atlantic coating and adhesive producers.
Paraffin wax and emulsions comprise saturated hydrocarbon mixtures derived from petroleum refining, typically featuring melting points between 46°C and 68°C and oil content below 0.5% for fully refined grades. These materials function primarily as moisture barriers, release agents, and viscosity modifiers across industrial and consumer applications. Specialty waxes command premium positioning in pharmaceutical and food-grade segments where FDA compliance and batch certification create margin pools. Emulsions represent the fastest-expanding category as water-based formulations displace solvent systems in coatings and personal care products under pressure from environmental regulations.
The EPA regulates volatile organic compound emissions from paraffin-containing coatings and adhesives under Clean Air Act provisions, while FDA 21 CFR standards govern direct and indirect food contact applications for wax formulations. Health Canada enforces parallel restrictions through the PMRA and Food and Drugs Act, creating a dual-compliance burden for cross-border suppliers. Stakeholders must monitor pending revisions to EPA VOC thresholds and FDA food-contact notification requirements to anticipate reformulation cycles and certification timelines.
Market Dynamics
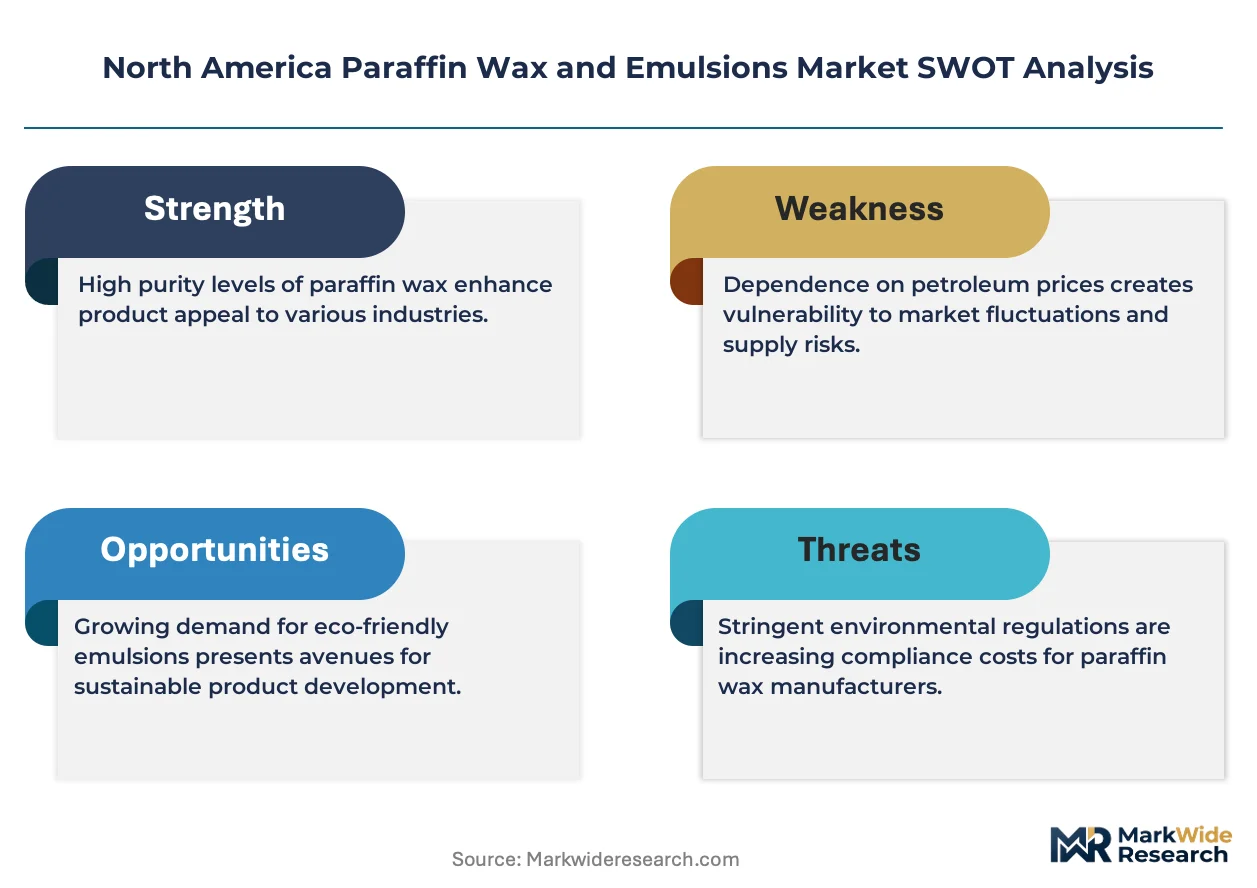
The North American paraffin market is restructuring around EPA VOC emission thresholds for coatings and adhesives, forcing reformulation toward low-emulsion wax blends while Gulf Coast refinery concentration tightens feedstock security.
Growth Catalysts
- EPA Clean Air Act compliance cycles:Manufacturers are accelerating adoption of water-based emulsion systems to meet tightening volatile organic compound limits in architectural coatings.
- Candle industry formulation upgrades:Scented and decorative candle producers across the United States and Canada are expanding orders for fully refined paraffin with sub-0.5% oil content.
- Texas-Louisiana Gulf Coast integration:Slack wax supply from integrated refineries is securing captive feedstock for downstream emulsion processors.
Market Restraints
- Crude oil price volatility:Paraffin wax pricing tracks petroleum feedstock swings, compressing margin predictability for blenders and distributors.
- Gulf Coast supply concentration:Overreliance on Texas and Louisiana petrochemical infrastructure creates hurricane and logistics disruption exposure.
- Natural wax substitution:Soy and beeswax alternatives are capturing premium candle and personal care segments where sustainability positioning commands price premiums.
Strategic Opportunities
- Canadian cross-border expansion:Health Canada PMRA alignment with EPA standards creates streamlined certification pathways for US-formulated emulsions.
- Pharmaceutical-grade specialization:FDA 21 CFR compliance for direct and indirect food contact is opening margin pools in oral solid dosage coatings.
- Mid-Atlantic distribution hub development:Pennsylvania and New Jersey warehousing positions are shortening lead times to New England coating clusters.
Industry Challenges
- Dual-compliance certification timelines:Cross-border suppliers face staggered EPA and Health Canada notification requirements that extend product launch cycles.
- Specialized blending technician scarcity:Formulation chemistry expertise for low-VOC emulsion development is concentrating at integrated refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paraffin Wax and Emulsions Market |
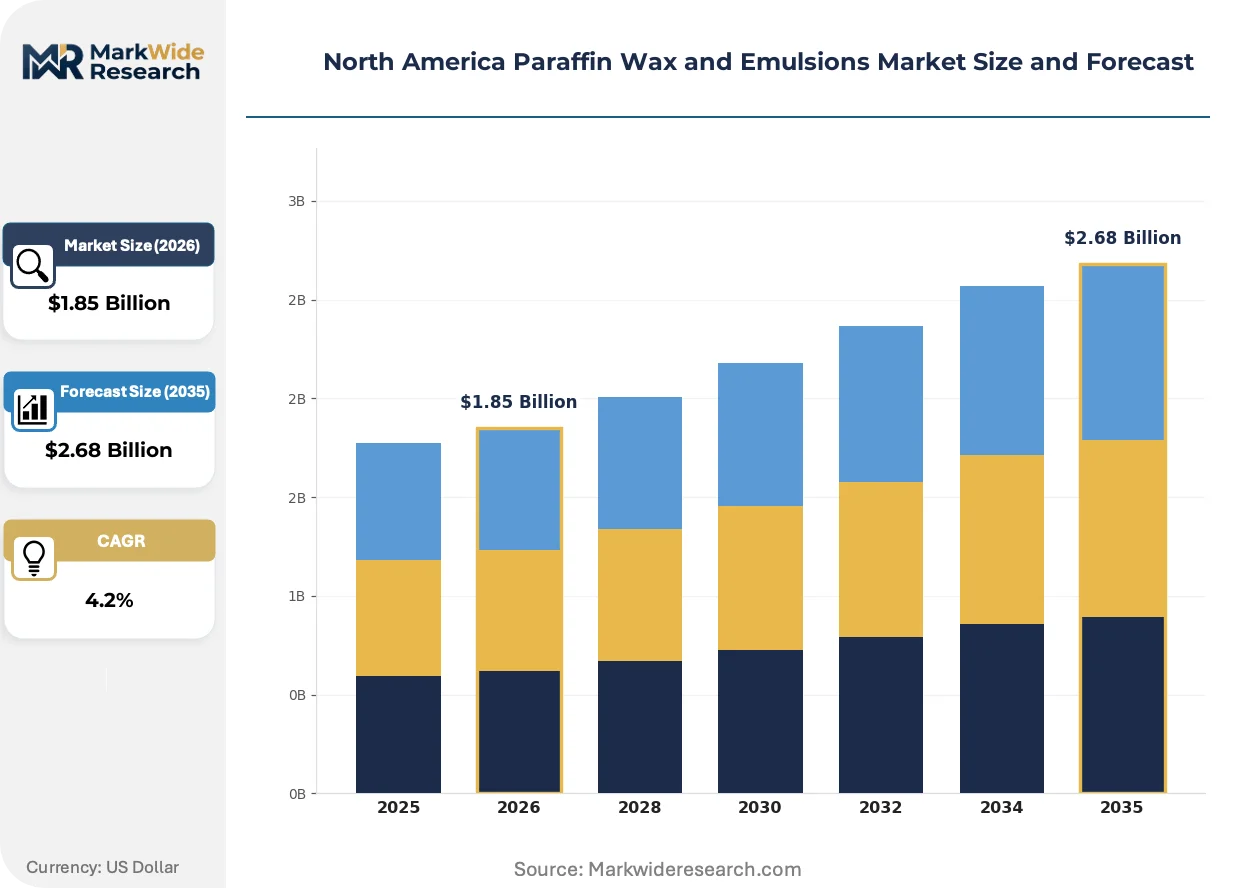
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Emulsions, Specialty Waxes, Processed Waxes End User: Candlemakers, Coating Manufacturers, Pharmaceuticals, Food Industry Application: Cosmetics, Food Packaging, Adhesives, Personal Care Packaging Type: Bulk Packaging, Retail Packaging, Custom Size, Drums |
| Companies Covered | Dominion Chemical Company, Hexion, The International Group, Inc., Walker Industries, Willamette Valley Company, Accu-Blend Corporation, King Honor International Ltd., Clariant, Moretex Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paraffin Wax and Emulsions Market Strategic Shifts & Innovations
Water-based emulsion chemistry is displacing solvent systems across industrial coatings, while regulatory alignment between US and Canadian agencies is simplifying cross-border formulation strategies.
Microcrystalline wax blends are expanding into high-performance barrier coatings for food packaging. Flexible packaging converters in the Midwest are adopting these formulations at accelerated pace to meet FDA grease-resistance specifications. This expansion is compressing demand for conventional paraffin in favor of tailored petroleum wax combinations with superior moisture and oxygen blocking.
EPA VOC threshold revisions under Clean Air Act Section 183(e) are forcing coatings manufacturers below 250 grams per liter limits. Industrial maintenance and automotive refinish segments are responding with accelerated water-based emulsion trials. The Southwestern US construction corridor is experiencing the most acute reformulation pressure as state implementation plans tighten ahead of federal deadlines.
Direct mill procurement is displacing traditional distributor relationships among large-volume coating manufacturers. Tier-one adhesive producers are negotiating long-term offtake agreements directly with Gulf Coast refiners. This pattern is most visible in the Ohio River Valley manufacturing belt where logistics costs favor consolidated purchasing over fragmented supply.
North America Paraffin Wax and Emulsions Market Segmentation
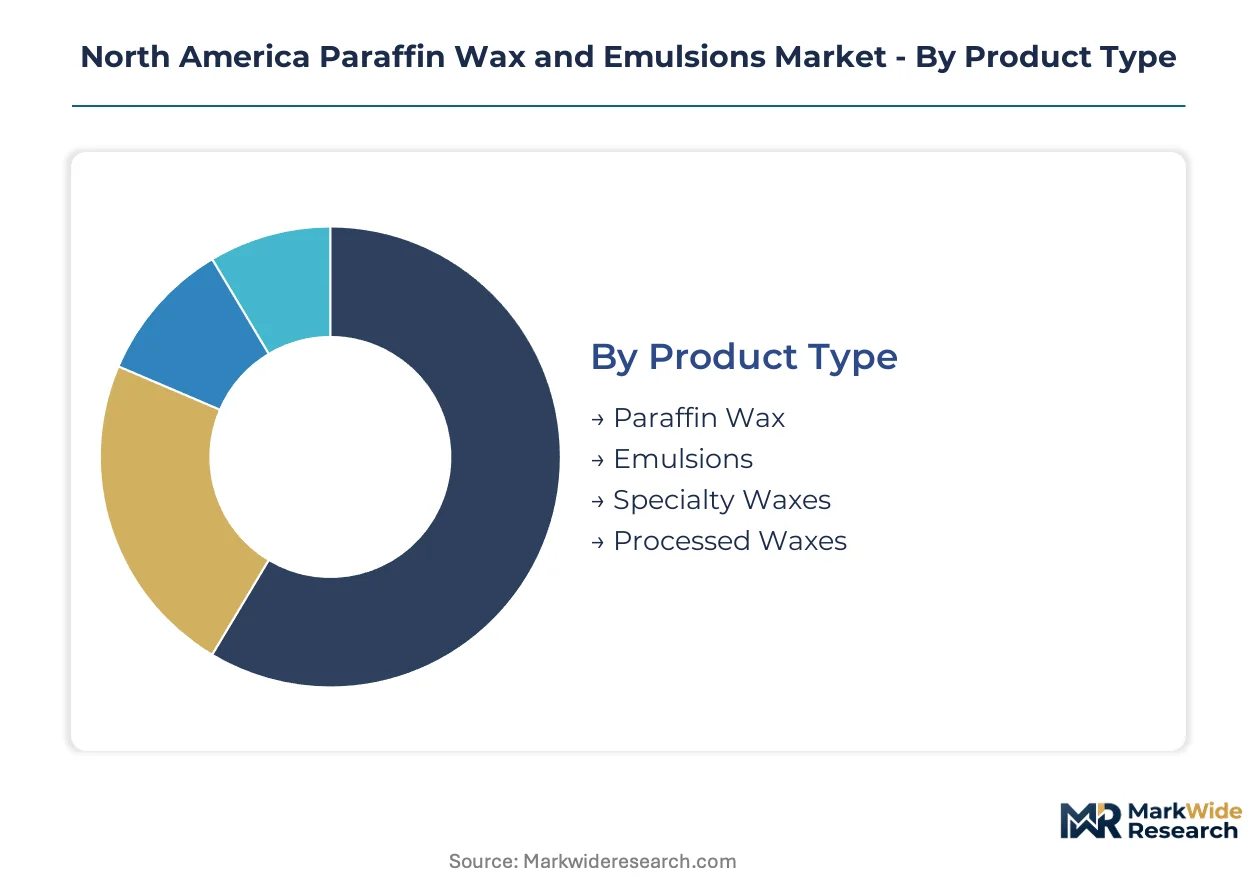
Paraffin wax and emulsion buyers across North America face divergent specification requirements depending on end-use regulatory exposure. Segmentation reveals how Gulf Coast refiners, mid-Atlantic blenders, and Canadian formulators target distinct margin pools through product architecture and certification tiering.
Product Type:
Standardization dominates commodity grades while specialty waxes command formulation premiums through FDA 21 CFR batch certification and custom melt-point engineering.
- Paraffin Wax:Saturated hydrocarbon mixtures with melting points between 46°C and 68°C and oil content below 0.5% for fully refined grades. Candlemakers across the United States and Canada are expanding procurement of refined formulations for scented and decorative products, though natural wax substitution threatens premium positioning.
- Emulsions:Water-based dispersions displacing solvent systems under EPA VOC emission pressure. Coating manufacturers in the Southwestern US construction corridor are accelerating trials to meet sub-250 grams per liter thresholds ahead of state implementation plan deadlines.
- Specialty Waxes:Microcrystalline and tailored petroleum combinations with superior moisture and oxygen blocking for high-performance barriers.
- Processed Waxes:Oxidized and chemically modified grades for adhesives and industrial maintenance coatings.
Leading the category by volume: Paraffin Wax. Expanding most quickly: Emulsions.
End User:
Procurement scale separates large-volume direct mill buyers from fragmented distributor-dependent segments.
- Candlemakers:Scented and decorative producers across the United States and Canada drive demand for fully refined grades with sub-0.5% oil content. EPA indoor air quality considerations and consumer fragrance load preferences are forcing reformulation toward cleaner-burning paraffin blends.
- Coating Manufacturers:Architectural and industrial maintenance producers face the most acute EPA VOC compliance pressure. Tier-one adhesive producers in the Ohio River Valley manufacturing belt are negotiating long-term offtake agreements directly with Gulf Coast refiners to compress logistics costs.
- Pharmaceuticals:Oral solid dosage coating applications require FDA 21 CFR compliance for direct and indirect food contact.
- Food Industry:Grease-resistant packaging converters in the Midwest are adopting microcrystalline wax blends at accelerated pace.
Candlemakers generate the largest absolute volume. Coating manufacturers are climbing the fastest on regulatory reformulation cycles.
Application:
Regulatory jurisdiction determines formulation complexity — FDA food contact versus EPA emission control creates divergent specification paths.
- Cosmetics:Personal care formulations demand pharmaceutical-grade certification and low-sensitization profiles. Health Canada PMRA alignment with EPA standards is streamlining cross-border certification for US-formulated emulsions entering Canadian cosmetic production.
- Food Packaging:Flexible packaging converters require FDA grease-resistance specifications and batch traceability. Midwest converters are shifting toward microcrystalline-paraffin combinations that outperform conventional paraffin on moisture and oxygen blocking.
- Adhesives:Water-based emulsion systems are displacing solvent formulations under Clean Air Act pressure.
- Personal Care:Skin contact applications require dermatological safety testing and preservative compatibility.
Food Packaging leads by volume. Cosmetics shows the steepest expansion trajectory on premium personal care demand.
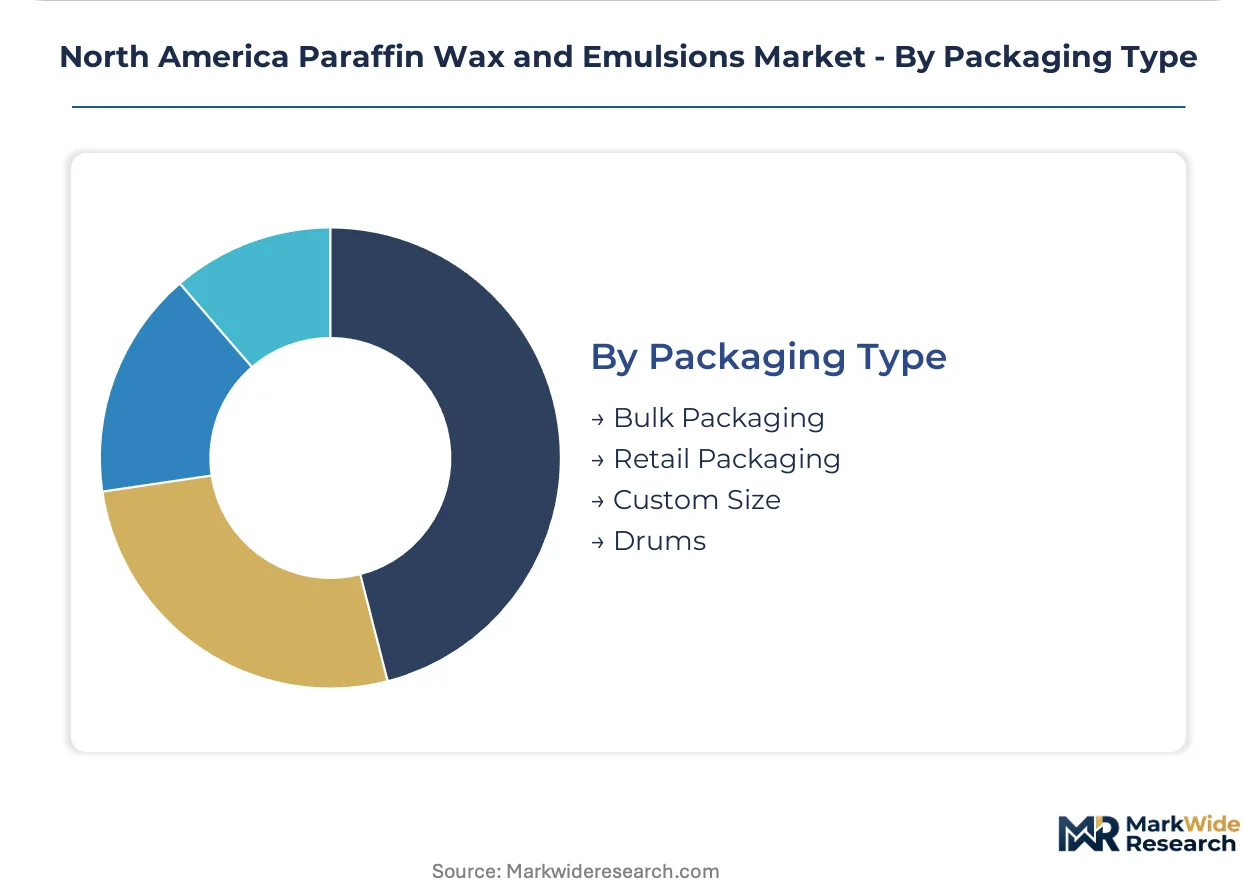
Packaging Type:
Logistics economics favor bulk for integrated refiners while custom sizing captures margin from specialty formulators.
- Bulk Packaging:Tanker and railcar deliveries serve high-volume coating clusters in the Ohio River Valley and Texas-Louisiana Gulf Coast corridor. Direct mill procurement is displacing traditional distributor relationships among large-volume manufacturers seeking to compress per-unit logistics costs.
- Drums:Standard 55-gallon containers dominate mid-tier procurement for mid-Atlantic coating and adhesive producers served by regional distribution networks.
- Retail Packaging:Small-lot containers serve artisan candlemakers and specialty cosmetic formulators.
- Custom Size:Tailored volumes and specifications for pharmaceutical and food-grade applications requiring lot certification.
Bulk Packaging dominates volume. Custom Size is gaining share fastest on pharmaceutical and food-grade specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Louisiana Gulf Coast petrochemical corridor anchors North American paraffin wax supply, with integrated refineries supplying slack wax feedstock to downstream processors. This concentration shapes procurement patterns across the region.
United States
Candlemakers across the United States are expanding orders for fully refined paraffin with sub-0.5% oil content for scented and decorative products. EPA Clean Air Act Section 183(e) revisions are forcing coatings manufacturers below 250 grams per liter VOC thresholds. The Ohio River Valley manufacturing belt is seeing tier-one adhesive producers negotiate long-term offtake agreements directly with Gulf Coast refiners to compress logistics costs.
Canada
Canadian cosmetic formulators are accelerating procurement of US-formulated emulsions as Health Canada PMRA alignment with EPA standards streamlines cross-border certification. The Food and Drugs Act governs direct and indirect food contact applications, creating parallel compliance requirements. Ontario and Quebec warehousing positions are shortening lead times to serve regional coating clusters.
Mexico
Mexican flexible packaging converters are adopting microcrystalline-paraffin combinations for FDA grease-resistant specifications serving export markets. The country's national chemical regulator enforces evolving environmental standards on solvent-based coatings. Northern border states are experiencing accelerated water-based emulsion trials as manufacturers anticipate harmonization with US VOC thresholds.
North America Paraffin Wax and Emulsions Market Key Industry Players
Global majors compete with regional champions across formulation certification tiers and feedstock integration depth. The North American paraffin market exhibits moderate consolidation around Gulf Coast refiners with captive slack wax supply, while specialty blenders fragment across pharmaceutical and personal care grades. Three archetypes dominate: integrated petrochemical refiners with backward control into feedstock, specialty chemical formulators targeting FDA 21 CFR compliance tiers, and regional distributors anchoring mid-Atlantic logistics networks. Competitive intensity centers on M&A activity consolidating blending capacity and strategic partnerships securing long-term offtake agreements with coating manufacturers.
Within the integrated refiner archetype, The International Group, Inc. and Hexion occupy positions defined by upstream feedstock security. Among specialty formulators, Clariant exemplifies the premium-tier vector targeting pharmaceutical and personal care certification requirements. Dominion Chemical Company anchors the regional distribution tier, serving mid-Atlantic coating and adhesive producers through established logistics networks.
| Leading Market Players |
|---|
| Dominion Chemical Company |
| Hexion |
| The International Group, Inc. |
| Walker Industries |
| Willamette Valley Company |
| Accu-Blend Corporation |
| King Honor International Ltd. |
| Clariant |
| Moretex Chemical |
| Others |
Cost & Logistics Intelligence
FDA 21 CFR certification tiers create a three-rung ladder where pharmaceutical-grade batch certification commands substantial premiums over commodity candle wax, and this quality bifurcation shapes both contract structures and sourcing geography across the North American value chain. Buyers of fully refined grades with sub-0.5% oil content face longer qualification cycles and concentrated supplier pools, while commodity purchasers exploit fragmented blending capacity for price leverage.
Pricing Analysis
Service bundling separates integrated refiners offering technical formulation support from unbundled commodity traders, with The International Group and Hexion embedding application engineering into long-term offtake agreements while spot buyers absorb unassured quality variance. Price differentiation hinges on certification grade—FDA 21 CFR compliance versus industrial specifications—and volume scale, with direct mill procurement compressing per-unit costs for Ohio River Valley adhesive producers. Pricing pressure stems from crude oil feedstock volatility transmitting through slack wax input costs. Candlemakers show highest price sensitivity as soy and beeswax alternatives capture sustainability-premium segments.
Supply Chain Analysis
Domestic-content preferences in US government procurement and Buy America provisions for infrastructure coatings are reinforcing Texas-Louisiana Gulf Coast sourcing over Canadian or Mexican alternatives despite cross-border trade flows. Supply concentrates in the United States, with secondary nodes in Canada and emerging Mexican flexible packaging capacity. Feedstock draws from petroleum refining slack wax, microcrystalline wax for barrier applications, and specialized emulsion surfactants. Single-source vulnerability runs through hurricane-exposed Gulf Coast infrastructure. Distribution runs through direct mill railcar deliveries for volume buyers and regional drum networks for mid-Atlantic coating clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Air Act VOC thresholds function as a cost-of-compliance moat, with sub-250 grams per liter reformulation requirements forcing capital-intensive emulsion chemistry investments that screen out undercapitalized blenders.
For Market Incumbents: Cement backward integration into captive slack wax supply through long-term Gulf Coast refinery agreements, insulating margin from crude price volatility while natural wax substitution threatens premium candle positioning. Expand pharmaceutical-grade certification capacity to capture oral solid dosage coating demand as FDA 21 CFR compliance creates sticky customer relationships. For New Entrants and Emerging Players: Capture mid-Atlantic distribution white space through Pennsylvania and New Jersey warehousing positions serving coating clusters with shortened lead times versus Gulf Coast supply. Target Health Canada PMRA-aligned emulsion formulations for cross-border cosmetic formulators seeking streamlined certification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with specialty formulators possessing FDA 21 CFR batch certification infrastructure given pharmaceutical-grade margin expansion. Long-term viability favors acquisition targets with dual EPA-Health Canada compliance capabilities. Watch EPA VOC threshold enforcement acceleration in Southwestern state implementation plans as inflection signal for water-based emulsion demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive slack wax supply from Texas-Louisiana refineries secures feedstock cost predictability for emulsion processors. |
| Long-term Supply Agreement | Direct mill offtake contracts with Ohio River Valley adhesive producers compress logistics costs and displace distributor relationships. |
| Green Manufacturing Transition | Water-based emulsion chemistry investments align with EPA Clean Air Act Section 183(e) compliance deadlines. |
| Capacity Expansion | Pharmaceutical-grade blending capacity additions capture FDA 21 CFR oral solid dosage coating demand. |
| Joint Venture | Cross-border partnerships with Canadian formulators leverage Health Canada PMRA-EPA alignment for streamlined certification. |
Research Approach
Multi-period observation of EPA enforcement patterns, refinery capacity utilization, and candlemaker procurement cycles anchored the trend analysis, supplemented by interviews with Gulf Coast refinery operations managers, mid-Atlantic coating procurement leads, pharmaceutical formulation scientists, Health Canada regulatory affairs specialists, and flexible packaging converters. Secondary validation drew from EPA enforcement databases, FDA 21 CFR food-contact notifications, customs trade records, and SEC filings of integrated petrochemical firms. Bottom-up segment sizing triangulated against top-down petrochemical derivative demand models.
Segment-weighting across product type, end user, application, and packaging format dimensions structured the analytical framework across the analysis window. CAGRs derived from elasticity-adjusted demand projections incorporating regulatory compliance cycle timing, feedstock cost transmission coefficients, and substitution elasticity estimates for natural wax alternatives. Industry-specific inputs included EPA state implementation plan deadline schedules and FDA food-contact notification approval velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil price volatility, hurricane disruption frequency in the Gulf Coast corridor, and acceleration of natural wax substitution in premium consumer segments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market