
 Dextrin Market | 2026-2036
Dextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Dextrin Market Analysis
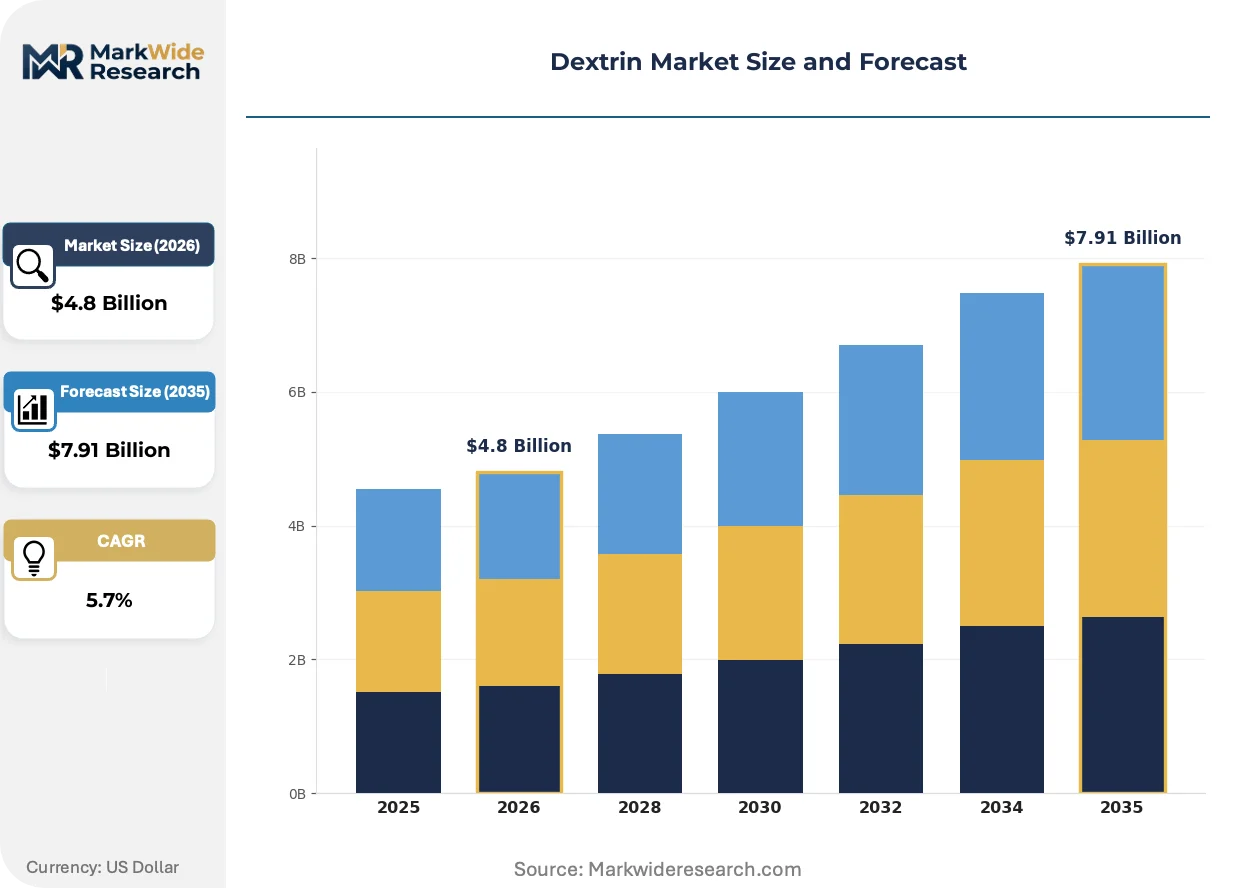
REACH compliance is rebalancing the cost-of-entry calculus for European dextrin suppliers, forcing reformulation investments that favor larger producers with dedicated regulatory teams. Cargill, Incorporated leverages its integrated corn processing network to absorb these compliance costs without fragmenting pricing. Roquette Frères anchors its position through pea and potato starch diversification, reducing exposure to single-crop volatility. Matsutani Chemical Industry Co., Ltd. competes on cyclodextrin purity grades that meet Japan's PMDA pharmaceutical excipient standards.
Dextrin comprises partially hydrolyzed starch polymers produced through controlled heat and acid treatment, yielding water-soluble carbohydrates with dextrose equivalent values typically ranging from 5 to 30 depending on processing severity. These compounds serve primarily as binders, thickeners, and encapsulating agents across food, pharmaceutical, and adhesive formulations. Maltodextrin dominates volume flows due to its neutral flavor profile and instant solubility in sports nutrition and infant formula applications, while cyclic dextrin commands premium positioning in pharmaceutical solubilization where host-guest molecular complexation delivers bioavailability advantages. The food and beverage application segment sustains the broadest demand base, though pharmaceutical-grade specifications are tightening and shifting margin pools toward excipient certification programs.
The EPA regulates dextrin manufacturing effluents under Clean Water Act provisions, while FDA food additive and GRAS determinations govern ingredient market access in the United States. EFSA's evolving guidance on modified starch labeling within the EU is reshaping product positioning requirements for clean-label formulations. Stakeholders must monitor how carbon border adjustment mechanisms and renewable feedstock traceability standards will restructure sourcing economics for starch derivatives across major producing regions.
Market Dynamics
Clean-label formulation mandates and pharmaceutical excipient certification requirements are compressing supplier margins while fragmenting procurement patterns across food and drug manufacturing channels.
Growth Catalysts
- Sports nutrition formulation:Maltodextrin serves as the primary carbohydrate source in endurance hydration products, with powder premix manufacturers in Germany and the United States expanding dedicated dextrin blending lines to capture performance nutrition contract manufacturing volumes.
- EU Green Deal carbon accounting:Starch derivative suppliers achieving verified Scope 3 reductions now qualify for preferential procurement terms under European food conglomerate sustainability scorecards, accelerating facility retrofits in the Netherlands and France.
- India's pharmaceutical excipient surge:Domestic generic formulation output expansion is tightening supply of cyclodextrin complexes for solubility enhancement, with CDSCO accelerating excipient master file approvals for local manufacturers.
Market Restraints
- Corn price volatility:Feedstock concentration in U.S. Midwest grain belts exposes processors to drought-induced input cost spikes that compress gross margins during El Niño cycles.
- REACH compliance burden:ECHA's evolving data requirements for modified starch derivatives force smaller European suppliers to either consolidate or exit, reducing competitive pressure at the mid-tier.
- Native starch substitution:Clean-label purists in Nordic retail markets increasingly specify unmodified tapioca or rice starches, displacing dextrin in premium sauce and dressing applications.
Strategic Opportunities
- Pea starch dextrin expansion:Roquette's Canadian processing complex enables non-GMO, allergen-free binding solutions that penetrate North American plant-based meat analog formulations previously locked out by corn and wheat sourcing constraints.
- Japan's PMDA pharmaceutical-grade certification:Cyclodextrin producers meeting host-guest complexation purity thresholds access premium pricing in oncology drug solubilization contracts.
- Direct-to-manufacturer digital procurement:B2B platforms connecting Indian pharmaceutical formulators with regional dextrin refiners are disintermediating traditional chemical distributor networks, compressing lead times from weeks to days.
Industry Challenges
- Excipient certification timelines:FDA Type II drug master file reviews for novel dextrin derivatives now extend 18-24 months, freezing capital in pipeline products awaiting pharmaceutical market access.
- Skilled process engineering scarcity:Controlled hydrolysis reactor optimization requires expertise at the intersection of enzymatic catalysis and polymer chemistry that remains concentrated among retiring specialists at legacy European starch houses.
- Legacy ERP integration friction:Food manufacturers migrating to cloud-based procurement systems struggle to map dextrin specification hierarchies onto standardized material master databases, delaying supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dextrin Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Dextrin, Yellow Dextrin, Maltodextrin, Cyclic Dextrin Application: Food & Beverage, Pharmaceuticals, Personal Care, Adhesives Form: Powder, Granules, Liquid, Tablet End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Chemical Industries |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Tate & Lyle, Roquette Frères, Ingredion Incorporated, Avebe, Emsland-Stärke GmbH, Grain Processing Corporation, Matsutani Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dextrin Market Emerging Trajectories
Enzymatic processing advances and carbon traceability infrastructure are restructuring how dextrin specifications are negotiated, certified, and priced across ingredient supply chains.
Continuous enzymatic hydrolysis systems are modularizing production economics for mid-scale dextrin refiners. Food ingredient technology firms in Denmark and the Netherlands deploy plug-and-play reactor skids that slash capital requirements versus batch acid hydrolysis installations. Pharmaceutical contract manufacturers now source from distributed regional enzymatic facilities rather than consolidated commodity starch processors, fragmenting volume concentration.
REACH's 2024 update to polymer registration requirements is forcing reformulation investments across European adhesive and textile sizing applications. ECHA's expanded data obligations for starch derivatives with dextrose equivalent values below 20 now require chronic toxicity studies that smaller suppliers cannot fund independently. German and Belgian industrial dextrin consumers are consolidating supplier panels to three qualified vendors with dedicated regulatory affairs divisions.
Specification-driven procurement now dominates pharmaceutical excipient sourcing as CDSCO and PMDA align on cyclodextrin purity testing protocols. Indian generic drug exporters previously accepting food-grade dextrin for oral solid dosages now mandate USP-NF or JPE certification, disqualifying commodity suppliers. Mumbai and Hyderabad formulation clusters have established dedicated excipient qualification teams that audit dextrin refiners against IPEC-PQG good manufacturing practice standards before contract execution.
Dextrin Market Segmentation
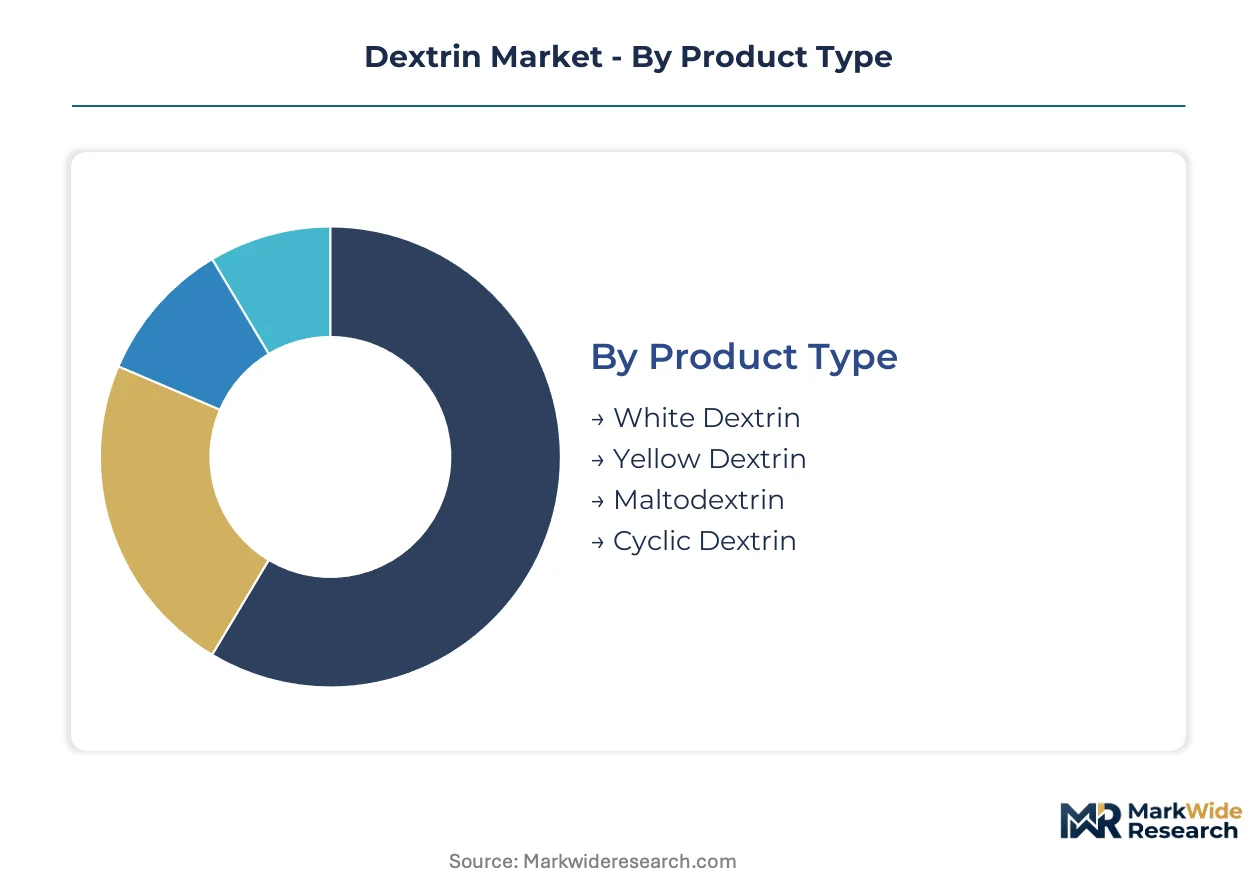
Dextrin specifications fragment across four intersecting dimensions that reshape procurement economics. Product chemistry determines functional performance in binding and solubility applications. End-user certification requirements now override commodity pricing in contract negotiations.
Product Type:
Buyers in this category differentiate by molecular weight distribution and dextrose equivalent thresholds that dictate formulation compatibility.
- Maltodextrin:Low dextrose equivalent polymers with neutral sensory profiles dominate sports nutrition and infant formula applications. Powder premix manufacturers in Germany and the United States expand dedicated blending lines to capture performance nutrition contract volumes.
- Cyclic Dextrin:Toroidal oligosaccharide structures enable host-guest molecular complexation for pharmaceutical solubilization. CDSCO and PMDA alignment on purity testing protocols is tightening supply qualification for Indian generic drug exporters.
- White Dextrin:Cold-water soluble starch derivatives manufactured through controlled roasting serve adhesive and textile sizing applications in Belgium and the Netherlands.
- Yellow Dextrin:Higher dextrose equivalent variants produced via acid hydrolysis at elevated temperatures provide stronger binding characteristics for corrugated board manufacturing.
Volume sits with maltodextrin; growth tilts toward cyclic dextrin.
Application:
Regulatory jurisdiction determines grade specifications more than functional requirements in this dimension.
- Food & Beverage:Clean-label binding and thickening applications span sauce, dressing, and bakery formulations. Nordic retail markets increasingly specify unmodified native starches, displacing dextrin in premium positioning.
- Pharmaceuticals:Excipient certification under USP-NF or JPE standards governs oral solid dosage and solubility enhancement contracts. Mumbai and Hyderabad formulation clusters audit refiners against IPEC-PQG standards before execution.
- Adhesives:Industrial dextrin serves paperboard lamination and corrugated bonding where REACH compliance is consolidating European supplier panels.
- Personal Care:Film-forming and encapsulation properties drive demand in cosmetic serum and hair care formulations.
Food and beverage commands absolute volume; pharmaceuticals deliver the steepest margin expansion trajectory.
Form:
Handling economics and dissolution kinetics separate procurement preferences across manufacturing footprints.
- Powder:Instant solubility and bulk density optimization dominate sports nutrition and pharmaceutical powder premix specifications.
- Granules:Controlled release and reduced dusting characteristics serve tablet compression and direct compression formulations.
- Liquid:Pre-hydrated dextrin solutions eliminate dissolution steps in continuous manufacturing processes for adhesives and textile sizing.
- Tablet:Direct compression grades with specified disintegration profiles target pharmaceutical excipient applications.
Powder form anchors current procurement; liquid concentrates are gaining share fastest in continuous processing environments.
End User:
Scale and certification intensity fragment this category between commodity volume buyers and specification-driven purchasers.
- Food Manufacturers:Clean-label mandates and carbon accounting scorecards now govern supplier selection for binding applications in plant-based meat analogs and bakery systems.
- Pharmaceutical Companies:FDA Type II drug master file requirements and 18-24 month review timelines freeze capital in pipeline excipient products awaiting market access.
- Chemical Industries:Adhesive and textile sizing applications in Germany and Belgium consolidate toward three qualified vendors with dedicated regulatory affairs divisions.
- Cosmetic Brands:Film-forming and encapsulation specifications drive demand from formulation houses seeking natural-derived alternatives to synthetic polymers.
Food manufacturers generate baseline volume; pharmaceutical companies concentrate margin capture through certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate pharmaceutical excipient manufacturing under India's PLI scheme incentives. These zones attract cyclodextrin refiners serving Mumbai and Hyderabad formulation clusters.
United States
Corn belt processors supply maltodextrin to sports nutrition manufacturers in Utah and Colorado. EPA Clean Water Act effluent rules govern production economics. Omaha and Cedar Rapids house integrated starch-to-dextrin facilities expanding capacity for infant formula premix customers.
Germany
REACH compliance costs filter smaller suppliers from adhesive and textile sizing contracts. ECHA's 2024 polymer registration updates force chronic toxicity investments. Cologne and Hamburg industrial zones consolidate procurement panels to three qualified vendors with dedicated regulatory divisions.
India
Domestic generic formulation output tightens cyclodextrin supply for solubility enhancement applications. CDSCO accelerates excipient master file approvals under revised pharmaceutical sector guidelines. Mumbai and Hyderabad clusters now mandate IPEC-PQG audits before dextrin refiner contracts execute.
Japan
PMDA pharmaceutical-grade certification requirements govern oncology drug solubilization procurement. Cyclodextrin producers meeting host-guest complexation purity thresholds command premium positioning. Osaka and Tokyo pharmaceutical corridors source exclusively from certified refiners with validated analytical protocols.
Netherlands
EU Green Deal carbon accounting scorecards reward starch derivative suppliers with verified Scope 3 reductions. Rotterdam and Groningen enzymatic processing facilities capture preferential terms from European food conglomerate sustainability frameworks. Continuous reactor retrofits modularize production economics for mid-scale refiners.
Dextrin Market Vendor Landscape
North American producers anchor the commodity volume tier; European specialists hold the regulatory-intensive premium segment. Market structure tilts toward consolidation as REACH compliance burdens eliminate mid-tier suppliers without dedicated regulatory affairs divisions. Three archetypes dominate: integrated agribusiness conglomerates with captive corn processing networks, diversified starch houses with multi-feedstock flexibility, and pharmaceutical-grade specialists with cyclodextrin purity certifications. Capacity expansion and portfolio diversification toward pea and potato starch alternatives represent the dominant competitive vectors.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through Midwest grain belt processing networks. Roquette Frères occupies a position within the diversified starch house archetype, leveraging multi-crop sourcing flexibility. Matsutani Chemical Industry Co., Ltd. represents the pharmaceutical-grade specialist segment, anchoring premium positioning through PMDA-aligned certification standards.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Tate & Lyle |
| Roquette Frères |
| Ingredion Incorporated |
| Avebe |
| Emsland-Stärke GmbH |
| Grain Processing Corporation |
| Matsutani Chemical Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned European starch houses and agribusiness conglomerates with captive corn processing networks anchor supply discipline, translating feedstock concentration in the U.S. Midwest and enzymatic processing clusters in the Netherlands into tiered pricing power that rewards verified carbon accounting and punishes spot-market volatility.
Pricing Analysis
Lead-time compression commands premium positioning, with pharmaceutical formulators in Mumbai and Hyderabad paying up for cyclodextrin lots delivered within days versus standard four-week cycles. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-NF certified excipients from commodity maltodextrin, with certification premiums widening as CDSCO and PMDA alignment tightens. Cost compression in industrial-grade white dextrin is intensifying because REACH compliance investments filter smaller European adhesive suppliers from contract panels. Chemical industry buyers in Germany and Belgium exhibit highest price sensitivity, while oncology drug manufacturers in Japan accept substantial premiums for host-guest complexation purity.
Supply Chain Analysis
Return flows of spent enzymatic catalysts and acid hydrolysis byproducts to specialized reprocessors in Belgium and the Netherlands complete circular material loops that reduce virgin input dependence. Supply concentrates in the United States, France, and India, with corn belt processing in Iowa and Illinois, pea starch diversification in northern France, and pharmaceutical excipient refinement in Maharashtra. Raw material draws from U.S. Midwest grain belts, Canadian non-GMO pea crops, and Indian tapioca starch streams. Single-source vulnerability runs through El Niño-exposed corn harvests that spike input costs unpredictably. Distribution runs through B2B platforms disintermediating traditional chemical distributors for Indian pharmaceutical formulators, alongside long-term offtake contracts governing European food conglomerate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive starch processing and downstream excipient certification capabilities defines competitive positioning, with players racing to control feedstock origination and pharmaceutical-grade validation pipelines simultaneously.
For Market Incumbents: To counter enzymatic processing modularization by Danish and Dutch technology firms deploying plug-and-play reactor skids, Cargill-scale integrated processors should expand dedicated regulatory affairs divisions to capture REACH-consolidated adhesive contracts in Cologne and Hamburg industrial zones, while accelerating pea starch dextrin capacity at Canadian facilities to lock plant-based meat analog formulations. For New Entrants and Emerging Players: The price-point gap between PMDA-certified cyclodextrin premiums and food-grade maltodextrin commodities offers entry traction for regional enzymatic refiners serving Mumbai and Hyderabad pharmaceutical clusters with IPEC-PQG audit-ready facilities, bypassing incumbent distributor networks through direct-to-manufacturer digital procurement platforms that compress lead times from weeks to days. For Investors and Strategic Acquirers: CDSCO acceleration of excipient master file approvals is the leading indicator that Indian pharmaceutical dextrin demand is structurally tightening, suggesting five-to-ten year viability for specialized refiners with cyclodextrin purity capabilities; acquisition targets should show validated analytical protocols and existing relationships with generic drug exporters, with monitoring focus on FDA Type II drug master file review timelines that signal capital freeze duration in pipeline products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Processing | Captive corn and pea starch supply secures margin control against El Niño price spikes. |
| Pharmaceutical-Grade Certification Investment | USP-NF and PMDA alignment unlocks oncology drug solubilization contracts at premium pricing. |
| Enzymatic Processing Retrofit | Continuous reactor modularization reduces capital requirements versus batch acid hydrolysis installations. |
| Direct-to-Manufacturer Digital Platform | B2B procurement disintermediation captures Indian pharmaceutical formulator volumes from distributor networks. |
| Multi-Feedstock Diversification | Pea and potato starch alternatives reduce single-crop volatility exposure in binding applications. |
Methodological Framework
SEC 10-K filings, CDSCO regulatory submissions, and ECHA registration databases formed the secondary backbone, cross-referenced with primary interviews involving starch processing plant managers, pharmaceutical procurement leads at Mumbai and Hyderabad formulation clusters, and regulatory affairs directors at European adhesive manufacturers. Bottom-up and top-down triangulation validated volume estimates across maltodextrin, cyclic dextrin, and industrial dextrin product tiers.
Bottom-up modeling anchored projections, with top-down macroeconomic validation across the analysis window. Segmentation dimensions included dextrose equivalent thresholds, excipient certification grades, application-specific regulatory jurisdictions, and regional production hub concentration. CAGRs derived from historical volume trajectories adjusted for REACH compliance filtering effects and pharmaceutical excipient demand elasticity. Industry-specific inputs encompassed corn price volatility indices, enzymatic processing capacity expansion announcements, and carbon accounting verification rates under EU Green Deal frameworks.
Inputs from CDSCO filing databases and ECHA polymer registration updates were available through the study window; gaps in real-time corn futures correlation data introduce uncertainty bands around feedstock cost assumptions. Practitioners should monitor FDA Type II drug master file approval velocity and El Niño cycle projections for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Bulk Molding Compounds Market