
 Paint Additives Market | 2026-2036
Paint Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Additives Market Outlook
Waterborne formulation technology is reshaping how paint manufacturers engineer viscosity stability and substrate adhesion. BASF SE leverages its integrated surfactant portfolio to anchor supply relationships with European automotive OEMs transitioning coating lines. Arkema Group specializes in rheology modifiers that sustain performance in high-solids aqueous systems, while Dow Inc. competes through geographic dominance in North American construction coatings channels.
Paint additives comprise surface-active chemicals, polymeric dispersants, and organoclays dosed at 0.1-5.0 wt% to control flow, prevent pigment flocculation, and extend shelf stability in liquid coatings. Their primary commercial purpose is to enable consistent application properties across varying temperature and humidity conditions during film formation. Dispersants command the deepest margin pools due to patent-protected graft copolymer architectures that lock pigment particles in colloidal suspension. Solvent-based formulations remain structurally entrenched in industrial maintenance and marine segments where corrosion resistance specifications resist waterborne substitution, while aqueous systems in decorative end uses are absorbing the fastest volume growth as VOC regulations tighten.
EPA regulates VOC content under 40 CFR Part 59, ECHA enforces REACH restrictions on hazardous substance registration, and China's MEE implements GB standards limiting solvent emissions from coating operations. These frameworks collectively shift procurement toward low-VOC additive packages certified for regulatory compliance. Stakeholders must monitor how dual carbon targets in China and the EU Green Deal's chemical sustainability criteria will redefine acceptable additive chemistries before the next formulation cycle locks in.
Market Dynamics
Waterborne coating reformulation is compressing demand for solvent-compatible additives while amplifying procurement of rheology modifiers and dispersants engineered for aqueous stability. Multinational coating houses face simultaneous pressure from VOC regulations and performance specifications that legacy additive packages cannot satisfy.
Growth Catalysts
- GB Standards on VOC Emissions:China's MEE enforcement limits solvent content in architectural coatings, compelling domestic paint manufacturers to adopt waterborne additive packages certified for compliance.
- Automotive OEM Transition:European vehicle manufacturers are converting coating lines to high-solids aqueous systems, generating concentrated demand for dispersants that sustain pigment suspension under accelerated cure cycles.
- Construction Coatings Volume:Residential and commercial building activity across Asia-Pacific is absorbing higher volumes of shelf-stabilized water-based paints requiring specialized rheology control.
Market Restraints
- Petrochemical Feedstock Volatility:Polymeric dispersant production depends on acrylate and urethane precursor supply chains exposed to naphtha price swings.
- Patent-Protected Architectures:Graft copolymer intellectual property held by incumbent suppliers limits formulation freedom for regional additive compounders.
- Solvent System Entrenchment:Marine and industrial maintenance specifications specify corrosion resistance thresholds that waterborne technologies have not yet achieved.
Strategic Opportunities
- India Architectural Penetration:Waterborne decorative coatings remain underpenetrated relative to solvent alternatives, creating white space for dispersant suppliers establishing local technical service presence.
- EU Green Deal Chemical Criteria:The European Commission's sustainability taxonomy will favor bio-based rheology modifiers in public procurement, rewarding early certification investments.
- Digital Formulation Platforms:Machine learning tools predicting additive-pigment compatibility are compressing development cycles and enabling remote technical support for distant customers.
Industry Challenges
- Colloidal Chemistry Expertise Scarcity:Formulation laboratories lack sufficient trained personnel to optimize dispersant selection across expanding waterborne product portfolios.
- REACH Registration Burden:ECHA data requirements for novel additive chemistries extend commercialization timelines and consume regulatory affairs capacity.
- Legacy Equipment Retrofit Costs:Coating manufacturers face capital intensity in converting solvent-based production lines to handle higher-water-content formulations without corrosion damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Additives Market |
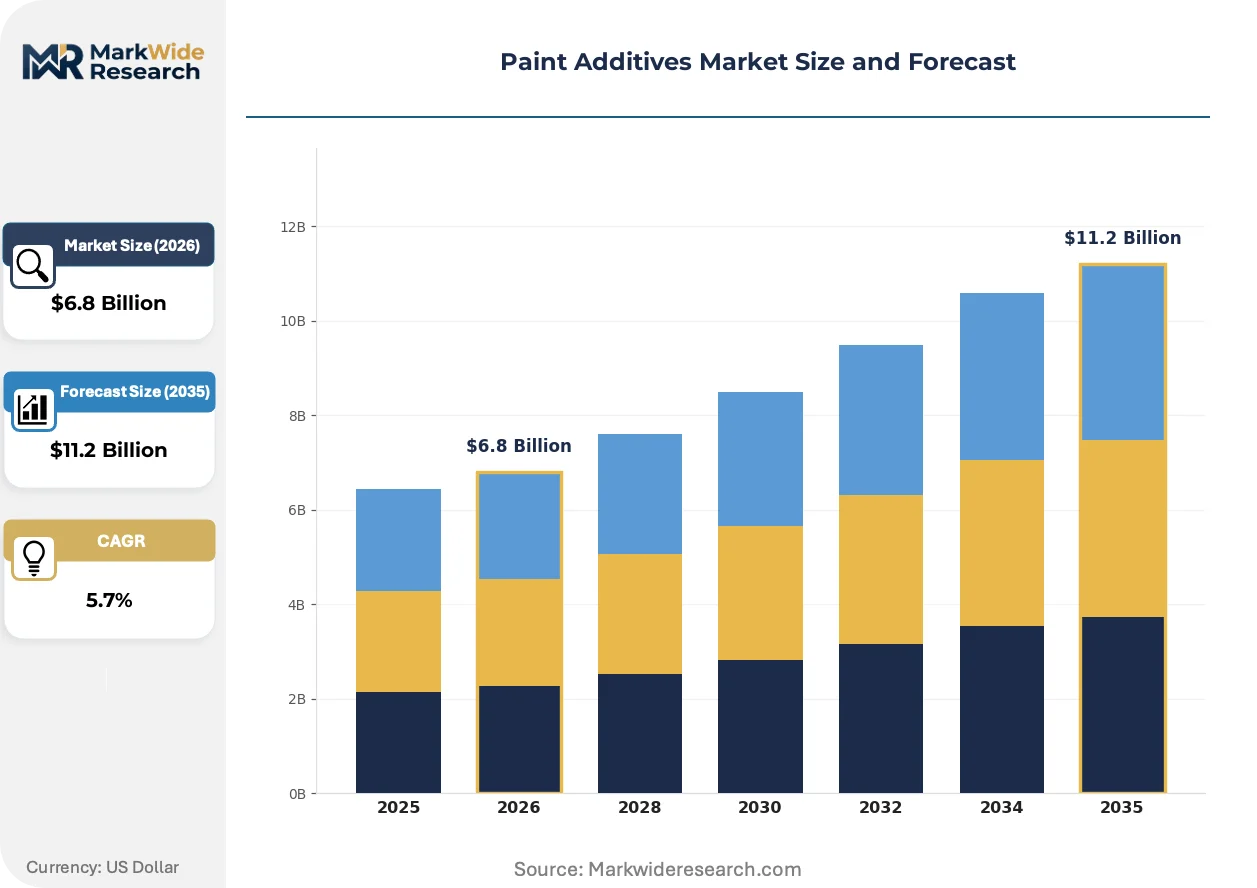
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Dispersants, Rheology Modifiers, Colorants Function: Flow Aid, Defoamer, Wetting Agent, Anti-settling Agent Formulation Type: Aqueous, Solvent-based, Powdered, Concentrate End User: Construction, Automotive, Industrial, Decorative |
| Companies Covered | Eastman Chemical Company, Clariant AG, BASF SE, Ashland Global Holdings Inc., Allnex GmbH, Evonik Industries AG, Arkema Group, Altana Group, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Additives Market Strategic Shifts
Additive suppliers are engineering functionality that transcends traditional viscosity control, embedding sensors-responsive behavior and sustainability credentials directly into molecular architecture. These advances are compressing the performance gap between regulatory-compliant and premium-performance coating systems.
Responsive rheology modifiers incorporating stimuli-sensitive polymer networks are rendering obsolete static viscosity control in temperature-variable application environments. Automotive OEMs in Germany and Japan are piloting these materials for robotic spray applications where ambient humidity fluctuates. The technology is rendering obsolete conventional organoclay thickeners that require extended shear histories to activate.
REACH authorization procedures for persistent organic pollutants are forcing reformulation of legacy biocide packages used in can preservation. ECHA's sunset date scheduling creates predictable compliance windows that coating manufacturers use to synchronize additive procurement transitions. Decorative paint portfolios in Northern Europe face the most compressed substitution timelines as authorization deadlines approach.
Specification-driven procurement now dominates large contractor relationships, with certified low-VOC additive packages becoming mandatory for project eligibility rather than discretionary quality premiums. Distributor technical service teams in China are displacing traditional broker relationships by embedding formulation support directly into logistics contracts. This pattern concentrates most visibly in municipal infrastructure coating tenders where compliance documentation requirements have intensified.
Paint Additives Market Segmentation
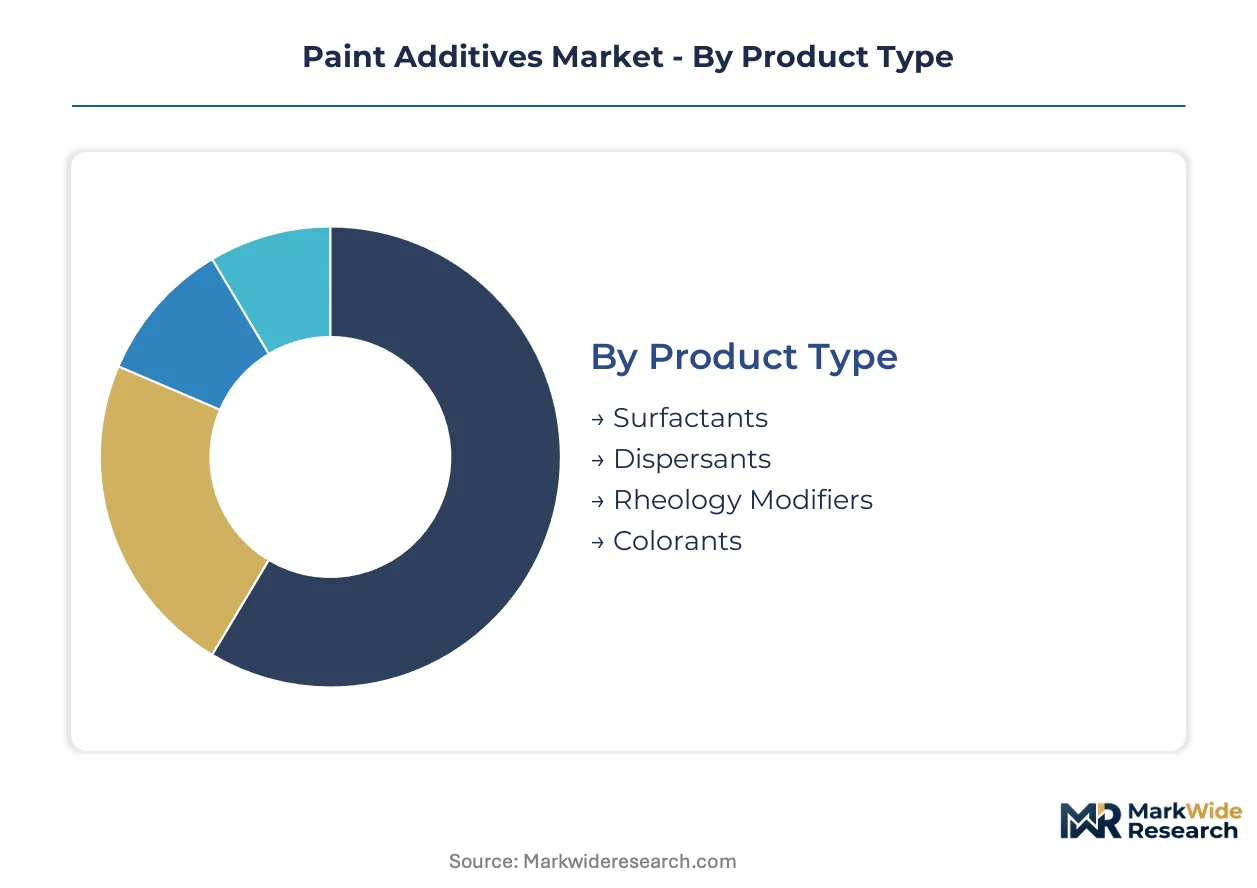
Paint additive procurement patterns diverge sharply across formulation requirements and end-use specifications. Segment-level dynamics reveal where technical service investments yield returns and where commoditization pressures concentrate.
Product Type:
Rheology modifiers and dispersants turn over fastest as waterborne reformulation accelerates, while surfactant specifications shift more gradually with established supply relationships.
- Dispersants:Graft copolymer architectures lock pigment particles in colloidal suspension through steric stabilization mechanisms. Demand concentrates in European automotive OEM coating lines converting to high-solids aqueous cure cycles, where pigment suspension under accelerated thermal profiles determines film quality. Patent-protected molecular designs sustain margin premiums against generic alternatives.
- Rheology Modifiers:Polymeric thickeners and organoclays control viscosity profiles across shear-rate ranges during application and storage. Construction coatings in China absorb expanding volumes as domestic architectural paint production scales and local additive suppliers expand manufacturing capacity. Stimuli-responsive polymer networks are displacing conventional organoclay systems in temperature-variable environments.
- Surfactants:Surface-active chemicals reduce interfacial tension between coating components and substrates.
- Colorants:Pigment dispersions and dye systems provide optical properties and hiding power.
Surfactants dominate installed base. Rheology modifiers are where expansion concentrates.
Function:
Cost tier stratification separates premium functional additives from commodity flow aids, with defoamer procurement showing highest price sensitivity in volume decorative applications.
- Wetting Agent:Surfactant systems reduce surface tension to enable substrate penetration and film adhesion. Automotive OEM specifications in Germany and Japan mandate wetting performance under robotic spray conditions where substrate contamination varies. Reformulation investments follow REACH restrictions on legacy fluorosurfactant chemistries.
- Defoamer:Silicone and mineral oil systems collapse foam generated during high-speed dispersion and application. Decorative paint manufacturers in India prioritize cost-optimized defoamer packages as waterborne penetration expands in price-sensitive architectural segments. Technical service requirements are minimal compared to dispersant selection.
- Flow Aid:Additives modify surface tension to control leveling and eliminate surface defects.
- Anti-settling Agent:Thixotropic systems prevent pigment and filler sedimentation during storage.
Flow aids dominate installed base. Wetting agents are gaining share fastest.
Formulation Type:
Volume concentration in aqueous systems is accelerating procurement shifts, while solvent-based formulations retain structural entrenchment in corrosion-resistant industrial segments.
- Aqueous:Water-based additive packages engineered for hydrolytic stability and freeze-thaw resistance. Construction coatings across Asia-Pacific absorb higher volumes as China's GB standards on VOC emissions compel domestic paint manufacturers toward certified compliance formulations. Shelf stability requirements drive dispersant selection complexity.
- Solvent-based:Hydrocarbon-compatible additives for alkyd and epoxy systems. Marine and industrial maintenance specifications in Europe specify corrosion resistance thresholds that waterborne technologies have not yet achieved, preserving demand for solvent-compatible rheology control. REACH authorization timelines create predictable substitution windows.
- Powdered:Solid additive concentrates for powder coating applications.
- Concentrate:High-active-content liquid dispersions for automated dosing systems.
Solvent-based systems dominate installed base. Aqueous formulations are where expansion concentrates.
End User:
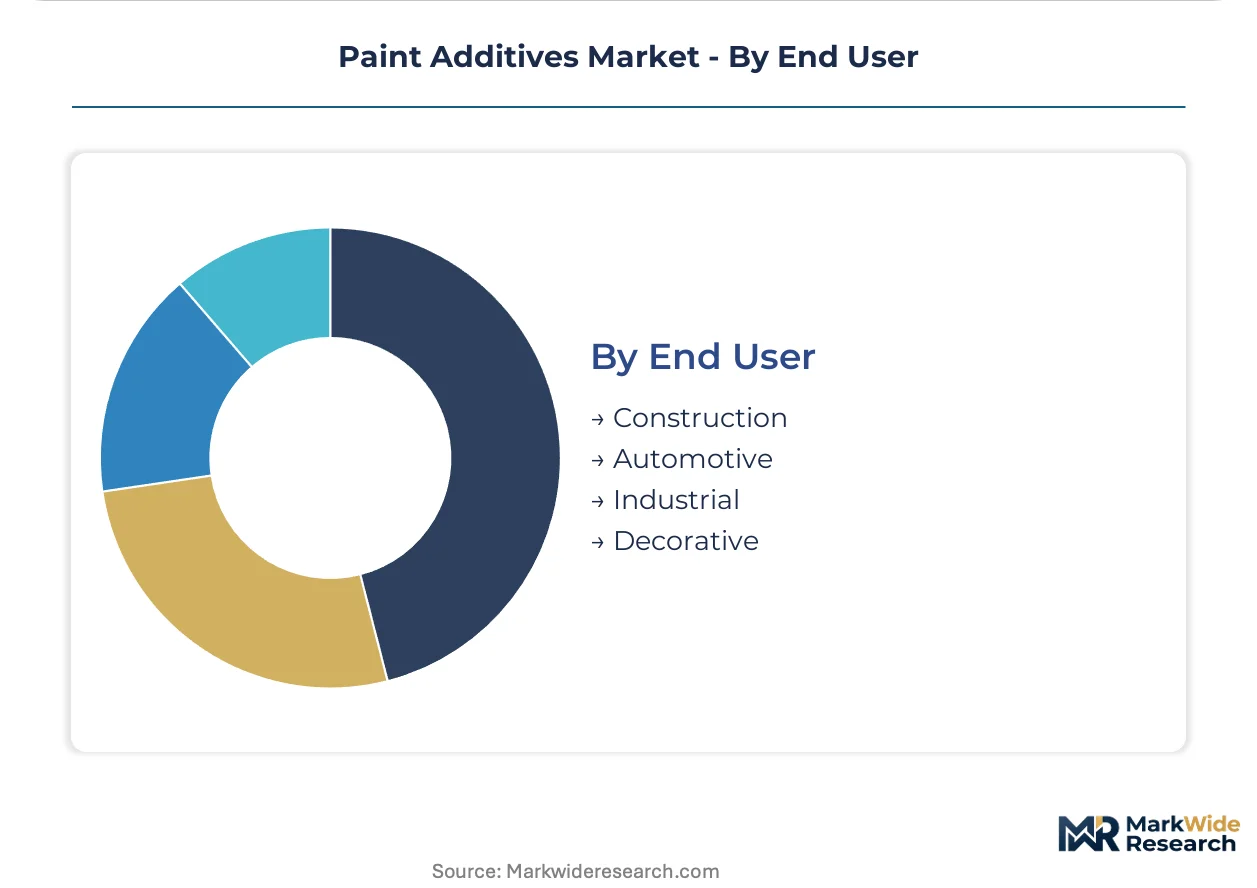
Customer type segmentation separates specification-driven procurement in automotive and industrial from price-sensitive decorative volume, with construction occupying intermediate technical service intensity.
- Construction:Architectural and protective coatings for residential, commercial, and infrastructure applications. Municipal infrastructure tenders in China intensify compliance documentation requirements, embedding formulation support into distributor logistics contracts. Rheology modifiers sustain performance across variable temperature and humidity conditions during film formation.
- Automotive:OEM and refinish coating systems with exacting appearance and durability specifications. European vehicle manufacturers generate concentrated demand for dispersants that sustain pigment suspension under accelerated cure cycles, with technical relationships anchored by integrated surfactant portfolios.
- Industrial:Protective and functional coatings for machinery, equipment, and process environments.
- Decorative:Consumer and professional architectural paints with performance differentiated by price tier.
Decorative coatings dominate installed base. Construction applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and construction contractors concentrate procurement power in Germany, China, and the United States, with regulatory pressure amplifying demand for certified low-VOC additive packages across these markets.
Germany
Automotive coating lines in Stuttgart and Munich generate concentrated demand for dispersants sustaining pigment suspension under accelerated cure cycles. ECHA enforces REACH authorization timelines for legacy biocide packages, forcing synchronized procurement transitions. BASF SE anchors supply relationships through integrated surfactant portfolios serving Volkswagen and BMW coating operations.
China
Domestic architectural paint production scales rapidly in Shanghai and Guangdong provinces, absorbing expanding volumes of rheology modifiers. MEE implements GB standards limiting solvent emissions, compelling reformulation investments across multinational coating portfolios. Local additive suppliers expand manufacturing capacity in Jiangsu and Zhejiang to capture waterborne formulation demand.
United States
Construction coatings channels in Texas and California absorb shelf-stabilized water-based paints requiring specialized viscosity control. EPA regulates VOC content under 40 CFR Part 59, shifting procurement toward certified low-VOC additive packages. Dow Inc. competes through geographic dominance in North American distribution networks serving residential and commercial building activity.
India
Waterborne decorative coatings remain underpenetrated in Maharashtra and Gujarat relative to solvent alternatives, creating white space for dispersant suppliers. BIS standards on architectural coating quality intensify compliance documentation requirements for municipal infrastructure tenders. Technical service teams establish local presence in Mumbai and Ahmedabad to embed formulation support into logistics contracts.
Japan
Automotive OEMs in Toyota City and Yokohama pilot stimuli-responsive rheology modifiers for robotic spray applications. METI promotes chemical sustainability criteria aligned with EU Green Deal benchmarks, favoring bio-based additive architectures. Formulation laboratories in Kansai region face colloidal chemistry expertise scarcity as waterborne portfolios expand.
Paint Additives Market Competitive Environment
Channel-controlling players compete with product-specialist players across formulation-driven and specification-driven segments. The vendor base fragments between integrated chemical conglomerates with surfactant portfolios and focused additive compounders with patent-protected graft copolymer architectures. Three archetypes dominate: integrated surfactant suppliers anchoring automotive OEM relationships, rheology modifier specialists serving construction coatings channels, and regional compounders competing on price in decorative volume segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for waterborne formulation transitions.
Among integrated chemical conglomerates, BASF SE and Dow Inc. exemplify channel-controlling archetypes through geographic and portfolio breadth. Arkema Group occupies a position within the product-specialist tier, representing focused expertise in rheology modifiers for high-solids aqueous systems. Evonik Industries AG sits within the premium functional additives segment, anchoring supply relationships through specialty chemical positioning. These three companies illustrate how competitive positioning stratifies between scale-driven coverage and technical-specialization depth.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Clariant AG |
| BASF SE |
| Ashland Global Holdings Inc. |
| Allnex GmbH |
| Evonik Industries AG |
| Arkema Group |
| Altana Group |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Acrylate and urethane precursor supply chains centered in Germany, China, and the United States anchor margin pools downstream in patent-protected graft copolymer dispersants. Naphtha price volatility transmits directly into polymeric additive production costs, compressing returns for regional compounders lacking backward integration into surfactant feedstocks.
Pricing Analysis
Cost-plus contracts with naphtha indexation dominate long-term supply agreements between multinational additive houses and European automotive OEMs. Price differentiation separates REACH-certified premium tiers from generic alternatives in Asian decorative markets, with certification grade and volume scale as primary levers. Pricing pressure stems from local Chinese suppliers expanding aqueous rheology modifier capacity. Decorative paint manufacturers in India exhibit highest price sensitivity, while German automotive coating lines accept premium dispersant pricing for pigment suspension performance.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard in distributor relationships across Asia-Pacific construction coatings channels. Manufacturing concentrates in China, Germany, and the United States, with Jiangsu and Zhejiang provinces absorbing new capacity investments. Raw material dependencies include acrylate monomers, organoclay feedstocks, and silicone precursors. Single-source vulnerability persists in patent-protected graft copolymer architectures held by incumbent suppliers. Distribution runs through technical service-embedded logistics contracts in municipal infrastructure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions expand faster than base additive volumes as coating manufacturers outsource colloidal chemistry expertise. Recurring revenue from remote compatibility testing and machine-learning platform access now exceeds hardware margins in customer relationships.
For Market Incumbents: Build regulatory certification moats through early REACH authorization investments for novel biocide alternatives. Anchor automotive OEM relationships with integrated surfactant portfolios that lock in dispersant specification. Capacity addition in Jiangsu province captures waterborne formulation demand from scaling Chinese architectural paint producers. Patent-protected graft copolymer architectures defend margin position against regional compounders. For New Entrants and Emerging Players: Pursue white-space expansion in India's underpenetrated waterborne decorative coatings market. Establish local technical service presence in Mumbai and Ahmedabad to embed formulation support into distributor logistics contracts. Target municipal infrastructure tenders where BIS compliance documentation requirements intensify procurement complexity. Digital formulation platforms offering remote additive-pigment compatibility prediction compress development cycles for distant customers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional additive compounders in Asia-Pacific lacking backward integration into surfactant feedstocks. Long-term viability over the analysis window favors specialists with patent-protected aqueous rheology modifier portfolios and automotive OEM technical relationships. Acquisition targets include India-focused dispersant suppliers with established BIS certification pathways. Watch ECHA sunset date scheduling for biocide authorizations as inflection indicator for reformulation-driven procurement transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylate Feedstocks | Captive precursor supply insulates margin from naphtha volatility in German production. |
| Green Manufacturing Transition | Bio-based rheology modifiers align with EU Green Deal chemical sustainability criteria for public procurement. |
| Long-term Supply Agreement | Automotive OEM coating lines in Stuttgart lock in dispersant volumes under accelerated cure specifications. |
| Joint Venture | Local manufacturing partnerships in Jiangsu province capture GB standards-driven waterborne demand. |
| Digital Formulation Platform Launch | Machine learning tools predict additive-pigment compatibility for remote technical service delivery. |
Study Parameters
The analysis maps dispersant, rheology modifier, surfactant, and colorant sub-sectors, each validated through formulation laboratory directors, coating manufacturer procurement leads, and distributor technical service teams. Primary interviews with ECHA regulatory affairs specialists and MEE compliance officers cross-check policy impact assumptions. Secondary sources include customs and trade data, SEC 10-K filings, and Cefic sector reports. Bottom-up additive volume estimates triangulate against top-down coating production forecasts.
Assumptions hold REACH authorization timelines and China's GB standards enforcement fixed, while varying naphtha price trajectories and automotive OEM conversion rates across the projection horizon. Segmentation dimensions include product type, formulation chemistry, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity modeling of coating production growth against additive loading rates. Industry-specific inputs capture waterborne penetration curves and patent expiration schedules.
Sensitivities concentrate around MEE enforcement intensity, ECHA authorization delays, and automotive OEM coating line conversion pace. Forecasts reflect documented assumptions about regulatory compliance windows and feedstock cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Crosslinking Agents Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Calcium Diglutamate Market
Additives
Automotive Additives Market
Additives
Global Corrosion Inhibitor Market
Additives
China Sodium Reduction Ingredient Market
Additives
Global PVC Additives Market
Additives
Competitive Inhibitors Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Glyceryl Caprylate Market
Additives
Encapsulated Citric Acid Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Metal Modifiers Market
Additives
Tartaric Acid Market
Additives
Global Feed Acidifiers Market