
 Global Chlorinated Paraffin Wax Market | 2026-2036
Global Chlorinated Paraffin Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorinated Paraffin Wax Market Intelligence
Demand from large-volume industrial users in plastics and coatings is bifurcating the market from smaller, specialized buyers in niche lubricant applications. KLJ Group leverages its significant manufacturing scale to serve the high-volume plastic additives segment. In contrast, Dover Chemical Corporation differentiates through its focus on specialized formulations for metalworking fluids. INOVYN sustains a strong position in Europe, navigating complex regional chemical regulations and maintaining supply for critical end-uses.
Chlorinated paraffin wax consists of polychlorinated n-alkanes, produced by chlorinating paraffin fractions. Its properties, determined by carbon chain length and chlorine content typically ranging from 30% to 70%, make it a valuable secondary plasticizer in PVC and a flame retardant in various polymers. While medium-chain and long-chain variants gain traction due to regulatory pressures on short-chain types, plastic additives and metalworking fluids remain the largest application segments by volume. The flame retardants application represents a high-value niche, commanding premium pricing for certified grades.
The European Chemicals Agency's (ECHA) classification of short-chain chlorinated paraffins (SCCPs) as a Substance of Very High Concern under REACH severely restricts their use in the EU. Similarly, the U.S. EPA monitors these substances under the Toxic Substances Control Act, while producers in China must comply with evolving MEE environmental standards. Consequently, successful market participation now depends on developing and commercializing cost-effective, compliant medium-chain and long-chain alternatives.
Market Dynamics
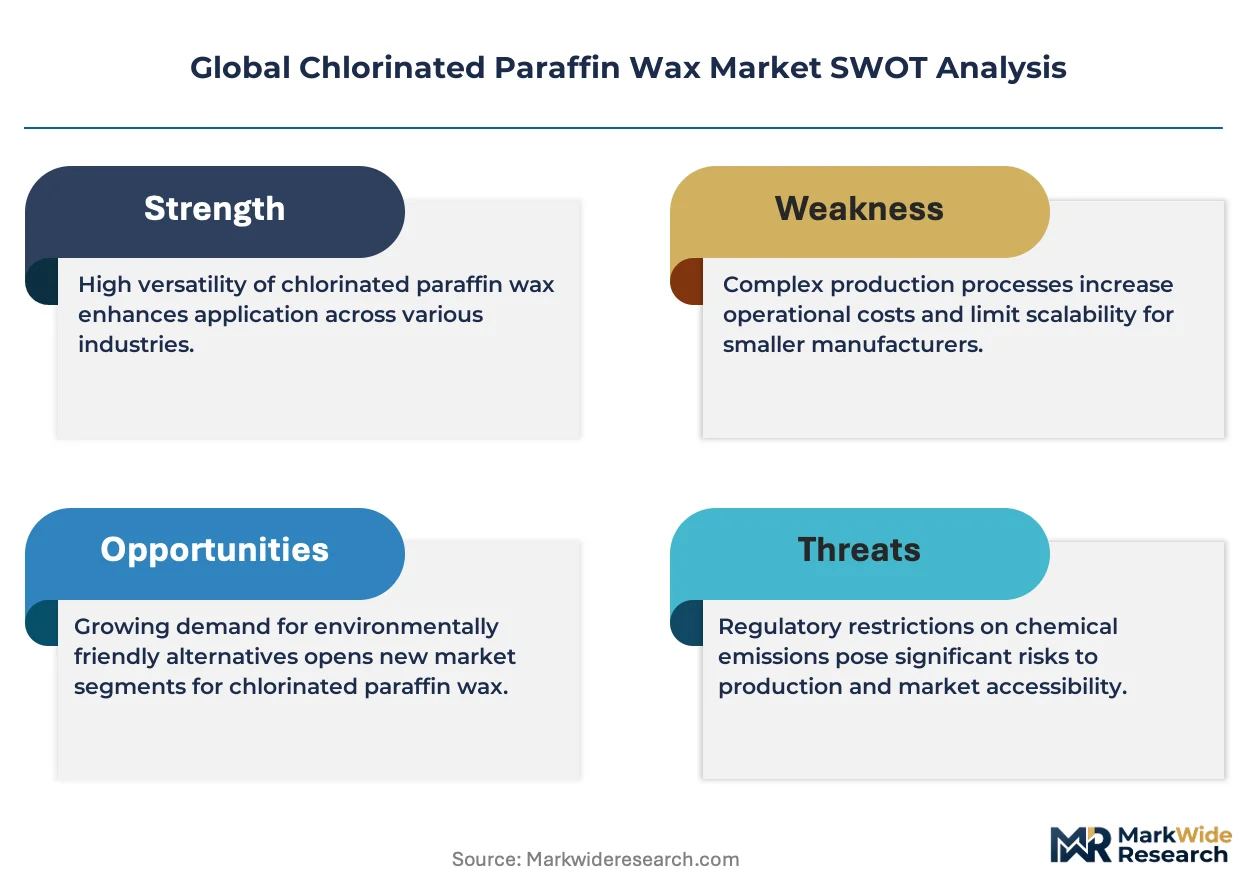
The chlorinated paraffin wax market is defined by a fundamental regulatory pressure forcing product substitution. Global restrictions on short-chain chlorinated paraffins (SCCPs), led by frameworks like the EU's REACH, compel a market-wide shift toward medium-chain and long-chain alternatives.
Growth Catalysts
- Industrial Expansion in Asia:Demand for metalworking fluids and PVC compounds in rapidly industrializing economies, particularly India and Vietnam, provides a consistent volume driver for chlorinated paraffins used as extreme pressure additives and secondary plasticizers.
- Shift to Compliant Alternatives:Regulatory phase-outs of SCCPs directly stimulate demand for medium-chain (MCCP) and long-chain (LCCP) chlorinated paraffins, creating a growth segment for producers who have invested in compliant production capabilities.
- Flame Retardant Applications:The incorporation of chlorinated paraffins as cost-effective flame retardants in materials like rubber, textiles, and coatings for the construction industry continues to support market growth, especially for certified grades.
Market Restraints
- Intense Regulatory Scrutiny:The classification of SCCPs as Substances of Very High Concern by ECHA in Europe and similar monitoring by the U.S. EPA creates significant compliance burdens and restricts market access for non-compliant products.
- Threat from Substitutes:Non-halogenated flame retardants, such as phosphate esters and aluminum trihydroxide, as well as alternative plasticizers like dioctyl terephthalate (DOTP), pose a significant substitution threat in sensitive applications.
- Feedstock Price Volatility:The market is exposed to price fluctuations in its primary raw materials, paraffin (derived from crude oil) and chlorine, which can compress manufacturer margins and create price instability for end-users.
Strategic Opportunities
- High-Value Formulation Development:There is a clear opportunity in developing specialized, high-chlorine-content LCCPs for demanding flame retardant applications in electronics and transportation, which command premium pricing over commodity grades.
- Bio-Based Paraffin Feedstocks:Research into synthesizing paraffin waxes from bio-based sources presents a long-term opportunity to develop a new class of products with an improved environmental profile, appealing to sustainability-focused customers.
- Geographic Expansion in South America:Markets like Brazil and Argentina, with growing industrial and manufacturing bases but limited local production, represent an untapped opportunity for exporting compliant MCCP and LCCP formulations for plastics and lubricants.
Industry Challenges
- Complex Reformulation Cycles:End-users in sectors like PVC compounding and coatings face long and costly reformulation and testing cycles to qualify products made with SCCP alternatives, slowing the adoption rate of new materials.
- Supply Chain Concentration:Heavy reliance on China for both raw material chlorination and finished product supply creates logistical risks and exposure to shifts in Chinese domestic environmental policy or export controls.
- Capital Investment for Conversion:Modifying or building new production lines to manufacture specific medium-chain and long-chain chlorinated paraffins requires significant capital expenditure, creating a barrier for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorinated Paraffin Wax Market |
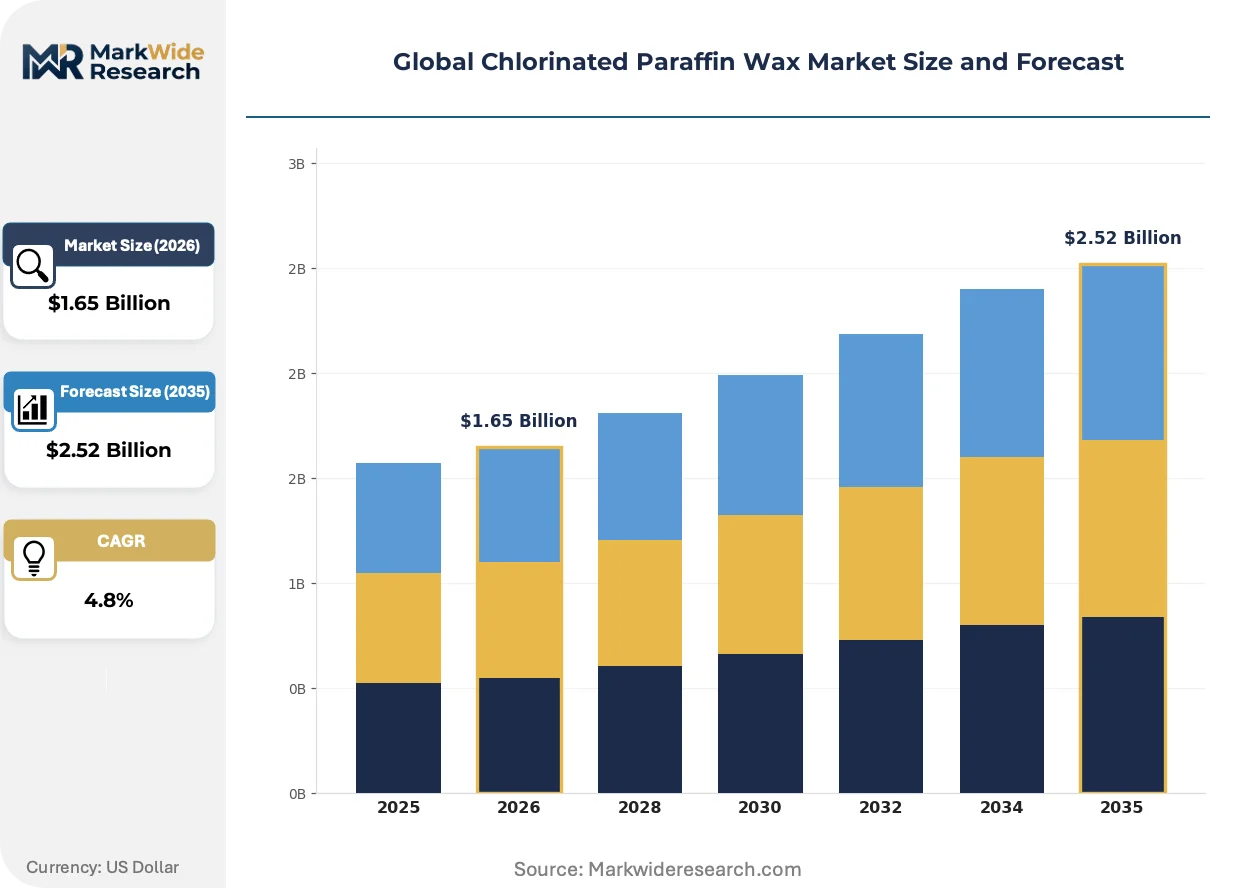
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Chain, Medium Chain, Long Chain, Blend Application: Plastic Additives, Metalworking Fluids, Paints & Coatings, Flame Retardants, Lubricants Packaging Type: Drums, Bags, Bulk Containers, Cartons End Use Industry: Construction, Electronics, Textile Manufacturing, Chemical Processing |
| Companies Covered | NCP Chlorchem, KLJ Group, Dover Chemical Corporation, Altair Chimica SpA, Makwell Group, Aditya Birla Chemicals, LEUNA Tenside GmbH, JSC Kaustik, INOVYN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorinated Paraffin Wax Market Strategic Shifts & Innovations
Product innovation is focused on creating cost-effective and compliant medium-chain and long-chain alternatives to meet stringent global regulations. This shift is driving new developments in formulation science and creating demand for greater supply chain transparency and certification.
Synergistic additive packages are becoming essential for formulating with compliant MCCPs and LCCPs. PVC compounders and lubricant blenders are increasingly adopting these multi-component systems to achieve desired performance metrics. This trend is miniaturizing the functional role of the primary chlorinated paraffin within the final product, embedding it within a more complex and precise chemical system.
The Stockholm Convention on Persistent Organic Pollutants has listed SCCPs for global elimination, creating a powerful international mandate for their phase-out. This forces producers in major manufacturing countries like China and India to align with global standards, not just for export. Small and medium-sized formulators in developing economies are most affected, facing pressure to secure compliant material or risk exclusion from global supply chains.
A clear behavioral shift toward certification-driven procurement is underway among industrial buyers. This trend is disrupting traditional purchasing based on price alone, especially in the European Union, where importers demand extensive compliance documentation for REACH. This preference for fully documented, compliant materials is most visible in the automotive and construction sectors, which require strict material declarations.
Global Chlorinated Paraffin Wax Market Segmentation
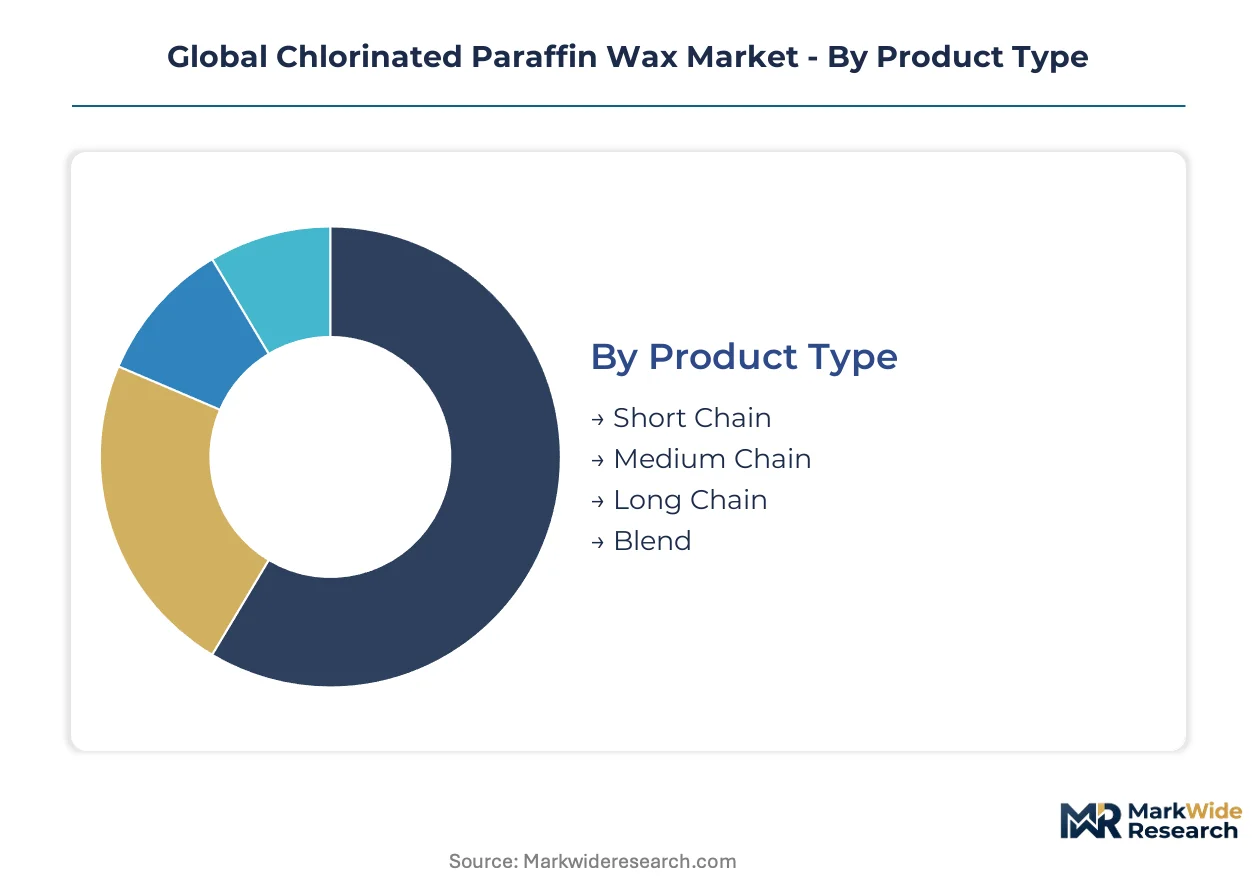
Understanding the segmentation of the global chlorinated paraffin wax market is critical for identifying specific demand drivers and regulatory impacts across various product types, applications, packaging, and end-use industries. This breakdown highlights where innovation and compliance efforts are most concentrated.
Product Type:
The distribution channels for chlorinated paraffin wax are significantly influenced by its product type, with different formulations flowing through specialized supply chains to meet varied industrial requirements.
- Medium Chain:MCCPs feature 14-17 carbon atoms and 40-70% chlorine content, offering a balanced performance profile. Demand concentrates in PVC and metalworking fluids in India and Vietnam, driven by regulatory shifts away from short-chain variants.
- Long Chain:LCCPs possess 18-30 carbon atoms and 40-70% chlorine, offering higher thermal stability and lower volatility. High-value formulations for electronics and transportation in Europe gain traction, commanding premium pricing for certified grades.
- Short Chain:SCCPs contain 10-13 carbon atoms and 50-70% chlorine. Regulatory restrictions, especially from the EU's REACH and U.S. EPA monitoring, severely limit their use and market access.
- Blend:Blends combine different chain lengths to optimize performance and cost for specific applications. These formulations target a balance of regulatory compliance with desired technical properties.
Short Chain chlorinated paraffins dominate the historical installed base. Medium Chain and Long Chain variants are where market expansion concentrates.
Application:
The volume consumption of chlorinated paraffin wax varies significantly across its diverse application landscape, with industrial sectors exhibiting distinct demand profiles.
- Plastic Additives:Chlorinated paraffins serve as secondary plasticizers in PVC compounds, enhancing flexibility, flame retardancy, and processing. Demand from construction and infrastructure projects in China and Southeast Asia remains a primary driver.
- Metalworking Fluids:These paraffins function as extreme pressure additives in lubricants, improving tool life and surface finish in machining operations. Industrial expansion in Asian economies, particularly for manufacturing, fuels consistent demand.
- Flame Retardants:Chlorinated paraffins provide cost-effective flame retardancy in polymers, textiles, and rubber materials. Certified grades find high-value niche applications in construction and automotive sectors.
- Paints & Coatings:They enhance film formation, adhesion, and flame resistance in various coating formulations. Industrial and protective coatings for infrastructure projects utilize these properties.
- Lubricants:Beyond metalworking, chlorinated paraffins are used in other specialized lubricant formulations. These include gear oils and hydraulic fluids requiring enhanced wear protection and stability.
Plastic Additives and Metalworking Fluids represent the most mature application segments. Flame Retardants demonstrate a strong growth trajectory due to increasing safety regulations.
Packaging Type:
Customer procurement patterns for chlorinated paraffin wax are directly influenced by the packaging type, reflecting varying logistical needs and scale of operations.
- Drums:Typically 200-250 liter steel or plastic containers, suitable for intermediate-volume users. These are common for specialty chemical distributors and medium-sized industrial manufacturers globally.
- Bulk Containers:Large ISO tanks or flexi-bags holding thousands of liters, designed for high-volume transport. Major industrial consumers like large PVC compounders or lubricant blenders in China and Europe prefer this cost-effective option.
- Bags:Multi-layer bags, often 25kg or 50kg, used for solid or flaked chlorinated paraffins. Smaller formulators and those requiring precise batch weighing utilize this format.
- Cartons:Typically used for smaller quantities or specific solid grades, often for research and development or very niche applications. These offer ease of handling for specialized buyers.
Bulk Containers offer the lowest unit cost for large-scale procurement. Drums provide a balanced solution for medium-volume needs, balancing cost and handling convenience.
End Use Industry:
The profitability profile for chlorinated paraffin wax suppliers varies across end-use industries, with some sectors demanding higher-value, specialized formulations.
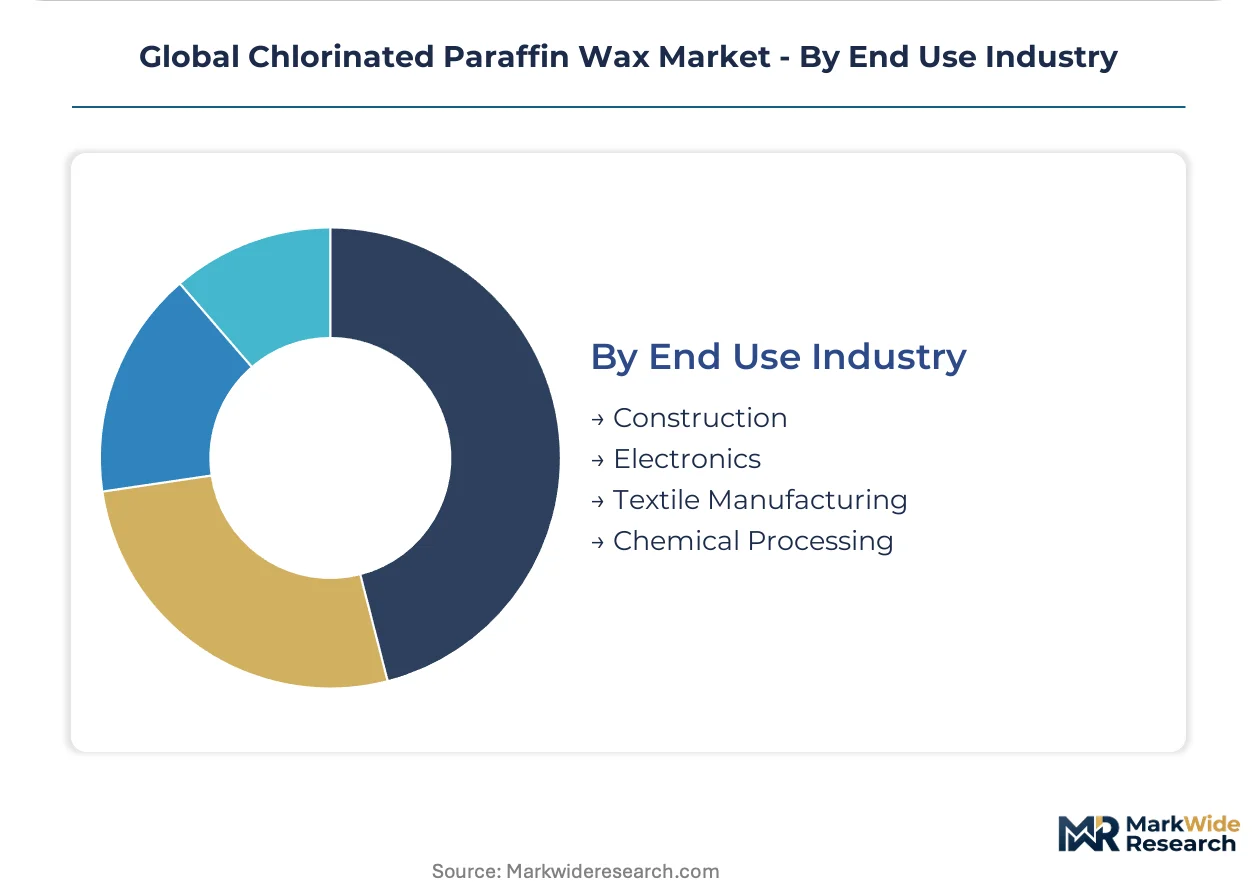
- Construction:This industry primarily utilizes chlorinated paraffins in PVC compounds for pipes, cables, and profiles, acting as plasticizers and flame retardants. Rapid urbanization and infrastructure development in developing economies drive substantial demand.
- Electronics:High-chlorine content LCCPs serve as critical flame retardants in electronic components, cables, and casings, meeting stringent safety standards. Premium pricing is commanded for certified grades used in advanced electronics manufacturing.
- Textile Manufacturing:Chlorinated paraffins are incorporated into textile coatings to impart flame retardancy and improve durability. Technical textiles and specialized fabrics for industrial applications represent key usage areas.
- Chemical Processing:Used as intermediates or additives in various chemical formulations beyond their primary applications. This includes their role in certain adhesive and sealant compositions.
Supply of commodity grades concentrates heavily in the Construction sector. The Electronics industry demands specialized, certified materials, leading to more focused supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chlorinated paraffin wax production capabilities serve its domestic market and export channels, supplying industrial users across Asia. This global trade flow supports demand in rapidly industrializing economies. European manufacturers also maintain critical supply chains within the region, navigating complex regulatory landscapes.
China
China's construction sector drives demand for PVC compounds, utilizing chlorinated paraffins as plasticizers. The Ministry of Ecology and Environment (MEE) implements evolving environmental standards for chemical producers. Industrial clusters in the Yangtze River Delta, particularly around Shanghai, focus on high-volume production and export.
India
India's manufacturing expansion consistently requires metalworking fluids and PVC additives. The Bureau of Indian Standards (BIS) continually updates material specifications for industrial chemicals. Industrial centers like Gujarat and Maharashtra exhibit strong demand for compliant chlorinated paraffin formulations.
Vietnam
Vietnam's burgeoning infrastructure projects and manufacturing base create consistent demand for plastic additives. The country's Ministry of Natural Resources and Environment (MONRE) monitors chemical imports and domestic production. Industrial zones near Ho Chi Minh City are significant consumers of these materials for various applications.
Germany
Germany's advanced manufacturing industries require specialized flame retardants and lubricant additives. The European Chemicals Agency (ECHA) strictly enforces REACH regulations, particularly concerning short-chain chlorinated paraffins. Chemical parks in regions like North Rhine-Westphalia are hubs for developing compliant alternatives.
United States
United States industrial growth, especially in automotive and construction, supports demand for specialized lubricants and PVC. The Environmental Protection Agency (EPA) monitors chlorinated paraffin substances under the Toxic Substances Control Act. Manufacturing centers in the Midwest, such as around Detroit, utilize these additives in various industrial processes.
Global Chlorinated Paraffin Wax Market Key Industry Players
Player mix skews toward established chemical manufacturers and specialized formulators, creating a distinct market structure. The market exhibits a tiered structure, with large-scale producers supplying commodity grades for construction and plastics, while smaller entities focus on niche applications requiring higher compliance. Two strategic archetypes dominate: high-volume commodity suppliers driven by cost efficiency and innovation-driven specialty chemical companies developing compliant alternatives. Competitive moves include significant capital investment in new production lines for medium and long-chain variants, alongside the development of high-value formulations for demanding end-uses.
At the scale-driven end, KLJ Group represents manufacturers leveraging significant capacity to serve the high-volume plastic additives segment, particularly in rapidly industrializing Asian economies. Dover Chemical Corporation exemplifies specialized formulators, differentiating through a focus on advanced formulations for metalworking fluids, often targeting specific industrial sectors. INOVYN occupies a strong position in Europe, demonstrating expertise in navigating complex regional chemical regulations and maintaining critical supply for specific end-uses like construction and automotive. These companies collectively illustrate the market's strategic divide between broad commodity supply and specialized, compliant product development.
| Leading Market Players |
|---|
| NCP Chlorchem |
| KLJ Group |
| Dover Chemical Corporation |
| Altair Chimica SpA |
| Makwell Group |
| Aditya Birla Chemicals |
| LEUNA Tenside GmbH |
| JSC Kaustik |
| INOVYN |
| Others |
Cost & Logistics Intelligence
Chlorinated paraffin wax production scale economies in China drive significant supply concentration, establishing lower price floors for commodity grades globally. This scale allows Chinese producers to serve both domestic and export markets efficiently.
Pricing Analysis
Short-chain chlorinated paraffin (SCCP) pricing faces severe regulatory pressure, leading to a significant price gap compared to compliant medium-chain (MCCP) and long-chain (LCCP) variants. The dominant pricing structure is per-unit transactional, with price differentiation driven by certification level and volume scale. Pricing softness for SCCPs stems from global phase-out mandates. Construction sector buyers are highly price-sensitive, while electronics industry formulators prioritize certified LCCP grades.
Supply Chain Analysis
China anchors global chlorinated paraffin wax production, supplying both its vast domestic market and export channels for industrial users. The supply chain sources primary raw materials, paraffin and chlorine, from global commodity markets. Single-source vulnerability from China's concentrated production creates a significant supply chain risk. Distribution runs through specialized chemical distributors and direct bulk shipments to large industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chlorinated paraffin wax market is in a cyclical recovery, driven by renewed industrial expansion in Asian economies. Regulatory shifts are accelerating the transition to compliant alternatives, creating new growth opportunities.
For Market Incumbents: Consolidate existing production capacity for MCCPs and LCCPs to achieve greater cost efficiencies against emerging regulatory shifts. Invest in certification processes for high-value flame retardant grades to counter competitive threats from non-halogenated substitutes. Deepen vertical integration into specialized formulation development to secure critical end-use applications. Expand compliant production capabilities in strategic geographies like India and Vietnam.
For New Entrants and Emerging Players: Specialized formulation support for small and medium-sized enterprises in developing economies represents a service-layer gap. Target underpenetrated markets in South America, offering compliant MCCP and LCCP formulations for plastics and lubricants. Develop bio-based paraffin feedstocks to appeal to sustainability-focused customers in niche applications. Leverage agile production and localized technical support as a go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized chemical formulators with established compliant production capabilities. Long-term viability hinges on companies innovating with high-chlorine content LCCPs for demanding applications, offering a 5-10 year growth window. Acquire firms with strong R&D in bio-based feedstocks or advanced synergistic additive packages. The signal to watch is the accelerated adoption rate of certified MCCP/LCCP grades.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for MCCP/LCCP | Increases supply of compliant products for global regulatory phase-outs in various industrial sectors. |
| High-Value Formulation Development | Enhances performance and regulatory compliance for end-users in specialized applications. |
| Bio-Based Feedstock Research | Develops environmentally friendly alternatives for sustainability-conscious markets and customers. |
| Geographic Expansion in South America | Captures demand from growing industrial bases with limited local production and supply. |
| Certification Investment | Secures market access and premium pricing in regulated end-use sectors like automotive and electronics. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. Interviews engaged plant managers, procurement leads at OEMs, distribution channel partners, and technical R&D directors. Secondary data included customs trade statistics, chemical industry association reports, and regulatory body publications. This approach ensured robust bottom-up and top-down triangulation.
Sensitivity analysis informed the projection of market dynamics across the analysis window, considering various macroeconomic scenarios. Segmentation dimensions modeled included product type, application, packaging, and end-use industry, alongside regional regulatory impacts. CAGRs were derived using historical trend analysis and future growth drivers. Key forecast inputs included crude oil prices and industrial output indices.
Forecasts assume regulatory continuity in EU REACH and US EPA frameworks; material policy shifts would require re-modeling. The analysis reflects assumptions regarding global economic stability and raw material supply. Recalibration cycles align with material shifts in regulatory mandates or industrial expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Ammonium Molybdate Market