
 Hexacomb Packaging Market | 2026-2036
Hexacomb Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hexacomb Packaging Market Foresight
Single-source to multi-source procurement is rebalancing how converters secure honeycomb substrate supply across North America and Europe. Smurfit Kappa Group plc leverages its integrated containerboard network to control virgin and recycled fiber flows into hexacomb lines. DS Smith plc anchors its position through closed-loop recycling partnerships with major retail distributors. WestRock Company competes by extending its corrugated portfolio into engineered protective formats for appliance and automotive markets.
Hexacomb packaging consists of a hexagonal cell core structure manufactured from kraft paperboard layers, bonded with water-based adhesives and faced with linerboard to achieve compressive strength-to-weight ratios exceeding traditional corrugated alternatives. The structure absorbs impact energy through cell wall buckling, making it suitable for heavy-goods protective crating and palletized unitization. Heavy-Duty Hexacomb commands the premium tier in industrial applications where load-bearing specifications exceed standard corrugated limits. Custom Hexacomb is expanding fastest among electronics OEMs requiring die-cut insert configurations for fragile component protection. Recycled Paperboard dominates material flows as brand owners enforce post-consumer content minimums in supplier scorecards.
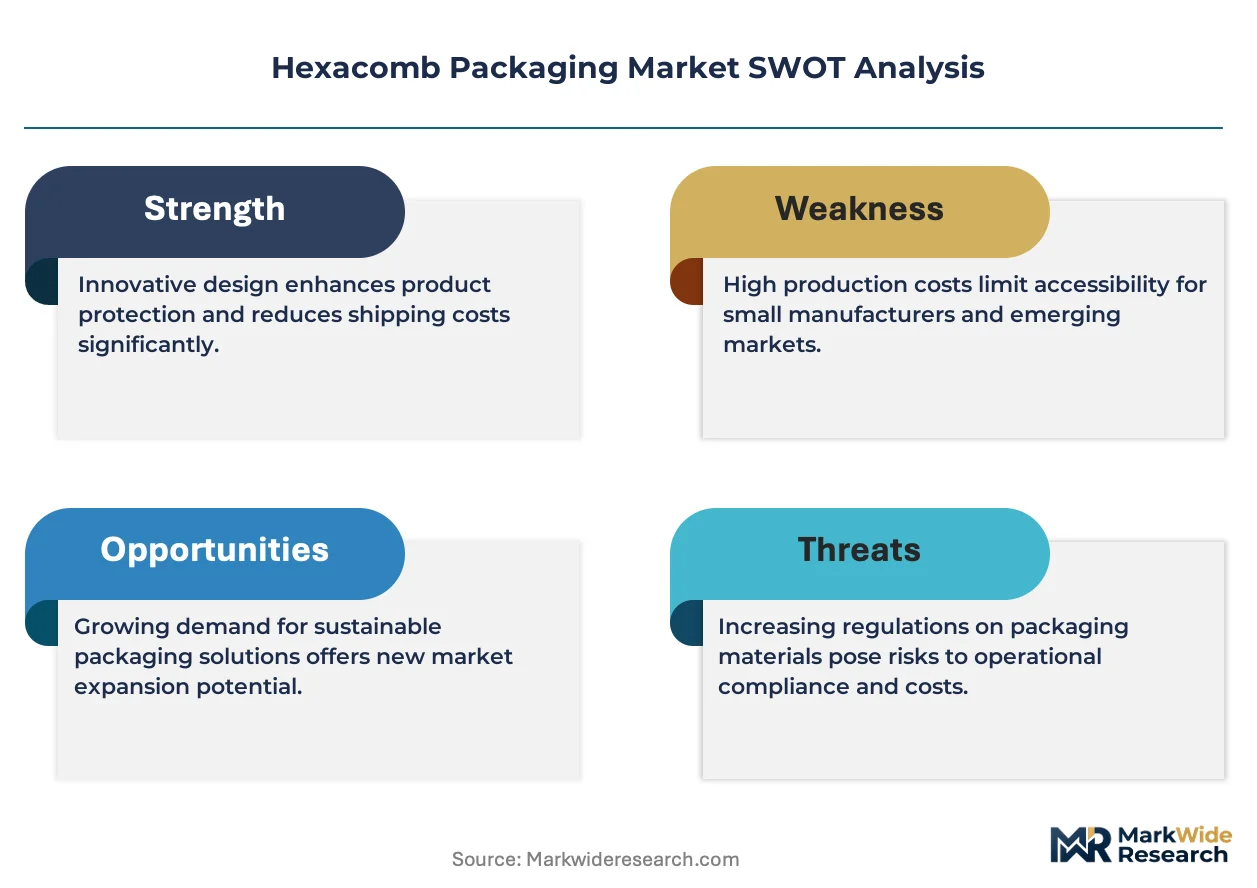
The EPA governs adhesive emissions and recycled fiber sourcing claims under TSCA and FFR guidelines in the United States, while the EU Green Deal and REACH restrict certain chemical binders and mandate circularity disclosures for packaging placed on European markets. These frameworks compel manufacturers to reformulate adhesives and document fiber provenance to maintain market access. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in regional substrate production or rely on cross-border supply arrangements.
Market Dynamics
Recycled fiber mandates under the EU Green Deal are compressing virgin substrate margins while accelerating converter investments in closed-loop collection infrastructure across European supply chains.
Growth Catalysts
- E-Commerce Fulfillment Surge:Electronics manufacturers in East Asia are expanding protective packaging procurement as direct-to-consumer shipment volumes strain traditional corrugated capacity.
- REACH Chemical Restrictions:European converters are reformulating water-based adhesives to eliminate restricted binders, creating first-mover advantages for compliant substrate suppliers.
- Automotive Export Specifications:Germany's vibration-dampening packaging standards for component exports are tightening, displacing foam-based alternatives in heavy-goods crating.
Market Restraints
- Recycled Fiber Price Volatility:Post-consumer OCC bale costs fluctuate with municipal collection rates, squeezing converter margins on fixed-price supply contracts.
- Adhesive Supply Concentration:Specialty water-based adhesive production clusters in the Rhine-Ruhr industrial corridor, exposing hexacomb manufacturers to single-source risk.
- Corrugated Substitution:Double-wall corrugated advances in compressive strength are capturing light-duty protective applications below 50-pound load thresholds.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for smartphone and semiconductor assembly are creating virgin demand for die-cut protective inserts in Gujarat and Tamil Nadu.
- Battery Cell Logistics:EV battery pack shipping regulations are mandating cell-level isolation packaging, opening specification-driven demand for engineered honeycomb separators.
- Digital Print Integration:Hybrid production lines combining hexacomb fabrication with direct-to-substrate branding are capturing premium shelf-ready packaging contracts from CPG brands.
Industry Challenges
- Adhesive Formulation Expertise:Converter R&D teams lack polymer chemistry depth to validate alternative binder systems under accelerated aging protocols.
- Die-Cut Tooling Investment:Custom insert programs for electronics OEMs require precision steel-rule tooling with 18-month amortization horizons.
- Multi-Species Fiber Sorting:Contamination in post-consumer streams degrades hexacomb cell wall integrity, demanding optical sorting capex that mid-scale converters cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexacomb Packaging Market |
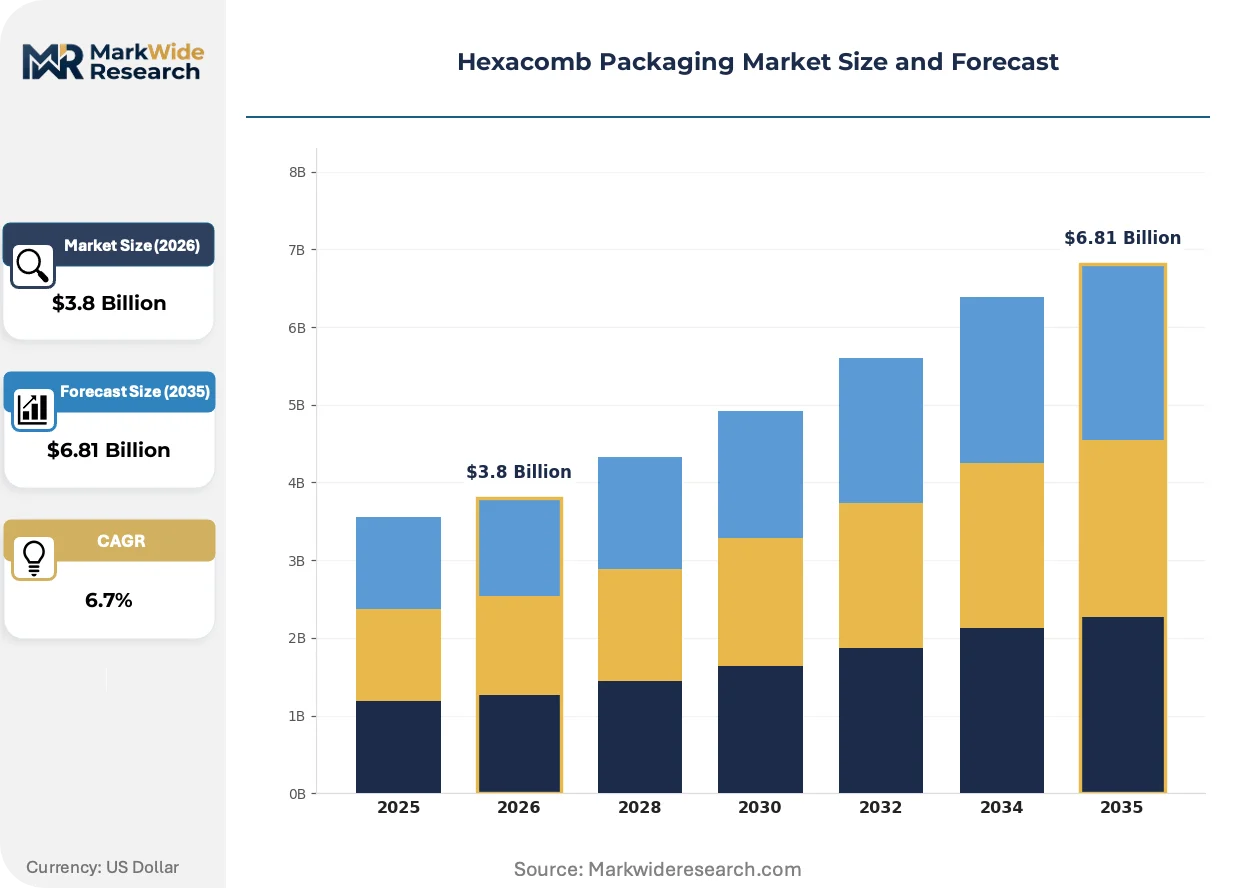
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hexacomb, Custom Hexacomb, Pre-Cut Hexacomb, Heavy-Duty Hexacomb Material: Recycled Paperboard, Virgin Paperboard, Coated Paperboard, Organic Paperboard End User: Electronics, Food & Beverage, Consumer Goods, Industrial Packaging Distribution Channel: Online Sales, Retail, Direct Sales, Distributors |
| Companies Covered | Sonoco Products Company, Smurfit Kappa Group plc, WestRock Company, Amcor plc, Flexi-Hex, DS Smith plc, Sealed Air Corporation, Cascades Inc, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexacomb Packaging Market Shifts & Advancements
Active investment in substrate engineering and regulatory compliance tooling is compressing product development cycles while fragmenting the supplier base between integrated giants and specialized converters.
Bio-based adhesive platforms derived from lignin and starch polymers are rewriting qualification protocols for food-contact and electronics applications. Appliance manufacturers in South Korea are piloting these binders for refrigerator crating programs. The shift is compressing petrochemical adhesive share in premium protective segments.
Extended producer responsibility schemes under the EU Green Deal are mandating fiber provenance documentation for all packaging placed on European markets. Converters must now maintain chain-of-custody records from pulping through lamination. Heavy-Duty Hexacomb specifications for automotive exports face the most stringent audit requirements.
Modular die-cut insert libraries are displacing custom tooling programs for mid-volume electronics OEMs. Distributors in Taiwan and South Korea now stock parametric insert families configurable via CAD-to-cut workflows. The model is visible in semiconductor component logistics where shipment volatility punishes long tooling lead times.
Hexacomb Packaging Market Segmentation
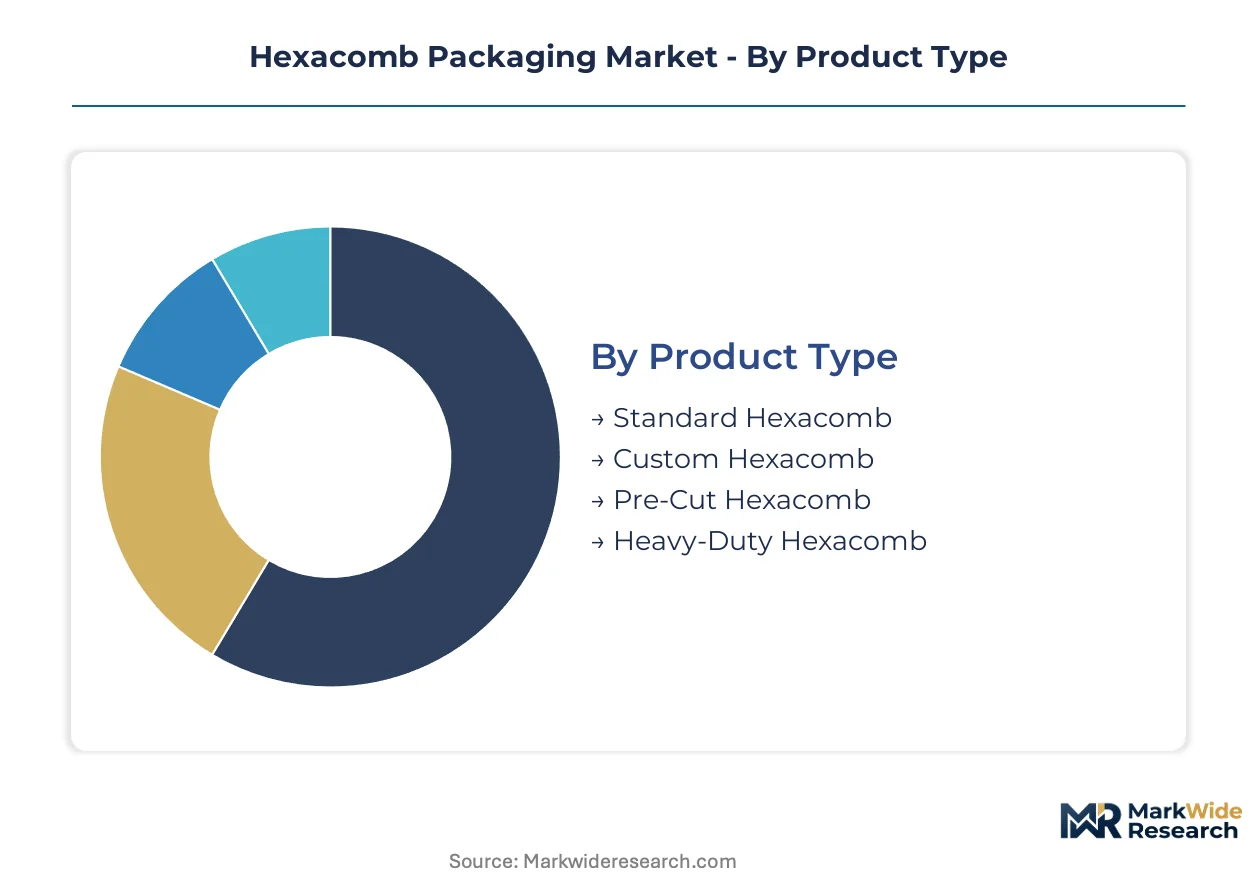
Hexacomb packaging specifications diverge sharply across load-bearing requirements and end-use fragility thresholds. Converters must match cell density, face paper weight, and adhesive systems to precise application demands or risk specification failure in automotive and electronics supply chains.
Product Type:
Structural performance tiers define competitive positioning across protective packaging procurement.
- Heavy-Duty Hexacomb:Multi-layer kraft construction with reinforced face papers achieves compressive strengths exceeding 1,500 psi for automotive component crating. Germany's KBA vibration standards for powertrain exports mandate this specification tier.
- Custom Hexacomb:Die-cut cell configurations with precision insert geometries protect fragile semiconductor and display components during East Asian e-commerce fulfillment. Electronics OEMs in Taiwan and South Korea specify parametric insert libraries to avoid 18-month tooling amortization.
- Standard Hexacomb:Generic cell geometries serve commodity palletization and light-duty protective applications across consumer goods distribution.
- Pre-Cut Hexacomb:Modular blank formats reduce on-site fabrication labor for mid-volume appliance manufacturers seeking standardized crating solutions.
Mature deployment sits with Standard Hexacomb in bulk industrial logistics. Newer deployment is concentrated in Custom Hexacomb configurations for semiconductor and battery cell protection.
Material:
Post-consumer content thresholds and fiber provenance documentation are reshaping substrate procurement specifications under EU Green Deal mandates.
- Recycled Paperboard:Post-consumer OCC streams dominate European converter supply chains under circularity disclosure requirements. ECHA REACH compliance demands chain-of-custody records from municipal collection through lamination.
- Virgin Paperboard:Uncontaminated long-fiber kraft maintains cell wall integrity for heavy-load specifications in Germany's automotive export corridor. Virgin substrate commands premium positioning where recycled fiber contamination risks buckling failure.
- Coated Paperboard:Moisture-resistant barrier treatments extend hexacomb utility to food-contact cold chain applications requiring humidity protection.
- Organic Paperboard:Lignin and starch-based binder systems from bio-refinery feedstocks qualify for food-contact and electronics applications in South Korean appliance crating pilots.
Volume concentration rests with Recycled Paperboard across European supply chains. Specification-driven growth is accelerating in Organic Paperboard as petrochemical adhesive restrictions tighten.
End User:
Fragility sensitivity and shipment velocity determine protective packaging specification intensity across downstream industries.
- Electronics:Die-cut insert precision for smartphones, semiconductors, and display panels drives the steepest expansion trajectory in Gujarat and Tamil Nadu under India's PLI scheme incentives. Direct-to-consumer fulfillment volumes strain traditional corrugated capacity.
- Industrial Packaging:Palletized unitization and heavy-goods crating for machinery exports absorb high-volume honeycomb consumption in mature manufacturing corridors.
- Consumer Goods:Shelf-ready packaging with direct-to-substrate branding integrates hexacomb structural performance with retail presentation requirements.
- Food & Beverage:Cold chain humidity protection and food-contact adhesive compliance limit penetration to coated and organic substrate variants.
Established procurement patterns anchor Industrial Packaging. Emerging specification intensity is concentrating in Electronics as battery cell isolation mandates multiply.
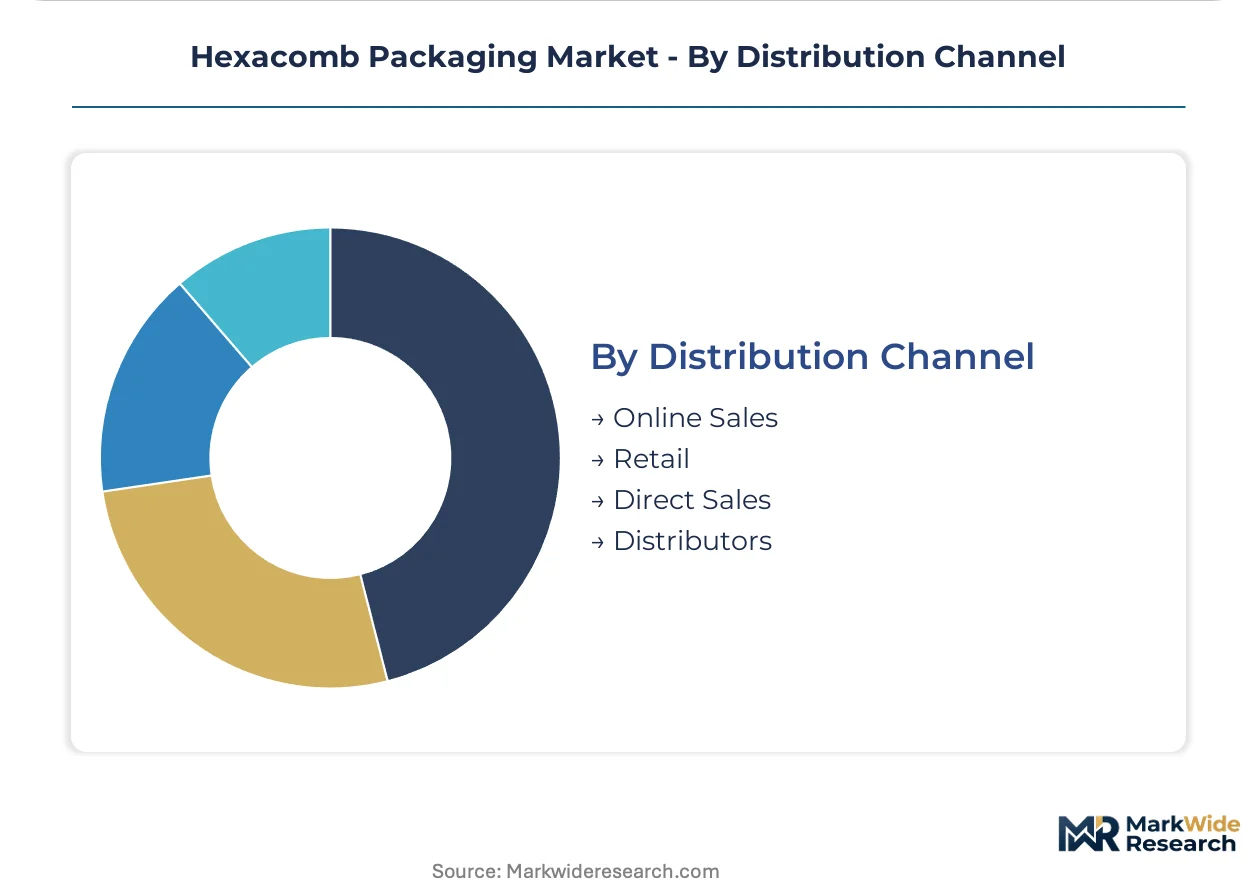
Distribution Channel:
Customer scale and order customization depth determine channel economics for hexacomb converters.
- Distributors:Inventory-holding intermediaries in Taiwan and South Korea stock parametric insert families for mid-volume electronics OEMs facing shipment volatility.
- Direct Sales:Converter-engineered solutions for automotive tier-1 suppliers require collaborative design iteration on vibration-dampening specifications.
- Online Sales:Standard blank and modular insert configurations serve small-batch procurement through digital catalog platforms.
- Retail:Limited penetration given hexacomb's industrial specification orientation and minimum order quantity thresholds.
Channel maturity resides with Direct Sales for automotive specification development. Fastest channel expansion is occurring in Distributor networks serving volatile electronics component logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-fiber kraft pulp availability in the southeastern United States anchors North American substrate supply chains. Recovered paper collection density in Germany's Rhine-Ruhr corridor shapes European converter economics. East Asian electronics manufacturing clusters in Taiwan and South Korea drive specification intensity for die-cut protective formats.
United States
Appliance manufacturers in the Southeast expand honeycomb crating procurement as reshoring accelerates durable goods production. EPA TSCA adhesive emission guidelines compel reformulation of water-based binders used in hexacomb lamination. The Appalachian containerboard corridor supplies virgin kraft substrate to automotive component packagers serving Detroit's tier-1 supplier base.
Germany
KBA vibration-dampening standards for powertrain exports mandate Heavy-Duty Hexacomb specifications displacing foam alternatives. EU Green Deal circularity disclosure requirements enforce chain-of-custody documentation from municipal collection through lamination. The Stuttgart automotive cluster sources certified substrate from converters operating closed-loop collection partnerships with retail distributors.
China
E-commerce fulfillment volumes strain traditional corrugated capacity across the Yangtze River Delta electronics corridor. SAMR packaging standards and GB certification requirements govern adhesive safety in food-contact and electronics applications. Shenzhen-based smartphone OEMs specify custom die-cut insert configurations for direct-to-consumer shipment protection.
India
PLI scheme incentives for semiconductor and smartphone assembly create virgin demand for protective packaging in Gujarat and Tamil Nadu. BIS quality certification mandates govern substrate performance claims for export-bound automotive components. The Chennai electronics manufacturing cluster contracts converters for precision insert programs serving volatile component shipment schedules.
South Korea
Refrigerator OEMs pilot lignin-based bio-adhesives for appliance crating programs under MFDS food-contact guidelines. Display panel manufacturers in Gyeonggi Province specify parametric insert libraries to avoid long tooling amortization horizons. The Busan logistics hub stocks modular honeycomb configurations configurable via CAD-to-cut workflows for mid-volume electronics procurement.
Hexacomb Packaging Market Competitive Landscape
Strategic partnerships dominate the current landscape as converters secure adhesive supply and fiber sourcing arrangements. The supplier base concentrates around integrated paperboard producers with captive containerboard networks, mid-scale specialists in die-cut tooling, and regional distributors holding parametric insert inventories. Two archetypes define competitive positioning: vertically integrated giants controlling substrate flows from pulping through lamination, and nimble converters leveraging modular production lines for custom electronics programs. Capacity expansion in recycled fiber processing and technology licensing for bio-based adhesive platforms represent the dominant competitive vectors.
Among Ireland-based integrated producers, Smurfit Kappa Group plc exemplifies the substrate-control archetype through its containerboard network, while DS Smith plc occupies a parallel position emphasizing closed-loop recycling partnerships. WestRock Company represents the North American integrated model extending corrugated portfolios into engineered protective formats. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Smurfit Kappa Group plc |
| WestRock Company |
| Amcor plc |
| Flexi-Hex |
| DS Smith plc |
| Sealed Air Corporation |
| Cascades Inc |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
EU Green Deal circularity mandates are compressing virgin substrate availability across European supply chains, forcing converters toward recycled fiber sourcing that intensifies price competition for compliant material streams.
Pricing Analysis
Extended producer responsibility bundling separates compliant substrate premiums from bare-material procurement in European markets. Three-tier pricing structure across certified-recycled, standard-recycled, and virgin-kraft levels reflects ECHA REACH documentation depth. Cost compression in standard-recycled tiers is intensifying because municipal OCC collection volatility exposes fixed-contract converters to margin erosion. Electronics OEMs in Taiwan and South Korea exhibit lowest price sensitivity due to die-cut precision requirements, while appliance manufacturers in Southeast Asia drive hardest bargain negotiations for modular blank formats.
Supply Chain Analysis
Skilled lamination technicians concentrate in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta, constraining hexacomb production scaling outside these clusters. Raw material flows draw from Swedish long-fiber kraft pulp, American OCC recovery streams, and South Asian jute-paperboard alternatives. Single-source vulnerability clusters in specialty water-based adhesive production around Düsseldorf and Shanghai chemical parks. Distribution runs through converter-direct relationships for automotive tier-1 specifications and distributor-held parametric insert inventories for volatile electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty adhesive formulation capacity anchors supply-constrained pricing power, with polymer chemistry expertise scarcity propping margins across specification-intensive segments.
For Market Incumbents: Lock in closed-loop fiber partnerships with retail distributors to secure post-consumer OCC streams before EU Green Deal disclosure requirements harden. Backward integration into captive containerboard pulping insulates margin position from virgin kraft price spikes. Prioritize bio-based adhesive R&D to outpace REACH chemical restriction timelines. For New Entrants and Emerging Players: Digital catalog platforms for modular hexacomb blanks offer lowest-friction entry path into mid-volume appliance procurement. Target India's PLI-subsidized electronics manufacturing corridors in Gujarat and Tamil Nadu where converter capacity lags smartphone assembly growth. Lead with CAD-to-cut workflow integration to bypass 18-month tooling amortization barriers. For Investors and Strategic Acquirers: The window for entry favors die-cut tooling specialists with parametric insert libraries and established semiconductor OEM relationships. Five-to-ten year viability hinges on battery cell isolation packaging specification capture as EV logistics regulations multiply. Watch for EU extended producer responsibility scheme enforcement intensity as inflection indicator for recycled fiber premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Pulping | Captive virgin kraft supply secures Heavy-Duty Hexacomb margins for German automotive exports. |
| Bio-Based Adhesive Platform Development | Lignin and starch polymer qualification opens food-contact and electronics specification access under REACH. |
| Parametric Insert Library Expansion | CAD-to-cut workflows reduce tooling lead times for Taiwan and South Korean semiconductor OEMs. |
| Closed-Loop Recycling Partnerships | Chain-of-custody documentation satisfies EU Green Deal circularity disclosure mandates. |
| Digital Print Integration Investment | Direct-to-substrate branding captures premium shelf-ready packaging contracts from CPG brands. |
Research Methodology
Multi-period observation of hexacomb substrate pricing spreads, adhesive formulation patent filings, and electronics OEM procurement patterns anchored the trend analysis, supplemented by interviews with converter operations managers, containerboard procurement leads, die-cut tooling engineers, and retail distributor inventory planners. Secondary validation drew from ECHA REACH substance restriction updates, EU Green Deal implementation guidance, EPA TSCA adhesive emission guidelines, SEC 10-K disclosures from integrated paperboard producers, and customs trade data on kraft pulp flows. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Input-output matrices mapped hexacomb fabrication capacity against end-use demand across product type tiers, material grade specifications, electronics versus automotive versus industrial end-user segments, and channel structures from direct sales to distributor networks. CAGRs were derived from segment-level growth trajectory analysis across the projection horizon. Forecast inputs incorporated PLI scheme incentive disbursement timelines for Indian electronics manufacturing and EV battery shipping regulation evolution.
The model holds under stable recycled fiber collection rates and REACH enforcement continuity; deviation in municipal OCC supply disruption or adhesive raw material trade restriction would shift capacity expansion assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Films Market
Poly film
Polysaccharide Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Metallized Film Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Thermoforming Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Polyolefin Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Wrap Around Label Films Market
Poly film
Soft Touch Film Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Japan Plastic Packaging Film Market