
 PVC Blister Packs Market | 2026-2036
PVC Blister Packs Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Blister Packs Market Outlook
Software-defined serialization and track-and-trace subscription layers is recalibrating how PVC blister pack vendors monetize compliance-ready formats. Amcor plc leverages its global film extrusion network to anchor high-barrier pharmaceutical contracts across multiple continents. Klockner Pentaplast specializes in multi-layer barrier films that sustain premium positioning in regulated drug packaging segments. Constantia Flexibles competes through integrated printing and forming operations that compress lead times for European pharmaceutical clients.
PVC blister packs are thermoformed plastic cavities sealed to lidding material, typically using polyvinyl chloride film with thicknesses ranging from 0.25 mm to 0.80 mm, designed to provide product visibility, tamper evidence, and dose-level protection for pharmaceuticals and consumer goods. The pharmaceutical end-user segment leads volume allocation due to strict dose-control requirements and child-resistance protocols, while high barrier blisters capture expanding margin pools as moisture-sensitive biologics and generics proliferate. Carded blister packs maintain stable demand in over-the-counter retail channels where point-of-sale visibility drives shelf performance.
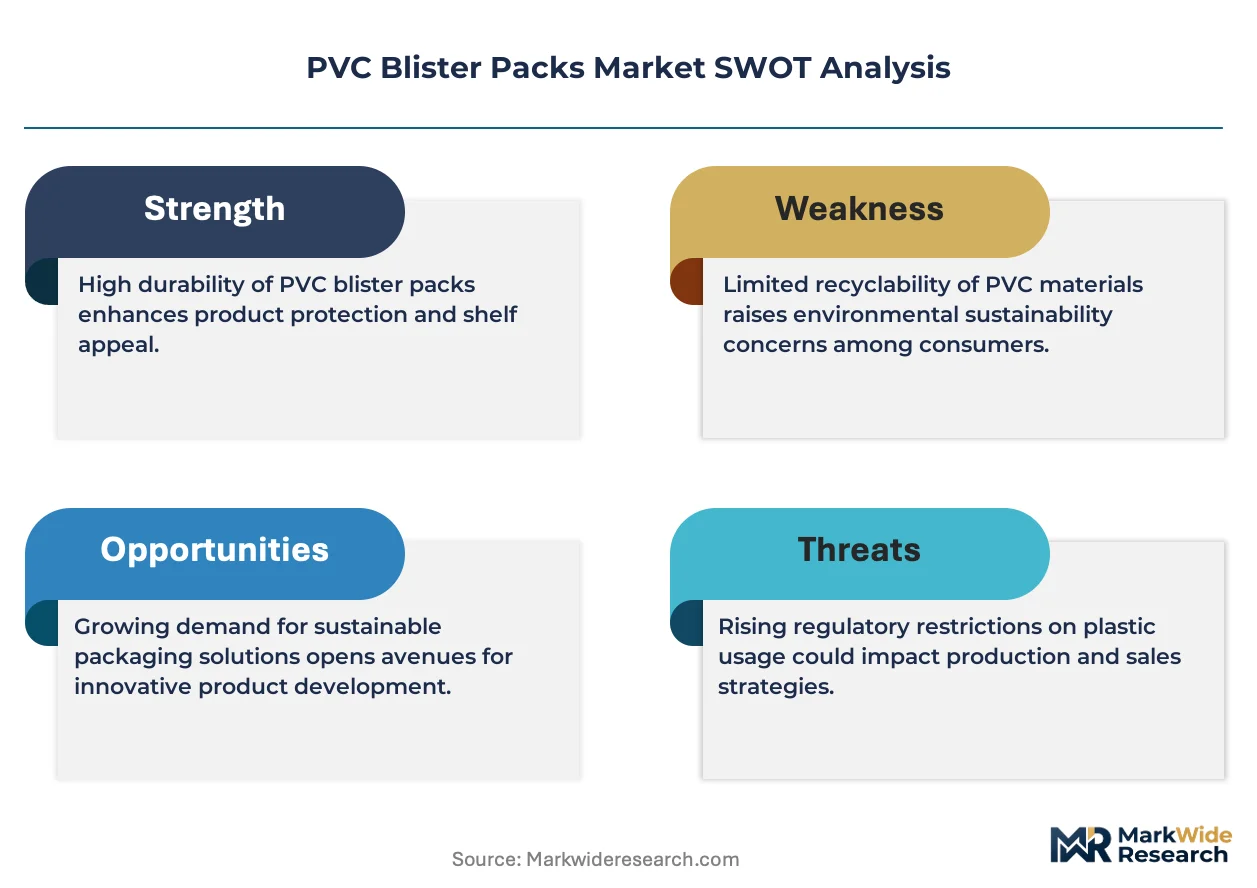
FDA regulations on unit-dose packaging and child-resistant standards shape product design requirements for US-bound pharmaceutical blisters, while REACH restrictions on phthalate plasticizers and the EU Green Deal circularity mandates are forcing reformulation toward non-PVC and reduced-chloride alternatives. India's CDSCO quality guidelines and BIS packaging standards are tightening local manufacturing compliance for export-oriented blister producers. Stakeholders must monitor how regulatory divergence between FDA, EMA, and emerging market agencies fragments tooling and material certification requirements across supply chains.
Market Dynamics
Regulatory fragmentation between FDA child-resistance mandates and EU Green Deal circularity requirements is forcing PVC blister pack manufacturers to maintain dual-certification tooling and parallel material streams across export markets.
Growth Catalysts
- Unit-dose compliance mandates:FDA regulations on dose-level packaging for solid oral dose pharmaceuticals are accelerating format standardization across US-bound production lines.
- India's CDSCO quality guidelines:Domestic pharmaceutical packaging capacity expansion is localizing blister production for export-oriented generics manufacturers.
- High-barrier film technology:Moisture-sensitive biologics and complex generics are pulling multi-layer barrier formats into volume production.
Market Restraints
- Phthalate plasticizer restrictions:REACH regulations on plasticizer chemistry are forcing reformulation costs and material requalification cycles.
- Raw material concentration:PVC resin supply clusters in specific coastal manufacturing zones create input vulnerability during logistics disruptions.
- Non-PVC substitution pressure:Polyethylene terephthalate and polypropylene alternatives are capturing share in retail OTC segments.
Strategic Opportunities
- Recyclable mono-material designs:EU Green Deal circularity mandates are creating first-mover advantage for suppliers with certified recyclable streams.
- Software-defined serialization:Track-and-trace subscription layers are opening recurring revenue models beyond unit sales.
- Biologics packaging expansion:Cold-chain compatible high-barrier formats for temperature-sensitive injectables represent underpenetrated application space.
Industry Challenges
- Dual-certification tooling complexity:Divergent FDA and EMA validation protocols are extending equipment commissioning timelines.
- Specialized thermoforming expertise:Thin-gauge pharmaceutical forming requires skilled technicians that compete with semiconductor and medical device sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Blister Packs Market |
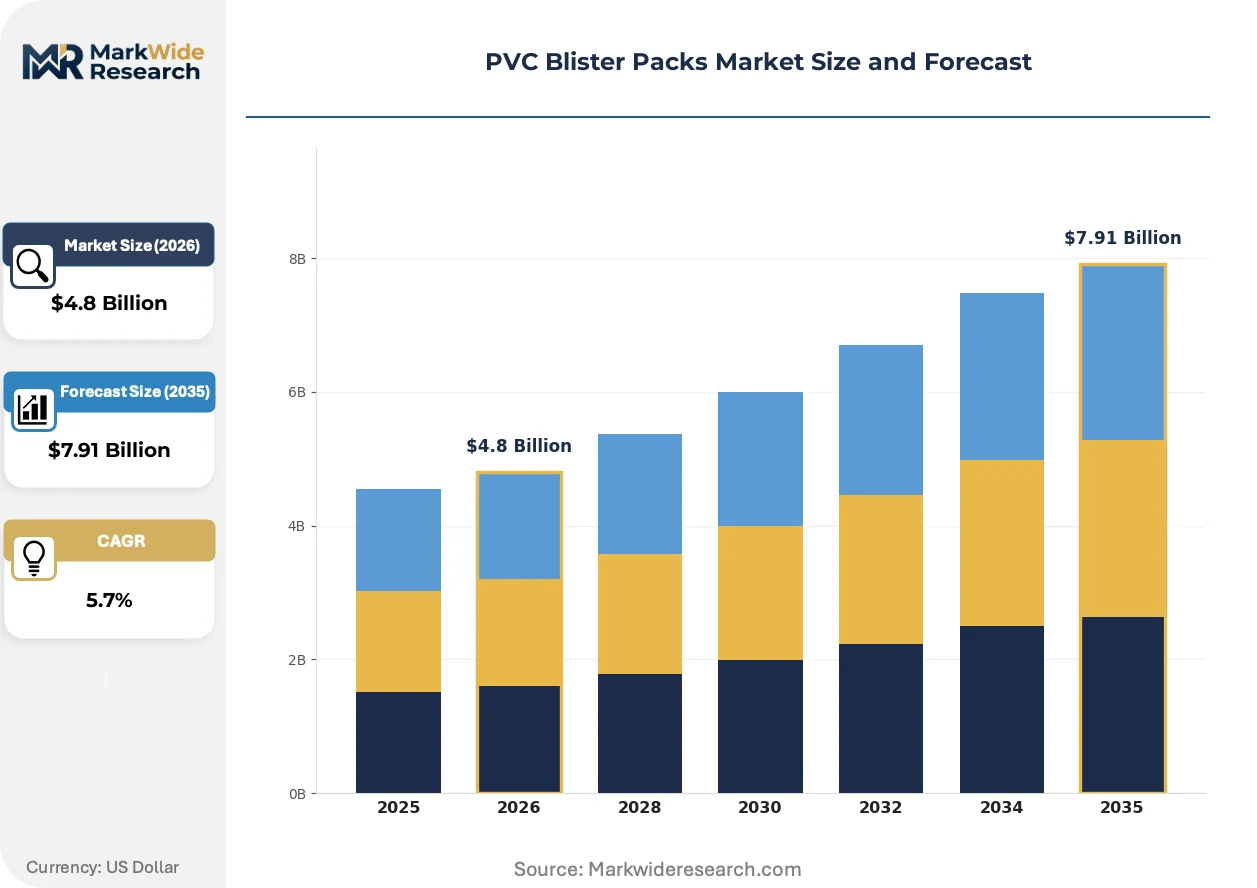
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
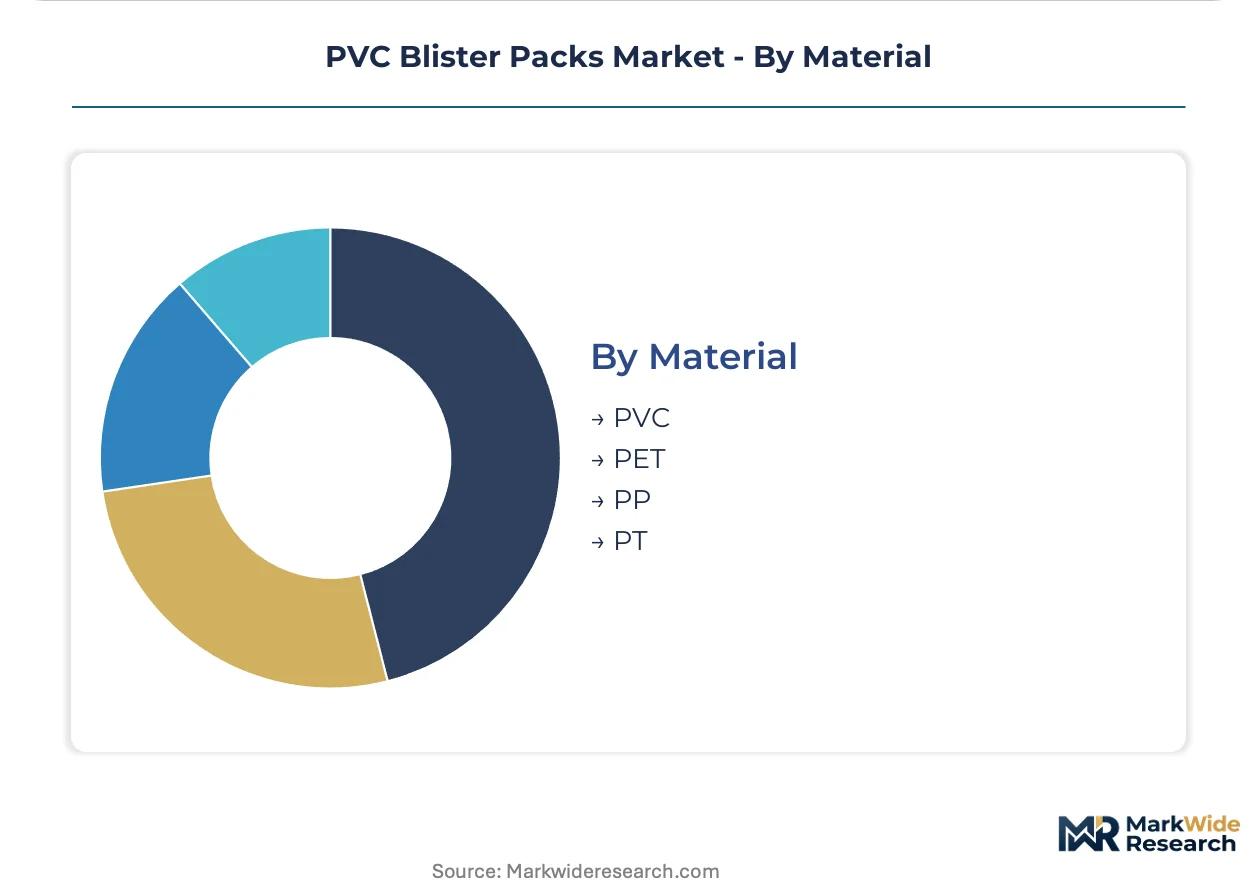
| Segmentation | Product Type: Standard Blister Packs, Carded Blister Packs, Clamshell Packs, High Barrier Blisters End User: Pharmaceutical Companies, Consumer Goods, Electronics, Medical Devices Application: Packaging Solutions, Retail Packaging, Transportation Packaging, Industrial Packaging Material: PVC, PET, PP, PT |
| Companies Covered | Amcor plc, Klockner Pentaplast, Constantia Flexibles, Winpak Ltd., Sonoco Products Company, WestRock Company, Tekni-Plex, Inc., UFlex Ltd., Bilcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Blister Packs Market Strategic Shifts
Material science advances and regulatory compliance architectures are rewriting competitive boundaries in pharmaceutical packaging, compressing the gap between commodity formats and certified high-barrier solutions.
Multi-layer co-extrusion barrier films is converging with serialization-ready forming lines as the dominant technical architecture for moisture-sensitive drug packaging. Pharmaceutical contract manufacturers are adopting these integrated systems at replacement cycle pace. The technology is converging with cloud-based compliance platforms to compress validation timelines and reduce manual audit preparation.
REACH restrictions on phthalate plasticizers and the EU Green Deal circularity mandates are forcing systematic material requalification across European supply chains. Industrial consequence includes accelerated R&D spend on non-PVC and reduced-chloride alternatives. High-barrier biologics segments are responding fastest, with some manufacturers pre-qualifying recyclable mono-material formats ahead of mandate deadlines.
Buyer consolidation among large pharmaceutical contract packagers is compressing supplier qualification cycles and unbundling after-sales technical support. Regional distributors are losing share to direct manufacturer relationships with top-tier pharma accounts. India and Southeast Asia show this pattern most visibly, where domestic CDSCO-compliant producers are securing long-term supply agreements with multinational generics manufacturers.
PVC Blister Packs Market Segmentation
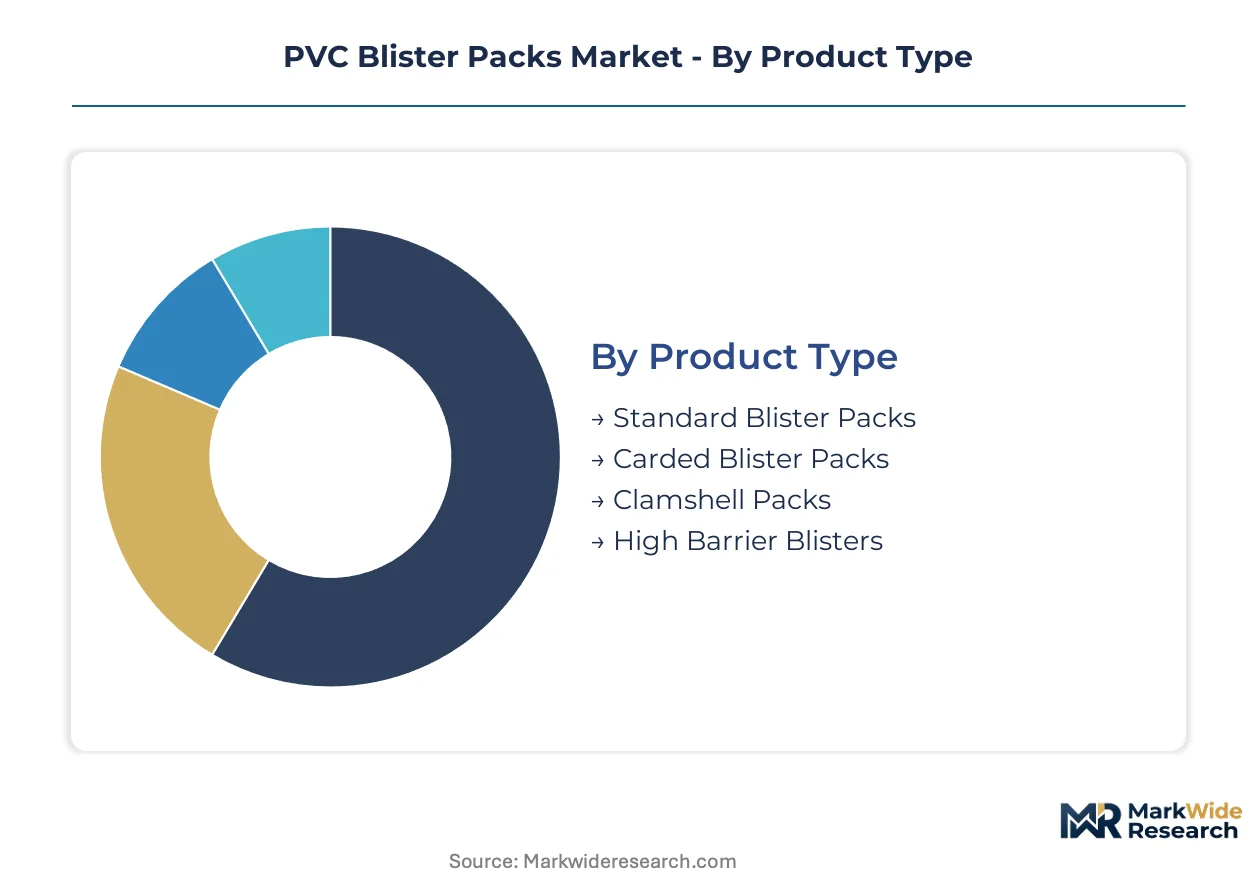
PVC blister pack performance varies sharply across product architecture, end-use requirements, and material specifications. Manufacturers configure extrusion and thermoforming assets around segment-specific barrier properties and regulatory compliance tiers.
Product Type:
Film thickness and cavity depth specifications define the technical axis for product differentiation across pharmaceutical and consumer applications.
- Standard Blister Packs:Single-layer PVC construction with 0.25-0.50 mm film thickness serves generic oral solid dose pharmaceuticals where cost efficiency outweighs barrier demands. Demand concentrates in Indian export-oriented generics manufacturing, where CDSCO compliance mandates standardize tooling investments.
- High Barrier Blisters:Multi-layer co-extrusion incorporating EVOH or PVDC interlayers delivers moisture vapor transmission rates below 0.1 g/m²/day for hygroscopic biologics. Moisture-sensitive generics in European markets under EMA stability guidelines are pulling this format into volume production.
- Carded Blister Packs:Heat-sealed to printed paperboard backing for retail shelf visibility in OTC channels.
- Clamshell Packs:Hinged two-piece thermoformed shells for consumer electronics and hardware protection.
Standard blister packs lead on scale; high barrier blisters lead on momentum.
End User:
Regulatory stringency and volume concentration shape how suppliers prioritize technical support and certification investments.
- Pharmaceutical Companies:Unit-dose compliance mandates from FDA and EMA drive qualification cycles for child-resistant and senior-friendly opening features. Cold-chain biologics expansion is accelerating demand for validated forming lines with integrated serialization.
- Consumer Goods:Tamper-evident packaging for personal care and household products emphasizes point-of-sale differentiation over barrier performance.
- Electronics:Static-dissipative formulations protect semiconductors and components during distribution.
- Medical Devices:Sterile barrier systems for single-use instruments require ISO 11607 compliance and ethylene oxide sterilization compatibility.
Pharmaceutical companies anchor volume commitment; medical devices represent the steepest expansion trajectory.
Application:
Distribution channel requirements determine whether visibility, protection, or handling efficiency dominates design priorities.
- Packaging Solutions:Integrated contract packaging services combining thermoforming, printing, and serialization for pharmaceutical clients.
- Retail Packaging:Carded and clamshell formats optimized for shelf impact and theft deterrence in mass merchandising.
- Transportation Packaging:Protective trays and cushioning inserts for electronics and precision components.
- Industrial Packaging:Heavy-gauge PVC containers for hardware and automotive parts distribution.
Packaging solutions command premium pricing; retail packaging scales fastest.
Material:
Polymer selection balances thermoformability, barrier performance, and regulatory acceptance across regional mandates.
- PVC:Dominant material with established thermoforming behavior and cost position; REACH phthalate restrictions are forcing plasticizer reformulation cycles.
- PET:Recyclable mono-material alternative gaining share in EU markets under Green Deal circularity mandates.
- PP:Higher temperature resistance for autoclave-sterilized medical applications.
- PT:Polyethylene terephthalate glycol-modified variants for deep-draw forming of complex cavity geometries.
PVC maintains installed base dominance; PET is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's blister pack production scales faster than Germany's mature high-barrier segment, yet both face divergent regulatory pressures that reshape manufacturing footprints and export competitiveness.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina drive unit-dose format standardization for FDA-regulated oral solid dose drugs. The FDA's child-resistant packaging mandates and DSCSA serialization deadlines compress supplier qualification timelines. Chicago-area thermoforming clusters are expanding cleanroom capacity to serve biologics cold-chain requirements.
Germany
Specialty pharma manufacturers in Baden-Württemberg prioritize multi-layer barrier films for moisture-sensitive generics under EMA stability guidelines. REACH phthalate restrictions and EU Green Deal circularity mandates accelerate R&D spend on recyclable mono-material alternatives. The Rhine-Main packaging corridor hosts integrated printing-forming operations serving European export markets.
India
Domestic generics manufacturers in Maharashtra and Gujarat localize blister production to meet CDSCO quality guidelines for export-oriented formulations. BIS packaging standards and DGFT pharmaceutical export incentives strengthen captive packaging capacity. The Hyderabad-Visakhapatnam corridor attracts multinational contract manufacturing investments with integrated thermoforming lines.
China
Active pharmaceutical ingredient producers in Jiangsu and Zhejiang provinces backward-integrate into packaging to capture margin downstream. NMPA pharmaceutical packaging regulations and GB standards for medical materials tighten local compliance requirements. The Yangtze River Delta concentration of film extrusion assets serves both domestic and Southeast Asian export demand.
Switzerland
Specialty biologics manufacturers in Basel and Zurich demand validated high-barrier formats for temperature-sensitive injectables under Swissmedic oversight. Precision thermoforming expertise concentrates in the Swiss-German border region, competing with semiconductor sector talent pools. Geneva-area packaging innovators pilot recyclable mono-material designs ahead of EU mandate deadlines.
PVC Blister Packs Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with film extrusion scale concentrating among integrated multinationals while regional thermoformers capture localized pharma contracts. The vendor base organizes into three tiers: global barrier-film suppliers with multi-continent extrusion networks, mid-cap integrated converters serving single-region pharma clusters, and specialized contract packagers with validated cleanroom forming lines. Consolidation pressure intensifies through backward integration by pharmaceutical companies into captive packaging capacity, alongside technology licensing partnerships that transfer barrier-film formulations to emerging market producers.
Within the global integrated tier, Amcor plc anchors multi-continent pharmaceutical contracts through its film extrusion network spanning multiple regulatory jurisdictions. Klockner Pentaplast occupies a position among multi-layer barrier specialists serving moisture-sensitive drug segments under stringent EMA and FDA protocols. Constantia Flexibles exemplifies the integrated printing-forming archetype compressing lead times for European pharmaceutical clients through co-located operations. These three represent divergent strategic positions: extrusion-scale dominance, barrier-technology specialization, and integrated service compression.
| Leading Market Players |
|---|
| Amcor plc |
| Klockner Pentaplast |
| Constantia Flexibles |
| Winpak Ltd. |
| Sonoco Products Company |
| WestRock Company |
| Tekni-Plex, Inc. |
| UFlex Ltd. |
| Bilcare Limited |
| Others |
Value Chain & Pricing Dynamics
Ethylene price indices cascading from Gulf Coast petrochemical complexes transmit directly into PVC resin cost structures, stratifying blister pack pricing across pharmaceutical certification tiers and geographic manufacturing zones. This commodity anchoring forces converters to absorb volatility or pass through via contract escalation clauses tied to named chemical benchmarks.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade pharmaceutical blisters serving export-oriented generics manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated high-barrier formats from CDSCO-compliant standard packs and uncertified commodity grades. Price differentiation hinges on barrier film certification tier and integrated serialization capability. Cost compression in the standard tier is intensifying because domestic Indian producers are backward-integrating into film extrusion. Small-volume biologics contract packagers show lowest price sensitivity; high-volume Indian generics exporters show highest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai orchestrate hub-and-spoke patterns for barrier film inventory positioning. PVC resin supply concentrates in China, the United States, and Germany, with specialty plasticizer chemistry anchored in Belgian and Dutch chemical corridors. Raw material dependencies span vinyl chloride monomer, phthalate and non-phthalate plasticizers, and EVOH barrier resins. Single-source vulnerability around specialized thermoforming equipment manufacturers in Germany and Japan creates commissioning bottlenecks. Distribution runs through direct manufacturer relationships with top-tier pharmaceutical contract packagers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVC blister packs market functions as a stable compounder underpinned by irreversible regulatory mandates for unit-dose compliance and child-resistant packaging across major pharmaceutical jurisdictions.
For Market Incumbents: To counter non-PVC substitution pressure from PET and PP alternatives in European retail channels, prioritize recyclable mono-material R&D ahead of EU Green Deal mandate deadlines. Secure backward integration into film extrusion capacity in India to defend cost position against domestic competitors capturing CDSCO-compliant contracts. Anchor high-barrier technology leadership through multi-layer co-extrusion patent estates. For New Entrants and Emerging Players: Mid-sized biologics contract manufacturers in Switzerland and Singapore represent an underserved buyer archetype requiring validated cold-chain compatible forming lines with integrated serialization. Capture share by offering software-defined compliance subscriptions that compress validation timelines against incumbent hardware-centric models. Target direct relationships bypassing consolidated distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional thermoformers lack scale to fund dual-certification tooling for simultaneous FDA and EMA compliance. Long-term viability favors integrated converters with captive film extrusion and forming operations spanning multiple regulatory jurisdictions. Acquisition target archetype: mid-cap European specialists with recyclable mono-material pre-qualifications. Monitor EU Green Deal implementation timelines as inflection indicator for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Mono-Material Qualification | Pre-positions suppliers ahead of EU Green Deal circularity mandates for pharmaceutical packaging. |
| Software-Defined Serialization Platform | Opens recurring revenue streams beyond unit sales through cloud-based track-and-trace subscriptions. |
| Backward Integration into Film Extrusion | Captures margin upstream and insulates against PVC resin price volatility in coastal manufacturing zones. |
| Dual-Certification Tooling Investment | Enables simultaneous FDA and EMA compliance without parallel equipment commissioning delays. |
| Cold-Chain Biologics Forming Line | Addresses underpenetrated demand for temperature-sensitive injectables packaging under Swissmedic protocols. |
Study Parameters
Multiple input streams — executive interviews with pharmaceutical packaging directors, regulatory affairs specialists at EMA and FDA, and thermoforming equipment engineers — were reconciled against secondary validation from CDSCO quality guidelines, REACH regulatory filings, and customs trade data for PVC resin and pharmaceutical packaging machinery. Bottom-up triangulation across film extrusion capacity databases and top-down reconciliation against pharmaceutical production statistics anchored volume estimates.
Data-stream reconciliation across product architecture, end-user regulatory tier, and material specification dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate blending weighted by pharmaceutical production forecasts and generics export intensity. Industry-specific forecast inputs included CDSCO compliance mandate implementation pacing and EU Green Deal circularity target deadlines.
Underlying measurement precision varies by segment; high-barrier pharmaceutical formats carry tighter precision than commodity consumer goods applications. Forecasts reflect documented assumptions around regulatory implementation timelines and resin price trajectory continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Blister Cards Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Blister Packs Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Carded Blister Packaging Market