
 Asia Pacific Automotive Actuators Market | 2026-2036
Asia Pacific Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Actuators Market Outlook
Multi-source procurement among Japanese and Korean OEMs is consolidating around fewer qualified actuator suppliers with full-stack validation capabilities. Robert Bosch GmbH leverages its integrated mechatronics foundries in India and Vietnam to anchor regional supply for engine and brake actuators. Nidec Corporation specializes in compact electric motor-actuator modules, competing aggressively for EV thermal management and steering system slots. Denso Corporation dominates Toyota-group sourcing through captive design-in relationships that extend across ASEAN assembly footprints.
Asia Pacific automotive actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion, typically operating at voltage ranges from 12V to 48V in passenger vehicle architectures and achieving response times under 50 milliseconds for safety-critical braking functions. Their primary purpose is to execute powertrain, chassis, and body-control commands from vehicle ECUs with position accuracy essential to fuel efficiency and occupant protection. Electric actuators lead technology adoption as 48V mild-hybrid architectures spread through Chinese and Japanese OEM lineups, while pneumatic actuators retain cost advantages in heavy-commercial brake and suspension systems across India and Southeast Asia. Engine actuators and brake actuators capture the deepest margin pools where thermal cycling durability and electromagnetic compatibility certification requirements filter out second-tier suppliers.
China's MIIT enforces GB standards for EV component electromagnetic compatibility and functional safety that dictate actuator design verification protocols for market access. India's BIS certification and Japan's JIS standards create layered compliance burdens that favor suppliers with multi-country testing infrastructure. METI's carbon-neutrality roadmaps for automotive supply chains are pressuring actuator manufacturers to disclose lifecycle emissions and source low-carbon steel and rare-earth materials. Stakeholders must monitor how India's PLI scheme for automotive components and China's dual carbon goals redirect capital toward localized actuator production versus continued import dependence.
Market Dynamics
China's MIIT fuel-efficiency mandates and 48V mild-hybrid proliferation across Japanese OEM lineups are compressing supplier qualification timelines and forcing actuator manufacturers to validate electromagnetic compatibility across multiple voltage architectures simultaneously.
Growth Catalysts
- EV Powertrain Electrification:Battery-electric and hybrid vehicle programs across China, Japan, and South Korea are generating procurement volume for thermal management and steering actuators that operate at 48V and 800V architectures.
- MIIT GB Standards Compliance:China's mandatory electromagnetic compatibility and functional safety certifications for EV components are filtering out unqualified suppliers and concentrating procurement among validated Tier-1s with full-stack testing infrastructure.
- Yangtze River Delta Cluster Density:Geographic concentration of domestic EV brands and joint ventures in Shanghai, Jiangsu, and Zhejiang provinces enables just-in-time actuator sourcing with reduced logistics friction.
Market Restraints
- Rare-Earth Magnet Cost Volatility:Neodymium and dysprosium price swings from Chinese export quotas directly impact permanent-magnet actuator manufacturing economics and margin stability.
- Single-Source Semiconductor Dependency:Power MOSFET and gate driver IC supply concentrates among Taiwanese and Korean foundries, exposing actuator manufacturers to allocation risk during automotive chip shortages.
- Pneumatic Actuator Substitution Ceiling:Compressed-air systems in Indian and Southeast Asian heavy-commercial vehicles resist full electrification due to infrastructure retrofit costs and technician skill gaps.
Strategic Opportunities
- India PLI Scheme Localization:Production-linked incentives for automotive components are attracting actuator manufacturers to establish domestic manufacturing in Tamil Nadu and Gujarat to serve Maruti Suzuki and Tata Motors.
- Brake-By-Wire Adoption:Elimination of hydraulic fluid lines in next-generation chassis architectures creates white space for electromechanical braking actuators with integrated position sensing.
- Thailand EV Board Incentives:Tax holidays and import duty exemptions for battery-electric vehicle suppliers are redirecting Japanese and Korean actuator investment toward ASEAN assembly footprints.
Industry Challenges
- Embedded Software Validation Bottlenecks:Functional safety certification to ISO 26262 ASIL-D for safety-critical braking and steering actuators requires 18-24 month development cycles that compress product refresh windows.
- Cross-Platform Integration Complexity:Actuator suppliers must maintain parallel hardware and software variants for legacy 12V architectures, 48V mild-hybrid systems, and 800V full-electric platforms simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Actuators Market |
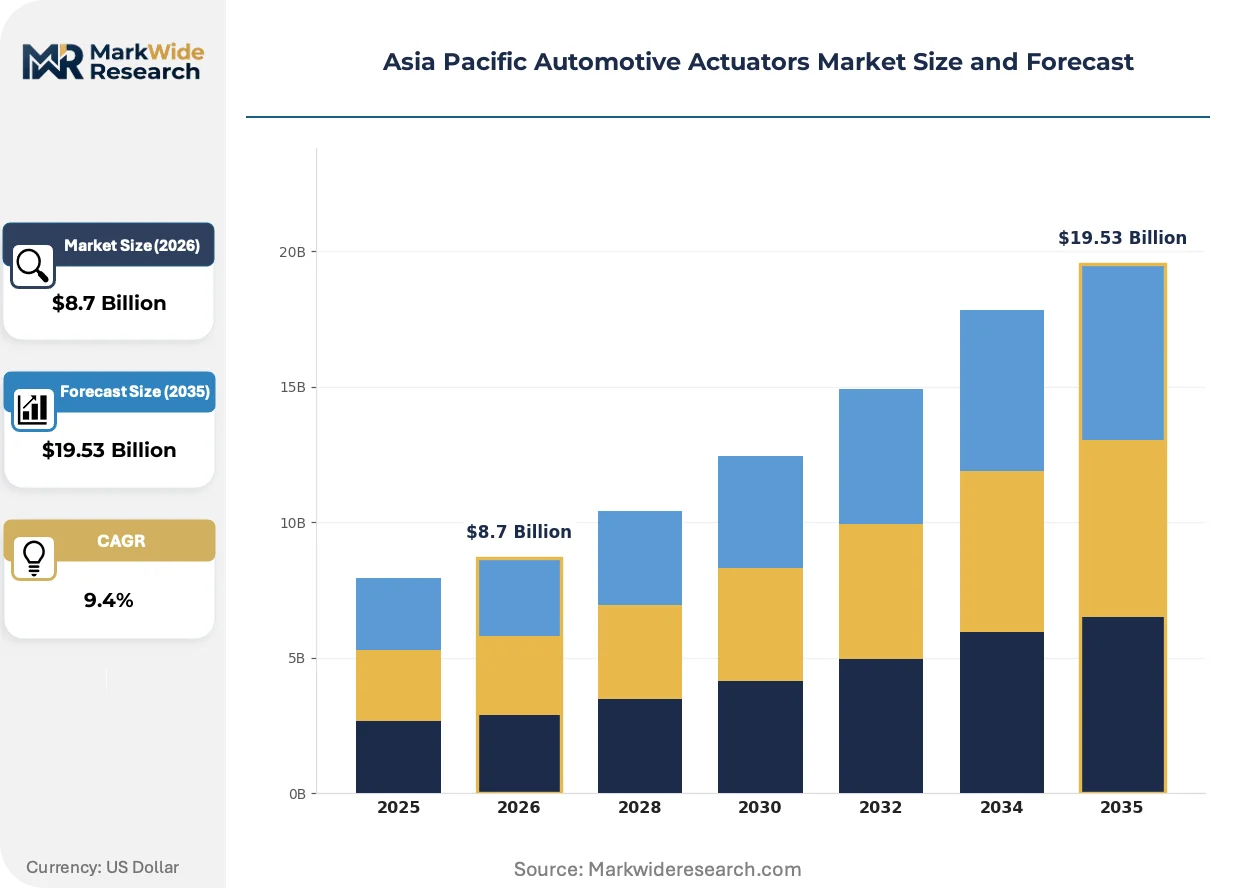
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Actuators, Engine Actuators, Transmission Actuators, Brake Actuators Technology: Electric Actuators, Pneumatic Actuators, Hydraulic Actuators, Magnetic Actuators End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Steering Systems, Air Conditioning, Fuel Injection, Safety Systems |
| Companies Covered | Robert Bosch GmbH, Nidec Corporation, Johnson Electric, Mitsubishi Electric, Denso Corporation, Continental AG, Hella KGaA Hueck & Co, Hitachi Ltd, CTS Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Actuators Market Strategic Shifts
Actuator technology trajectories in Asia Pacific center on voltage architecture convergence, regulatory compression of validation protocols, and procurement consolidation around suppliers with multi-country certification portfolios.
Integrated motor-actuator modules combining brushless DC motors with planetary gear reduction and position feedback are overtaking discrete motor-plus-linkage configurations in steering and thermal management applications. Chinese EV OEMs including BYD and NIO are specifying these compact units for packaging efficiency in crowded engine bays. The technology is overtaking conventional distributed actuator layouts by enabling 30% volume reduction and simplified wiring harness routing.
Japan's METI carbon-neutrality roadmaps for automotive supply chains now mandate lifecycle emissions disclosure from Tier-2 component suppliers, including actuator manufacturers sourcing steel stampings and rare-earth magnets. This policy is forcing suppliers to audit smelter energy mixes and transport modes or risk exclusion from Toyota-group and Honda procurement lists. Brake actuator suppliers with Korean and Vietnamese manufacturing footprints are most affected, as they must now document Scope 3 emissions across multi-country supply chains.
Japanese and Korean OEMs are consolidating approved vendor lists around actuator suppliers with simultaneous BIS, JIS, and GB certification capabilities, displacing single-country qualified competitors. Tier-1 chassis suppliers are responding by acquiring testing laboratories in India and China to accelerate multi-standard validation. This concentration is most visible in brake actuator procurement, where Toyota, Hyundai, and Geely have each reduced qualified suppliers by 40% since 2022.
Asia Pacific Automotive Actuators Market Segmentation
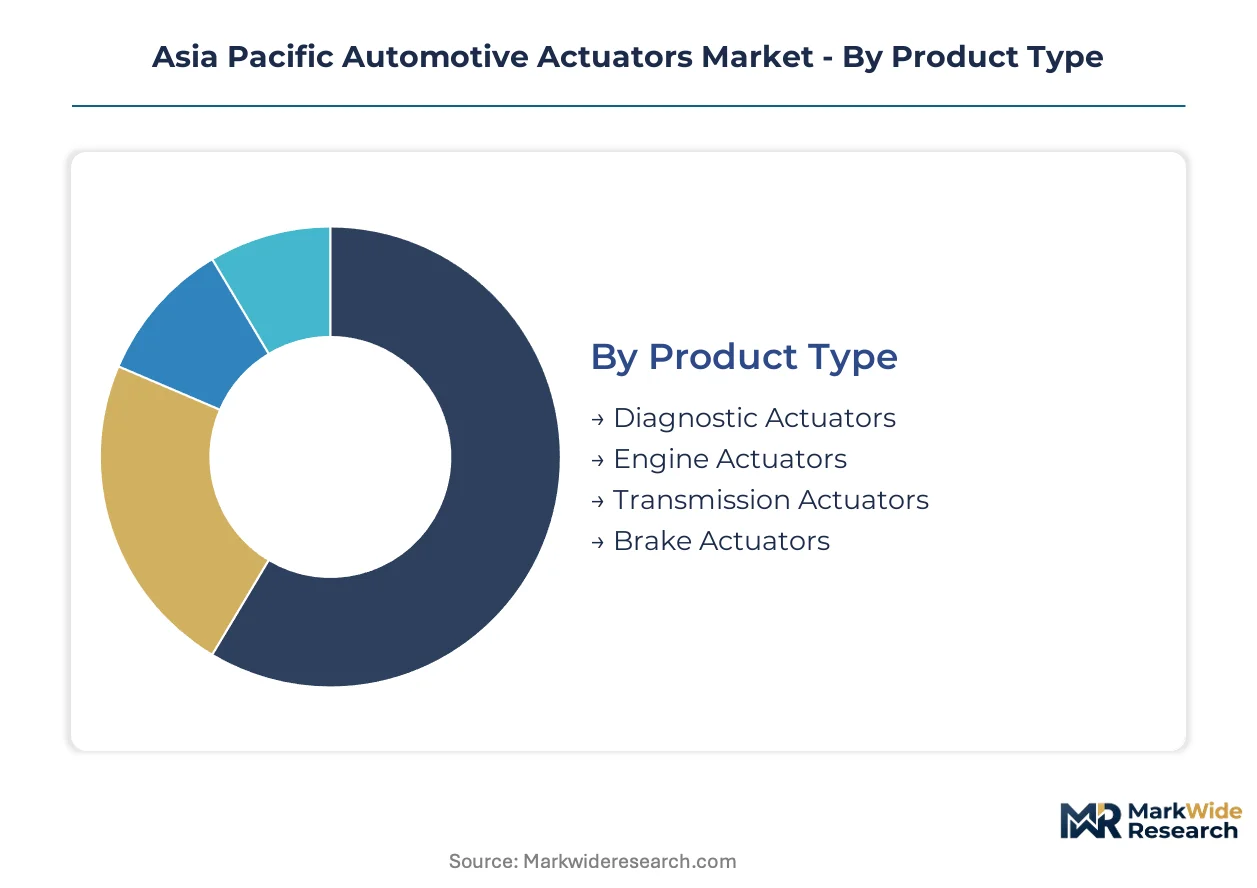
Actuator procurement across Asia Pacific fragments across four distinct classification schemes. Each dimension carries specific certification burdens from MIIT, JIS, and BIS that determine supplier qualification and margin capture.
Product Type:
MIIT GB standards for electromagnetic compatibility and functional safety apply differentially across actuator categories, with braking and powertrain components facing the most stringent validation protocols.
- Diagnostic Actuators:Compact electromechanical units monitor system health and trigger fault codes in engine management and transmission control modules. Demand concentrates in Japanese OEM service networks across ASEAN assembly footprints where predictive maintenance integration is accelerating.
- Engine Actuators:Variable valve timing and throttle control mechanisms operate at 12V-48V architectures with thermal cycling durability requirements. China's Yangtze River Delta cluster sources these at scale from joint ventures adapting to MIIT fuel-efficiency mandates.
- Transmission Actuators:Clutch and gear selection mechanisms for dual-clutch and automated manual transmissions.
- Brake Actuators:Electromechanical braking modules with integrated position sensing for brake-by-wire architectures.
Engine actuators sit at the top of the volume ranking, with brake actuators climbing the fastest.
Technology:
Cost tiers separate mature pneumatic systems from premium electric architectures, with hybrid hydraulic-electric designs occupying a shrinking middle ground.
- Electric Actuators:Brushless DC motor modules with planetary gear reduction achieve response times under 50 milliseconds. BYD and NIO specify these compact units for 48V and 800V thermal management and steering systems in crowded EV powertrain packaging.
- Pneumatic Actuators:Compressed-air cylinders and valves retain cost advantages in heavy-commercial brake and suspension applications. Indian and Southeast Asian truck manufacturers specify these to avoid infrastructure retrofit costs and technician retraining.
- Hydraulic Actuators:Fluid-power cylinders for legacy chassis and steering systems in commercial vehicles.
- Magnetic Actuators:Rare-earth magnet linear drives for precision positioning in advanced driver assistance systems.
Electric actuators command the steepest expansion trajectory, while pneumatic systems defend share in heavy-commercial segments.
End User:
Customer type determines procurement scale, with OEMs and Tier-1s driving specification standards that aftermarket providers must later match.
- OEMs:Vehicle manufacturers including Toyota, Hyundai, and Geely consolidate approved vendor lists around suppliers with simultaneous BIS, JIS, and GB certification capabilities.
- Aftermarket Providers:Independent distributors and service chains supply replacement actuators for out-of-warranty vehicles.
- Tier-1 Suppliers:Chassis and powertrain integrators such as Robert Bosch GmbH and Denso Corporation source actuators for assembly into larger systems.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations in Thailand and Indonesia.
Tier-1 suppliers capture the deepest volume pools, with aftermarket providers gaining share fastest as vehicle parc ages.
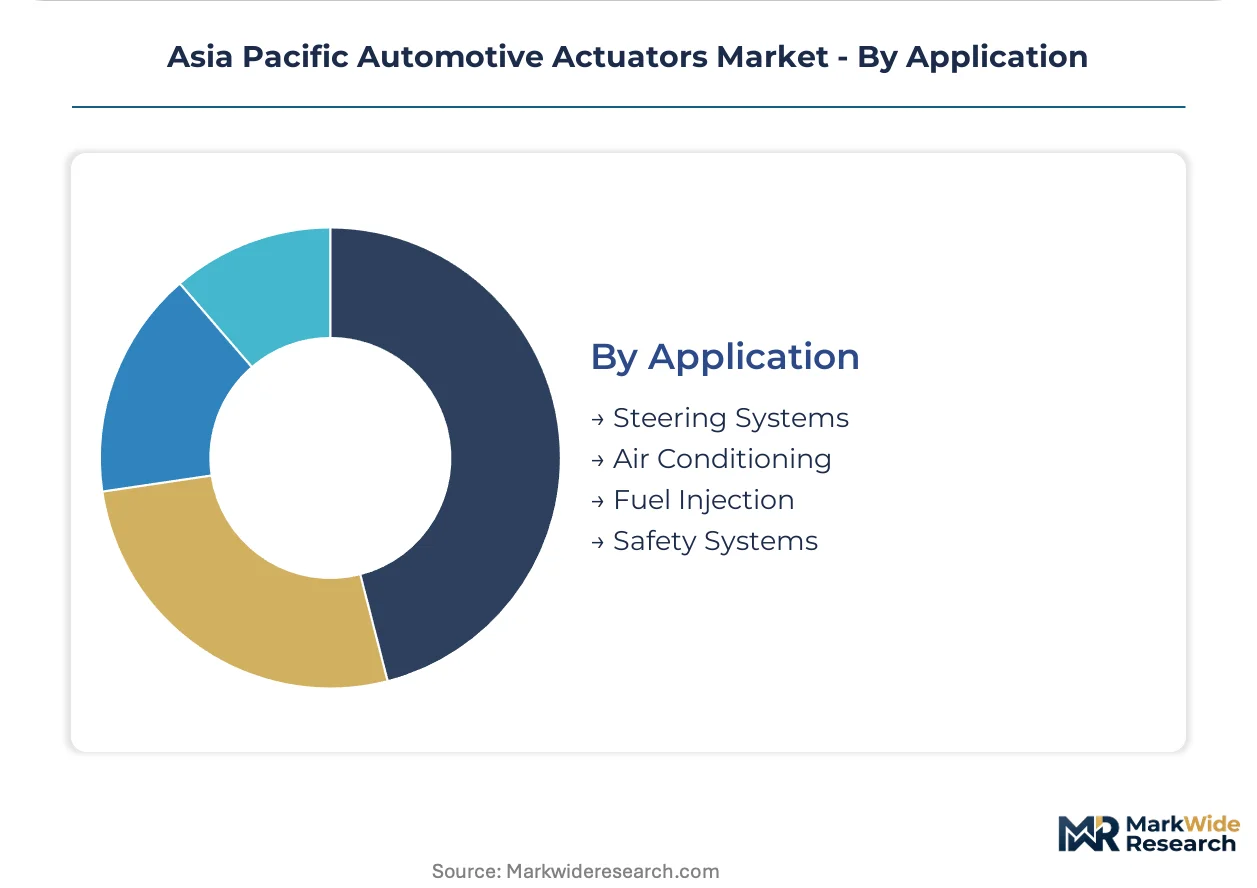
Application:
Application maturity varies, with safety-critical systems demanding ASIL-D functional safety certification that filters out second-tier suppliers.
- Steering Systems:Electric power steering actuators with torque and position feedback dominate new vehicle architectures. Japanese OEM lineups specify these for 48V mild-hybrid integration across ASEAN production bases.
- Safety Systems:Anti-lock braking and electronic stability control actuators require ISO 26262 ASIL-D validation. Development cycles of 18-24 months compress product refresh windows and favor incumbent suppliers with established testing infrastructure.
- Air Conditioning:HVAC blend door and compressor clutch actuators for thermal comfort management.
- Fuel Injection:Precision metering actuators for direct injection and port fuel injection systems.
Steering systems lead application volume, with safety systems expanding most quickly as brake-by-wire architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta automotive cluster anchors actuator procurement volume across the Asia Pacific region, with Shanghai, Jiangsu, and Zhejiang provinces hosting domestic EV brands and joint ventures sourcing brake and transmission actuators at scale.
China
BYD and NIO generate procurement volume for 48V and 800V thermal management actuators in crowded EV powertrain packaging. MIIT enforces GB standards for electromagnetic compatibility and functional safety that dictate design verification protocols. The Yangtze River Delta cluster enables just-in-time sourcing with reduced logistics friction for domestic brands and joint ventures.
Japan
Toyota-group and Honda procurement lists concentrate on suppliers with full-stack validation capabilities for brake and steering systems. METI carbon-neutrality roadmaps mandate lifecycle emissions disclosure from Tier-2 component suppliers. Kanto and Kansai industrial corridors host captive design-in relationships extending across ASEAN assembly footprints.
South Korea
Hyundai Motor Group consolidates approved vendor lists around suppliers with multi-country certification capabilities. MFDS-equivalent automotive safety frameworks filter unqualified competitors from safety-critical braking procurement. Seoul Capital Area and Busan-Ulsan manufacturing belts anchor electromechanical module production for export-oriented assembly.
India
Maruti Suzuki and Tata Motors drive localization requirements for engine and chassis actuators under BIS certification mandates. PLI scheme incentives for automotive components attract manufacturing investment to Tamil Nadu and Gujarat. Pune and Chennai industrial corridors concentrate Tier-1 supplier expansion serving domestic OEM assembly networks.
Thailand
Japanese and Korean OEMs redirect actuator investment toward ASEAN assembly footprints under Board of Investment tax holidays. EV supplier import duty exemptions accelerate electromechanical braking module qualification. Eastern Economic Corridor industrial zones concentrate contract manufacturing for regional vehicle export programs.
Asia Pacific Automotive Actuators Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue EV-native architectures and integrated motor-actuator modules. The supplier base concentrates around Tier-1 chassis integrators with captive foundry networks and multi-country testing infrastructure. Three archetypes dominate: integrated mechatronics manufacturers with regional foundry footprints, compact electric motor specialists targeting thermal management slots, and conglomerate-affiliated suppliers leveraging captive OEM relationships. Competitive moves center on qualification timeline compression and backward integration into rare-earth magnet supply chains.
Among Germany-based diversified suppliers, Robert Bosch GmbH and Continental AG anchor regional supply through integrated production networks. Denso Corporation exemplifies the conglomerate-affiliated archetype with design-in relationships extending across Japanese OEM lineups. These three occupy positions defined by certification breadth and captive customer access rather than interchangeable component supply.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Nidec Corporation |
| Johnson Electric |
| Mitsubishi Electric |
| Denso Corporation |
| Continental AG |
| Hella KGaA Hueck & Co |
| Hitachi Ltd |
| CTS Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive foundry networks at Robert Bosch GmbH and Denso Corporation anchor supply positions and pricing power across brake and engine actuator tiers. These integrated manufacturing footprints in India and Vietnam compress procurement costs for Japanese and Korean OEMs while filtering out competitors lacking multi-country production assets.
Pricing Analysis
Rare-earth magnet and power semiconductor cost pass-through dominates actuator pricing structures across the region. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D functional safety certification and volume scale, with brake actuators commanding the steepest premiums. Cost compression in pneumatic systems is intensifying because Indian heavy-commercial OEMs resist electrification retrofits. Tier-1 chassis integrators show the least price sensitivity; aftermarket distributors face the most margin pressure from unvalidated imports.
Supply Chain Analysis
Dual-sourcing requirements from Toyota-group and Hyundai procurement teams mandate multi-supplier qualification for safety-critical braking modules. Manufacturing concentrates in China, Vietnam, and India, with rare-earth magnets drawing from Chinese smelters and power MOSFETs resting on Taiwanese foundry output. Single-source semiconductor vulnerability exposes actuator manufacturers to allocation risk during automotive chip shortages. Distribution runs through Tier-1 chassis integrators to OEM assembly plants across the Yangtze River Delta and ASEAN industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated motor-actuator modules and brake-by-wire architectures are expanding margin pools for suppliers with ASIL-D validation capabilities. 48V mild-hybrid proliferation across Chinese and Japanese OEM lineups creates premium-tier pricing power for electromechanical specialists.
For Market Incumbents: Anchor regional supply positions through backward integration into rare-earth magnet supply chains and captive foundry expansion in Tamil Nadu and Vietnam. Denso Corporation's design-in relationships with Toyota-group platforms demonstrate how certification breadth filters emerging competitors. Incumbents must defend against integrated motor-actuator specialists by accelerating multi-standard validation timelines for BIS, JIS, and GB compliance.
For New Entrants and Emerging Players: Brake-by-wire electromechanical modules with integrated position sensing offer the most penetrable white space as hydraulic line elimination accelerates across next-generation chassis architectures. Target India's PLI scheme corridors in Gujarat for localized engine actuator production serving Maruti Suzuki and Tata Motors. Go-to-market leverage rests on simultaneous MIIT GB standard pre-certification to compress OEM qualification cycles.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap testing laboratories because multi-country certification infrastructure scarcity concentrates buyer dependence on validated facilities. The five-to-ten year viability window favors suppliers with captive rare-earth sourcing and ASEAN manufacturing footprints. Watch for MIIT export quota announcements on neodymium and dysprosium as the inflection signal for margin compression in permanent-magnet actuator tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Country Certification Investment | BIS, JIS, and GB simultaneous qualification filters 40% of competitors from Toyota and Hyundai approved vendor lists. |
| Rare-Earth Magnet Backward Integration | Captive sourcing from audited smelters satisfies METI lifecycle emissions disclosure mandates for Tier-2 supplier retention. |
| Brake-By-Wire Module Development | Elimination of hydraulic fluid lines creates white space for electromechanical braking actuators with ASIL-D validation. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat localization captures Maruti Suzuki and Tata Motors procurement under BIS certification mandates. |
| Integrated Motor-Actuator Module Production | Compact brushless DC designs achieve 30% volume reduction for BYD and NIO thermal management specifications. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and MIIT certification consultants grounded the qualitative foundation. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and ASEAN trade flow records. Bottom-up and top-down triangulation reconciled actuator shipment volumes with OEM platform content assumptions across the projection horizon.
Bottom-up modeling segmented volume and value outputs across propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical procurement patterns and OEM electrification roadmaps. Forecast inputs incorporated MIIT fuel-efficiency mandate compliance timelines and METI carbon-neutrality disclosure requirements throughout the modeling period.
The model holds under stable rare-earth export quota regimes and semiconductor foundry allocation continuity; deviation in Chinese magnet supply restrictions or Taiwan Strait logistics disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
India Automotive Sunroof Market