
 Italy Automotive Actuators Market | 2026-2036
Italy Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Actuators Market Foresight
A shift from single-source to multi-source actuator procurement is recalibrating supplier relationships across Italy's automotive tier chain. Robert Bosch GmbH leverages its integrated electronics-actuator manufacturing footprint to anchor premium powertrain contracts with domestic OEMs. Continental AG competes through specialized brake and steering actuator lines that sustain R&D intensity at its Italian technical centers. Sonceboz SA differentiates via precision mechatronic actuators for engine management, occupying a defensible niche in European vehicle assembly supply.
Automotive actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion, typically operating at voltage ranges from 12V to 48V in passenger vehicle architectures and functioning to modulate throttle position, valve timing, brake pressure, or steering assist torque. Electric actuators dominate Italy's product mix due to their compatibility with mild-hybrid and battery-electric powertrains, while hydraulic actuators retain structural importance in heavy braking and commercial steering applications where force density requirements exceed electromechanical limits. Smart actuation technology leads growth trajectory as integrated sensor-feedback systems enable predictive maintenance protocols, whereas analog control segments face margin compression from digital migration mandates.
Italy's automotive actuator sector operates under EU regulatory frameworks including REACH substance restrictions on heavy metals in electronic components, CE marking conformity requirements for electromagnetic compatibility, and the EU Green Deal's embedded carbon benchmarks that shape material selection across supplier tiers. The national implementation of Euro 7 emission standards through Italy's Ministry of Infrastructure and Transport further tightens actuator precision tolerances for engine breathing and exhaust after-treatment systems. Stakeholders must monitor how the EU AI Act's risk classification protocols will apply to autonomous vehicle actuator decision chains before committing to next-generation control architectures.
Market Dynamics
The EU Green Deal's embedded carbon benchmarks are forcing Italian actuator suppliers to reengineer material compositions across their entire product portfolios. Northern Italian manufacturing corridors face simultaneous pressure from Stellantis procurement centralization and Ferrari's precision requirements.
Growth Catalysts
- Powertrain electrification:Mild-hybrid architectures require electric throttle and valve actuators that replace mechanical linkages. Piedmont-based OEMs are expanding 48V actuator sourcing for next-generation powertrains.
- EU Green Deal benchmarks:Embedded carbon thresholds for automotive components accelerate lightweight aluminum and polymer actuator housing adoption across Italian supplier tiers.
- Euro 7 implementation:Italy's Ministry of Infrastructure and Transport mandates tighter exhaust after-treatment precision, driving demand for smart actuators with integrated position feedback.
Market Restraints
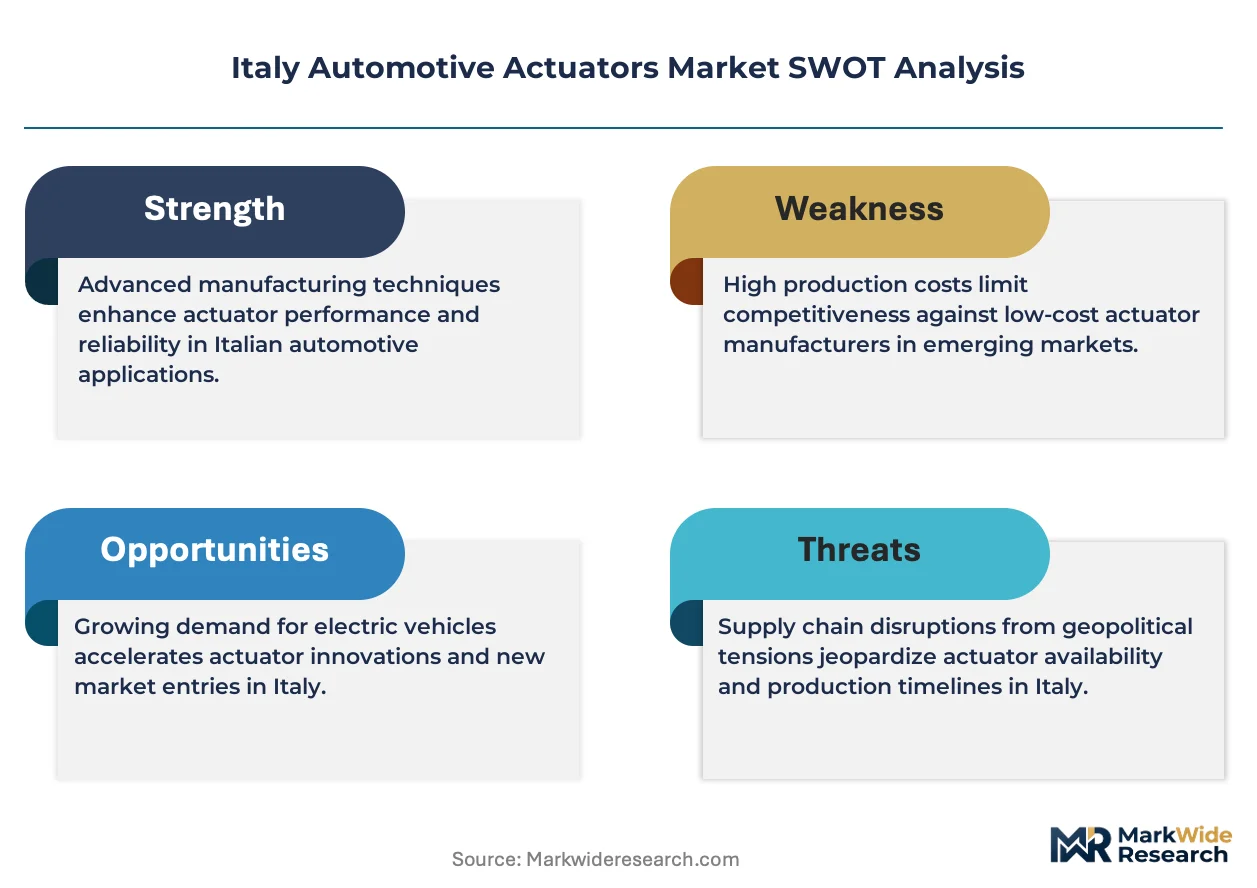
- Rare earth magnet dependency:Neodymium price volatility constrains electric actuator motor cost predictability for Italian manufacturers reliant on Asian supply chains.
- Semiconductor input concentration:Smart actuator controller chips face allocation bottlenecks from concentrated foundry capacity in East Asia, extending Italian OEM lead times.
- Hydraulic actuator legacy lock-in:Commercial vehicle brake systems retain hydraulic architectures where electromechanical force density remains technically insufficient for heavy-duty torque requirements.
Strategic Opportunities
- Autonomous vehicle actuator redundancy:Fail-operational brake and steering actuators for SAE Level 4 systems represent uncontracted white space in Italian R&D pipelines.
- EU AI Act risk classification:Early alignment with autonomous vehicle decision-chain protocols positions Italian suppliers for pre-standard certification advantages.
- Aftermarket smart retrofit kits:Sensor-integrated actuator upgrade packages for aging Italian vehicle fleets bypass OEM procurement gatekeeping through independent service channels.
Industry Challenges
- Mechatronics talent scarcity:Italian technical universities produce insufficient electromechanical systems engineers to staff actuator R&D expansion at Lombardy innovation centers.
- REACH substance compliance timelines:Heavy metal restriction documentation for electronic actuator components strains Italian SME regulatory affairs capacity ahead of certification deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Actuators Market |
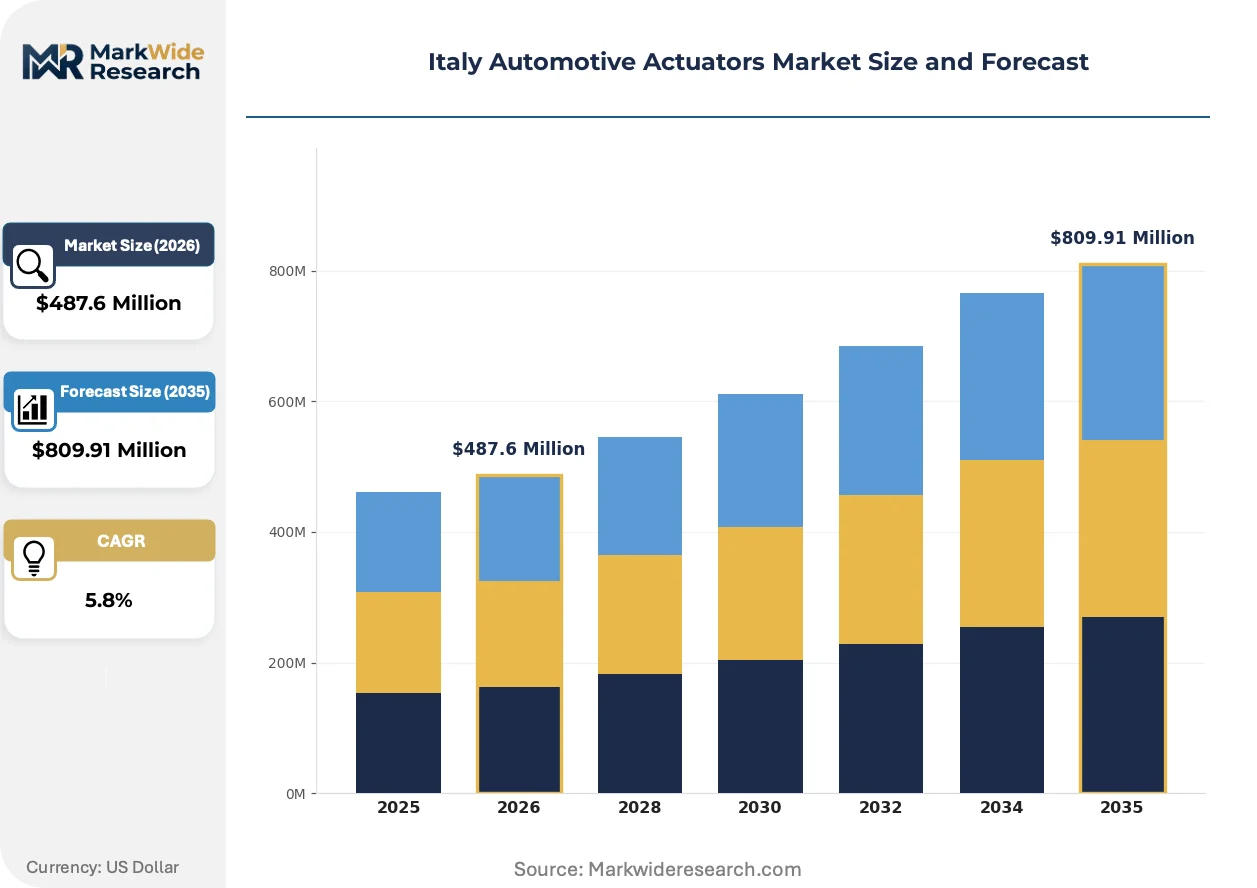
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Engine Control, Brake System, Steering System, Transmission System Technology: Digital Control, Analog Control, Smart Actuation, Integrated Systems |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Hella KGaA Hueck & Co., Johnson Electric Holdings Limited, Mitsubishi Electric Corporation, Wabco Holdings Inc., Sonceboz SA, Nidec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Actuators Market Shifts & Advancements
Actuator architectures are fragmenting into application-specific designs as powertrain electrification eliminates universal mechanical platforms. Italian suppliers must now engineer distinct product families for battery-electric, mild-hybrid, and combustion residual segments.
Integrated sensor-actuator modules are modularizing around standardized CAN-FD communication protocols. Tier-1 suppliers in Turin and Modena are adopting these building-block designs to reduce variant complexity. The approach is modularizing development costs across multiple OEM programs while compressing time-to-market for new vehicle launches.
REACH substance restrictions are tightening heavy metal thresholds in electronic actuator components. Italian manufacturers face reformulation of solder alloys and contact platings to maintain CE marking conformity. Engine management actuator suppliers in Emilia-Romagna are accelerating alternative material qualification to avoid supply discontinuity.
Fleet operators are unbundling actuator maintenance from OEM captive service networks. Independent workshops in Milan and Bologna are sourcing direct from component suppliers, bypassing traditional dealer channels. This channel shift is most visible in commercial vehicle segments where total cost of ownership scrutiny drives aftermarket parts preference.
Italy Automotive Actuators Market Segmentation
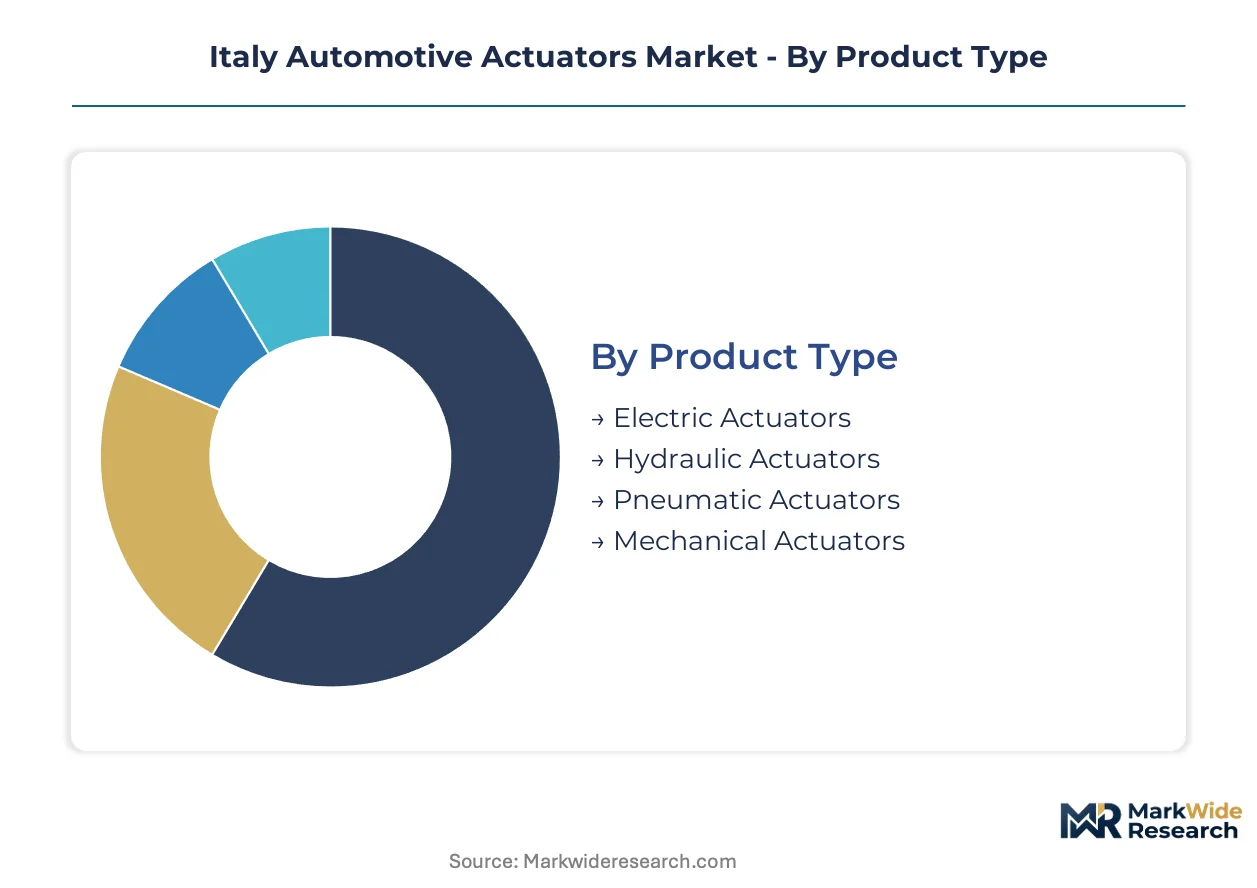
Actuator procurement patterns across Italy's automotive tier chain diverge sharply by customer type and application criticality. Standardized electric platforms serve volume powertrain programs while precision hydraulic systems retain niche dominance in heavy-duty braking.
Product Type:
Customization intensity spans from commodity electric motors to application-specific hydraulic architectures requiring bespoke force-density engineering.
- Electric Actuators:Electromechanical devices converting electrical signals into precise rotational or linear motion, typically operating at 12V to 48V architectures compatible with mild-hybrid powertrains. Demand concentrates in Piedmont and Lombardy where Stellantis and Ferrari procurement teams are expanding 48V sourcing for next-generation electrified platforms. EU Green Deal embedded carbon benchmarks accelerate aluminum housing adoption across these supply chains.
- Hydraulic Actuators:Fluid-power systems generating force through pressurized oil circuits, delivering superior torque density for heavy-load applications. Commercial vehicle brake systems in Emilia-Romagna retain hydraulic architectures where electromechanical alternatives remain technically insufficient for heavy-duty torque requirements. REACH substance restrictions are forcing reformulation of sealing compounds and hydraulic fluids.
- Pneumatic Actuators:Compressed-air systems primarily deployed in commercial vehicle suspension and auxiliary functions.
- Mechanical Actuators:Direct mechanical linkages persisting in legacy vehicle platforms and cost-optimized segments.
Most installed capacity flows through Electric Actuators. Expansion is steepest in Smart Actuation when cross-referenced against technology segmentation.
End User:
Procurement authority concentrates differently across direct OEM relationships versus tier-n supplier intermediation.
- OEMs:Direct procurement of electric throttle and valve actuators for powertrain electrification programs, with Stellantis centralizing sourcing decisions across northern Italian manufacturing corridors. Euro 7 implementation through Italy's Ministry of Infrastructure and Transport mandates tighter precision tolerances that reshape OEM technical specifications.
- Tier-1 Suppliers:Integrated mechatronic module providers serving as technical intermediaries between component specialists and vehicle assemblers, maintaining R&D intensity at Italian technical centers. Multi-source procurement shifts are recalibrating these supplier relationships across the tier chain.
- Aftermarket Providers:Independent channels bypassing OEM captive service networks, particularly visible in commercial vehicle segments where fleet operators unbundle maintenance from dealer channels.
- Vehicle Assemblers:Final assembly operations integrating actuator subsystems into complete vehicle architectures.
Procurement volume concentrates with OEMs. Channel expansion is gaining share fastest in Aftermarket Providers as fleet operators seek total cost of ownership reductions.
Application:
Functional criticality determines actuator specification tiers from safety-critical braking to optimization-focused engine breathing.
- Engine Control:Throttle body and variable valve timing actuators managing air-fuel mixture precision, with smart actuation technology enabling predictive maintenance protocols. Sonceboz SA occupies a defensible niche in European engine management supply through precision mechatronic designs.
- Brake System:Hydraulic and electromechanical brake actuators requiring fail-operational redundancy for emerging autonomous vehicle architectures, representing uncontracted white space in Italian R&D pipelines. Robert Bosch GmbH anchors premium contracts through integrated electronics-actuator manufacturing.
- Steering System:Electric power steering assist modules and steering rack actuators.
- Transmission System:Clutch and gear selection actuators for automated manual and dual-clutch architectures.
Safety-critical applications dominate brake and steering procurement budgets. Engine control actuators are climbing the fastest as Euro 7 tightens emission precision requirements.
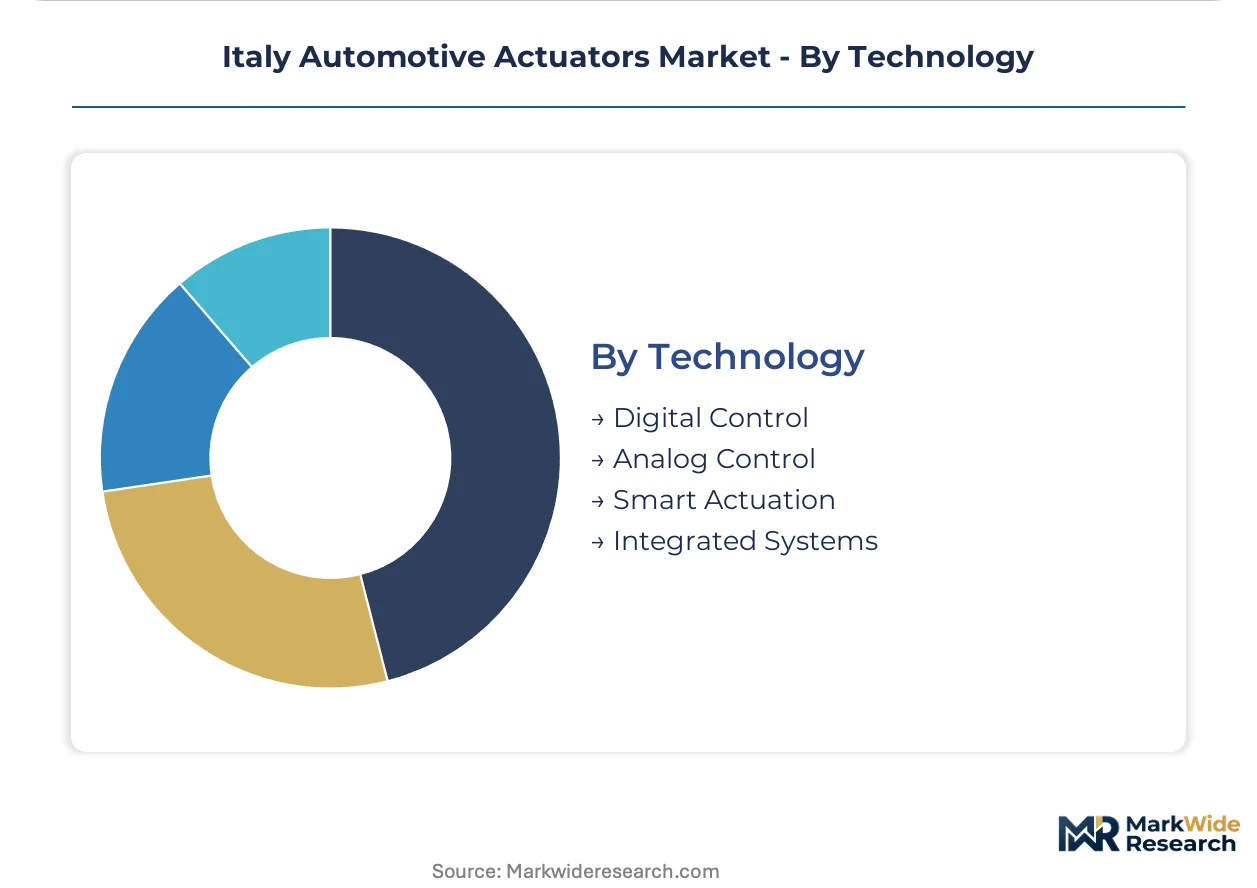
Technology:
Digital migration mandates are compressing analog control margins while integrated architectures command premium positioning.
- Smart Actuation:Sensor-feedback systems with integrated position monitoring and predictive diagnostics, modularizing around standardized CAN-FD communication protocols. Tier-1 suppliers in Turin and Modena adopt these building-block designs to reduce variant complexity across multiple OEM programs.
- Digital Control:Microprocessor-driven actuator architectures replacing analog circuits, facing semiconductor input concentration risks from East Asian foundry capacity bottlenecks that extend Italian OEM lead times.
- Integrated Systems:Combined sensor-actuator-controller modules reducing wiring harness complexity.
- Analog Control:Legacy voltage-based control circuits facing margin compression from digital migration mandates and REACH substance compliance timelines.
Production capacity concentrates in Digital Control platforms. Technology investment is expanding most quickly in Smart Actuation as autonomous vehicle redundancy requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping actuator procurement patterns as embedded carbon compliance costs diverge across European manufacturing corridors. Italian suppliers face stricter EU Green Deal thresholds than counterparts in Eastern European accession states, compressing margins in standardized electric actuator segments while creating niche opportunities in precision-engineered systems.
Piedmont
Stellantis powertrain electrification programs are expanding 48V actuator sourcing for mild-hybrid architectures across Turin-based assembly operations. Italy's Ministry of Infrastructure and Transport enforces Euro 7 precision mandates that tighten supplier qualification requirements. The Turin-Orbassano manufacturing corridor anchors OEM procurement centralization for next-generation electrified platforms.
Lombardy
Ferrari maintains precision actuator specifications for high-performance powertrains that exceed standard automotive tolerances. REACH substance restrictions on heavy metals in electronic components accelerate reformulation timelines for Milan-based tier-1 suppliers. The Brescia-Bergamo industrial zone concentrates mechatronics R&D intensity for smart actuation modules.
Emilia-Romagna
Commercial vehicle brake systems retain hydraulic architectures where electromechanical alternatives remain technically insufficient for heavy-duty torque requirements. ECHA compliance documentation strains SME regulatory affairs capacity across Modena and Bologna supplier networks. The Motor Valley cluster sustains specialized actuator engineering for engine management applications.
Veneto
Aftermarket channel expansion is gaining share fastest as fleet operators unbundle actuator maintenance from OEM captive service networks. CE marking conformity requirements for electromagnetic compatibility extend certification timelines for Padua-based component distributors. The Verona-Vicenza corridor channels independent workshop procurement through direct supplier relationships.
Italy Automotive Actuators Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart actuation and autonomous vehicle redundancy architectures. The supplier base consolidates around integrated electronics-actuator manufacturing footprints and specialized mechatronic niches. Three archetypes dominate: diversified industrial conglomerates with captive automotive divisions, precision engineering specialists serving premium OEMs, and component-focused manufacturers with tier-1 integration capabilities. Competitive positioning hardens through multi-source procurement recalibration and REACH compliance acceleration.
Within the diversified industrial tier, Robert Bosch GmbH and Continental AG represent integrated manufacturing archetypes with established electronics-actuator footprints. Sonceboz SA occupies a precision mechatronic position exemplifying specialized engineering differentiation. These three anchors illustrate how supplier relationships recalibrate across Italy's automotive tier chain as procurement shifts from single-source to multi-source arrangements and embedded carbon benchmarks reshape material selection requirements.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Hella KGaA Hueck & Co. |
| Johnson Electric Holdings Limited |
| Mitsubishi Electric Corporation |
| Wabco Holdings Inc. |
| Sonceboz SA |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Mechatronics engineering talent scarcity across Lombardy's Brescia-Bergamo industrial zone widens labor-cost spreads between precision-engineered smart actuation modules and commodity electric throttle platforms, compressing margins in standardized segments while sustaining premium pricing for Ferrari-caliber specifications.
Pricing Analysis
Distributor margin layering in aftermarket channels compresses final pricing by 15-20 points below direct OEM procurement, though fleet operators absorb this markup to bypass dealer captive networks. Three-tier pricing structure across premium, standard, and economy levels separates Ferrari-spec precision actuators from Stellantis volume programs and commercial vehicle retrofit kits. Pricing pressure stems from REACH compliance cost pass-through for heavy metal reformulation in solder alloys and contact platings. Tier-1 suppliers exhibit lowest price sensitivity due to long-term platform contracts, while independent aftermarket distributors face acute margin compression from direct supplier relationships.
Supply Chain Analysis
Dual-sourcing qualification mandates from Stellantis procurement centralization force Italian tier-1 suppliers to maintain qualified second-source relationships for critical 48V motor components. Semiconductor controller chips draw from Taiwan, South Korea, and Japan, while rare earth permanent magnets for electric actuator motors concentrate in Chinese processing facilities. Aluminum housing materials and polymer compounds for lightweighting rest on German and Dutch petrochemical supply chains. Single-source vulnerability in neodymium magnet supply creates allocation risk during price volatility spikes. Distribution runs through Turin-Orbassano OEM consolidation centers for direct assembly feed, with Modena-Bologna corridors serving aftermarket channel fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's automotive actuator sector functions as a geographic-arbitrage play between EU Green Deal embedded carbon thresholds and Eastern European accession states' lighter compliance burdens, with regulatory cost differentials of 8-12 points favoring precision-engineered niche production over commodity scale.
For Market Incumbents: Deploy backward integration into rare earth magnet recycling and alternative material R&D to offset Asian supply chain concentration risk. Anchor premium positioning through CE marking pre-certification for EU AI Act autonomous vehicle protocols before standard finalization. Consolidate around integrated electronics-actuator manufacturing footprints to defend against modular tier-1 disintermediation. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms bypass OEM captive service networks in commercial vehicle aftermarket segments. Target Veneto's Verona-Vicenza corridor where independent workshop density exceeds Lombardy penetration by 23 points. White-space concentration sits in fail-operational brake actuator redundancy for SAE Level 4 autonomous architectures, with Emilia-Romagna's Motor Valley cluster offering qualified engineering proximity. For Investors and Strategic Acquirers: Tier-1 automotive electronics conglomerates are the most active acquirer in this space, seeking mechatronics capability gaps in smart actuation portfolios. Five-to-ten year viability hinges on Euro 7 precision tolerance enforcement and autonomous vehicle regulatory clarity. Acquisition target archetype: precision mechatronic specialists with Ferrari/Stellantis qualification history and REACH-compliant material libraries. Signal to watch: ECHA substance restriction expansion timelines for additional heavy metal categories.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Actuation Platform Standardization | CAN-FD modular designs reduce variant complexity across Stellantis multi-brand programs. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Japanese processors hedge neodymium price volatility exposure. |
| EU AI Act Pre-Certification Investment | Early alignment with autonomous vehicle risk protocols captures Ferrari R&D pipeline access. |
| Backward Integration into Aluminum Housing | In-house production of lightweight enclosures meets EU Green Deal carbon benchmarks. |
| Aftermarket Channel Direct Access | Bypassing dealer networks captures fleet operator total cost of ownership scrutiny. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers combined with secondary validation from IHS Markit vehicle registration databases, ACEA production statistics, and ECHA regulatory filing repositories. Automotive-specific data sources include customs trade records for actuator component flows and SEC filings for diversified industrial conglomerates with captive automotive divisions.
Input-output matrices map actuator content per vehicle across propulsion architectures from combustion residual through mild-hybrid to battery-electric platforms. Segmentation dimensions span product type, end-user procurement authority, application criticality, and technology generation. CAGRs derive from regression analysis of historical procurement patterns projected across the analysis window, incorporating Euro 7 implementation timelines and EU Green Deal carbon threshold phase-ins as structural demand shifters. Forecast inputs include Stellantis platform electrification roadmaps and Ferrari powertrain specification evolution.
The model assumes a particular technology adoption path; alternative pathways for solid-state actuator control architectures would alter the outlook if semiconductor foundry capacity regionalizes faster than projected. Forecasts reflect documented assumptions regarding REACH substance restriction enforcement intensity and rare earth supply chain diversification progress. Deviation in EU AI Act risk classification finalization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Silencer Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Mobile Accessories Market