
 Automotive Connecting Rod Bearing Market | 2026-2036
Automotive Connecting Rod Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
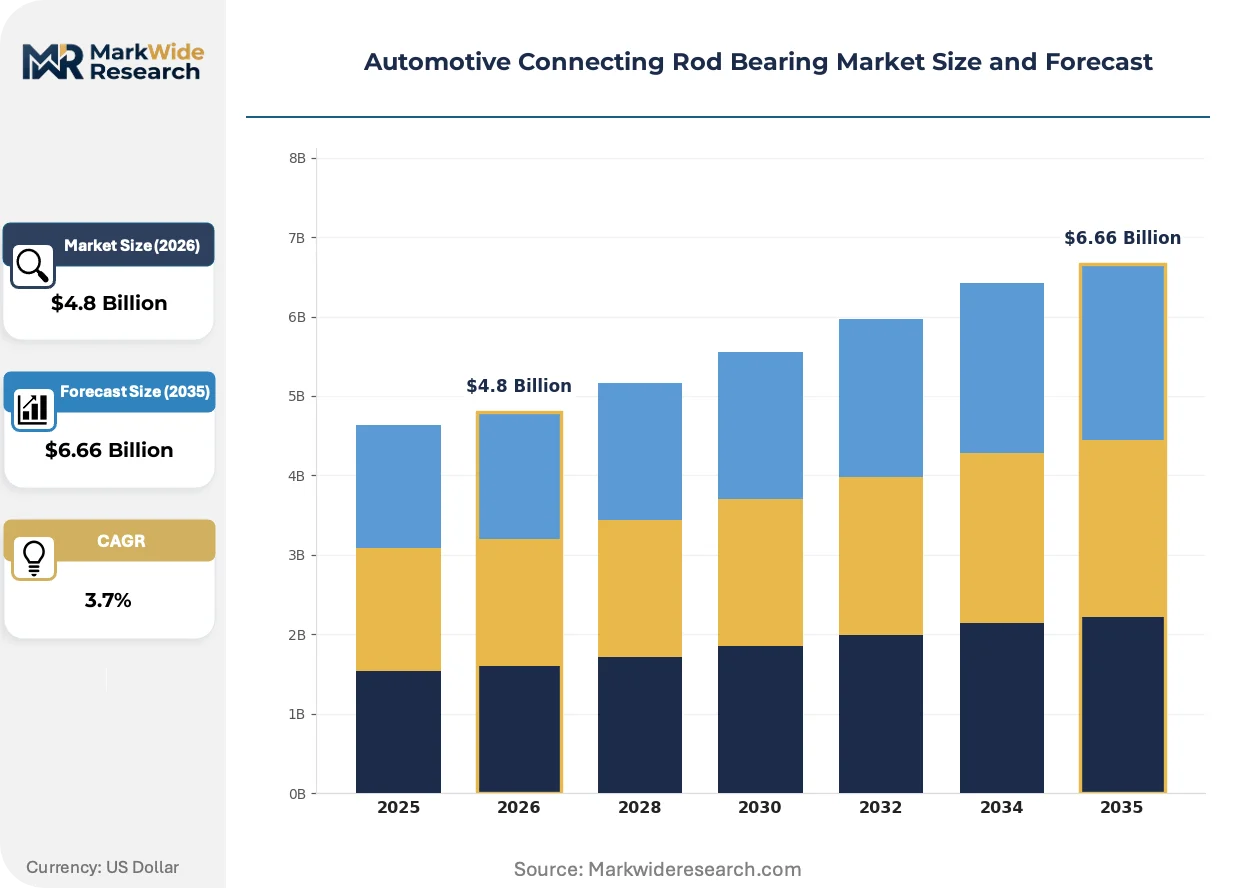
Automotive Connecting Rod Bearing Market Outlook
Modular engine architecture is decoupling bearing procurement from full crankshaft assemblies, letting buyers specify connecting rod bearings as standalone performance tiers. MAHLE GmbH leverages its vertically integrated powder-metallurgy capacity to supply OEM-specified aluminum-tin bearings across European passenger car programs. Federal-Mogul (Tenneco) anchors aftermarket demand through Clevite-branded replacement channels in North American heavy-duty fleets. Daido Metal Co., Ltd. dominates Japanese OEM supply through its copper-lead sputtered bearing technology.
An automotive connecting rod bearing is a split cylindrical shell, typically steel-backed with a babbitt, aluminum, or copper-lead overlay, that interfaces between the connecting rod small end and the crankshaft journal to manage hydrodynamic lubrication under cyclic combustion loads. It must maintain oil film integrity across thermal excursions from cold start to peak operating temperatures near 150°C while resisting fatigue from millions of firing cycles. Full floating configurations lead OEM installations for their self-aligning properties and reduced journal wear, though semi-floating designs sustain margin pools in high-performance aftermarket applications where tuners prioritize direct control over bearing clearance. Aluminum material grades capture the fastest growth trajectory as OEMs shed lead content to meet REACH and RoHS substance restrictions, while bronze retains niche dominance in racing vehicles where extreme load tolerance overrides cost sensitivity.
EPA tailpipe standards and the EU Green Deal's combustion efficiency mandates are forcing OEMs to tighten bearing tolerances and reduce friction coefficients to extract marginal fuel economy gains from internal combustion platforms. NHTSA corporate average fuel economy rules in the United States and China's MIIT passenger vehicle fuel consumption limits create parallel compliance pressures that standardize multi-layer bearing specifications across export programs. Stakeholders must monitor how Euro 7's particulate and NOx limits accelerate engine downspeeding strategies, since lower rpm operation alters hydrodynamic bearing load profiles and shifts material specification priorities away from traditional high-speed formulations.
Market Dynamics
Engine downspeeding strategies driven by Euro 7 and EPA Tier 4 emission standards are compressing bearing operating rpm ranges and forcing material specification pivots away from legacy high-speed aluminum-tin formulations toward multi-layer steel-backed composites.
Growth Catalysts
- REACH substance restrictions:European chemical regulations banning lead content in automotive components are accelerating OEM migration to lead-free aluminum bearing alloys and sputtered copper-lead alternatives.
- Thailand's Eastern Economic Corridor:Japanese automaker powertrain localization is concentrating demand for high-load bearings in Southeast Asian light commercial vehicle assembly plants.
- Dual carbon goals:China's MIIT passenger vehicle fuel consumption limits are mandating friction coefficient reductions in powertrain components to squeeze marginal efficiency gains from combustion platforms.
Market Restraints
- Copper price volatility:Sputtered copper-lead bearing substrates face input cost instability from London Metal Exchange copper futures, compressing margin pools for specialty overlay suppliers.
- Japanese OEM supply concentration:Daido Metal's dominance through copper-lead sputtering technology creates single-source risk for European and North American automakers seeking qualified second-source suppliers.
- Semi-floating design obsolescence:Full floating bearing configurations now lead OEM installations, relegating semi-floating architectures to shrinking high-performance aftermarket niches.
Strategic Opportunities
- Indian commercial vehicle expansion:Bharat Stage VI emission implementation is driving domestic heavy-duty engine production and localized bearing procurement outside traditional Japanese supply chains.
- Powder-metallurgy convergence:Integration of additive manufacturing with conventional sintering processes enables complex internal geometries for improved oil retention in high-load applications.
- EU Green Deal combustion efficiency mandates:Regulatory pressure to extend internal combustion platform viability creates demand for next-generation low-friction bearing surfaces in European passenger car programs.
Industry Challenges
- Tribology specialist scarcity:Hydrodynamic lubrication modeling expertise sits concentrated among aging engineering cohorts at established Tier 1 suppliers, constraining new entrant R&D velocity.
- Euro 7 certification timelines:Accelerated particulate and NOx limit implementation compresses bearing validation cycles, forcing parallel track development against unfinalized test protocols.
- Legacy crankshaft integration:Modular engine architecture decoupling requires bearing suppliers to reconfigure quality systems for standalone component qualification rather than assembly-level acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Connecting Rod Bearing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Floating, Semi-Floating, Fixed, Others End User: OEMs, Aftermarket Providers, Repair Shops, Vehicle Assemblers Material: Aluminum, Steel, Bronze, Plastic Application: Passenger Vehicles, Commercial Vehicles, Racing Vehicles, Heavy Machinery |
| Companies Covered | MAHLE GmbH, Federal-Mogul (Tenneco), Daido Metal Co., Ltd., Clevite (Dana Inc.), King Engine Bearings, Schaeffler Group, NSK Ltd., Taiho Kogyo Co., Ltd., ACL Bearing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Connecting Rod Bearing Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to displace century-old babbitt metal formulations. Bearing suppliers now compete on sputtering precision and aluminum alloy microstructure control rather than conventional casting economies.
Tri-metal sputtering technology deposits nanoscale copper-lead overlays onto steel backings with thickness tolerances below five microns. European passenger car OEMs have adopted this process for Euro 7 pre-compliance engine builds. The technology is automating quality inspection protocols previously dependent on destructive metallographic sampling.
REACH Annex XVII lead restrictions and RoHS automotive exemptions are tightening in parallel, eliminating historical material carve-outs for internal combustion components. ECHA substance evaluation is forcing reformulation of traditional high-lead bronze alloys within the current regulatory window. Aftermarket suppliers serving North American heavy-duty fleets now face inventory stranding risk from incompatible chemistry specifications.
Fleet operators and independent repair channels are unbundling bearing replacement from full engine rebuilds, compressing order cycles and fragmenting volume across SKU proliferation. E-commerce parts platforms are capturing share from traditional jobber distribution in North American aftermarket segments. This pattern concentrates most visibly in independent heavy-duty repair shops across the US Midwest and Southeast corridor states.
Automotive Connecting Rod Bearing Market Segmentation
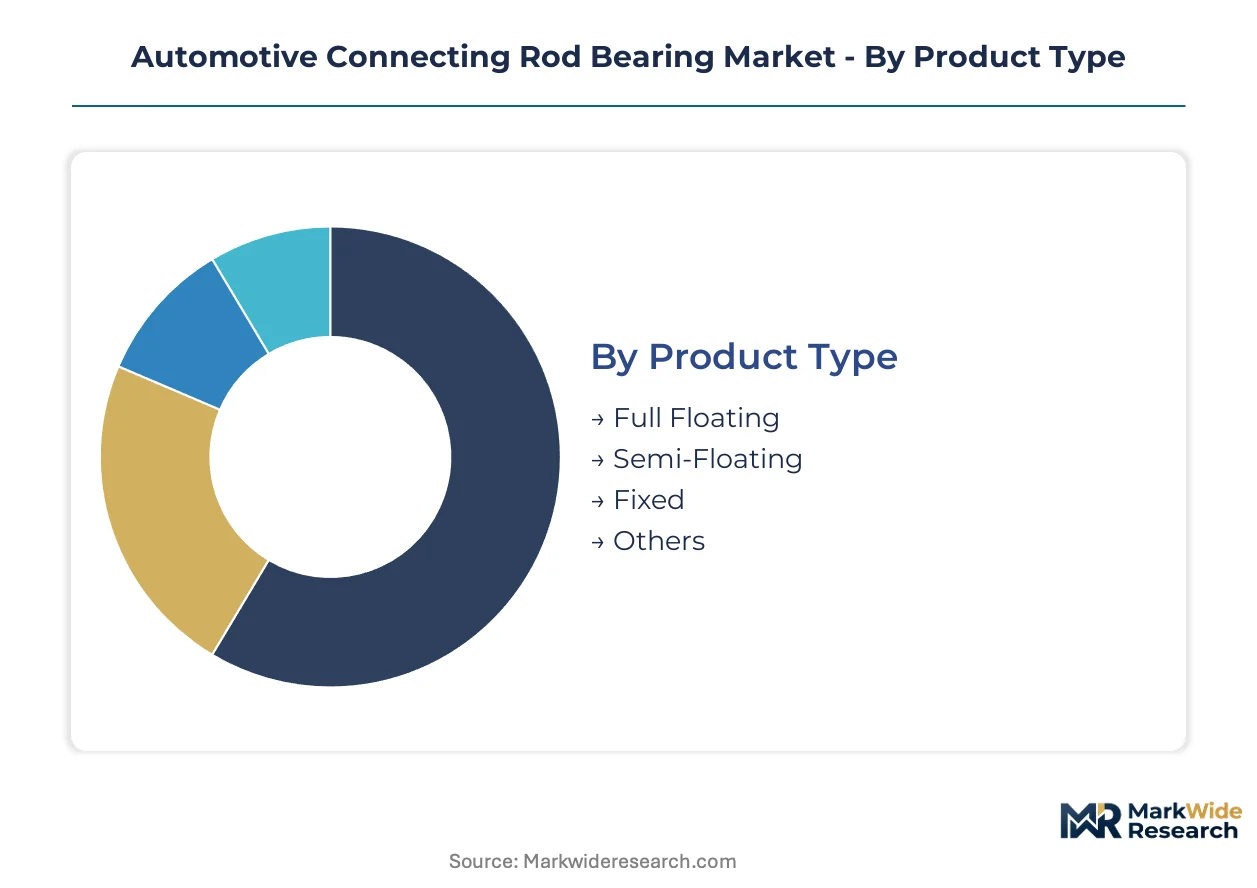
Segmentation in the Automotive Connecting Rod Bearing Market reveals how regulatory chemistry bans and engine architecture shifts are redistributing procurement volumes across material grades and bearing configurations. Suppliers must align certification pathways with each segment's distinct approval burden.
Product Type:
Full floating bearings carry Euro 7 pre-compliance validation requirements for European passenger car programs, while semi-floating configurations face no mandatory OEM certification for aftermarket racing applications. EPA Tier 4 and NHTSA friction reduction mandates apply differentially based on self-aligning versus fixed-mount geometries.
- Full Floating:Steel-backed shells with independent rotation capability maintain hydrodynamic oil films through crankshaft journal misalignment. OEM procurement concentrates in Japanese automaker powertrain localization across Thailand's Eastern Economic Corridor as emission standards tighten bearing tolerance specifications. Dual carbon goals from China's MIIT accelerate specification for friction-critical passenger vehicle platforms.
- Semi-Floating:Direct pin-to-bearing contact delivers tunable clearance control for high-performance aftermarket rebuilds. Demand clusters in North American independent heavy-duty repair shops where fleet operators prioritize direct journal wear monitoring over OEM warranty coverage.
- Fixed:Press-fit steel shells without rotational freedom serve cost-optimized small engine applications.
- Others:Hybrid configurations combining floating and fixed elements address niche agricultural machinery requirements.
Full floating sits at the top of the volume ranking, with semi-floating climbing the fastest as racing aftermarket channels fragment order cycles.
End User:
Cost tier stratification separates qualification-intensive OEM supply from price-sensitive aftermarket channels, with repair shops occupying a volatile middle ground between warranty compliance and independent sourcing flexibility.
- OEMs:Powertrain manufacturers enforce REACH Annex XVII substance documentation and RoHS automotive exemption tracking across aluminum-tin and copper-lead bearing chemistries. Japanese OEM supply chains dominate through Daido Metal's sputtering technology, creating single-source risk for European and North American programs seeking qualified alternatives.
- Aftermarket Providers:Clevite-branded replacement channels in North American heavy-duty fleets anchor demand through jobber distribution networks now losing share to e-commerce parts platforms.
- Repair Shops:Independent operators across US Midwest and Southeast corridor states unbundle bearing replacement from full engine rebuilds, compressing SKU proliferation into fragmented order cycles.
- Vehicle Assemblers:Light commercial vehicle producers in Southeast Asian assembly plants concentrate high-load bearing procurement as localization accelerates.
OEMs command the highest absolute volumes, with aftermarket providers gaining share fastest through digital distribution disruption.
Material:
Application-driven specification splits between lead-free regulatory compliance in mass-market automotive and extreme load tolerance in performance segments where substance restrictions carry exemption pathways.
- Aluminum:Lead-free aluminum-tin alloys from MAHLE GmbH's powder-metallurgy capacity capture specification across European passenger car programs as ECHA substance evaluation eliminates historical bronze carve-outs. REACH and RoHS convergence accelerates fastest expansion trajectory among material grades.
- Bronze:High-lead bronze retains niche dominance in racing vehicles where extreme cyclic load tolerance overrides cost sensitivity and regulatory exemption windows remain operative.
- Steel:Backing substrates for multi-layer sputtered composites dominate Euro 7 pre-compliance engine builds.
- Plastic:Polymer-lined bearings address specialized low-load auxiliary applications with minimal friction requirements.
Aluminum leads volume rankings as regulatory chemistry bans displace legacy formulations, with bronze holding stable in exempted performance segments.
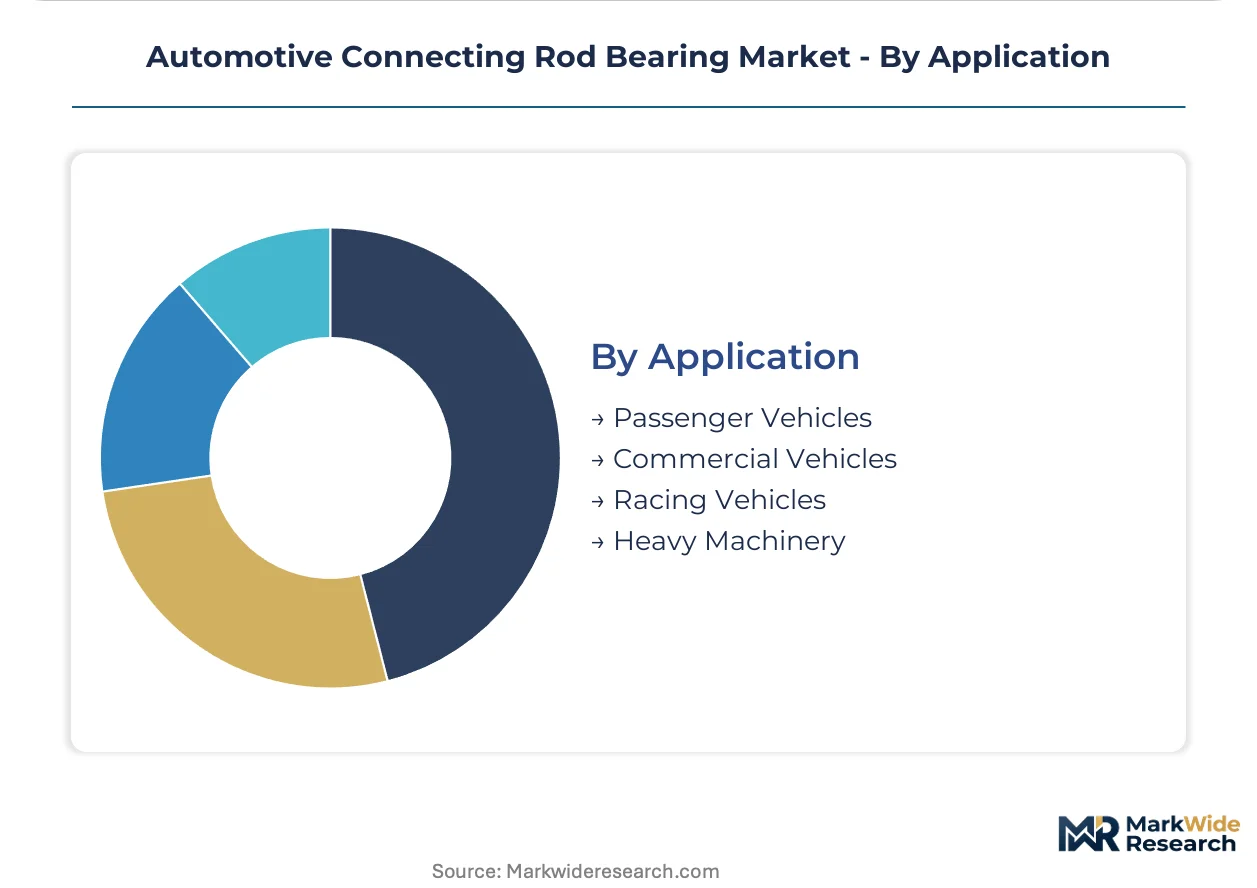
Application:
Customer type differentiation separates fleet-scale procurement with standardized multi-layer specifications from individualized racing builds where material tolerance extremes justify premium overlay chemistry.
- Passenger Vehicles:European OEMs specify tri-metal sputtered bearings with nanoscale copper-lead overlays below five micron thickness tolerances for Euro 7 combustion efficiency mandates. Bharat Stage VI implementation in India drives domestic heavy-duty engine localization outside traditional Japanese supply chains.
- Commercial Vehicles:Light commercial vehicle OEMs in Thailand's Eastern Economic Corridor expand orders for high-load bearings as powertrain assembly concentrates in Southeast Asian export platforms.
- Racing Vehicles:Semi-floating configurations sustain margin pools where tuners prioritize direct clearance control over self-aligning properties.
- Heavy Machinery:Agricultural and construction equipment applications specify fixed bearings for cost-optimized durability in intermittent duty cycles.
Passenger vehicles anchor volume concentration, with commercial vehicles expanding most quickly through emission-driven powertrain localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connecting rod bearing manufacturing traces its industrial lineage to German precision engineering centers and Japanese automotive supply chains established during the mid-20th century expansion of mass-market vehicle production. These foundational clusters continue to shape global specification standards and material science advancement.
Germany
MAHLE GmbH anchors European OEM supply through powder-metallurgy capacity serving passenger car programs. REACH Annex XVII substance documentation requirements from ECHA accelerate lead-free aluminum alloy migration. Manufacturing concentrates in Stuttgart and Nuremberg metropolitan zones where powertrain R&D facilities cluster alongside automotive headquarters.
Japan
Daido Metal Co., Ltd. dominates domestic OEM supply chains through copper-lead sputtering technology developed for high-load applications. METI industrial standards enforce bearing tolerance specifications that propagate across export programs. Production gravity centers on Aichi Prefecture's Nagoya industrial corridor, where Toyota and Honda powertrain assembly localizes procurement.
Thailand
Japanese automaker powertrain localization in the Eastern Economic Corridor concentrates demand for high-load bearings serving light commercial vehicle export platforms. Board of Investment incentives attract tier-1 supplier facility investment alongside emission standard harmonization with Euro 7. Rayong and Chonburi provinces host the densest concentration of engine assembly plants and bearing qualification laboratories.
United States
Federal-Mogul anchors aftermarket demand through Clevite-branded replacement channels serving North American heavy-duty fleets. NHTSA corporate average fuel economy rules mandate friction coefficient reductions that standardize multi-layer bearing specifications. Distribution and technical service operations cluster in Michigan's automotive corridor and Ohio's industrial Midwest.
India
Bharat Stage VI emission implementation drives domestic heavy-duty engine production outside traditional Japanese supply chains. Ministry of Heavy Industries production-linked incentive schemes support localized bearing procurement for commercial vehicle programs. Manufacturing investment concentrates in Tamil Nadu's Sriperumbudur-Oragadam belt and Maharashtra's Pune-Chakan automotive cluster.
Automotive Connecting Rod Bearing Market Competitive Environment
Premium-margin players sit above commodity-margin players across material science capability and OEM certification depth, creating a tiered competitive structure. The vendor base organizes around three strategic archetypes: vertically integrated powder-metallurgy specialists, sputtering technology leaders, and aftermarket distribution anchors. Consolidation pressure operates through backward integration moves by powertrain manufacturers and capacity expansion by qualified second-source suppliers seeking to displace single-source dependencies.
Within the vertically integrated tier, MAHLE GmbH and Schaeffler Group represent German-engineered precision manufacturing archetypes with captive material production capabilities. Daido Metal Co., Ltd. anchors Japanese OEM supply chain concentration through specialized overlay deposition expertise. Federal-Mogul exemplifies aftermarket channel dominance through branded replacement networks spanning North American fleet service infrastructure.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Federal-Mogul (Tenneco) |
| Daido Metal Co., Ltd. |
| Clevite (Dana Inc.) |
| King Engine Bearings |
| Schaeffler Group |
| NSK Ltd. |
| Taiho Kogyo Co., Ltd. |
| ACL Bearing Company |
| Others |
Value Chain & Pricing Dynamics
Euro 7 pre-compliance validation requirements are compressing procurement timelines and forcing bearing suppliers to absorb certification costs upfront, which reshapes margin distribution across aluminum-tin and copper-lead formulation tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified sputtered bearings from aftermarket jobber channels and racing semi-floating configurations. Price differentiation hinges on REACH Annex XVII substance documentation burden and MIIT friction coefficient certification tier. Cost compression in aluminum alloy grades is intensifying because ECHA evaluation timelines compress supplier R&D amortization windows. Fleet operators in North American heavy-duty segments exhibit highest price sensitivity, while Japanese OEM procurement through Daido Metal's technology maintains lowest elasticity due to single-source dependency.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and Thailand form a hub-and-spoke pattern that feeds bearing shell production into powertrain assembly clusters. Raw material sourcing draws from LME copper futures markets for sputtered overlays, powder-metallurgy aluminum feedstock from European smelters, and steel backing substrates from integrated mills. Single-source vulnerability concentrates in Japanese sputtering technology for high-load applications. Distribution runs through tier-1 supplier direct-ship programs to OEM engine plants and fragmented jobber networks serving aftermarket rebuild channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through Bharat Stage VI localization in India, where emission-driven domestic engine production escapes Japanese supply chain premiums.
For Market Incumbents: Anticipate REACH Annex XVII lead restriction acceleration by securing alternative sputtering capacity outside Aichi Prefecture concentration. Backward integration into powder-metallurgy aluminum production defends margin position against commodity feedstock volatility. Certification investment in Euro 7 pre-validation protocols creates switching costs for OEM procurement committees. For New Entrants and Emerging Players: The premium-to-economy price gap in sputtered copper-lead bearings opens entry space for qualified second-source suppliers targeting European passenger car programs. White-space concentrates in Indian commercial vehicle localization outside traditional Daido Metal supply chains. A direct technical sales approach to Bharat Stage VI engine developers bypasses entrenched Japanese distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with powder-metallurgy specialists possessing captive aluminum alloy formulation capability. Long-term viability hinges on extending internal combustion platform relevance through friction reduction technology rather than electrification displacement. Watch for Euro 7 final protocol publication as inflection signal for validation cycle compression and qualification backlog formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Powder Production | Captive supply of lead-free alloy feedstock secures MAHLE GmbH's REACH compliance positioning. |
| Second-Source Qualification Programs | European OEMs reduce Daido Metal dependency through parallel sputtering technology validation. |
| Localized Bearing Procurement in India | Domestic heavy-duty engine production outside Japanese supply chains captures Bharat Stage VI volume. |
| E-Commerce Platform Expansion | Digital distribution disrupts Clevite-branded jobber networks in North American aftermarket segments. |
| Additive Manufacturing Convergence | Complex internal geometries from sintering integration improve oil retention for high-load applications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and powder-metallurgy R&D directors with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from bearing manufacturers, and ECHA substance evaluation records. Bottom-up volume builds and top-down market reconciliation anchored segment-level outputs.
Comparable historical periods across the analysis window established baseline growth trajectories for aluminum, bronze, and steel material grades. Segmentation modeling incorporated product type configuration, end-user channel, material chemistry tier, and application duty cycle. CAGRs emerged from regression against powertrain production forecasts and emission standard implementation timelines. Forecast inputs included Euro 7 pre-compliance engine build schedules and Thailand Eastern Economic Corridor localization rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery displacement of combustion platforms would alter the outlook. Forecasts reflect documented assumptions regarding REACH enforcement timing and copper price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
India Automotive Heat Exchanger Market