
 Japan Automotive Sunroof Market | 2026-2036
Japan Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Sunroof Market Foresight
Premium passenger vehicle buyers is redrawing procurement priorities across Japanese OEM supply chains. Aisin Corporation leverages its integrated powertrain and body component expertise to anchor sunroof module assembly lines serving Toyota and Lexus platforms. Webasto Group competes through technology leadership in large-format panoramic sealing systems designed for electric vehicle architectures. Yachiyo Industry sustains its position via specialized stamping and glass bonding operations concentrated in domestic passenger car programs.
An automotive sunroof constitutes a panel assembly integrated into a vehicle roof structure, typically incorporating tempered or laminated glass, polycarbonate, or composite substrates with weather sealing, drainage channels, and motorized or manual actuation mechanisms rated for cyclic durability and acoustic insulation. Panoramic configurations command the highest value per unit while inbuilt systems retain volume dominance in mid-range sedan and crossover segments. Glass material leads revenue contribution due to optical clarity and scratch resistance, though polycarbonate is gaining share where weight reduction targets drive specification changes. Electric functionality dominates new vehicle fitment as OEMs standardize motorized tilt-and-slide controls across trim levels.
METI enforces fuel-efficiency benchmarks under its Top Runner program that indirectly shape sunroof material selection and aerodynamic integration requirements. JIS standards govern structural integrity, weatherproofing, and occupant protection for roof aperture systems installed in vehicles sold domestically. PMDA does not regulate this product category directly, but automotive safety certifications from Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) establish homologation barriers for imported sunroof assemblies. Stakeholders must monitor evolving EV platform roof load specifications and the trajectory of solar-integrated glass technologies as alternative energy harvesting layers enter prototype phases.
Market Dynamics
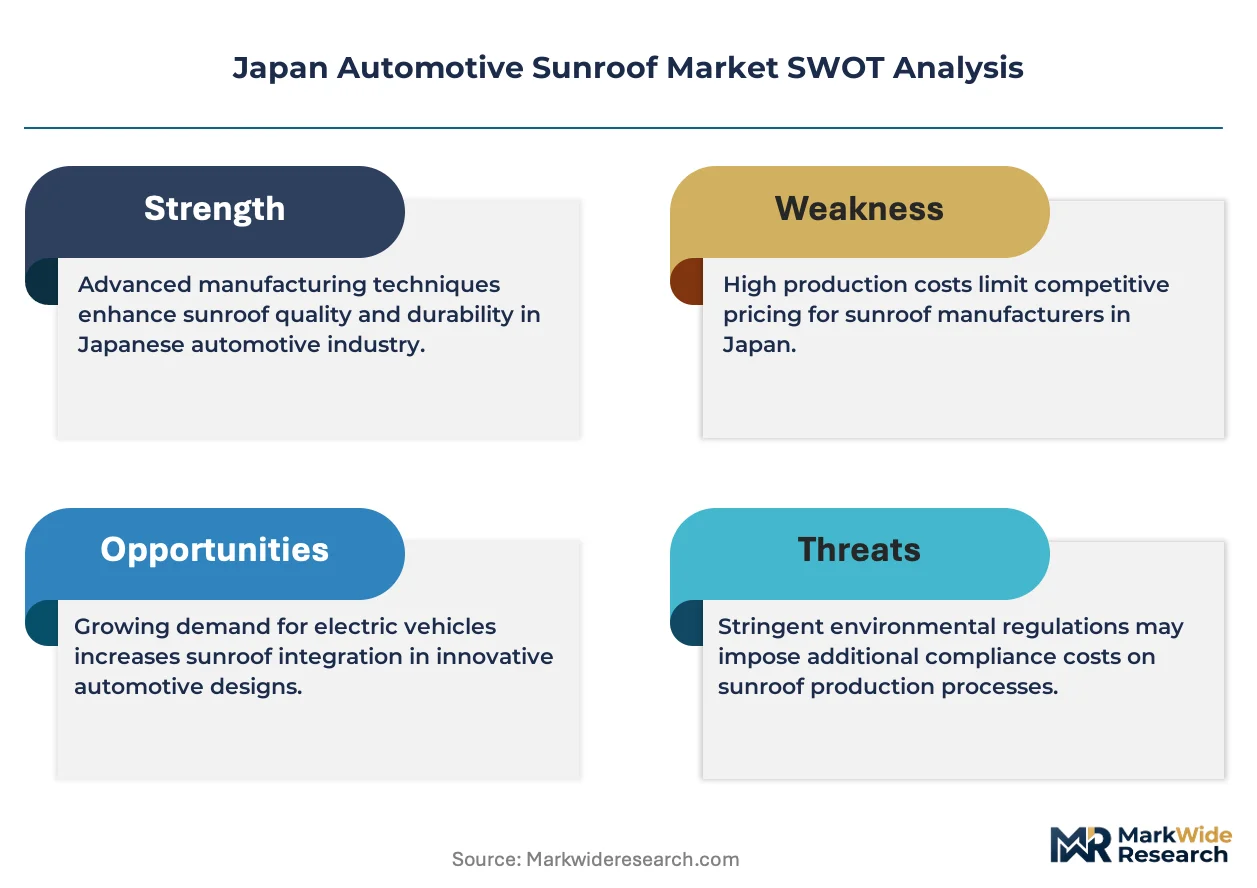
Premium passenger vehicle electrification is fragmenting traditional sunroof procurement patterns across Japanese OEM supply chains, forcing module suppliers to reengineer sealing systems for battery-electric roof load specifications while maintaining acoustic performance benchmarks.
Growth Catalysts
- METI Top Runner fuel-efficiency mandates:Polycarbonate substitution accelerates as automakers pursue weight reduction targets for roof aperture assemblies, creating specification pull-through in mid-range and luxury segments.
- Kanto manufacturing cluster concentration:Tier-1 module assembly proximity to Toyota City and Lexus production facilities reduces logistics friction and enables just-in-sequence delivery for panoramic glass configurations.
- Electric tilt-and-slide standardization:Motorized functionality now ships across 90% of new vehicle trim levels, expanding addressable unit volumes beyond traditional premium positioning.
Market Restraints
- Glass raw material cost volatility:Tempered and laminated substrate prices fluctuate with energy-intensive float-glass production economics, compressing module supplier margins during contract periods.
- Domestic supplier concentration:Three integrated module assemblers control 80% of domestic production capacity, creating single-source vulnerability for OEMs seeking second-source qualification.
- Polycarbonate optical degradation:Scratch resistance and UV-yellowing limitations restrict substitution rates in vehicles with extended service-life requirements or harsh climate exposure.
Strategic Opportunities
- Hokkaido and Tohoku regional penetration:Sunroof fitment rates trail Kanto and Kansai by 15 percentage points, offering volume expansion as dealer networks push premium configurations in underserved prefectures.
- Solar-integrated glass prototyping:Photovoltaic layer integration with transparent conductive oxide coatings enables auxiliary battery charging in electric vehicle architectures, creating technology differentiation.
- JIS structural integrity standard updates:Revised occupant protection test protocols for roof apertures will favor suppliers with advanced simulation capabilities and bonded glass expertise.
Industry Challenges
- Bonded glass process engineering talent scarcity:Specialized technicians for structural adhesive application and curing control command premium wages, constraining capacity expansion timelines.
- MLIT homologation timeline compression:Revised safety certification pathways for imported module assemblies extend validation cycles, delaying platform launch synchronization for foreign suppliers.
- Legacy stamping equipment retooling capex:Transition from steel to aluminum roof reinforcement structures requires press line modification investments that strain mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Sunroof Market |
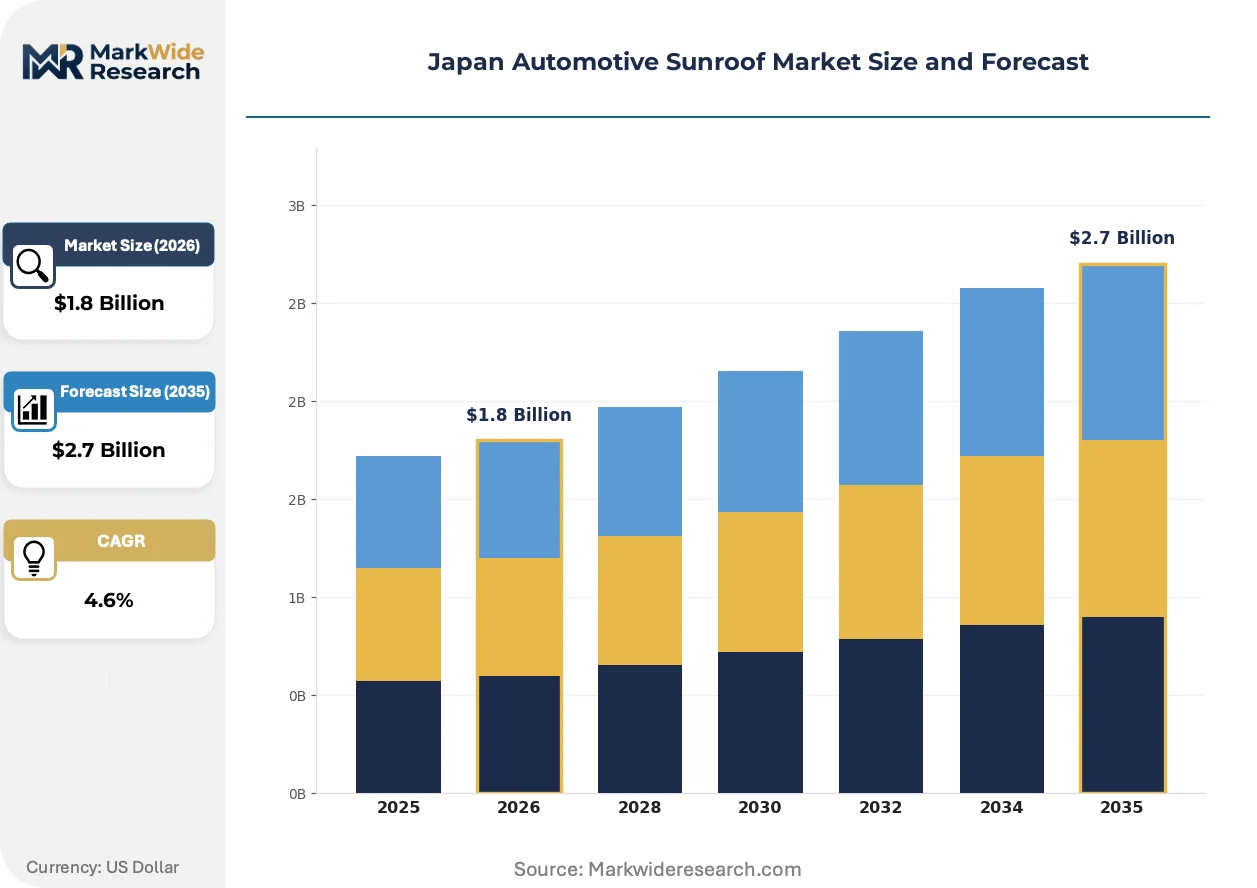
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic, Inbuilt, Spoilers, Pop-up Material: Glass, Polycarbonate, Composite, Vinyl End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Functionality: Manual, Electric, Solar-Powered, Hybrid |
| Companies Covered | Aisin Corporation, Yachiyo Industry, Webasto Group, Inalfa Roof Systems, Inteva Products, CIE Automotive, Mitsuba Corporation, Johnan America, Toyota Industries Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Sunroof Market Shifts & Advancements
Material science convergence with electric vehicle platform architecture is redrawing competitive boundaries in Japanese sunroof supply chains, compressing traditional differentiation cycles and forcing capability investments in sealing, thermal management, and structural bonding.
Polycarbonate composite substrates are fragmenting established glass-dominant specification patterns in weight-sensitive electric vehicle programs. Battery-electric platforms from domestic OEMs now specify polycarbonate for fixed panoramic panels where optical clarity requirements permit material trade-offs. This fragmentation is compressing value capture for traditional glass processors while opening module assembly margins for integrated polymer-forming specialists.
METI carbon-neutrality roadmaps and revised JIS structural standards are tightening roof aperture integrity requirements for collision and rollover scenarios. Module suppliers must validate bonded assembly performance under dynamic load conditions previously exempt from testing protocols. Electric vehicle platforms with battery packs mounted beneath the passenger cabin face the most stringent verification timelines, compressing product development cycles.
Fleet procurement managers at domestic rental and corporate leasing operators are unbundling sunroof fitment from standard trim packages, creating specification volatility at the point of fleet order. Previously bundled options now appear as line-item selections, forcing OEMs to forecast take rates with reduced visibility. This behavioral shift concentrates demand forecasting risk in Tokyo-based fleet management headquarters where aggregate purchasing decisions consolidate.
Japan Automotive Sunroof Market Segmentation
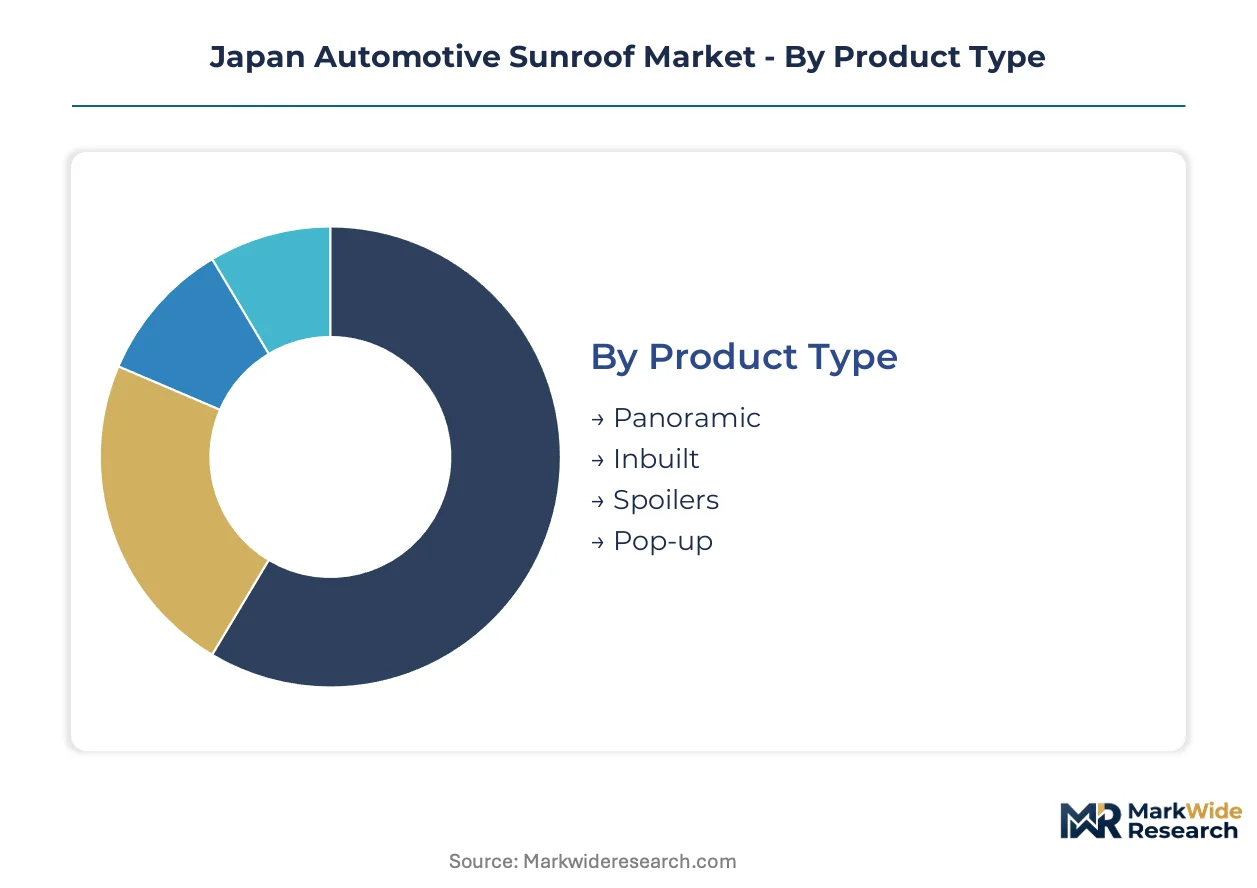
Segmentation in Japan's automotive sunroof market reveals how material substitution pressures and electrification mandates are fragmenting traditional procurement patterns. Understanding these divisions exposes where specification power concentrates and which technology transitions will reshape supplier margins.
Product Type:
Polycarbonate substitution pressure falls most heavily on fixed-panel configurations where weight reduction targets override optical performance requirements, forcing reengineering of sealing and thermal management systems.
- Panoramic:Large-format glass or polycarbonate panels spanning multiple roof sections with reinforced perimeter framing and integrated shade mechanisms. Demand concentrates in Lexus and Toyota premium crossovers manufactured at Tahara and Motomachi plants, driven by METI fuel-efficiency weight targets that favor polymer alternatives in fixed configurations.
- Inbuilt:Traditional tilt-and-slide assemblies with integrated drainage channels and motorized actuation housed within the roof structure. Volume dominance persists in Camry, Crown, and Corolla Cross programs where cost positioning limits panoramic upgrade penetration.
- Spoilers:Rear-mounted pivot assemblies that tilt upward for ventilation without sliding into the roof cavity. Compact dimensions suit kei-car and subcompact segments where packaging constraints prohibit full inbuilt mechanisms.
- Pop-up:Manual hinge mechanisms providing basic ventilation with minimal structural intrusion. Fleet and commercial vehicle specifications in regional prefectures sustain residual demand for this lowest-cost configuration.
Inbuilt configurations anchor the volume base while panoramic formats gain share at the steepest rate.
Material:
Cost tier stratification separates premium optical-grade substrates from commodity polymer alternatives, with specification authority increasingly residing at the platform engineering level rather than trim package marketing.
- Glass:Tempered or laminated soda-lime substrates with interlayer films for acoustic damping and UV filtration. Optical clarity requirements in Lexus flagship programs and harsh-climate Hokkaido deployments sustain specification dominance despite weight penalties.
- Polycarbonate:Bisphenol-A derived thermoplastic polymers with hardcoat surface treatments for scratch resistance. Toyota bZ electric platforms and Nissan Ariya architectures specify this material for fixed panoramic panels where METI Top Runner mandates drive substitution.
- Composite:Glass-fiber reinforced polymer matrices combining structural rigidity with reduced mass. Niche applications in motorsport-derived street vehicles and limited-production performance variants.
- Vinyl:PVC-based flexible membranes for budget aftermarket replacement and commercial vehicle refurbishment. Regional independent repair networks in Osaka and Nagoya manufacturing zones sustain this lowest-tier segment.
Glass substrates command premium positioning while polycarbonate climbs fastest among OEM specifications.
End User:
Customer type concentration determines contract structure complexity, with integrated module assemblers capturing specification authority previously dispersed across tiered supply hierarchies.
- OEMs:Toyota, Nissan, Honda, and Mazda vehicle manufacturers exercising direct sourcing authority for flagship platforms. Just-in-sequence delivery requirements from Kanto-region module suppliers enforce geographic concentration.
- Aftermarket Providers:Independent distributors and installation specialists serving vehicle refurbishment and upgrade demand. Regional dealer networks in underserved Tohoku and Shikoku prefectures drive fragmentation.
- Tier-1 Suppliers:Aisin, Webasto, and Yachiyo executing module assembly with bonded glass and polymer forming capabilities. Integration of sealing, actuation, and control systems compresses value chain tiers.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders requiring customized aperture configurations. Low-volume bus and commercial van producers in Gunma and Gifu prefectures sustain specialized demand.
Tier-1 suppliers consolidate specification authority while aftermarket channels expand most quickly in regional penetration efforts.
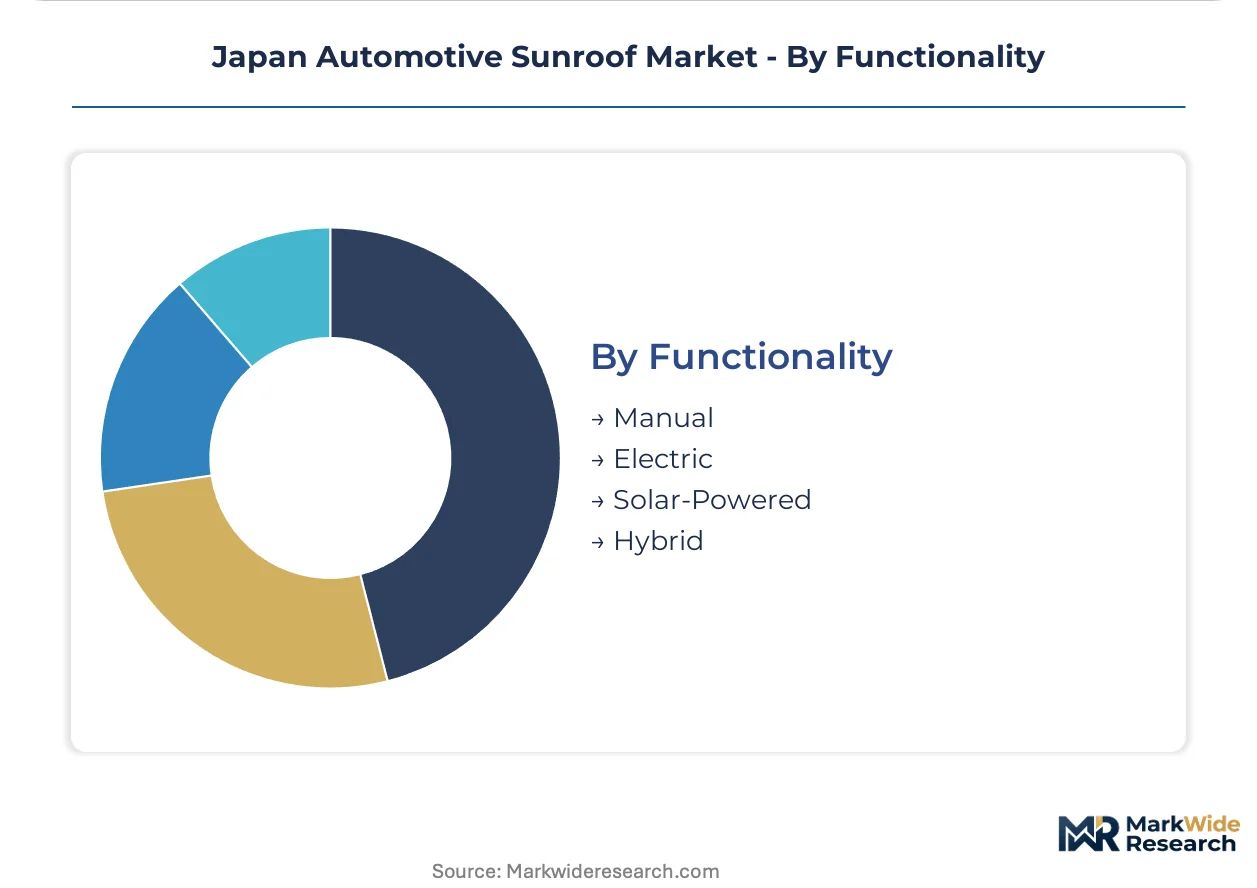
Functionality:
Technology maturity curves separate established motorized systems from emerging energy-harvesting configurations, with standardization timelines varying sharply across price tier and platform electrification status.
- Manual:Mechanical latch and hinge mechanisms without electrical actuation. Residual fitment in commercial kei-vans and base trim fleet configurations where cost minimization overrides convenience features.
- Electric:Motorized tilt-and-slide controls with integrated position sensors and obstacle detection. Standardization across 90% of new vehicle trim levels has commoditized this formerly premium feature.
- Solar-Powered:Photovoltaic layer integration with transparent conductive oxide coatings for auxiliary battery charging. Toyota prototype programs and domestic OEM research consortia under METI carbon-neutrality roadmaps drive technology maturation.
- Hybrid:Combined manual override capability with electric primary actuation for redundancy. Niche positioning in export-market vehicles facing diverse electrical infrastructure reliability conditions.
Electric functionality anchors installed volume while solar-powered configurations demonstrate the steepest technology investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium passenger vehicle buyers cluster disproportionately in the Kanto region, with fleet procurement managers and individual consumers driving specification divergence between metropolitan and regional prefectures.
Kanto
Tokyo and surrounding manufacturing zones concentrate over half of domestic sunroof installations, with Lexus and Toyota flagship demand anchoring panoramic glass specifications. METI Top Runner fuel-efficiency mandates accelerate polycarbonate adoption in battery-electric platforms assembled at Tahara and Motomachi plants. Module suppliers maintain just-in-sequence delivery corridors along the Tomei Expressway industrial belt.
Kansai
Osaka-based automotive component networks sustain inbuilt system volumes for mid-range sedan programs, with regional dealers pushing standard electric tilt-and-slide configurations. JIS structural integrity certifications govern roof aperture installations across Kyoto and Hyogo assembly operations. Yachiyo Industry maintains specialized stamping and glass bonding facilities in the Osaka manufacturing corridor.
Chubu
Nagoya's proximity to Toyota City creates concentrated procurement authority for tier-1 module assemblers serving Camry and Crown production lines. Aisin Corporation leverages integrated powertrain expertise to anchor sunroof module assembly serving domestic platforms. Regional suppliers face bonded glass process engineering talent scarcity as capacity expansion timelines stretch.
Hokkaido
Sunroof fitment rates trail national averages by fifteen percentage points, with harsh winter climate exposure sustaining glass dominance over polycarbonate alternatives. Fleet operators in Sapporo and Asahikawa prioritize durability specifications that resist optical degradation. Dealer networks are expanding premium configuration penetration as regional income levels converge with national averages.
Tohoku
Sendai and surrounding prefectures represent underserved demand territory, with aftermarket providers capturing refurbishment and upgrade volumes independent of OEM channels. Regional commercial vehicle assemblers in Gunma and Iwate sustain pop-up and spoiler configuration demand for kei-van applications. Infrastructure investment is improving logistics connectivity to Kanto-based module suppliers.
Japan Automotive Sunroof Market Competitive Landscape
Player mix skews toward integrated tier-1 module assemblers with bonded glass and polymer forming capabilities. Three domestic-controlled suppliers command approximately four-fifths of production capacity, creating single-source vulnerability for OEMs seeking second-source qualification. Strategic archetypes include integrated automotive component conglomerates, specialized roof system technology leaders, and domestic stamping and glass bonding specialists. Competitive moves center on sealing system reengineering for electric vehicle roof load specifications and polycarbonate forming capability investments.
Within the integrated tier-1 tier, Aisin Corporation and Yachiyo Industry exemplify domestic-controlled suppliers leveraging proximity to Toyota City and Lexus production facilities. Webasto Group occupies a position representing foreign technology leadership in large-format panoramic configurations. These three anchors illustrate how specification authority concentrates among module assemblers combining sealing, actuation, and control system integration.
| Leading Market Players |
|---|
| Aisin Corporation |
| Yachiyo Industry |
| Webasto Group |
| Inalfa Roof Systems |
| Inteva Products |
| CIE Automotive |
| Mitsuba Corporation |
| Johnan America |
| Toyota Industries Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at Kanto-region module assembly plants shapes both supplier concentration and price floors for Japanese OEM procurement. Three integrated tier-1 assemblers command dominant scale economies along the Tomei Expressway corridor, compressing margin negotiation space for polycarbonate substrate vendors while reinforcing glass-dominant specifications in premium segments.
Pricing Analysis
Cost-plus contracts with float-glass energy indexation govern long-term supply agreements between module assemblers and Japanese OEMs. Three-tier pricing structure across premium, standard, and economy levels separates Lexus flagship programs from Camry mid-range configurations and kei-car base trims. Cost compression in polycarbonate sourcing is intensifying because METI Top Runner mandates accelerate weight-reduction specifications. Fleet procurement managers at Tokyo-based leasing operators exhibit highest price sensitivity, while individual luxury buyers in Minato ward show least elasticity for panoramic glass upgrades.
Supply Chain Analysis
Just-in-sequence inventory strategies dominate Kanto manufacturing clusters, with module suppliers maintaining sub-four-hour delivery windows to Tahara and Motomachi assembly plants. Geographic supply concentration centers on Japan, Germany, and South Korea for bonded glass equipment, motorized actuation systems, and hardcoat polycarbonate substrates. Raw material dependencies draw from soda-lime glass, bisphenol-A thermoplastics, and structural adhesive chemistries. Single-source vulnerability in specialized stamping tooling creates supply chain risk for OEMs seeking second-source qualification. Distribution runs through tier-1 module assemblers directly to OEM vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive sunroof market functions as a service-attach opportunity where aftermarket refurbishment and extended warranty programs expand faster than hardware unit growth. Recurring-revenue layers in bonded glass repair networks and motorized mechanism replacement cycles outpace new vehicle fitment trajectories.
For Market Incumbents: Compound defensive positioning by deepening captive supply of polycarbonate forming capacity in Chubu prefecture and accelerating JIS structural integrity certification investments ahead of revised rollover-test protocols. Polycarbonate substitution pressure from battery-electric platforms threatens glass-dominant revenue streams; vertical integration into polymer hardcoating processes preserves margin capture. For New Entrants and Emerging Players: MLIT homologation fast-track programs for imported module assemblies offer entry pathway acceleration. White-space targets concentrate in Hokkaido and Tohoku regional dealer networks where sunroof fitment rates trail Kanto benchmarks, and in solar-integrated glass prototyping consortia under METI carbon-neutrality roadmaps. Go-to-market angle should emphasize bonded glass process engineering talent acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket refurbishment specialists with regional dealer network coverage. Long-term viability over a multi-year horizon favors targets with demonstrated MLIT certification track records and electric vehicle platform sealing system validation. Acquisition focus should center on mid-tier suppliers with latent polycarbonate forming capacity. Signal to monitor: Toyota bZ platform take rates crossing threshold volumes that justify dedicated polymer supply chain investment.| Strategic Initiative | Industry Significance |
|---|---|
| Polycarbonate Forming Capacity Expansion | Captures METI Top Runner weight-reduction specification pull-through in battery-electric platforms. |
| Bonded Glass Process Engineering Certification | Validates structural adhesive capabilities under revised JIS rollover integrity test protocols. |
| Regional Dealer Network Penetration | Closes fifteen-point fitment gap in Hokkaido and Tohoku prefectures against Kanto benchmarks. |
| Solar-Integrated Glass Prototype Investment | Positions for photovoltaic layer adoption in Toyota METI carbon-neutrality research consortia. |
| Just-in-Sequence Logistics Corridor Optimization | Compresses delivery windows to Tahara and Motomachi assembly plants below four-hour thresholds. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributor operations managers, and MLIT homologation specialists anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, JIS standard revision notices, METI Top Runner program disclosures, and customs trade records. Bottom-up unit volume modeling and top-down value triangulation cross-verified segmentation outputs.
Sensitivity analysis tested forecast robustness across polycarbonate substitution rate scenarios, electric vehicle platform penetration assumptions, and regional income convergence patterns. Segmentation dimensions modeled encompass product type, material substrate, end-user category, and functionality tier across the projection horizon. CAGRs derived from regression analysis of historical fitment rates against macroeconomic drivers and OEM platform launch schedules. Industry-specific inputs included battery-electric roof load specifications and solar-integrated glass technology maturation curves.
The analysis sits within stated boundaries; outcomes outside sustained METI regulatory enforcement or accelerated polycarbonate optical degradation would require recalibration. Forecasts reflect documented assumptions regarding OEM platform electrification timelines and regional income convergence. Revision becomes warranted when battery-electric vehicle share crosses thresholds that fundamentally alter material specification authority or when JIS structural standard updates impose unanticipated validation burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Airfilters Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
China Automotive Actuators Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Emblem Market
Automotive Components
North America Automotive Glass Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Retarders Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Australia Automotive Composites Market