
 Traction Control System Market | 2026-2036
Traction Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Control System Market Analysis
A shift from single-source to multi-source sensor procurement is recalibrating cost structures across the supply base. Robert Bosch GmbH leverages its in-house semiconductor fabrication to control chip supply for traction control modules. Continental AG anchors European OEM relationships through integrated braking-stability platforms. ZF Friedrichshafen AG competes on torque vectoring specialization for electrified axle systems.
A traction control system comprises wheel-speed sensors, a control module, and actuation hardware that modulates brake pressure or engine torque to prevent wheel slip during acceleration. The system typically operates within milliseconds, using pulse-width modulation to manage friction limits across variable road surfaces. Active Traction Control and Torque Vectoring command premium positioning as EV architectures demand precise torque distribution. Mechanical Limited Slip retains share in heavy machinery and budget commercial segments where electronic complexity adds unacceptable cost. OEM deployment dominates volume, though aftermarket retrofitting grows in regions with aging vehicle fleets and tightening inspection standards.
The National Highway Traffic Safety Administration enforces electronic stability control mandates for light vehicles sold in the United States, directly embedding traction control functionality in federal safety requirements. The European Union's General Safety Regulation mandates intelligent speed assistance and lane-keeping systems, expanding the sensor and control module base from which traction systems draw. Stakeholders must monitor how software-defined vehicle architectures reshape hardware-software boundaries in stability system procurement.
Market Dynamics
Electrification of vehicle platforms is forcing a fundamental redesign of traction control architectures, as battery-electric drivetrains require distributed torque management rather than centralized engine-brake modulation.
Growth Catalysts
- EU Green Deal mandates:The European Union's vehicle certification framework now embeds advanced stability requirements, compelling OEMs to spec higher-grade control modules across production lines.
- Electric axle proliferation:Battery-electric platforms in Germany, Japan, and the United States demand precise wheel-slip algorithms that legacy mechanical systems cannot deliver.
- Sensor fusion advancement:LiDAR and radar integration with wheel-speed data is enabling predictive traction intervention before slip occurs.
Market Restraints
- Semiconductor supply concentration:Control module fabrication depends on concentrated Asian foundry capacity, exposing procurement to single-point disruption risks.
- Copper and rare-earth magnet costs:Actuation hardware and motor components face input price volatility that compresses module margins.
- Mechanical substitution persistence:Heavy machinery and budget commercial segments in emerging markets continue specifying limited-slip differentials over electronic systems.
Strategic Opportunities
- Aftermarket retrofit channels:Aging vehicle fleets in India and Brazil face tightening inspection standards, creating demand for upgrade kits.
- Software-defined vehicle convergence:Over-the-air update capability allows traction algorithm refinement post-sale, opening recurring revenue streams.
- India's PLI scheme for auto components:Localized module production incentives are drawing supplier investment toward domestic OEM supply.
Industry Challenges
- Embedded systems engineering talent scarcity:Real-time control firmware development requires specialized skill sets concentrated in Stuttgart, Detroit, and Nagoya.
- ISO 26262 functional safety certification:ASIL-D qualification timelines for new control modules extend 18-24 months, delaying product launches.
- Legacy CAN bus integration friction:New torque vectoring systems must interoperate with decades-old vehicle communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Control System Market |
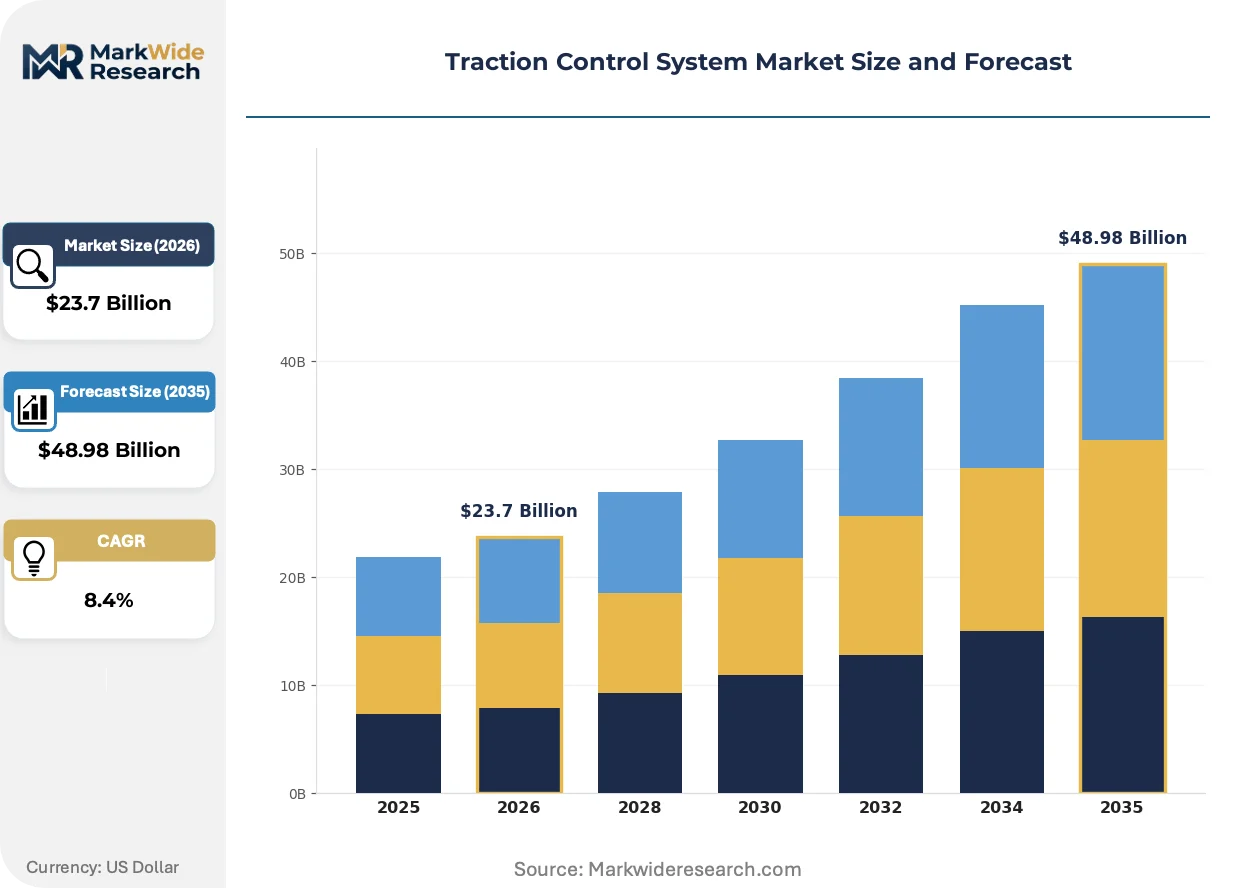
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Traction Control, Electronic Differential Lock, Mechanical Limited Slip, Traction Control Module Technology: ABS Integration, Torque Vectoring, Predictive Control, Adaptive Control End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Deployment: OEM, Aftermarket, Retrofitting, Custom Builds |
| Companies Covered | Denso Corporation, Knorr-Bremse AG, Robert Bosch GmbH, BorgWarner Inc., Hitachi Astemo Ltd., Continental AG, Autoliv Inc., Infineon Technologies AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Control System Market Emerging Trajectories
Control architectures are migrating from discrete hardware modules to software-defined functions, compressing the traditional supplier-OEM boundary in stability system procurement.
Model-predictive control algorithms are absorbing the core traction management function previously executed by dedicated electronic control units. Tier-1 suppliers in Germany and Japan are deploying these algorithms as virtualized functions on domain controllers. This consolidation is absorbing standalone module volume while expanding software licensing value pools.
The EPA's tailpipe standards and NHTSA stability mandates are embedding traction control deeper into federal safety compliance. Light vehicle manufacturers must certify integrated braking-stability platforms as single systems rather than separable components. California's Air Resources Board is extending these requirements to medium-duty commercial vehicles, forcing platform redesigns.
Fleet operators are consolidating procurement around integrated chassis-electronics packages rather than discrete stability modules. Large commercial buyers in North America and Europe now specify torque vectoring as part of bundled axle contracts. This bundling is visible most acutely in long-haul trucking, where total cost of ownership calculations favor single-source chassis integration over multi-vendor assembly.
Traction Control System Market Segmentation
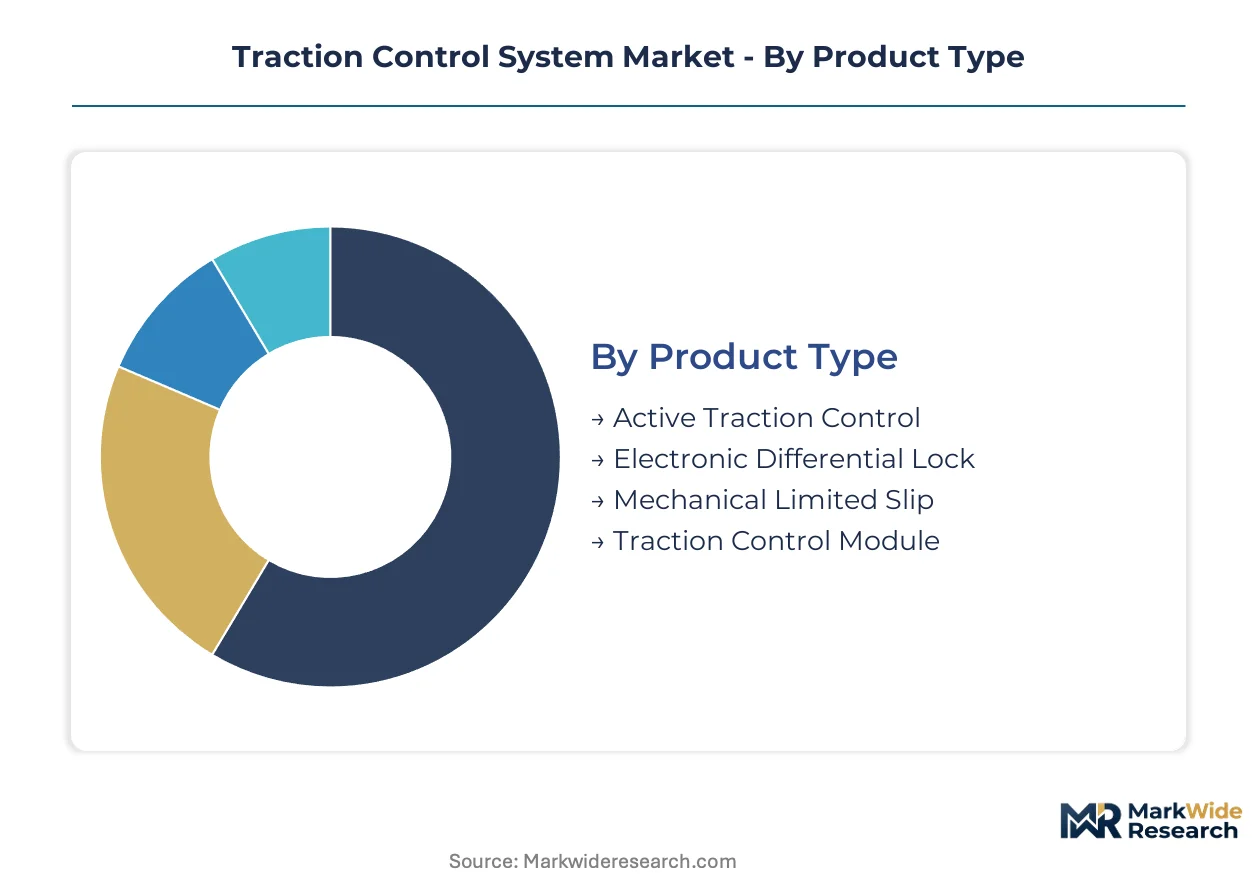
Traction control architectures fragment across electrification maturity, cost thresholds, and regulatory compliance tiers. OEM procurement patterns diverge sharply between legacy internal combustion platforms and battery-electric drivetrains requiring distributed torque management.
Product Type:
Volume deployment clusters in brake-based modulation systems while premium positioning concentrates in axle-integrated torque distribution.
- Active Traction Control:Pulse-width modulation manages brake pressure and engine torque through wheel-speed sensor feedback. Demand concentrates in Germany and Japan where NHTSA and EU Green Deal mandates enforce stability system certification across light vehicle production lines.
- Torque Vectoring:Dual-motor electric axles enable precise left-right torque split independent of brake intervention. Battery-electric platforms in the United States and Germany specify this architecture for performance differentiation and regenerative braking optimization.
- Electronic Differential Lock:Brake-based simulated locking for part-time all-wheel-drive systems.
- Mechanical Limited Slip:Clutch-pack or gear-based differentials for heavy machinery and budget commercial segments where electronic complexity adds unacceptable cost.
- Traction Control Module:Standalone control units processing sensor inputs for legacy vehicle architectures.
Mature deployment sits with Mechanical Limited Slip. Newer deployment is concentrated in Torque Vectoring.
Technology:
Algorithm sophistication separates predictive intervention from reactive slip correction, with sensor fusion commanding premium module pricing.
- ABS Integration:Shared wheel-speed sensors and hydraulic modulators between anti-lock braking and traction functions reduce per-vehicle component count. This architecture dominates high-volume passenger vehicle production in cost-sensitive segments.
- Predictive Control:LiDAR and radar data fused with wheel-speed telemetry enables torque intervention before slip detection. German and Japanese OEMs deploy this for premium electric SUVs where range optimization demands minimal tire scrub.
- Torque Vectoring:Dual-motor axle control distributing torque across wheels independent of brake application.
- Adaptive Control:Machine learning algorithms adjusting friction limit estimates based on surface condition history.
Cost leadership clusters around ABS Integration. Predictive Control is gaining share fastest among electrified platforms.
End User:
Vehicle mass and duty cycle dictate hardware specification, with commercial applications tolerating slower response times in exchange for durability.
- Passenger Vehicles:Federally mandated electronic stability control in the United States and EU General Safety Regulation requirements embed traction functionality as baseline equipment. Light vehicle OEMs specify integrated braking-stability platforms rather than discrete modules.
- Commercial Vehicles:Long-haul trucking and medium-duty delivery fleets in North America specify torque vectoring as part of bundled axle contracts where total cost of ownership calculations favor single-source chassis integration.
- Two-Wheelers:Motorcycle traction systems concentrate in premium displacement segments above 500cc.
- Heavy Machinery:Construction and agricultural equipment in emerging markets continues specifying mechanical limited-slip differentials over electronic systems due to field serviceability requirements.
Regulatory deployment sits with Passenger Vehicles. Fleet-driven deployment is expanding most quickly in Commercial Vehicles.
Deployment:
Channel structure separates factory-integrated volume from post-sale upgrade opportunities in aging fleet markets.
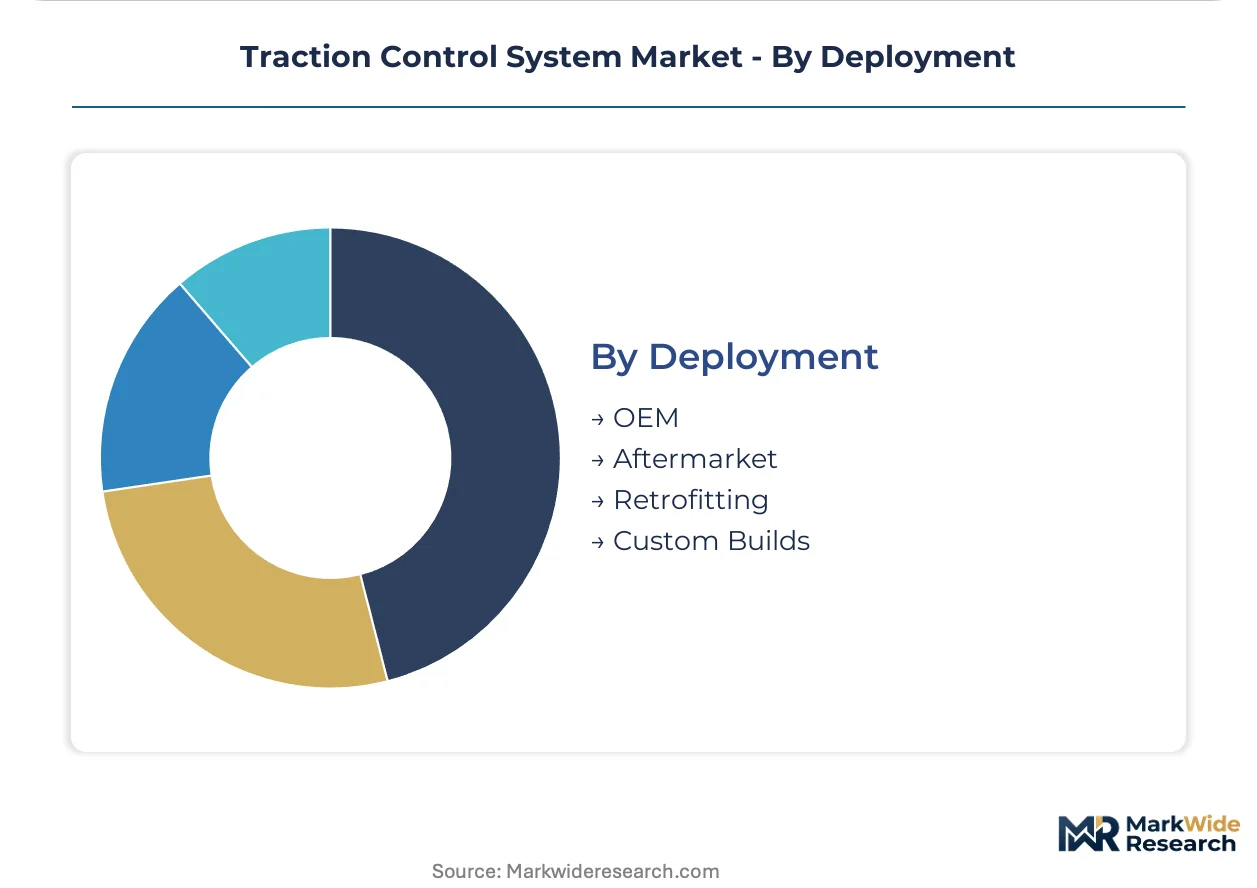
- OEM:Factory installation dominates volume with module procurement locked at platform design phase. German suppliers anchor production around Stuttgart and Wolfsburg assembly corridors.
- Aftermarket:Retrofit kits for aging vehicle fleets in India and Brazil face tightening inspection standards creating upgrade demand. Distribution runs through specialized chassis shops rather than general repair networks.
- Retrofitting:Government-mandated stability system upgrades for in-service commercial vehicles.
- Custom Builds:Low-volume specialty vehicle and motorsport applications requiring calibration outside standard OEM parameters.
Volume concentration sits with OEM. Aftermarket represents the steepest expansion trajectory as inspection standards tighten in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing in China and precision sensor fabrication in Germany anchor the geographic footprint for traction control system supply chains. Battery-grade copper and semiconductor-grade silicon concentrate procurement decisions in these localities. Regulatory mandates in the United States, European Union, and Japan then determine where module assembly finalizes.
United States
NHTSA electronic stability control mandates and EPA tailpipe standards drive OEM specification of integrated braking-stability platforms across light vehicle production. California's Air Resources Board extends these requirements to medium-duty commercial vehicles, forcing platform redesigns. Detroit anchors supplier engineering concentration for torque vectoring algorithms serving electric pickup and SUV programs.
Germany
EU Green Deal vehicle certification frameworks embed advanced stability requirements compelling higher-grade control module specification. Stuttgart and Wolfsburg assembly corridors concentrate Bosch, Continental, and ZF Friedrichshafen production ecosystems. KBA type-approval processes enforce ISO 26262 functional safety certification timelines that extend 18-24 months for new module launches.
Japan
METI carbon-neutrality roadmaps accelerate electrification timelines requiring precise wheel-slip management for dual-motor axle architectures. Nagoya and Tokyo metropolitan areas concentrate Hitachi Astemo and Denso engineering talent for real-time control firmware development. JIS standards interoperability requirements shape legacy CAN bus integration specifications for export markets.
China
MIIT new energy vehicle mandates and dual carbon goals expand procurement of torque vectoring modules for domestic battery-electric platforms. Yangtze River Delta manufacturing clusters concentrate rare-earth magnet processing for actuation hardware. GB standards for intelligent connected vehicles reshape sensor fusion architectures integrating LiDAR with wheel-speed telemetry.
India
PLI scheme incentives for auto components draw supplier investment toward localized module production for domestic OEM supply. Maharashtra and Gujarat industrial corridors concentrate aftermarket retrofit kit distribution for aging commercial vehicle fleets. BIS certification tightening for vehicle inspection standards creates upgrade demand in specialized chassis shops.
Traction Control System Market Vendor Landscape
Strategic partnerships dominate the current landscape as tier-1 suppliers align with domain controller manufacturers to virtualize traction functions. The vendor base concentrates around three archetypes: diversified automotive electronics conglomerates with in-house semiconductor fabrication, specialized chassis-system integrators bundling axle and stability electronics, and semiconductor firms supplying control chips to module assemblers. M&A activity and technology licensing agreements represent the primary competitive moves as software-defined vehicle architectures compress hardware boundaries.
Within the diversified electronics tier, Robert Bosch GmbH and Continental AG exemplify integrated platform strategies spanning sensor fabrication through module assembly. Among chassis-specialist positions, ZF Friedrichshafen AG occupies a torque vectoring focus for electrified axle systems. These three German entities anchor European OEM relationships while competing on distinct vectors of vertical integration depth and software licensing scope.
| Leading Market Players |
|---|
| Denso Corporation |
| Knorr-Bremse AG |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Hitachi Astemo Ltd. |
| Continental AG |
| Autoliv Inc. |
| Infineon Technologies AG |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal vehicle certification framework gates qualified supply access and premium-tier pricing power, as OEMs must source ASIL-D certified modules from suppliers with proven ISO 26262 track records. Battery-electric platform proliferation concentrates procurement among German and Japanese tier-1s who bundle torque vectoring with axle contracts, compressing standalone module margins while elevating software licensing value.
Pricing Analysis
Warranty and calibration service bundling separates premium module suppliers from unbundled commodity assemblers, with integrated braking-stability platforms commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ASIL certification grade and volume scale, with fleet buyers negotiating axle-electronics packages that absorb per-unit module costs. Pricing pressure stems from semiconductor foundry concentration in Taiwan and South Korea, which exposes procurement to input volatility. Budget commercial segments in India and Brazil exhibit highest price sensitivity, while German OEMs prioritize certification reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for traction control modules remain underdeveloped, with refurbishment channels concentrated in European aftermarket networks handling warranty returns from Stuttgart and Wolfsburg assembly corridors. Geographic supply concentration centers on Germany, Japan, and China, where Bosch, Denso, and domestic suppliers anchor module fabrication. Raw material dependencies include rare-earth magnets for actuation hardware, copper for motor windings, and semiconductor-grade silicon for control chips. Single-source vulnerability in Asian foundry capacity represents the dominant structural risk. Distribution runs through OEM platform engineering teams at vehicle design phase, with aftermarket retrofit kits flowing through specialized chassis shops in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around software-defined vehicle architectures that favor suppliers with domain controller partnerships and in-house semiconductor fabrication, forcing module assemblers without chip supply control toward acquisition or exit.
For Market Incumbents: Cement control over torque vectoring algorithm licensing by deepening backward integration into semiconductor fabrication, mirroring Bosch's captive chip supply strategy. Acquire specialized firmware engineering teams in Stuttgart, Detroit, or Nagoya to defend against talent scarcity threatening real-time control development timelines. Prioritize ASIL-D certification pipeline expansion to capture platform design-phase procurement locked 18-24 months ahead of production.
For New Entrants and Emerging Players: The price-point gap between premium German-Japanese torque vectoring systems and economy brake-based modulation creates white-space opportunity in India's PLI-subsidized component manufacturing and Brazil's aftermarket retrofit channels. Target aging commercial vehicle fleets facing tightening BIS inspection standards with upgrade kits distributed through specialized chassis shops rather than general repair networks. Pursue software licensing partnerships with domain controller manufacturers to bypass standalone module fabrication barriers.
For Investors and Strategic Acquirers: MIIT new energy vehicle mandate acceleration is the leading indicator that Chinese domestic OEM procurement of torque vectoring modules will consolidate around suppliers with Yangtze River Delta manufacturing footprints. Over a 5-10 year horizon, vertically integrated chassis-electronics specialists with rare-earth magnet processing capabilities present superior acquisition targets versus standalone module assemblers. Monitor EPA tailpipe standard extensions to medium-duty commercial vehicles as the signal for North American platform redesign cycles that reopen supplier qualification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Virtualized traction functions on domain controllers absorb standalone module volume while expanding recurring software licensing revenue pools. |
| Battery Supply Agreement | Dual-motor electric axle architectures demand precise torque distribution partnerships with cell manufacturers optimizing regenerative braking recovery. |
| Geographic Manufacturing Footprint | Localized module production under India's PLI scheme secures domestic OEM supply relationships insulated from import tariff exposure. |
| Platform Standardization | Shared control module architectures across light vehicle and commercial vehicle lines compress per-unit engineering costs and accelerate ASIL-D certification leverage. |
| Charging Infrastructure Partnership | Integration of traction control data with charging network optimization enables predictive thermal management for high-performance electric drivetrains. |
Methodological Framework
Regulatory filings from NHTSA, KBA type-approval databases, and MIIT new energy vehicle certification records formed the secondary backbone for mandate trajectory validation. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and semiconductor foundry planning officers combined with secondary validation from vehicle production databases, customs trade data, and SEC component supplier disclosures. Bottom-up module shipment estimates triangulated against top-down OEM platform production forecasts.
Bottom-up modeling aggregated traction control module specifications by vehicle class, propulsion architecture, and content per vehicle across regional production clusters, while top-down analysis scaled aggregate automotive electronics spending against stability system penetration rates. CAGRs derived from regression across electrification adoption curves and regulatory mandate phase-in schedules. Forecast inputs included battery-electric platform proliferation timelines, ASIL-D certification queue lengths, and rare-earth magnet price volatility indices.
Inputs from NHTSA enforcement data and EU General Safety Regulation implementation tracking were available through the study window; gaps in real-time semiconductor foundry capacity utilization introduce uncertainty bands around module availability assumptions. Forecasts reflect documented electrification adoption scenarios and regulatory compliance deadlines. Practitioners should monitor MIIT dual carbon goal acceleration and EPA medium-duty vehicle rulemaking for early signals of platform redesign intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market