
 Automotive Backing Plate Market | 2026-2036
Automotive Backing Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Backing Plate Market Outlook
The EU Green Deal is consolidating demand for low-carbon automotive components across European brake supply chains. NUCAP leverages its friction material integration to control backing plate specifications for major OEM programs. Brembo S.p.A. anchors high-performance segments with advanced metallurgy expertise in racing and premium road applications. ZF Friedrichshafen AG extends its position through captive supply relationships with German vehicle assemblers.
An automotive backing plate is a structural mounting component, typically fabricated from stamped steel, cast aluminum, or fiber-reinforced composite, that provides rigid support for brake pads and distributes clamping force across the caliper assembly. Stamping dominates high-volume passenger car production due to cycle speed and material efficiency, while aluminum and composite variants gain share in electric vehicle platforms where unsprung mass reduction extends range. OEM demand for stamped steel plates remains the largest volume pool, though aluminum segments capture expanding margin pools as automakers redesign thermal management systems for regenerative braking architectures. Tier-1 suppliers increasingly specify machined aluminum backing plates for premium electric vehicle programs where precision tolerances reduce noise-vibration-harshness.
EPA tailpipe standards and the EU F-Gas Regulation shape material selection criteria, compelling suppliers to document lifecycle carbon intensity for aluminum and composite alternatives. NHTSA brake performance standards maintain steel's position in heavy-duty commercial applications where thermal load capacity governs specification. Stakeholders must monitor how China's MIIT dual carbon goals and evolving GB standards for new energy vehicles redirect procurement patterns toward domestic composite backing plate manufacturers.
Market Dynamics
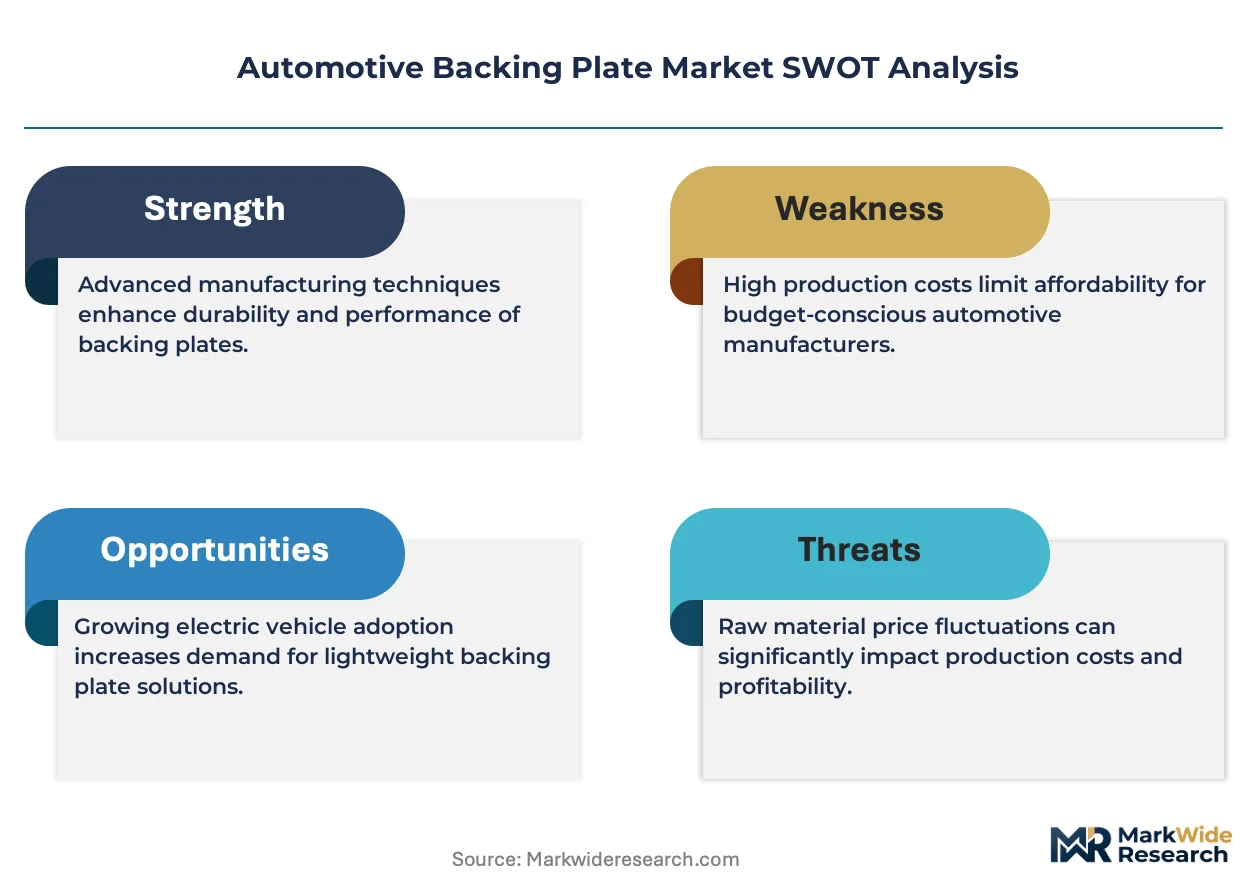
The EU Green Deal and EPA emissions standards are compressing material substitution timelines, forcing brake system suppliers to requalify aluminum and composite backing plates for mass-market vehicle platforms ahead of original equipment redesign cycles.
Growth Catalysts
- Lightweighting mandates:Germany's KBA enforcement of EU CO2 fleet targets accelerates aluminum backing plate procurement for electric vehicle brake assemblies.
- MIIT dual carbon goals:China's GB standards for new energy vehicles redirect domestic procurement toward composite backing plate manufacturers serving regional EV supply chains.
- Regenerative braking architectures:Reduced thermal loads in EV platforms enable thinner stamped aluminum designs that cut unsprung mass.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations compress margins for suppliers locked into annual OEM supply agreements.
- Steel supply concentration:German and Japanese specialty steel mills control high-strength alloy grades required for heavy-duty commercial backing plates.
- NHTSA thermal load standards:Federal brake performance requirements maintain steel specifications in commercial vehicle segments where aluminum alternatives lack certification pathways.
Strategic Opportunities
- India's PLI scheme:Automotive component incentives attract backing plate stamping investments to serve Maruti Suzuki and Tata Motors assembly networks.
- Recycled aluminum certification:EU CSRD lifecycle disclosure rules create premium positioning for suppliers documenting low-carbon aluminum sourcing.
- Additive manufacturing convergence:Topology-optimized aluminum lattice structures enable weight reduction beyond conventional stamping limits for racing applications.
Industry Challenges
- Material requalification timelines:OEM brake system validation cycles extend 18-24 months, delaying aluminum platform adoption.
- Welding automation skill gaps:Composite-to-metal hybrid backing plates require adhesive bonding expertise scarce in traditional stamping workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Backing Plate Market |
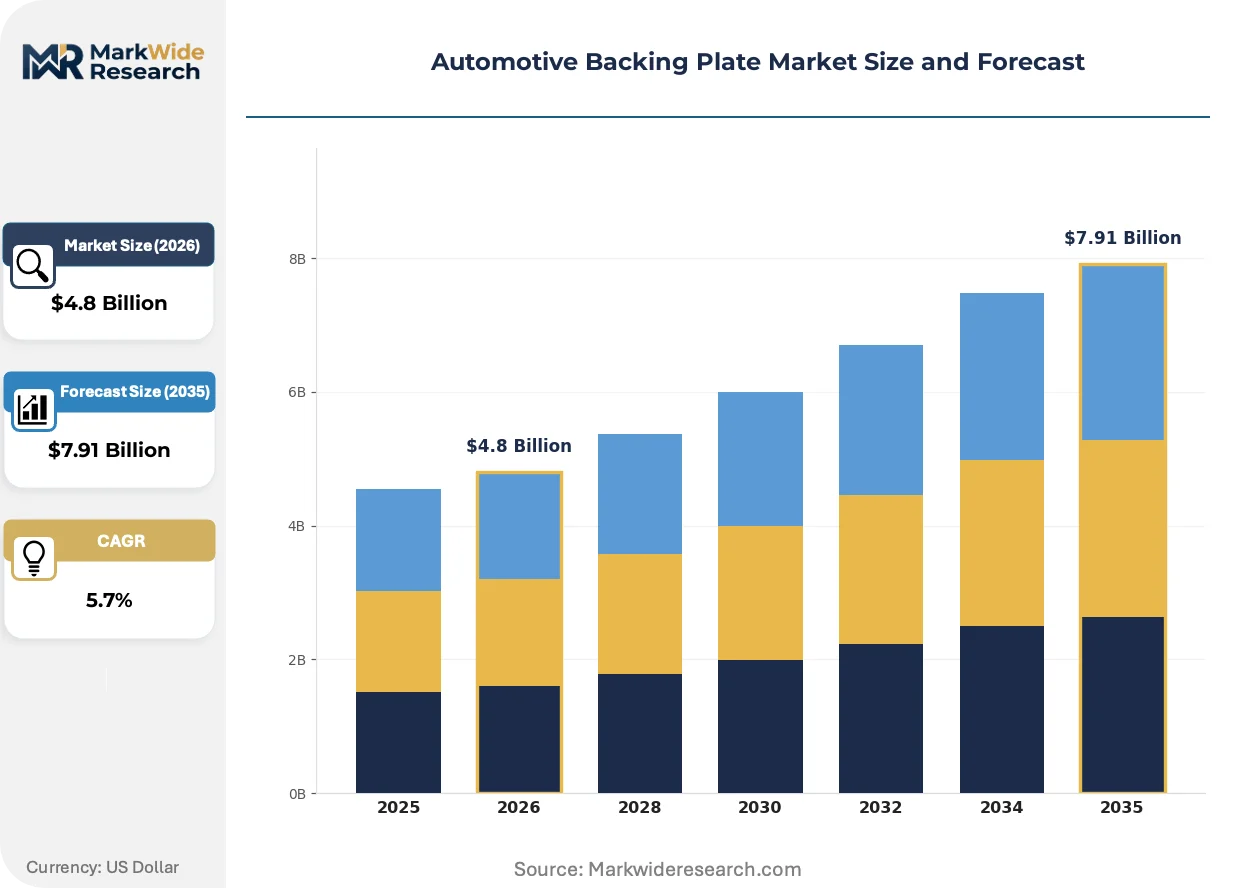
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Stamping, Casting, Machining, 3D Printing Installation: Front Mount, Rear Mount, Integrated, Removable |
| Companies Covered | NUCAP, Dorman Products, Brembo S.p.A., ORTLINGHAUS-WERKE GmbH, ZF Friedrichshafen AG, Aisin Seiki Co., Ltd., MAT Foundry Group Ltd., ACDelco, Akebono Brake Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Backing Plate Market Strategic Shifts
Material science advances and regulatory disclosure requirements are fragmenting the traditional steel-dominated specification landscape into technology-specific supply tiers.
Fiber-reinforced thermoplastic composites are expanding into passenger vehicle brake platforms where compression molding cycle times now approach steel stamping economics. Tier-1 suppliers in Germany and China are qualifying glass-fiber polyamide formulations for A-segment electric vehicles. The technology is expanding into wheel-end modules previously reserved for cast aluminum, compressing the addressable market for conventional metal forming.
REACH SVHC disclosure obligations and the EU F-Gas Regulation are forcing brake system suppliers to document full material composition for friction material-backing plate assemblies. Substance restriction lists now cover anti-corrosion coatings and bonding adhesives. European OEM procurement teams are rejecting unqualified suppliers, consolidating specification control among integrated friction material manufacturers.
Direct OEM contracting is displacing traditional Tier-2 supply relationships as vehicle assemblers internalize brake system thermal management engineering. Volkswagen, BYD, and Ford now specify backing plate tolerances directly rather than delegating to caliper suppliers. This pattern concentrates most visibly in Germany and China where in-house brake development centers coordinate global platform sourcing.
Automotive Backing Plate Market Segmentation
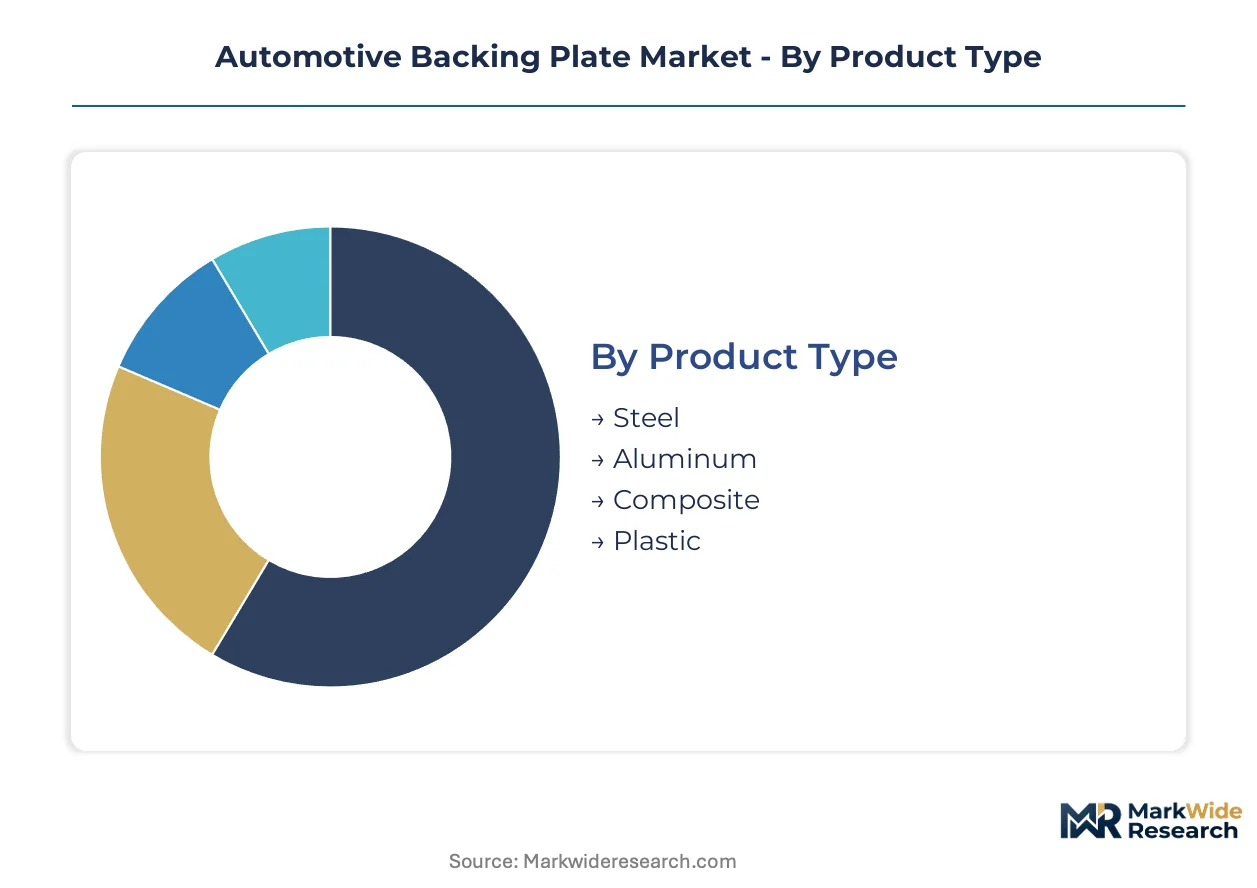
Material substitution timelines and thermal management redesigns are fragmenting specification standards across brake system supply chains. Procurement teams now segment backing plate categories by lifecycle carbon intensity and unsprung mass targets rather than legacy cost-per-unit metrics.
Product Type:
Upgrade cycles for electric vehicle platforms are compressing steel-to-aluminum transition timelines from model-cycle horizons to annual procurement reviews.
- Steel:Cold-rolled high-strength alloys dominate commercial vehicle and budget passenger car segments where NHTSA thermal load requirements govern specification. German and Japanese specialty mills control premium alloy grades, concentrating supply risk for heavy-duty applications.
- Aluminum:Stamped and machined variants capture expanding specification share in electric vehicle brake assemblies where unsprung mass reduction extends range. European OEMs under KBA-enforced EU CO2 fleet targets are accelerating platform redesigns to accommodate thinner aluminum profiles.
- Composite:Glass-fiber reinforced thermoplastics from Chinese domestic manufacturers serve regional new energy vehicle supply chains under MIIT dual carbon procurement directives.
- Plastic:Limited to auxiliary mounting brackets and non-structural applications where thermal exposure remains minimal.
Volume placements concentrate in steel; the faster expansion belongs to aluminum.
End User:
Direct OEM engineering engagement is displacing traditional delegated specification hierarchies across major vehicle assembly networks.
- OEMs:Volkswagen, BYD, and Ford now issue direct backing plate tolerance specifications rather than routing through caliper suppliers, compressing Tier-1 supplier margin pools while accelerating validation cycle ownership.
- Aftermarket Providers:Independent distributors serving North American and European repair networks stock steel-replacement inventories calibrated to NHTSA and KBA safety certification databases.
- Tier-1 Suppliers:Brembo and ZF Friedrichshafen AG maintain captive supply relationships with German vehicle assemblers, leveraging integrated friction material-backing plate assembly expertise to defend specification control.
- Vehicle Assemblers:Maruti Suzuki and Tata Motors in India are consolidating procurement under PLI scheme incentives that attract dedicated stamping investments to regional supply clusters.
Specification authority is climbing the value chain toward OEMs; aftermarket channels retain volume depth in replacement cycles.
Technology:
Process economics and precision tolerance requirements are stratifying manufacturing method selection across performance tiers.
- Stamping:High-speed progressive die operations dominate steel backing plate production for mass-market passenger vehicles, with cycle economics favoring volumes above 500,000 units annually.
- Casting:Gravity and low-pressure aluminum casting serves medium-duty commercial applications where thermal mass requirements exceed stamped sheet capabilities.
- Machining:CNC-machined aluminum plates command premium positioning in electric vehicle programs where noise-vibration-harshness tolerances require surface finish precision beyond stamping limits.
- 3D Printing:Topology-optimized lattice structures enable weight reduction beyond conventional forming limits for motorsport and limited-production hypercar applications.
Stamping retains the deepest volume footprint; machining gains specification share fastest in premium electric platforms.
Installation:
Brake system thermal management architectures are dictating mounting configuration selection across vehicle platform generations.
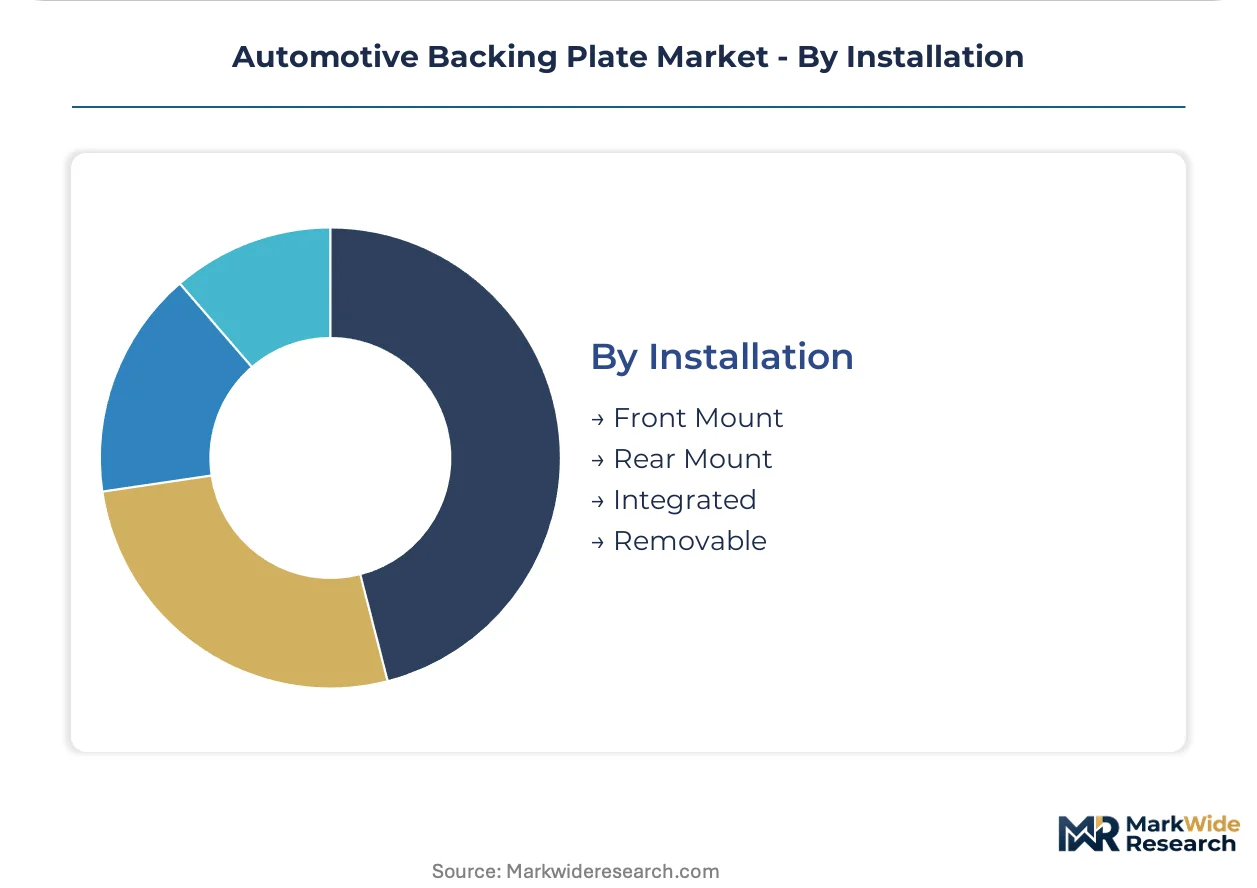
- Front Mount:Higher thermal load exposure drives specification toward aluminum and composite alternatives in electric vehicles where regenerative braking reduces but does not eliminate friction braking demand.
- Rear Mount:Reduced thermal stress permits thinner material gauges and expanded composite qualification in A-segment electric vehicle programs.
- Integrated:Combined backing plate-caliper bracket assemblies consolidate supplier responsibility for tolerance stack management, favoring vertically integrated Tier-1 manufacturers.
- Removable:Service-friendly designs dominate aftermarket replacement specifications where compatibility across multiple vehicle generations drives inventory breadth requirements.
Integrated configurations concentrate value capture among Tier-1 suppliers; removable designs expand fastest in independent aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Germany, China, and the United States where brake system manufacturing serves regional vehicle assembly networks. Consumption patterns diverge as regulatory pressure accelerates material substitution timelines in Europe while cost-sensitive markets retain steel specifications.
Germany
KBA enforcement of EU CO2 fleet targets drives aluminum backing plate procurement for electric vehicle brake assemblies. The EU Green Deal and REACH SVHC disclosure obligations compel suppliers to document lifecycle carbon intensity for friction material-backing plate assemblies. Stuttgart and Munich anchor high-performance brake development centers where Volkswagen and BMW coordinate global platform sourcing specifications.
China
MIIT dual carbon goals redirect domestic procurement toward composite backing plate manufacturers serving regional new energy vehicle supply chains. GB standards for new energy vehicles establish material qualification pathways that favor domestic glass-fiber reinforced thermoplastic producers. Shanghai and Shenzhen manufacturing clusters supply BYD and domestic EV assemblers with compression-molded composite plates.
United States
EPA tailpipe standards and NHTSA brake performance standards maintain steel's position in heavy-duty commercial applications where thermal load capacity governs specification. Detroit and South Carolina assembly networks source stamped steel plates for full-size truck platforms. Tier-1 suppliers face margin compression from aluminum price volatility under annual OEM supply agreements.
India
PLI scheme incentives attract backing plate stamping investments to serve Maruti Suzuki and Tata Motors assembly networks. The country's automotive component policy directs capital toward dedicated regional supply clusters. Gujarat and Tamil Nadu manufacturing corridors expand capacity for budget passenger car steel plate production.
Japan
METI energy efficiency regulations and JIS standards shape material selection for hybrid vehicle brake systems where thermal management requirements differ from pure electric platforms. Aichi Prefecture and Kansai industrial zones maintain specialty steel supply relationships for precision stamping operations serving Toyota and Honda global platforms.
Automotive Backing Plate Market Competitive Environment
The competitive structure tilts toward integrated friction material manufacturers with captive specification control over OEM brake programs. Market concentration remains moderate with distinct capability tiers separating high-volume stampers from precision machining specialists. Three archetypes dominate: vertically integrated brake system suppliers, independent stamping specialists, and composite material innovators. Consolidation pressure intensifies through direct OEM contracting and material requalification partnerships that compress traditional Tier-2 supply margins.
Among European-anchored brake system suppliers, Brembo S.p.A. and ZF Friedrichshafen AG exemplify the integrated archetype through their positions within German vehicle assembler supply networks. NUCAP occupies a position representing friction material integration specialists who control backing plate specifications for major OEM programs. These three entities anchor the competitive landscape across distinct capability vectors—racing and premium road applications, captive German OEM relationships, and friction material-backed specification authority.
| Leading Market Players |
|---|
| NUCAP |
| Dorman Products |
| Brembo S.p.A. |
| ORTLINGHAUS-WERKE GmbH |
| ZF Friedrichshafen AG |
| Aisin Seiki Co., Ltd. |
| MAT Foundry Group Ltd. |
| ACDelco |
| Akebono Brake Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up stamping specialists in North America and Europe are consolidating production assets to extract scale economics from fragmented tooling networks, compressing supplier margins while reinforcing annual contract pricing discipline against volatile aluminum input costs.
Pricing Analysis
Margin tightening in machined aluminum tiers reflects LME price volatility and OEM cost-down mandates. Contract-based long-term offtake agreements dominate high-volume steel stamping, while premium-mid-economy pricing differentiation separates CNC-machined EV plates from commodity stamped variants. Cost compression accelerates in standard-grade segments as Chinese composite producers undercut European aluminum suppliers. Aftermarket distributors exhibit highest price sensitivity; OEM brake engineering teams prioritize NVH performance over unit cost in premium electric platforms.
Supply Chain Analysis
China's MIIT domestic-content mandates for new energy vehicle components are redirecting procurement toward indigenous glass-fiber reinforced thermoplastic manufacturers, fragmenting previously German-dominated specification authority. Supply concentrates in Germany, China, and the United States where brake system manufacturing clusters serve regional vehicle assembly networks. Raw material flows draw from LME aluminum warehouses, German and Japanese specialty steel mills, and Chinese domestic resin compounders. Single-source vulnerability concentrates in high-strength alloy grades controlled by ThyssenKrupp and Nippon Steel. Distribution runs through captive Tier-1 supplier networks for OEM programs and independent aftermarket distributors for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty steel capacity constraints at German and Japanese mills are propping pricing power for qualified heavy-duty backing plate suppliers, creating supply-constrained conditions that favor incumbents with secured alloy allocations.
For Market Incumbents: Deploy friction material integration to lock OEM specification control before direct contracting accelerates. Secure long-term alloy supply agreements with ThyssenKrupp and Nippon Steel to defend against aluminum substitution in commercial segments. Add CNC machining capacity in Germany or China to capture premium EV platform demand as NVH tolerances tighten. For New Entrants and Emerging Players: Enter via composite compression molding for China's A-segment electric vehicle supply chain under MIIT dual carbon procurement directives. Target rear-mount applications where thermal stress permits thinner material gauges and faster qualification cycles. Partner with domestic Chinese EV assemblers bypassing traditional Tier-1 specification hierarchies. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent stamping specialists with secured OEM contracts in India under PLI scheme protections. Five-to-ten year viability hinges on material requalification capabilities as aluminum and composite substitution accelerates. Watch LME aluminum backwardation as inflection signal for margin compression severity in machined plate segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen and BYD are consolidating backing plate tolerances across global EV architectures to reduce validation overhead. |
| Backward Integration into Aluminum Sourcing | Tier-1 suppliers are securing low-carbon aluminum billet supply to meet EU CSRD lifecycle disclosure requirements. |
| Geographic Manufacturing Footprint | India's PLI scheme is attracting dedicated stamping investments to serve Maruti Suzuki and Tata Motors assembly networks. |
| Software-Defined Thermal Management | OEM brake development centers are internalizing regenerative braking integration engineering previously delegated to suppliers. |
| Charging Infrastructure Partnership | Composite backing plate qualification is expanding through partnerships with domestic Chinese EV charging network operators. |
Study Parameters
Vehicle production databases, IHS Markit registration data, and SEC filings from listed brake system suppliers formed the secondary backbone, supplemented by primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Bottom-up and top-down triangulation validated volume estimates across material type and installation configuration segments.
Bottom-up modeling anchored forecasts to named OEM platform launch timelines and content-per-vehicle assumptions across propulsion architectures, while top-down cross-checks referenced regulatory fleet targets from EPA, KBA, and MIIT. Segmentation dimensions included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of material substitution S-curves and thermal management redesign cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions or accelerated NHTSA composite certification pathways. Forecasts reflect assumptions regarding OEM brake system validation cycle durations and MIIT enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Subframe Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Bearing Market