
 Global Automotive Acoustic Materials Market | 2026-2036
Global Automotive Acoustic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Acoustic Materials Market Foresight
Aftermarket service revenue is fragmenting as OEMs push acoustic specifications upstream into platform design. BASF SE leverages its polyurethane foam chemistry leadership to anchor European supply contracts. Dow Inc. competes through silicone-based barrier mat formulations that sustain margin pools in North American EV programs.
Automotive acoustic materials encompass engineered substrates—polyurethane foams, ethylene-vinyl acetate barriers, nonwoven felts, and spray-applied viscoelastic polymers—designed to attenuate airborne noise, structure-borne vibration, and cavity resonance within vehicle architectures. These materials typically target transmission loss values above 25 dB and operate across temperature ranges from minus 40°C to 120°C to maintain NVH performance under powertrain thermal cycling. Foam insulation dominates value contribution due to its ubiquity across headliner and door panel assemblies, while spray-on coatings represent the fastest-expanding category as OEMs seek mass reduction and geometric conformity in battery enclosure sealing. Composite panels concentrate margin pools where multi-layer laminates integrate absorption, barrier, and damping functions into single-source supply.
The EPA regulates volatile organic compound emissions from spray-applied acoustic coatings under National Emission Standards for Hazardous Air Pollutants, while REACH restricts specific flame retardants and isocyanates in European foam formulations. Japan's METI enforces JIS standards for interior material flammability and fogging properties that shape product qualification timelines. Stakeholders must monitor evolving battery electric vehicle platform architectures where thermal-acoustic multifunctionality determines material selection criteria.
Market Dynamics
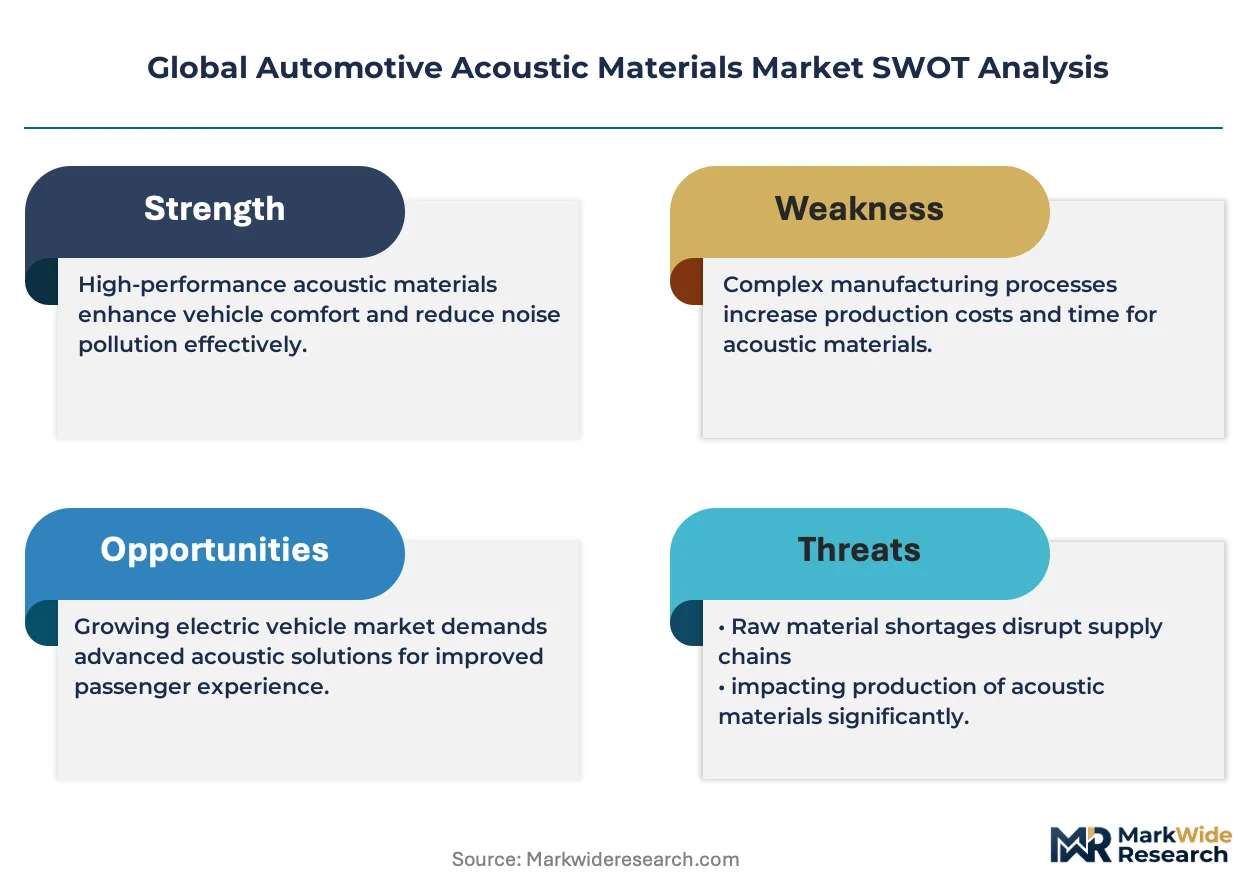
Electric vehicle platform architectures are forcing a fundamental recomposition of acoustic material specifications, as battery enclosures and reduced engine noise signatures expose cabin interior noise sources previously masked by powertrain vibration.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon blowing agents are accelerating polyurethane foam reformulation investments toward low-global-warming-potential alternatives.
- Lightweighting mandates:OEM engineering centers in Germany and Japan are specifying spray-applied viscoelastic coatings to replace multi-layer barrier mats in door cavities and floor pans.
- Powertrain electrification:Elimination of engine masking noise across battery electric vehicle programs is expanding addressable acoustic treatment surface area by 30-40% per vehicle architecture.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with crude oil derivatives, compressing formulation margin pools for foam insulation suppliers.
- REACH compliance complexity:ECHA restrictions on halogenated flame retardants and certain isocyanates are extending European product qualification timelines by 12-18 months.
- Glass fiber substitution:Nonwoven felt manufacturers face displacement risk from recycled textile fiber alternatives in lower-tier vehicle programs.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production are attracting acoustic material suppliers to establish localized compounding and converting operations.
- Thermal-acoustic multifunctionality:Battery pack enclosure sealing applications are converging fire resistance, thermal runaway containment, and NVH attenuation into single-material specifications.
- Direct-to-OEM channel expansion:Platform engineering integration is enabling material suppliers to bypass traditional tiered supply structures and contract directly with vehicle architecture teams.
Industry Challenges
- Cross-functional talent scarcity:Compound formulation chemists with simultaneous expertise in polymer rheology and acoustic engineering command premium compensation and limited availability.
- Multi-jurisdiction certification burden:Simultaneous EPA NESHAP, REACH, and JIS flammability qualification creates redundant testing expenditure for global product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Acoustic Materials Market |
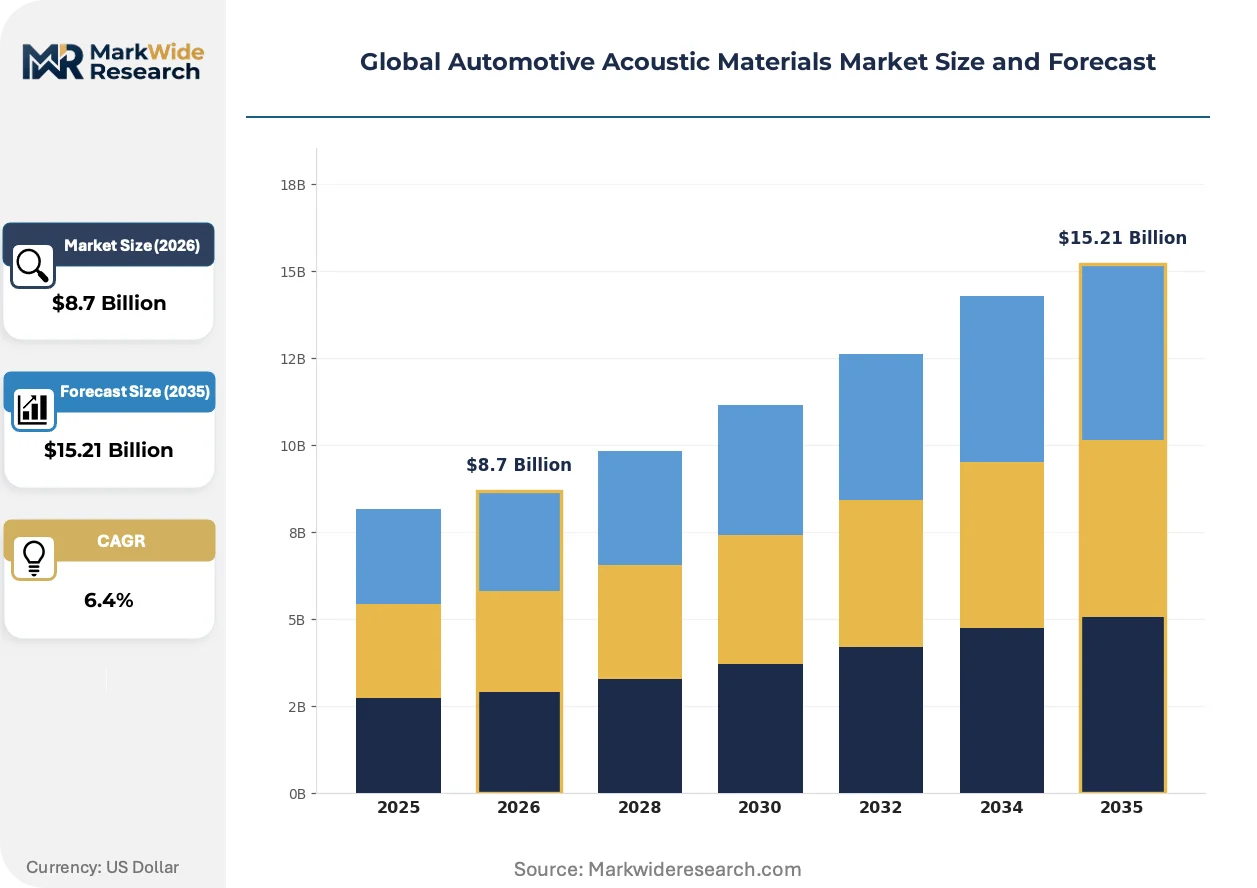
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Insulation, Barrier Mats, Felt Absorbers, Composite Panels, Spray-On Coatings Technology: Sound Absorption, Vibration Damping, Noise Barrier, Sound Transmission Loss, Acoustic Sealing Application: Engine Bay, Door Panels, Headliners, Floor Insulation, Wheel Wells End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Retrofitting, Vehicle Assemblers |
| Companies Covered | BASF SE, Armacell International S.A., Freudenberg Performance Materials SE & Co. KG, Forvia SA, Johns Manville International Inc., Autoneum Holding AG, Dow Inc., Henkel AG & Co. KGaA, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Acoustic Materials Market Shifts & Advancements
Material science convergence with vehicle electrification is collapsing traditional category boundaries between thermal management and acoustic attenuation functions.
Spray-applied viscoelastic polymer technology is collapsing the distinction between structural adhesive and noise barrier applications. Tier 1 suppliers in North American EV programs are adopting robotic dispensing systems to apply these coatings directly to stamped battery tray geometries. This process integration is collapsing separate supply chain steps—damping pad attachment, seam sealing, and NVH treatment—into single manufacturing stations.
REACH authorization requirements for specific isocyanates are forcing polyurethane foam producers to validate alternative curative chemistries. The industrial consequence is a bifurcation between legacy formulation assets and next-generation production lines. European foam insulation suppliers are responding by accelerating capital deployment toward water-blown and CO2-blown expansion technologies ahead of regulatory deadlines.
Fleet operators and ride-hailing platforms are introducing acoustic comfort specifications into procurement scorecards previously dominated by powertrain metrics. This buyer concentration is compressing incumbent supplier relationships and elevating direct contracting with specialty material producers. The shift is most visible in California and Germany, where premium electric vehicle fleet deployment rates exceed other markets by substantial margins.
Global Automotive Acoustic Materials Market Segmentation
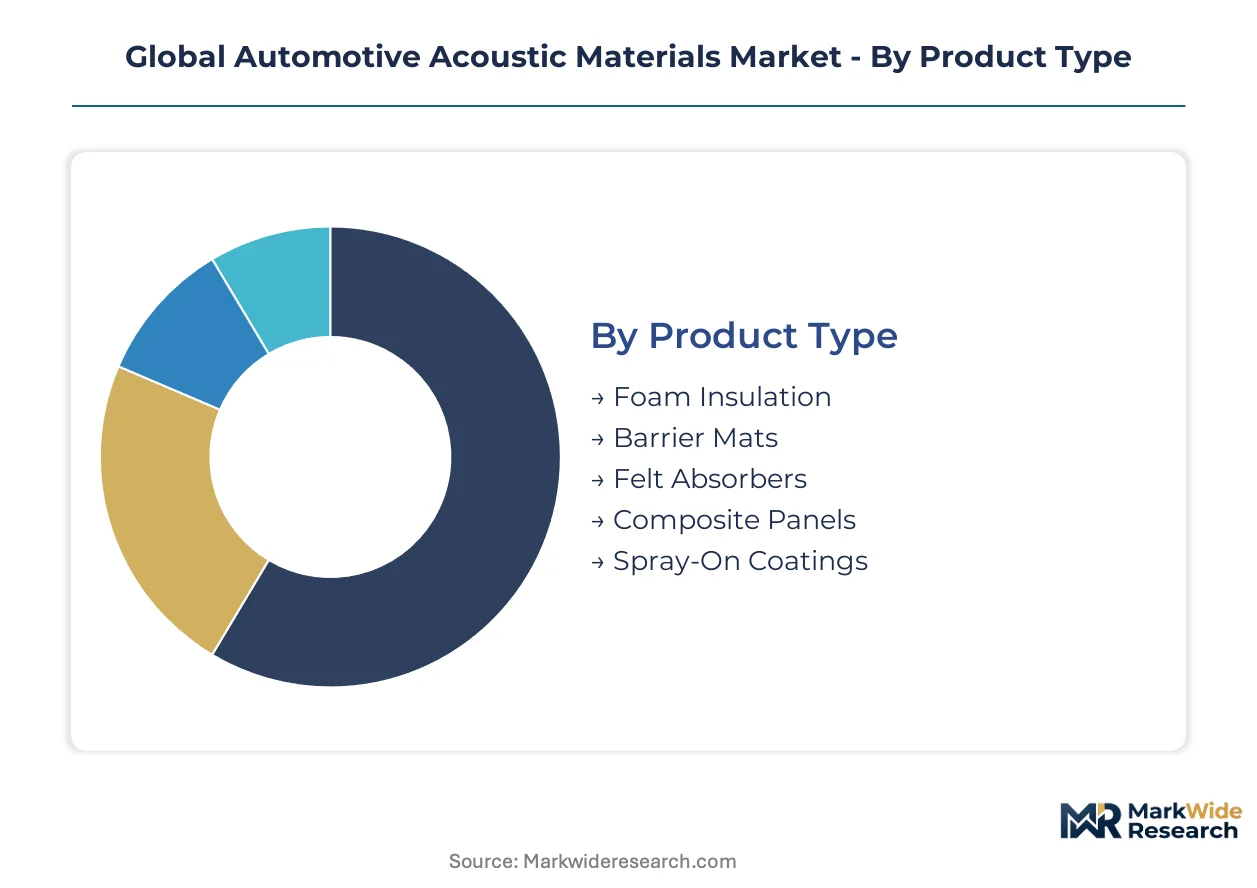
Segmentation in automotive acoustic materials tracks how powertrain electrification is redistributing value across substrate technologies and supply chain tiers. Material suppliers must align portfolio investments with shifting OEM platform architectures and tightening multi-jurisdictional compliance requirements.
Product Type:
Mature foam insulation dominates installed base volume while emerging spray-on coatings capture specification momentum in battery electric vehicle programs.
- Foam Insulation:Polyurethane-based cellular structures with densities ranging from 20 to 80 kg/m³ provide broadband absorption across 500-4000 Hz frequency ranges. German and Japanese OEM engineering centers specify these materials for headliner and door panel assemblies where legacy tooling investments sustain incumbent supply relationships.
- Spray-On Coatings:Viscoelastic polymer formulations applied through robotic dispensing achieve geometric conformity in complex battery tray geometries. North American EV programs are expanding surface treatment area by 30-40% per vehicle as these coatings replace multi-layer barrier mats.
- Barrier Mats:Ethylene-vinyl acetate and mass-loaded vinyl laminates block airborne noise transmission through floor pan and firewall assemblies.
- Felt Absorbers:Nonwoven polyester and recycled textile fiber constructions target wheel well and trunk compartment applications.
- Composite Panels:Multi-layer laminates integrating absorption, barrier, and damping functions into single-source supply for premium vehicle architectures.
Foam insulation handles the majority of throughput; spray-on coatings are expanding most quickly on share.
Technology:
Cost tier differentiation separates established absorption and damping methods from premium transmission loss and sealing specifications required in electric platforms.
- Sound Absorption:Porous material architectures convert acoustic energy to heat through viscous dissipation in open-cell foam and fibrous media. Door panel and headliner applications in Germany and the United States concentrate demand as cabin interior noise sources become more prominent with eliminated engine masking.
- Acoustic Sealing:Spray-applied and gasket-based solutions prevent cavity resonance and airborne leakage paths. Battery enclosure applications in Japan and the United States are converging fire resistance, thermal runaway containment, and NVH attenuation into unified material specifications.
- Vibration Damping:Constrained-layer and free-layer viscoelastic treatments reduce structure-borne noise from road and powertrain inputs.
- Noise Barrier:High-mass flexible membranes block airborne sound transmission through vehicle body panels.
- Sound Transmission Loss:Quantified performance metric driving specification of multi-layer composites in premium vehicle programs.
Sound absorption commands the largest specification volume; acoustic sealing is climbing the fastest as thermal-acoustic multifunctionality converges.
Application:
Customer type stratification separates high-value OEM platform engineering from price-sensitive aftermarket retrofitting channels.
- Floor Insulation:Multi-layer barrier and absorption assemblies address structure-borne road noise and airborne powertrain intrusion. German OEMs are specifying spray-applied viscoelastic coatings to replace traditional multi-layer mats in battery electric platforms.
- Engine Bay:Heat-resistant foam and composite treatments address powertrain noise in internal combustion and hybrid architectures. Japan's METI flammability standards shape qualification timelines for materials operating across minus 40°C to 120°C temperature ranges.
- Door Panels:Combined absorption and barrier treatments address side-impact noise and speaker cavity resonance.
- Headliners:Lightweight foam and nonwoven assemblies provide overhead absorption with head impact compliance.
- Wheel Wells:Spray-applied and molded treatments target tire road noise in premium and electric vehicle programs.
Floor insulation anchors value contribution; wheel well treatments are gaining share fastest as tire noise becomes more prominent in electric vehicle cabins.
End User:
Supply concentration varies sharply between direct OEM platform contracts and fragmented tiered supply structures.
- OEM Manufacturers:Direct material specification by vehicle architecture teams is collapsing traditional tiered supply relationships. California and Germany-based OEMs are introducing acoustic comfort scorecards into procurement decisions for premium electric vehicle fleets.
- Tier-1 Suppliers:Integrated module suppliers manage damping pad attachment, seam sealing, and NVH treatment through single manufacturing stations. North American EV programs are adopting robotic dispensing systems that compress these supply chain steps.
- Vehicle Assemblers:Contract manufacturing operations execute platform specifications with limited material selection autonomy.
- Aftermarket Retrofitting:Service channel revenue is fragmenting as OEMs push acoustic specifications upstream into platform design, reducing addressable retrofit volume.
OEM manufacturers capture the dominant specification authority; tier-1 suppliers are expanding fastest as platform engineering integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement in Germany tolerates premium acoustic specifications, while Indian commercial vehicle buyers remain acutely price-sensitive. This elasticity gradient shapes material supplier prioritization across geographies.
Germany
Premium EV fleet operators in Munich and Stuttgart specify multi-layer composite panels for cabin comfort scorecards. The EU F-Gas Regulation accelerates polyurethane foam reformulation toward low-GWP blowing agents. BASF SE anchors supply relationships from Ludwigshafen through direct OEM platform contracts.
United States
California-based ride-hailing platforms introduce acoustic comfort metrics into procurement decisions previously dominated by range and charging speed. EPA NESHAP standards govern volatile organic compound emissions from spray-applied coatings. Detroit-area OEM engineering centers specify robotic dispensing systems for battery tray NVH treatment.
Japan
Domestic OEMs expand acoustic treatment surface area by 30-40% per BEV architecture as engine masking noise disappears. METI enforces JIS flammability and fogging standards that extend material qualification timelines. Nagoya and Tokyo clusters concentrate tier-1 supplier module integration capabilities.
India
PLI scheme incentives for electric vehicle production attract acoustic material suppliers to establish localized compounding operations. BIS standards for interior material flammability shape product development requirements. Tamil Nadu and Maharashtra host emerging converting operations serving domestic OEM assembly plants.
China
Domestic EV platform architectures drive specification of thermal-acoustic multifunctional materials for battery enclosure sealing. MIIT oversees vehicle interior air quality and material safety standards. Yangtze River Delta manufacturing clusters integrate spray-applied coating lines into stamping and assembly operations.
Global Automotive Acoustic Materials Market Competitive Landscape
Diversified chemical conglomerates and specialized automotive suppliers split the market into distinct capability tiers. European and North American incumbents anchor premium specification relationships through formulation chemistry leadership. Three archetypes dominate: integrated chemical producers with polyurethane foam assets, tier-1 module suppliers with robotic application capabilities, and specialty coating formulators with viscoelastic polymer expertise. Competitive moves concentrate on direct-to-OEM channel expansion and qualification of low-GWP blowing agent formulations ahead of regulatory deadlines.
Within the integrated chemical producer tier, BASF SE and Dow Inc. exemplify divergent strategic positioning. BASF SE anchors European supply through polyurethane chemistry leadership and direct platform engineering relationships. Dow Inc. occupies a position in North American EV programs through silicone-based barrier formulations. Among specialized automotive suppliers, Autoneum Holding AG represents the tier-1 module integration archetype with capabilities spanning damping, sealing, and NVH treatment. 3M Company sits within the specialty materials tier, leveraging adhesive and coating technology portfolios for acoustic sealing applications.
| Leading Market Players |
|---|
| BASF SE |
| Armacell International S.A. |
| Freudenberg Performance Materials SE & Co. KG |
| Forvia SA |
| Johns Manville International Inc. |
| Autoneum Holding AG |
| Dow Inc. |
| Henkel AG & Co. KGaA |
| 3M Company |
| Others |
Supply & Pricing Matrix
Overcapacity in European polyurethane foam compounding facilities is compressing supplier margins while simultaneously accelerating price competition for battery electric vehicle platform contracts. BASF SE and Dow Inc. are diverting excess capacity toward direct OEM engagements, reshaping pricing power away from tiered distribution channels.
Pricing Analysis
Aftermarket service revenue—including acoustic retrofit kits and dealer-installed NVH treatments—drives lifetime value capture as OEMs push specifications upstream. Three-tier pricing structure across premium, standard, and economy levels separates direct platform engineering contracts from tier-1 module supply and aftermarket channels. Price differentiation rests on REACH compliance certification and thermal-acoustic multifunctionality performance grades. Cost compression in standard-grade foam insulation is intensifying because Indian and Chinese domestic OEMs are qualifying recycled textile fiber alternatives. Fleet operators in California and Germany exhibit the lowest price sensitivity, while Indian commercial vehicle buyers remain most acutely cost-conscious.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are forcing tier-1 suppliers to utilize supply-chain finance facilities, squeezing working capital for compounders. Manufacturing concentrates in Germany, Japan, and the United States where OEM engineering centers cluster. Raw material flows draw from Saudi Arabian petrochemical feedstocks for polyol production, Belgian isocyanate derivatives, and Chinese recycled textile fiber. Single-source vulnerability in hydrofluorocarbon blowing agent supply chains is elevating risk exposure ahead of EU F-Gas Regulation phase-down deadlines. Distribution runs through integrated tier-1 module suppliers with robotic dispensing capabilities rather than fragmented converting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering integration is transforming acoustic materials into a service-attach opportunity as direct OEM contracts expand faster than hardware-only supply. Recurring-revenue layers—including formulation co-development fees and lifecycle qualification services—are outpacing commodity foam sales.
For Market Incumbents: Insulate margin pools by accelerating backward integration into low-global-warming-potential blowing agent production ahead of regulatory deadlines. BASF SE and Dow Inc. should deepen captive supply of CO2-blown expansion technologies to defend against emerging Asian compounders with state-subsidized capacity. Certification investment in simultaneous EPA NESHAP, REACH, and JIS qualification creates switching costs that protect European and North American platform relationships.
For New Entrants and Emerging Players: Establish a beachhead in Indian electric vehicle acoustic treatment by qualifying BIS-compliant recycled textile fiber formulations under PLI scheme incentives. Tamil Nadu and Maharashtra assembly plants offer the most penetrable entry point for localized compounding operations. A direct-to-OEM channel strategy targeting domestic EV platform teams bypasses entrenched tier-1 relationships in saturated German and Japanese markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty coating formulators with viscoelastic polymer expertise and robotic application integration capabilities. Long-term viability over the next decade favors suppliers with thermal-acoustic multifunctionality patents serving battery enclosure sealing applications. The signal to monitor is fleet operator procurement scorecard adoption of acoustic comfort metrics in California and Germany, which would accelerate direct contracting and collapse traditional tiered supply structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP Blowing Agent Transition | EU F-Gas Regulation compliance secures European platform contracts against reformulation delays. |
| Direct-to-OEM Channel Expansion | Bypassing tier-1 suppliers captures higher margins in battery electric vehicle programs. |
| Thermal-Acoustic Multifunctionality R&D | Battery enclosure sealing convergence differentiates suppliers in premium EV architectures. |
| Robotic Dispensing System Deployment | North American EV programs integrate spray-applied coatings into single manufacturing stations. |
| Indian Localized Compounding Operations | PLI scheme incentives attract acoustic material suppliers to Tamil Nadu and Maharashtra clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and vehicle production databases. Interviews with OEM platform engineers, tier-1 supplier procurement leads, acoustic R&D directors, and aftermarket distributors informed demand-side assumptions. Bottom-up modeling of content-per-vehicle metrics and top-down validation against regional production volumes ensured triangulation integrity.
Forecast inputs span propulsion architecture transitions, battery electric vehicle platform rollout schedules, and regulatory compliance deadline clustering. Segmentation dimensions include material substrate type, vehicle class, OEM tier positioning, and regional manufacturing hub. CAGRs were derived from installed base evolution and specification shift modeling across the analysis window. Thermal-acoustic multifunctionality adoption curves and low-GWP blowing agent conversion timelines shaped scenario weightings.
Stress conditions across petrochemical feedstock volatility, REACH authorization delays, and Indian PLI scheme disbursement pacing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding battery electric vehicle penetration and OEM platform consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Distributor Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Actuators Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Glass Fiber Composites Market