
 Exhaust System Muffler Market | 2026-2036
Exhaust System Muffler Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust System Muffler Market Insights
Modular exhaust system packaging is realigning how fleet operators and OEM procurement teams evaluate muffler procurement. Tenneco leverages its vertically integrated emissions-control platform to bundle catalytic converters with tuned muffler modules for light-truck platforms. Eberspächer anchors its European position through R&D intensity in active noise-cancellation hardware integrated into dual-chamber architectures.
An exhaust system muffler is an acoustic device installed within a vehicle's exhaust stream, typically fabricated from 409-grade stainless steel or aluminized steel with internal baffle plates, perforated tubes, and sound-absorbing fill materials designed to attenuate pressure-wave noise while managing backpressure limits. Its primary commercial purpose is to ensure regulatory noise compliance and optimize engine breathing efficiency across operating regimes. Stainless steel absorptive mufflers command the widest OEM placement in passenger vehicles due to corrosion resistance and weight targets, while reactive dual-chamber designs dominate heavy-duty truck specifications where thermal cycling and low-frequency attenuation drive specification. Aftermarket installation channels for universal-fit aluminized steel units remain structurally fragmented, with margin pools concentrating in custom titanium and carbon fiber configurations for performance motorcycle segments.
The US EPA and NHTSA jointly enforce noise-emission ceilings and fuel-economy standards that directly shape muffler backpressure tolerances and material selection in domestic vehicle programs. Europe's Euro 7 framework, administered by the European Commission and ECHA, extends particulate and noise limits that force redesigns of chamber geometry and packing density. China's MIIT and MEE implement GB standards for commercial vehicle noise that push Shiyan-based manufacturers toward stainless steel compliance architectures. Stakeholders must monitor how regional decarbonization timelines recalibrate the trade-off between acoustic attenuation and exhaust-flow restriction across powertrain electrification strategies.
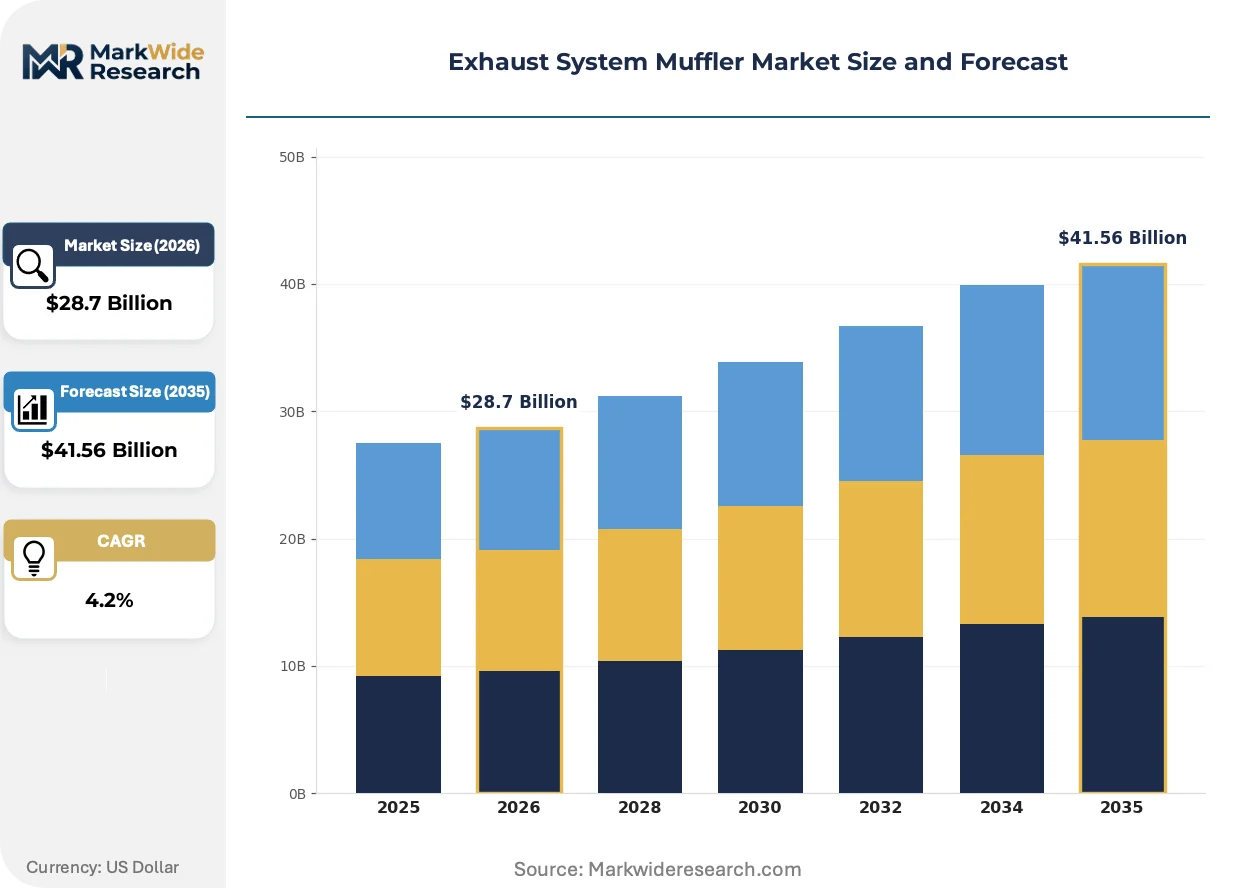
Market Dynamics
Euro 7 emission standards are compressing design cycles for acoustic-performance hardware while commercial vehicle electrification in China forces muffler suppliers to recalibrate thermal-management and backpressure specifications for hybrid powertrains.
Growth Catalysts
- Heavy-duty fleet replacement cycles:North American trucking operators are compressing muffler replacement intervals to preempt roadside inspection failures under EPA noise-enforcement protocols.
- Stainless steel compliance architectures:China's GB standards for commercial vehicle noise are pushing Shiyan and Chongqing manufacturers toward 409-grade stainless systems that withstand thermal cycling.
- Active noise-cancellation integration:European OEM procurement teams are specifying dual-chamber mufflers with embedded ANC hardware to meet stricter cabin-noise targets without flow restriction penalties.
Market Restraints
- Nickel price volatility:409-grade stainless steel feedstock costs fluctuate with Indonesian and Philippine nickel ore export quotas, squeezing margin pools on absorptive muffler production.
- Supply concentration in Shiyan:China's commercial vehicle exhaust corridor concentrates 60-plus percent of stainless steel muffler foundry capacity, creating single-point vulnerability to regional power-rationing or environmental stoppages.
- Particulate filter integration friction:Euro 7's combined particulate and noise limits force incompatible packaging geometries that increase backpressure beyond turbocharger efficiency tolerances.
Strategic Opportunities
- India commercial vehicle buildout:BIS noise standards for Bharat Stage VI trucks are creating first-time demand for stainless steel muffler architectures in Pune and Chennai manufacturing clusters.
- Titanium performance motorcycle segments:Aftermarket channels for custom titanium and carbon fiber configurations command margin multiples above OEM aluminized steel units.
- Hybrid powertrain thermal management:Convergence of active exhaust valves with variable-geometry muffler chambers enables real-time acoustic tuning for plug-in hybrid operating modes.
Industry Challenges
- Acoustic simulation talent scarcity:Computational fluid dynamics expertise for pressure-wave modeling concentrates at Tier-1 suppliers, limiting mid-tier foundries' in-house design capabilities.
- Euro 7 certification timeline compression:ECHA's extended particulate testing protocols add 8-14 months to chamber-geometry validation cycles, freezing platform development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust System Muffler Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $41.56 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Dual Chamber, Absorptive, Reactive Material: Stainless Steel, Aluminized Steel, Titanium, Carbon Fiber Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Installation Type: Original Equipment Manufacturer, Aftermarket, Custom Installation, Universal Fit |
| Companies Covered | Tenneco, Eberspächer, Forvia Faurecia, Bosal, Benteler International, Futaba Industrial, Magna International, Continental AG, Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust System Muffler Market Trends and Innovations
Acoustic engineering is converging with emissions-control hardware as modular packaging and active noise-cancellation hardware displace passive single-chamber designs across light-truck and heavy-duty specifications.
Micro-perforated titanium sheet is absorbing high-frequency pressure waves in performance motorcycle and premium passenger applications where weight targets preclude stainless steel bulk. European and Japanese OEM procurement teams are specifying titanium absorptive cores for sport-utility platforms above 200 kilowatt output. This material shift is absorbing margin from traditional aluminized steel aftermarket channels while concentrating volume at specialized foundries with vacuum-brazing capability.
REACH amendments on persistent organic pollutants are restricting sound-absorbing fill materials in chamber-packed mufflers, forcing reformulation of fiberglass and rock-wool blends across European supply chains. ECHA's substance restriction timeline is compressing packing-density specifications that previously attenuated low-frequency drone. Heavy-duty truck programs with extended idle regimes are most affected, with German and Swedish OEMs accelerating ceramic-fiber alternative qualification.
Fleet operators are consolidating muffler procurement through long-term service agreements that bundle replacement cycles with predictive maintenance telemetry. This behavior shift is disintermediating traditional jobber distributors in North American aftermarket channels. Large trucking conglomerates with 500-plus unit fleets are capturing volume discounts and guaranteed uptime clauses that fragment margin pools among smaller owner-operator segments concentrated in Texas and Ohio corridors.
Exhaust System Muffler Market Segmentation
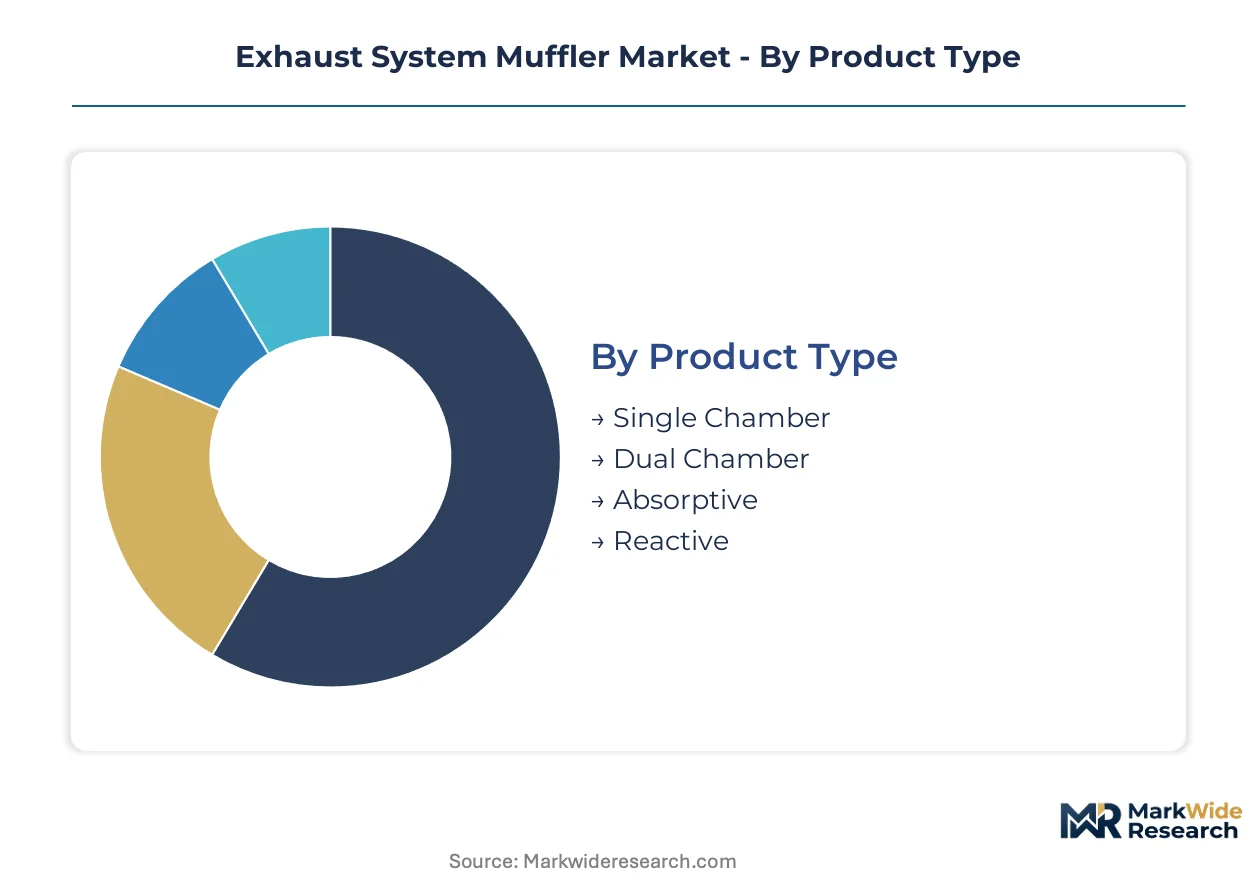
Muffler procurement patterns diverge sharply across product architectures and material grades. Fleet operators, OEMs, and aftermarket channels each prioritize distinct performance thresholds that reshape supplier positioning.
Product Type:
Supply concentration tilts toward dual-chamber and absorptive architectures where foundry capacity has consolidated around emission-compliant designs.
- Single Chamber:Simple baffle-plate construction dominates economy motorcycle and compact passenger platforms where cost minimization overrides acoustic refinement. Demand concentrates in India's two-wheeler belt around Pune and Chennai as BIS noise standards harden.
- Dual Chamber:Separate expansion and resonance chambers enable low-frequency attenuation without excessive backpressure. European OEM procurement teams specify these for light-truck platforms under Euro 7's combined particulate and noise limits.
- Absorptive:Perforated tubes packed with sound-absorbing material attenuate across broader frequency ranges.
- Reactive:Helmholtz resonators and quarter-wave tubes target specific engine orders.
Dual-chamber designs absorb the bulk of installed capacity; absorptive configurations are expanding most quickly.
Material:
Cost tier stratification separates commodity aluminized steel from premium titanium and carbon fiber grades with 5-8x margin multiples.
- Stainless Steel:409-grade ferritic stainless withstands thermal cycling and salt corrosion in heavy-duty truck specifications. China's Shiyan manufacturing corridor has concentrated foundry capacity for GB-compliant commercial vehicle architectures.
- Aluminized Steel:Hot-dip aluminum-silicon coating provides oxidation resistance at lower material cost.
- Titanium:Micro-perforated sheet absorbs high-frequency pressure waves at 40% weight reduction versus stainless. Japanese and German OEMs specify titanium cores for sport-utility platforms above 200 kilowatt output.
- Carbon Fiber:Woven composite shells encase absorptive cores in premium motorcycle aftermarket channels.
Stainless steel commands the greatest production volume; titanium is climbing the fastest as weight targets tighten.
Application:
Volume distribution follows commercial vehicle build rates and fleet replacement cycles across regional manufacturing corridors.
- Passenger Vehicles:Stainless steel absorptive mufflers with tuned backpressure dominate OEM placement.
- Commercial Vehicles:Reactive dual-chamber designs manage thermal shock from extended idle regimes. North American trucking operators compress replacement intervals to preempt EPA roadside inspection failures.
- Motorcycles:Aftermarket titanium and carbon fiber configurations command margin concentration in custom fabrication shops.
- Heavy-Duty Trucks:Severe-duty specifications require reinforced chamber geometries and ceramic-fiber packing alternatives as REACH amendments restrict traditional fill materials.
Commercial vehicles absorb the bulk of installed capacity; heavy-duty trucks are gaining share fastest on fleet renewal intensity.
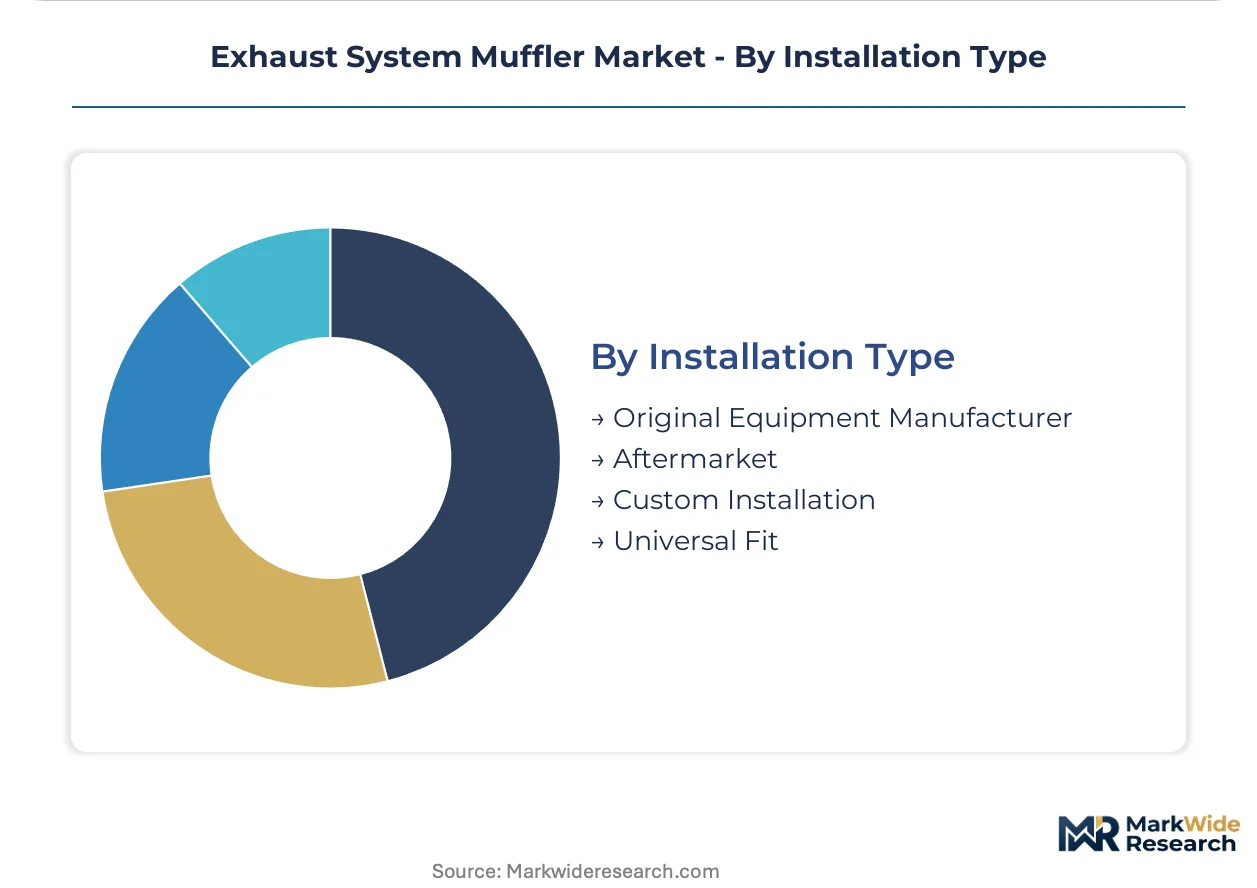
Installation Type:
Customer type fragmentation separates captive OEM supply from fragmented aftermarket channels with diverging margin structures.
- Original Equipment Manufacturer:Long-term platform contracts with volume guarantees and joint validation programs. Tenneco and Eberspächer anchor OEM supply through modular emissions-control bundling.
- Aftermarket:Jobber distributors face disintermediation as fleet operators consolidate procurement through predictive maintenance agreements.
- Custom Installation:Performance shops fabricate titanium systems for motorcycle racing segments.
- Universal Fit:Standardized inlet/outlet dimensions serve fragmented owner-operator segments in Texas and Ohio corridors.
OEM channels absorb the bulk of installed capacity; custom installation is expanding most quickly on premium motorcycle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China fabricates the majority of stainless steel muffler capacity while the United States and Germany consume premium architectures for heavy-duty and light-truck platforms. This production-consumption divide shapes supplier location strategies and tariff exposure.
United States
Heavy-duty trucking fleets compress replacement cycles to preempt EPA roadside inspection failures under NHTSA noise-enforcement protocols. The EPA and NHTSA jointly enforce fuel-economy standards that constrain backpressure tolerances in domestic vehicle programs. Manufacturing activity clusters in Ohio and Texas corridors where fleet operators consolidate procurement through predictive maintenance agreements.
Germany
ECHA's Euro 7 framework extends particulate and noise limits that force redesigns of chamber geometry and packing density. German OEM procurement teams specify dual-chamber mufflers with embedded active noise-cancellation hardware. Stuttgart and Munich engineering centers anchor acoustic simulation talent for pressure-wave modeling.
China
MIIT and MEE implement GB standards for commercial vehicle noise that push manufacturers toward 409-grade stainless steel compliance architectures. The Shiyan and Chongqing manufacturing corridor concentrates foundry capacity for GB-compliant systems. Regional power-rationing or environmental stoppages create single-point vulnerability for global supply.
India
BIS noise standards for Bharat Stage VI trucks generate first-time demand for stainless steel muffler architectures in commercial vehicle buildout. The central automotive regulator mandates stricter acoustic compliance for new truck registrations. Pune and Chennai manufacturing clusters absorb expanding foundry investment for absorptive and dual-chamber designs.
Japan
METI oversees JIS standards that shape thermal-management specifications for hybrid powertrain exhaust hardware. Japanese OEMs specify micro-perforated titanium cores for sport-utility platforms above 200 kilowatt output. Nagoya and Osaka industrial zones concentrate vacuum-brazing capability for lightweight absorptive systems.
Exhaust System Muffler Market Competitive Landscape
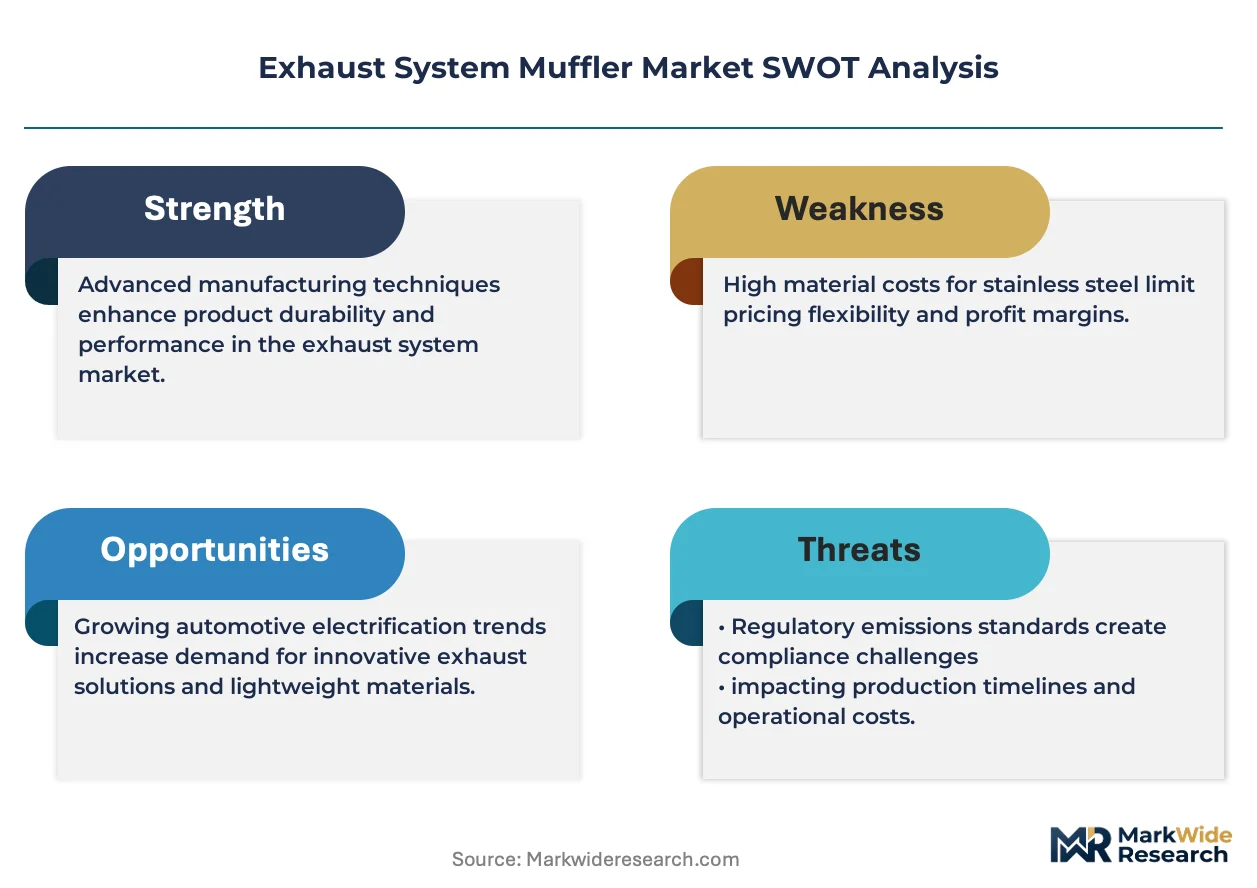
Diversified conglomerates compete with focused pure-play specialists across distinct tier positions. Tier-1 suppliers anchor OEM supply through modular emissions-control bundling and long-term platform contracts. The vendor base stratifies into three archetypes: vertically integrated emissions platforms, acoustic engineering specialists, and regional stainless steel fabricators. Dominant competitive moves include capacity concentration in China's Shiyan corridor and technology licensing for active noise-cancellation hardware.
Among diversified emissions-control platforms, Tenneco and Eberspächer occupy positions exemplifying modular bundling strategies with catalytic converters and tuned muffler modules. Forvia Faurecia represents the tier of automotive suppliers diversifying into exhaust system integration. These three companies anchor the competitive structure without exhaustive market share claims.
| Leading Market Players |
|---|
| Tenneco |
| Eberspächer |
| Forvia Faurecia |
| Bosal |
| Benteler International |
| Futaba Industrial |
| Magna International |
| Continental AG |
| Marelli |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange nickel futures cascade through 409-grade stainless steel feedstock costs into three-tier pricing structure across premium, standard, and economy levels. Indonesian export quota volatility compresses margin pools at foundries serving Shiyan-based commercial vehicle manufacturers while concentrating pricing power among vacuum-brazing specialists fabricating titanium absorptive cores.
Pricing Analysis
Margin tightening in aluminized steel aftermarket channels reflects nickel price volatility and REACH-driven reformulation costs for sound-absorbing fill materials. Contract-based long-term offtake agreements dominate OEM procurement with volume-guarantee clauses, while spot-market fragmentation persists for universal-fit replacement units. Price differentiation hinges on certification grade against Euro 7 and GB standards plus thermal-cycling performance tier. Fleet operators exhibit lowest price sensitivity due to predictive maintenance bundling; owner-operator segments in Texas and Ohio corridors show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through modular emissions-control bundling with catalytic converters. Manufacturing gravity centers on China, Germany, and Japan with raw material dependencies on Indonesian nickel ore, Philippine chromite, and titanium sponge from Japan. Distribution runs through captive Tier-1 supplier networks for OEM placement and fragmented jobber channels for aftermarket replacement. Single-source vulnerability concentrates in Shiyan's foundry corridor where environmental stoppages propagate global supply disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active noise-cancellation hardware integration is displacing passive single-chamber architectures across European and North American light-truck platforms, compressing design-cycle timelines and recalibrating supplier capability requirements.
For Market Incumbents: Deploy backward integration into nickel-bearing stainless steel feedstock to buffer Indonesian export quota volatility. Anchor capacity expansion in India's Pune and Chennai clusters to capture Bharat Stage VI commercial vehicle buildout. Counter titanium core displacement in premium sport-utility segments through vacuum-brazing capability acquisition. For New Entrants and Emerging Players: Begin with ceramic-fiber alternative qualification for heavy-duty truck packing applications as REACH amendments restrict traditional fiberglass blends. Target India's first-time stainless steel muffler demand driven by BIS noise standard enforcement. Pursue technology licensing partnerships with European acoustic simulation specialists to circumvent CFD talent scarcity. For Investors and Strategic Acquirers: The window for entry favors specialized foundries with vacuum-brazing capability and active noise-cancellation hardware integration expertise. Long-term viability hinges on hybrid powertrain thermal-management positioning as plug-in hybrid volumes expand. Monitor ECHA certification timeline compression as inflection signal for platform development budget freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Feedstock | Mitigates Indonesian export quota volatility squeezing 409-grade stainless margin pools. |
| Vacuum-Brazing Capability Acquisition | Captures titanium absorptive core demand from Japanese and German OEM sport-utility platforms. |
| Ceramic-Fiber Alternative Qualification | Addresses REACH restrictions on persistent organic pollutants in heavy-duty truck packing materials. |
| Active Noise-Cancellation Hardware Licensing | Accelerates Euro 7 compliance without backpressure penalties for dual-chamber architectures. |
| India Manufacturing Footprint Expansion | Positions for Bharat Stage VI commercial vehicle buildout in Pune and Chennai clusters. |
Research Methodology
Document review covered customs and trade data, MIIT production statistics, ECHA regulatory filings, and vehicle registration databases, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and foundry operations managers. Bottom-up volume triangulation across product type, material grade, and installation channel dimensions was cross-validated against top-down macroeconomic indicators and regional production forecasts.
Historical shipment patterns were cross-referenced against expert panel input from acoustic engineering specialists and thermal-management designers across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional regulatory cluster. CAGRs were derived from regression analysis of replacement cycle intensity, emission standard phase-in schedules, and fleet operator procurement consolidation trends.
Underlying measurement precision varies by segment; OEM channel volumes carry tighter precision than fragmented aftermarket replacement data. Forecasts reflect assumptions regarding nickel price trajectory, Euro 7 certification timeline adherence, and hybrid powertrain adoption curves. Periodic stress-testing of base assumptions is recommended against regulatory enforcement intensity and regional power-rationing events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Carburetor Market
Powertrain
Automotive Power Modules Market
Powertrain
Tuning Box Market
Powertrain
Automatic Transmission Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Automotive Coil Spring Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Iridium Spark Plug Market