
 Metal Cutting Tools Market | 2026-2036
Metal Cutting Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cutting Tools Market Analysis
Japanese carbide producers is pivoting toward coated insert capacity to serve electric vehicle powertrain machining. Sandvik Coromant leverages its captive powder metallurgy operations to secure tungsten supply. Kennametal anchors North American distribution through direct service contracts with Tier-1 aerospace suppliers. Iscar Ltd. specializes in modular quick-change tooling systems that reduce setup time in high-mix manufacturing.
Metal cutting tools are engineered implements designed to remove material from workpieces through shearing, abrasion, or erosion, typically featuring hardness exceeding 60 HRC and operating at surface speeds from 50 to 500 m/min depending on substrate. Their primary purpose centers on achieving dimensional tolerances within micrometers while maximizing material removal rates in subtractive manufacturing. Carbide inserts command the dominant material position due to thermal stability at elevated cutting temperatures, while high-speed steel retains cost advantages in intermittent cutting and regrinding applications. Aerospace application segments concentrate the highest value-per-unit demand, driven by titanium and nickel superalloy machining requirements that consume tool life rapidly.
OSHA enforces permissible exposure limits for metalworking fluids and airborne particulates in US fabrication facilities, directly influencing coolant system investments and tool coating selections. REACH compliance in Europe restricts cobalt and hexavalent chromium content in cutting tool substrates, compelling reformulation of cemented carbide grades. Japan's METI promotes domestic machine tool digitization standards that interface with tool life monitoring systems. Stakeholders must monitor how carbon border adjustment mechanisms reshape competitive sourcing between Asian carbide producers and European precision toolmakers.
Market Dynamics
Carbide insert recycling mandates under EU REACH compliance are forcing reformulation of cemented carbide grades across supplier networks, while tungsten supply concentration in Chinese processing facilities creates procurement risk for European and Japanese toolmakers.
Growth Catalysts
- Aerospace titanium machining demand:German and Japanese aerospace manufacturers are expanding precision machining capacity for engine components, driving consumption of heat-resistant coated inserts.
- REACH cobalt restrictions:European cemented carbide reformulation is accelerating development of nickel- and iron-binder alternatives that perform at elevated cutting temperatures.
- Yangtze River Delta cluster expansion:China's machine tool concentration is absorbing high volumes of indexable inserts for automotive and electronics manufacturing equipment.
Market Restraints
- Tungsten supply concentration:Chinese processors control over 80% of global tungsten concentrate supply, exposing European and North American carbide producers to export quota volatility.
- Hexavalent chromium coating bans:EU REACH restrictions on PVD coating chemistries limit corrosion-resistant surface treatments for high-speed steel tooling.
- High-speed steel substitution:Powder metallurgy high-speed steel retains cost advantages in intermittent cutting but faces displacement by solid carbide in continuous machining.
Strategic Opportunities
- Electric vehicle powertrain machining:Japanese carbide producers are pivoting toward coated insert capacity to serve motor housing and battery tray aluminum machining requirements.
- Tool life monitoring integration:Japan's METI digitization standards create interface specifications that favor domestic sensor-embedded tooling systems.
- Carbide powder recycling infrastructure:EU circular economy directives are mandating take-back programs that reward producers with captive recycling technology.
Industry Challenges
- Cobalt-free binder formulation:Metallurgical expertise for replacing cobalt in cemented carbide remains concentrated among a limited pool of powder specialists.
- Multi-axis machine tool synchronization:Complex tool path programming for five-axis machining centers requires CAM software integration that extends qualification timelines.
- OSHA metalworking fluid compliance:US fabrication facilities face airborne particulate monitoring requirements that demand upgraded coolant delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cutting Tools Market |
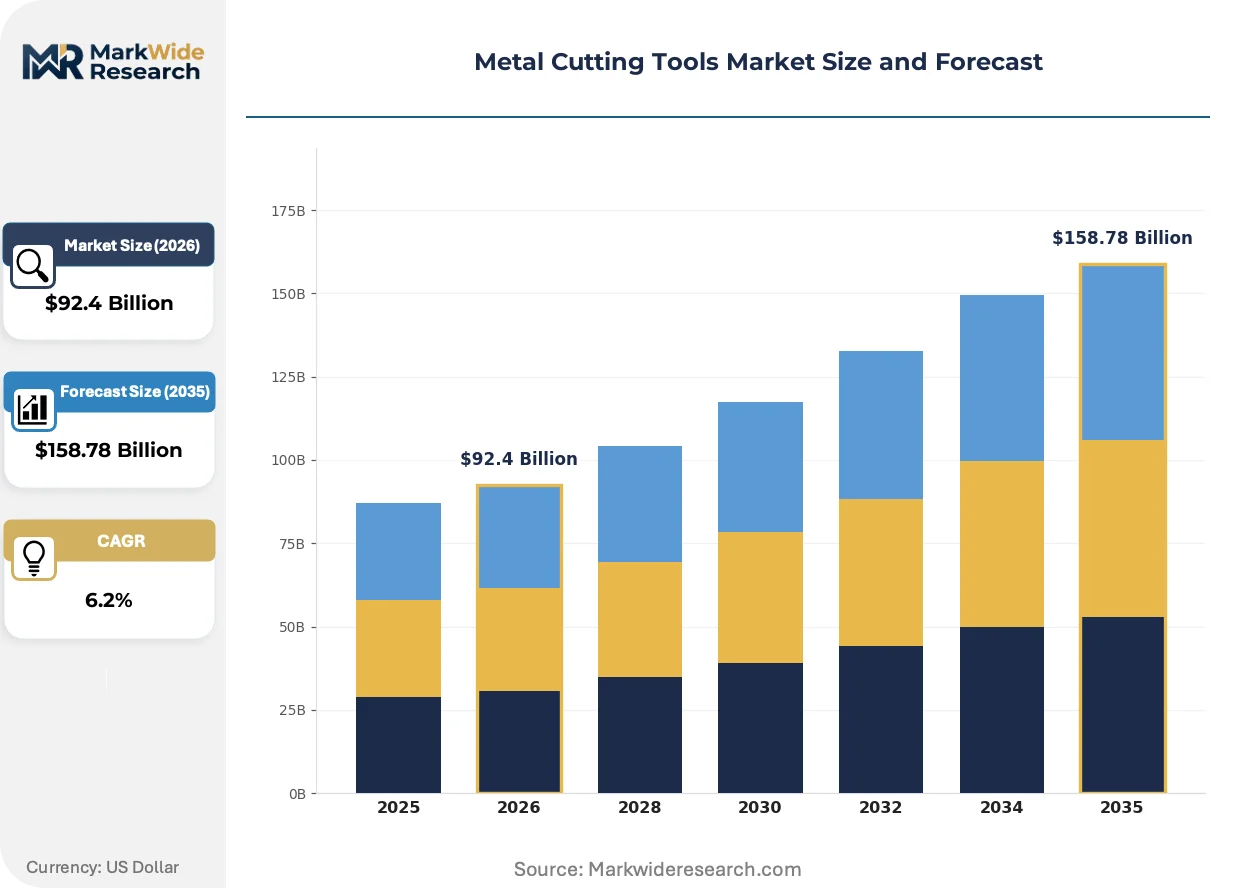
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End Mills, Drills, Taps, Saws Material: High-Speed Steel, Carbide, Cobalt, Ceramics Application: Aerospace, Automotive, Industrial Manufacturing, Construction Size: Small, Medium, Large, Extra Large |
| Companies Covered | Mitsubishi Materials Corporation, Seco Tools AB, Sandvik Coromant, Walter AG, Iscar Ltd., Kennametal, Kyocera Corporation, Ceratizit S.A., Tungaloy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cutting Tools Market Emerging Trajectories
Coating technologies and tool body architectures are converging to extend cutting edge longevity in difficult-to-machine alloys, while regulatory pressure on hazardous materials accelerates substrate reformulation.
Multi-layer CVD-PVD hybrid coatings are extending tool life in nickel superalloy applications by 40-60% through thermal barrier and oxidation resistance stacking. Aerospace engine manufacturers in Germany and Japan are specifying these coatings for turbine disk machining. The technology is modularizing tool specification into substrate-coating-geometry combinations that match specific alloy families rather than universal grades.
EU REACH Annex XVII restrictions on cobalt compounds are compelling carbide producers to validate nickel-iron binder systems for equivalent transverse rupture strength. Industrial consequence includes extended qualification cycles for new cemented carbide grades. European precision toolmakers are most affected, with several producers accelerating in-house powder metallurgy capabilities to control binder formulation.
Direct service contracts between carbide producers and Tier-1 aerospace suppliers are displacing distributor-led technical sales in North America and Western Europe. Sandvik Coromant and Kennametal are deploying application engineers to customer facilities for process optimization. This pattern concentrates most visibly in US and German aerospace clusters where long-term productivity guarantees replace per-insert pricing.
Metal Cutting Tools Market Segmentation
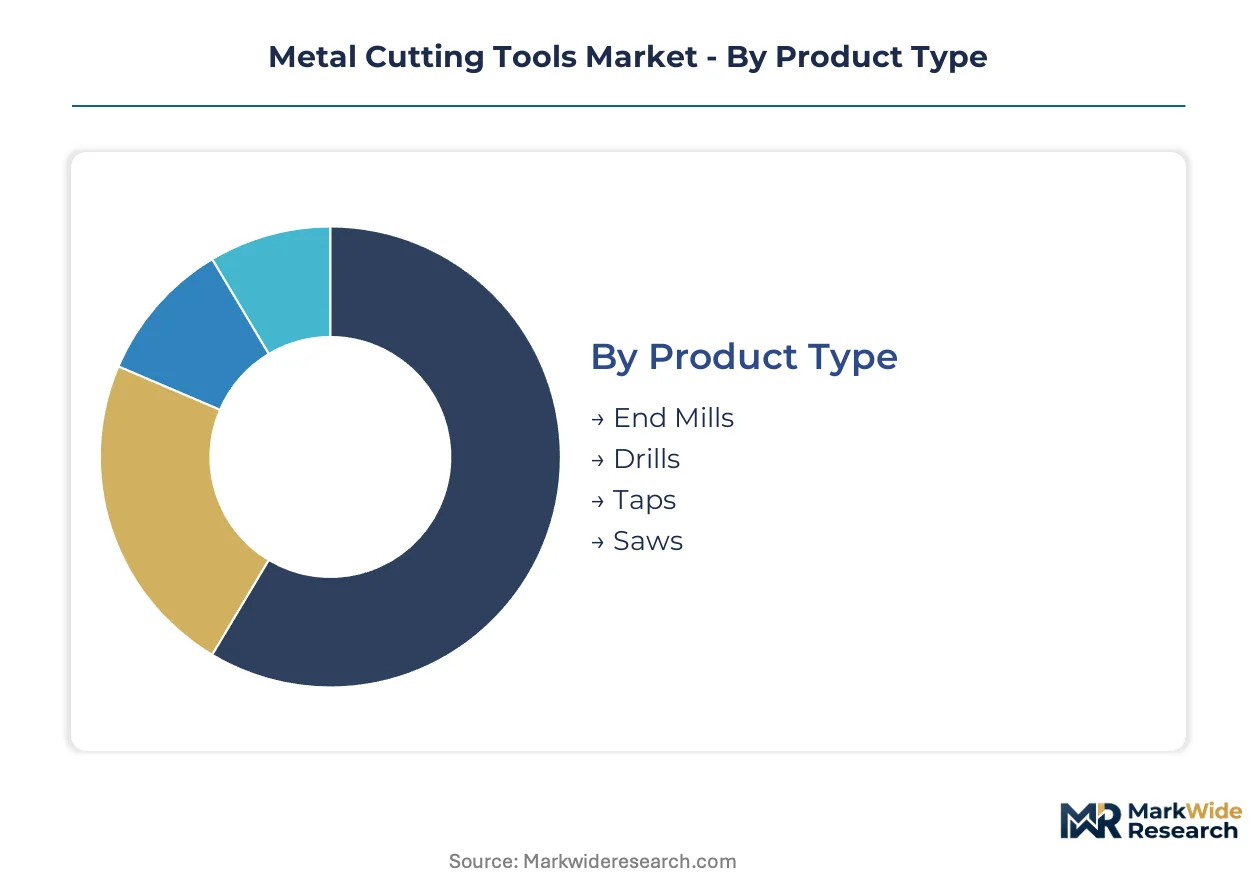
Metal cutting tool segmentation reveals how substrate engineering and dimensional specifications align with distinct manufacturing economics. Supply concentration in carbide powder processing and coating technology creates tiered performance categories that match specific alloy machining requirements.
Product Type:
End mills and drills concentrate the highest tooling inventory investment across precision machining facilities, with supply chains anchored by specialized insert foundries in Germany, Japan, and China.
- End Mills:Multi-flute rotating cutters machine profiles, slots, and complex contours in titanium and aluminum aerospace components. German aerospace manufacturers specify variable-helix geometries for chatter suppression in five-axis turbine blade machining.
- Drills:Indexable insert and solid carbide variants achieve hole tolerances within IT7-IT9 grades for automotive powertrain and hydraulic manifold applications. Yangtze River Delta machine tool clusters absorb high volumes for electronics enclosure production.
- Taps:Thread-forming and thread-cutting designs serve high-volume automotive fastener production, with powder metallurgy high-speed steel retaining cost advantages in regrindable applications.
- Saws:Circular and band saw blades handle bar stock and structural material cutoff, with carbide-tipped segments displacing bi-metal designs in continuous production environments.
End mills absorb the bulk of installed capacity; drills are expanding most quickly in electric vehicle powertrain machining applications.
Material:
Cost tier differentiation separates premium carbide substrates from regrindable high-speed steel, with cobalt and ceramic alternatives occupying narrow specialty niches.
- High-Speed Steel:M2, M35, and powder metallurgy grades retain economic viability in intermittent cutting, reaming, and tapping where tool replacement costs dominate cycle economics. Japanese machine shops specify these for small-batch die and mold work.
- Carbide:Cemented tungsten carbide with cobalt or nickel-iron binders delivers thermal stability above 800°C for continuous machining of nickel superalloys. REACH compliance mandates are accelerating nickel-binder validation across European supplier networks.
- Cobalt:Solid cobalt alloys and cobalt-enriched binders serve extreme heat applications in aerospace turbine disk roughing, though EU restrictions are compressing addressable market scope.
- Ceramics:Silicon nitride and whisker-reinforced alumina enable dry machining at speeds exceeding 1000 m/min in cast iron automotive brake rotor production.
Carbide commands the dominant production volume; ceramic inserts are climbing the fastest in high-speed aluminum machining for electric vehicle battery trays.
Application:
Application-driven segmentation concentrates value in aerospace and automotive, where material removal rates and surface finish requirements dictate premium tooling specifications.
- Aerospace:Titanium and nickel superalloy machining for engine components and airframe structures consumes coated carbide inserts at rates tenfold above aluminum applications. German and Japanese manufacturers specify multi-layer CVD-PVD hybrid coatings for turbine disk production.
- Automotive:Powertrain machining—cylinder heads, blocks, and transmission housings—drives high-volume indexable insert consumption. Electric vehicle motor housing aluminum machining is redirecting capacity from cast iron applications.
- Industrial Manufacturing:General machinery, fluid power, and industrial equipment production utilizes standard grades with emphasis on tool life predictability for unmanned operation.
- Construction:Structural steel and heavy equipment fabrication employs robust roughing tools with emphasis on edge toughness over dimensional precision.
Automotive absorbs the bulk of installed capacity; aerospace is gaining share fastest on value-per-unit metrics.
Size:
Dimensional scaling determines substrate material feasibility and machine tool spindle interface requirements across manufacturing facility tiers.
- Small:Tools under 6mm diameter serve electronics, medical device, and precision instrument machining, with solid carbide micro-grain substrates dominating due to rigidity requirements.
- Medium:6-25mm range covers the majority of automotive and general machining applications, balancing insert economy with chip evacuation capacity.
- Large:25-80mm tools handle heavy roughing in aerospace structural components and energy sector equipment, with modular shank systems reducing inventory carrying costs.
- Extra Large:Above 80mm diameter, custom fabricated cutters serve wind turbine hub, ship propeller, and mining equipment machining with extended lead times and dedicated application engineering.
Medium-size tools absorb the bulk of installed capacity; small-diameter instruments are expanding most quickly in electronics and medical device precision machining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten concentrate processing in Chinese facilities anchors raw material supply for cemented carbide production worldwide. Aerospace machining clusters in Germany and Japan concentrate premium tooling demand. Regulatory divergence across major manufacturing economies is fragmenting qualification requirements for cutting tool suppliers.
China
Yangtze River Delta machine tool manufacturers absorb high volumes of indexable inserts for automotive and electronics equipment production. MIIT promotes domestic machine tool digitization standards that interface with tool life monitoring systems. Zhengzhou and Xiamen house major carbide powder processing facilities that supply global toolmakers.
Germany
Aerospace engine component manufacturers specify multi-layer CVD-PVD hybrid coatings for titanium and nickel superalloy machining. REACH Annex XVII restrictions on cobalt compounds compel cemented carbide reformulation across supplier networks. Bavaria and Baden-Württemberg precision machining clusters drive consumption of heat-resistant coated inserts.
Japan
Electric vehicle powertrain machining is redirecting coated insert capacity toward aluminum motor housing and battery tray applications. METI digitization standards create interface specifications that favor domestic sensor-embedded tooling systems. Nagoya and Osaka manufacturing belts concentrate automotive and aerospace tooling demand.
United States
Tier-1 aerospace suppliers in the Midwest and Southeast are consolidating procurement through direct service contracts with carbide producers. OSHA enforces permissible exposure limits for metalworking fluids and airborne particulates that influence coolant system investments. Michigan and Ohio machining corridors absorb premium tooling for automotive powertrain production.
India
Automotive component manufacturing in Tamil Nadu and Maharashtra drives indexable insert consumption for powertrain machining. BIS certification requirements for cutting tools create qualification barriers for imported products. Pune and Chennai industrial clusters are expanding precision machining capacity for domestic and export automotive supply chains.
Metal Cutting Tools Market Vendor Landscape
Global majors compete with regional champions across coating technology and powder metallurgy capabilities. The vendor base separates into integrated carbide producers, specialized insert fabricators, and distribution-focused service providers. Strategic archetypes include captive tungsten processors, coating technology licensors, and application engineering specialists. Competitive moves concentrate on backward integration into carbide powder production and direct service contracting with Tier-1 aerospace accounts.
Among Japanese materials conglomerates, Mitsubishi Materials Corporation and Kyocera Corporation occupy positions emphasizing ceramic and carbide substrate integration. Swedish-headquartered Sandvik Coromant exemplifies the integrated model with captive powder operations. Kennametal anchors North American presence through direct technical service deployment. Iscar Ltd. represents the specialized modular tooling archetype with quick-change system expertise.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| Seco Tools AB |
| Sandvik Coromant |
| Walter AG |
| Iscar Ltd. |
| Kennametal |
| Kyocera Corporation |
| Ceratizit S.A. |
| Tungaloy Corporation |
| Others |
Supply Flow & Price Mechanics
Tungsten concentrate processing costs in Chinese facilities cascade through three distinct pricing tiers for cemented carbide inserts, with captive powder metallurgy operations at Sandvik Coromant and Kennametal insulating against raw material volatility that compresses margins for distributor-dependent competitors.
Pricing Analysis
Service bundling separates premium coated insert suppliers from commodity competitors, with Sandvik Coromant and Kennametal embedding application engineering and tool life guarantees into long-term contracts while unbundled transactional pricing dominates standard-grade indexable inserts. Price differentiation rests on coating technology tier and direct technical support availability. Cost compression in standard grades intensifies as Chinese carbide producers expand Yangtze River Delta capacity. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to productivity guarantee requirements, while general machining job shops prioritize per-insert economics.
Supply Chain Analysis
Specialized powder metallurgists in Germany and Japan face workforce constraints that limit binder formulation capacity for REACH-compliant cobalt alternatives. Raw material supply draws from tungsten concentrate processing in China, cobalt mining in the DRC, and nickel refining in Indonesia. Single-source vulnerability concentrates in Chinese tungsten concentrate supply exceeding 80% of global processing. Distribution runs through direct service contracts with Tier-1 aerospace accounts in the US Midwest and German Bavaria, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into carbide powder production and captive coating technology represents the decisive competitive lever, with regulatory pressure on hazardous materials accelerating the race to control upstream substrate formulation.
For Market Incumbents: Deepen captive tungsten supply arrangements to offset Chinese export quota volatility threatening European and North American production continuity. Expand in-house nickel-iron binder metallurgy capabilities ahead of EU REACH Annex XVII enforcement timelines. Defensive priority centers on qualifying alternative binder systems before cobalt restriction deadlines compress formulation windows. For New Entrants and Emerging Players: Launch via modular quick-change tooling systems targeting high-mix manufacturing segments underserved by integrated majors. White-space opportunity concentrates in sensor-embedded tooling compatible with Japan METI digitization standards. Target electric vehicle powertrain machining applications where aluminum motor housing demand outpaces established capacity allocation. For Investors and Strategic Acquirers: REACH compliance certification completion at European precision toolmakers is the leading indicator that acquisition timing has compressed toward regulatory deadline windows. Long-term viability favors producers with captive recycling infrastructure positioned for EU circular economy mandate expansion. Monitor cobalt-free cemented carbide qualification cycles as inflection signal for binder technology leadership transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Carbide Powder Production | Insulates Sandvik Coromant and Kennametal from Chinese tungsten export volatility. |
| Direct Service Contracting | Displaces distributor channels in US and German aerospace machining clusters. |
| Coating Technology Licensing | Accelerates multi-layer CVD-PVD hybrid adoption for nickel superalloy applications. |
| Carbide Insert Recycling Infrastructure | Positions European producers for EU circular economy take-back mandate compliance. |
| Sensor-Embedded Tooling Development | Aligns with Japan METI digitization standards favoring domestic interface specifications. |
Methodological Framework
Multi-period observation of carbide insert consumption patterns in German and Japanese aerospace clusters anchored the trend analysis, supplemented by interviews with application engineers at Tier-1 suppliers, procurement directors at automotive powertrain manufacturers, powder metallurgy specialists at cemented carbide producers, and aftermarket service managers at machine tool distributors. Secondary validation drew from SEC filings of listed toolmakers, EU REACH Annex XVII regulatory documentation, Japanese METI standardization notices, and US OSHA metalworking fluid exposure databases. Bottom-up segment sizing triangulated against top-down macroeconomic manufacturing indicators.
Segment-weighting across product type, material substrate, application end-use, and dimensional size categories structured the analytical framework across the analysis window. CAGRs derived from regression analysis of historical consumption patterns projected against machine tool installation forecasts and alloy-specific machining intensity coefficients. Industry-specific inputs included electric vehicle powertrain machining adoption curves and REACH compliance timeline assumptions for cobalt binder substitution.
The model assumes a particular technology adoption path for nickel-iron binder systems; alternative metallurgical pathways for cobalt-free cemented carbide would alter the outlook for European supplier qualification timelines. Forecasts reflect documented assumptions regarding tungsten supply concentration and regulatory enforcement intensity. Material deviation in REACH Annex XVII implementation schedules or Chinese export quota administration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Tools Market
Tools
Automotive Torque Tools Market
Tools
Handheld Engraving Machine Market
Tools
Tension Tester Market
Tools
Welding Products Market
Tools
Land Survey Equipment Market
Tools
Hydraulic Tools Market
Tools
Rebar Cutter Market
Tools
Scroll Saws Market
Tools
Step Ladder Market
Tools
Woodpecker Tools Market
Tools
Saw Blades Market
Tools
Mortiser Market
Tools
Power Press Machines Market
Tools
End Mill Holder Market
Tools
High-Speed Steel Metal Cutting Tools Market