
 Scroll Saws Market | 2026-2036
Scroll Saws Market Size, Share, and Industry Trends Forecast 2026-2036
Scroll Saws Market Analytics
Equipment leasing and pay-per-use workshop models are reshaping how small-scale woodworkers access scroll saws without capital outlay. DEWALT leverages its battery-platform ecosystem to anchor recurring accessory revenue. Grizzly specializes in direct-to-consumer distribution, controlling pricing and support channels. JPW Industries operates across multiple power-tool categories, extending manufacturing scale into scroll saw production.
A scroll saw is a reciprocating-blade cutting machine that uses thin, pinned or pinless blades moving at 400–1,800 strokes per minute to execute intricate internal and external contours in wood, plastic, and non-ferrous metals. Its primary commercial purpose is detailed fretwork, marquetry, and inlay production where bandsaws or jigsaws lack precision. Benchtop configurations dominate unit volume among home users, while variable-speed electric models capture margin pools in professional settings. Digital technology remains nascent but attracts educational institutions seeking programmable repeatability.
ISO 4875 governs blade geometry and safety interfaces, while OSHA machine-guarding standards in the United States and CE machinery directives in Europe shape product design and market access requirements. The EU Green Deal's ecodesign regulations pressure motor efficiency and material recyclability, filtering which suppliers can serve European buyers. Stakeholders must monitor whether digital control integration crosses into machinery cybersecurity compliance scope.
Market Dynamics
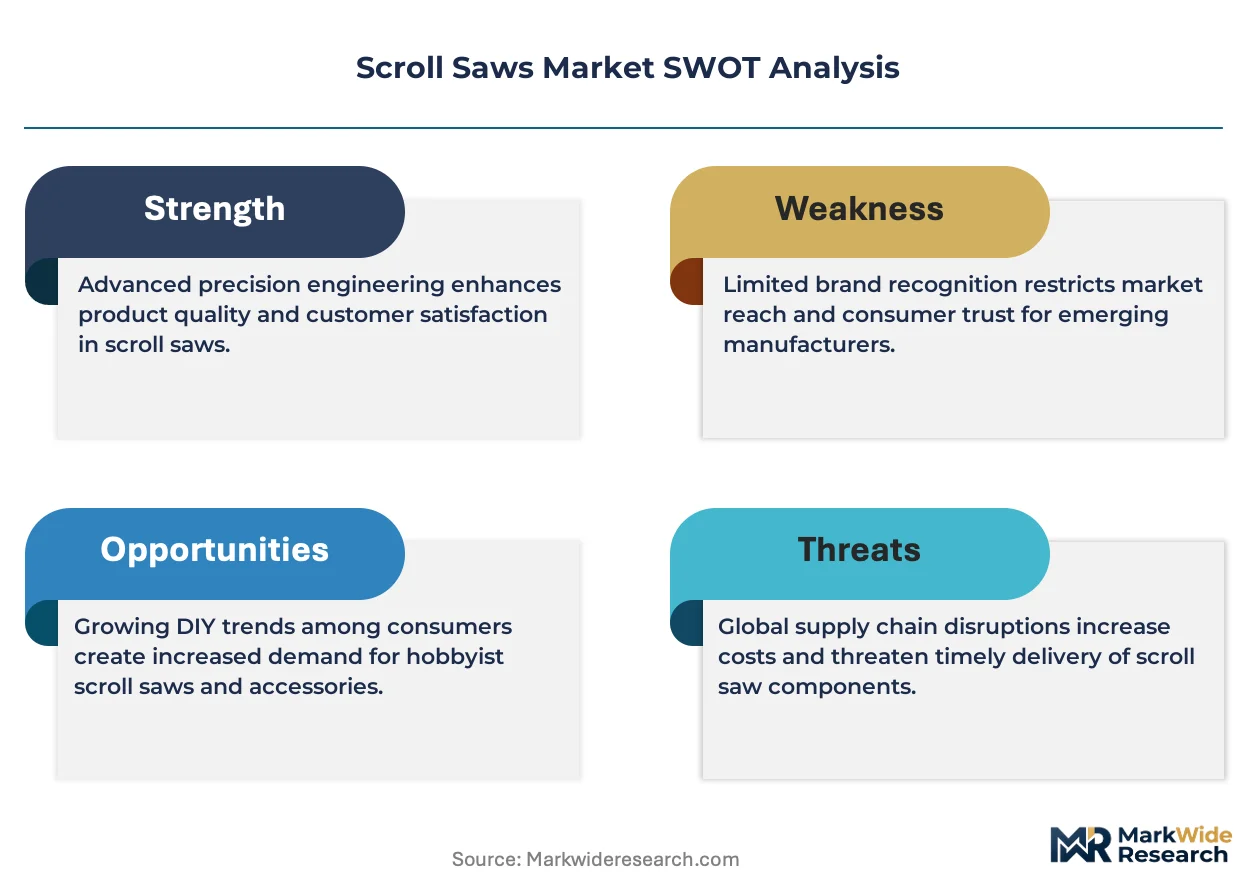
Battery-platform standardization is forcing scroll saw manufacturers to choose between proprietary ecosystems and universal compatibility, reshaping R&D allocation and margin structures across the power-tool value chain.
Growth Catalysts
- EU Green Deal ecodesign mandates:Motor efficiency regulations are accelerating brushless motor adoption in European-bound equipment, creating upgrade cycles among vocational training centers.
- Maker culture proliferation:Community workshops in Germany, China, and the United States are expanding equipment procurement for member-access programs.
- Lithium-ion energy density improvements:Extended runtime per charge is enabling cordless scroll saw deployment in mobile demonstration and field repair applications previously served by corded units.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet dependency on Chinese processing infrastructure creates input cost volatility for brushless motor production.
- OSHA machine-guarding compliance:Blade exposure mitigation requirements add engineering cost and limit compact form-factor feasibility for benchtop models.
- Laser cutting substitution:Fiber and CO2 laser systems are capturing high-volume fretwork applications where tolerances permit non-mechanical processing.
Strategic Opportunities
- Vocational curriculum mandates:German and Chinese secondary technical education investments are creating institutional procurement pipelines for programmable, repeatable equipment.
- Equipment-as-a-service models:Pay-per-use workshop networks in the United States are reducing capital barriers for hobbyist entry and expanding addressable user bases.
- Digital-physical convergence:CAD-to-cut workflow integration between design software and scroll saw control interfaces is attracting educational technology budgets.
Industry Challenges
- Blade geometry expertise scarcity:Specialized knowledge of pinned versus pinless blade selection and tension calibration is diminishing among retail sales staff, complicating customer support.
- CE machinery directive certification timelines:Extended conformity assessment procedures for electronic speed control modules delay European market entry for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scroll Saws Market |
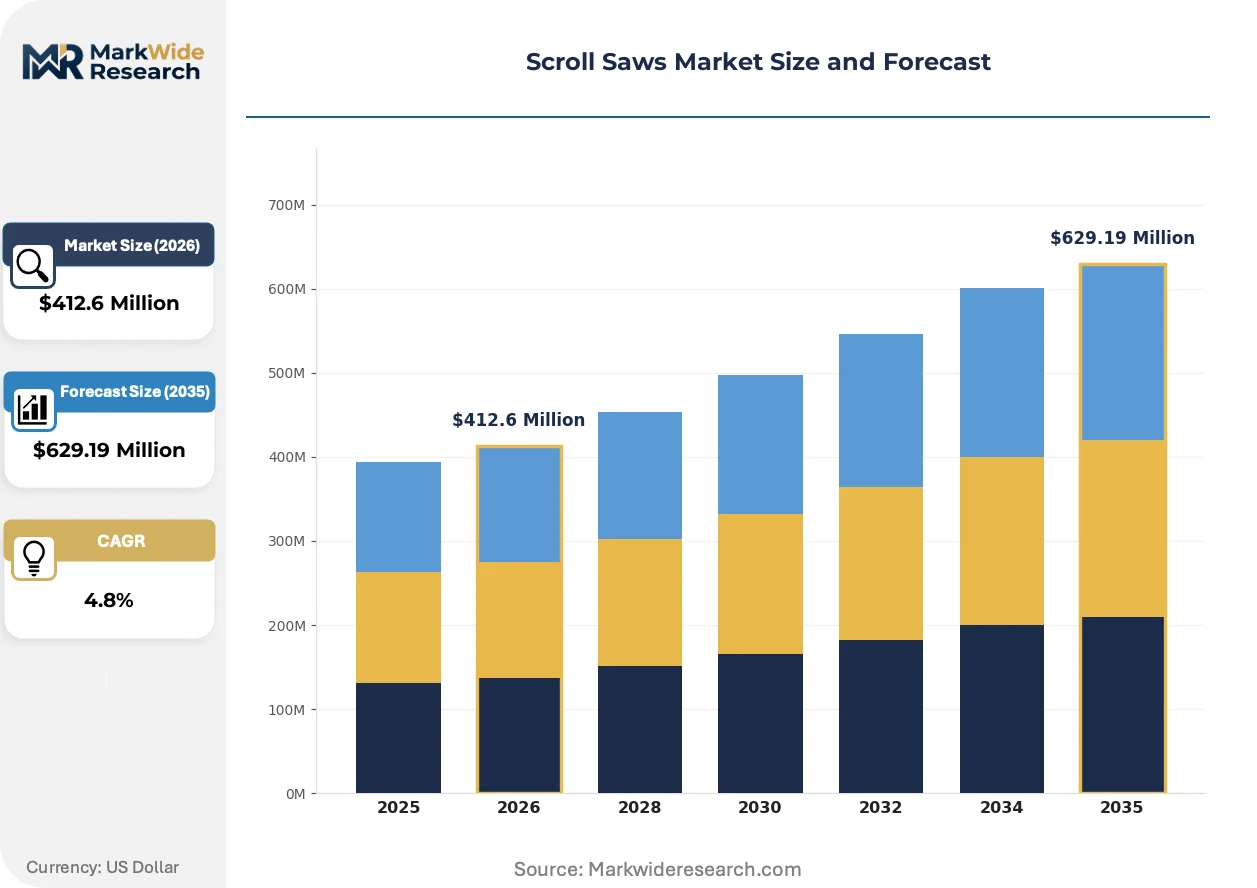
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Portable, Stationary, Variable Speed End User: Home Users, Professionals, Educational Institutions, Artisans Application: Woodworking, Crafting, Model Making, Upholstery Technology: Electric, Manual, Digital, Hybrid |
| Companies Covered | WEN Products, Grizzly, Delta, Performance 1, SEG, DEWALT, JPW Industries, Woodcraft, Dremel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scroll Saws Market Evolving Landscape
Scroll saw technology trajectories center on electrification architecture, regulatory compliance automation, and access-model disruption that separates equipment ownership from utilization.
Brushless DC motor platforms are virtualizing the traditional power transmission stack by eliminating brush wear maintenance and enabling software-defined speed curves. Vocational programs in Germany and China are standardizing on these configurations to reduce downtime in high-throughput training environments. The technology is virtualizing aftermarket parts revenue streams as sealed motor units reduce consumable replacement frequency.
EU Green Deal ecodesign regulations are mandating minimum motor efficiency thresholds and material recyclability disclosures for machinery placed on the European market. Manufacturers must redesign housings and control electronics to satisfy extended producer responsibility frameworks. Professional-grade equipment with modular, serviceable construction is capturing preference share among institutional buyers subject to public procurement sustainability criteria.
Subscription-based workshop access is displacing individual equipment ownership among urban woodworking hobbyists in the United States and Germany. Makerspace networks are unbundling machine time from capital commitment, compressing the traditional retail sales cycle. This pattern concentrates demand in metropolitan clusters where real estate constraints already limit home workshop feasibility.
Scroll Saws Market Segmentation
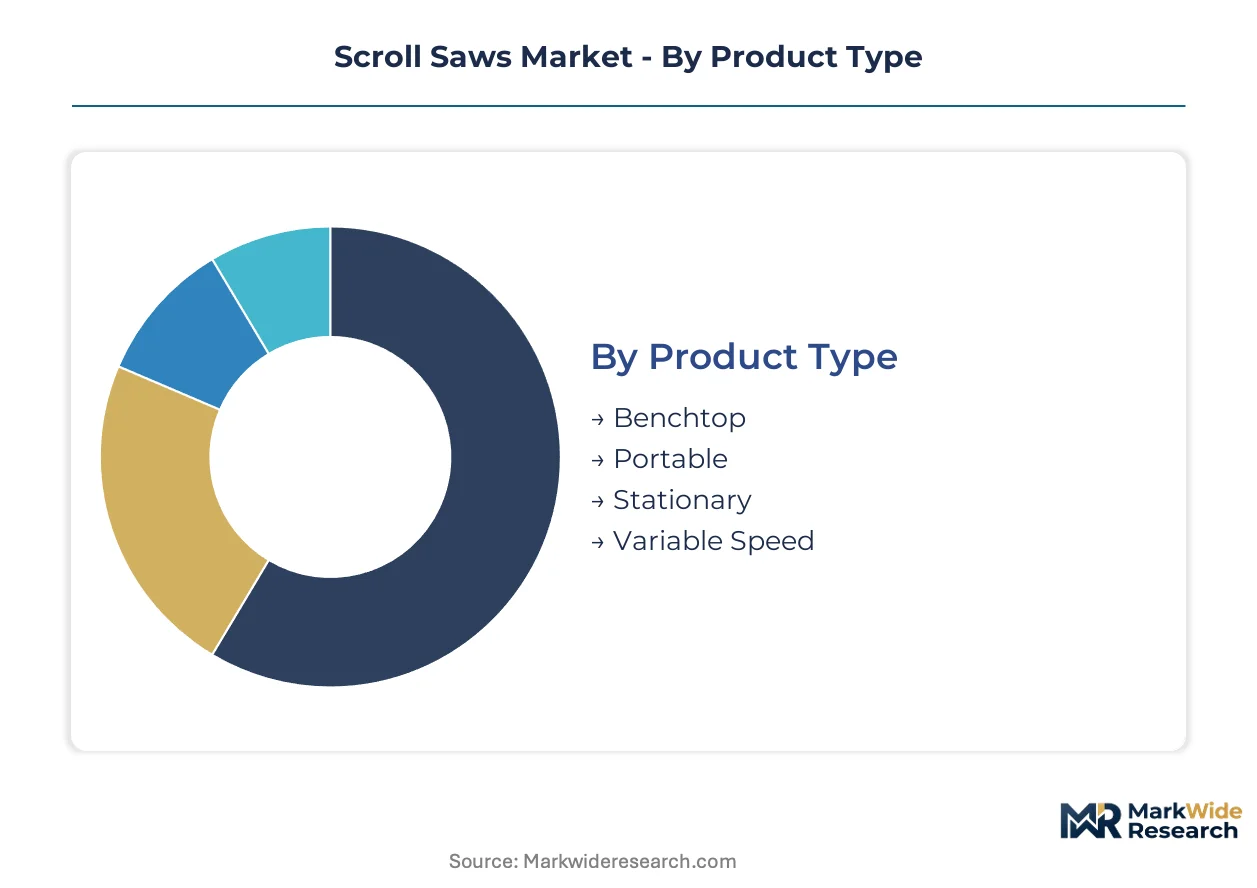
Scroll saw segmentation reveals divergent equipment specifications across user sophistication levels. Product architecture, power delivery, and precision requirements fragment procurement patterns between hobbyist entry points and institutional repeatability mandates.
Product Type:
Mature benchtop configurations dominate unit economics while emerging cordless platforms reshape portability expectations.
- Benchtop:Fixed-position machines with cast-iron or aluminum tables ranging from 16 to 20 inches throat depth anchor residential workshop installations. Home users in the United States concentrate demand here, driven by space-constrained garage workshops where permanent mounting replaces floor-standing alternatives.
- Portable:Compact units under 25 pounds with folding stands or carry handles serve mobile demonstration and field repair applications. Lithium-ion energy density improvements from suppliers like Samsung SDI and LG Chem enable cordless deployment for makerspace educators conducting off-site vocational training.
- Stationary:Floor-standing frames with 30-plus inch throat depths and integrated dust collection serve production marquetry shops.
- Variable Speed:Electronic control modules enabling 400–1,800 strokes per minute adjustment capture margin pools in professional settings requiring material-specific blade optimization.
Benchtop retains volume leadership; portable holds the steepest expansion curve.
End User:
Customer type segmentation tracks equipment durability requirements against utilization intensity and technical support expectations.
- Home Users:Occasional-use hobbyists operating fewer than 10 hours monthly prioritize price accessibility over serviceability. German and Chinese online marketplaces concentrate this demand, where direct-to-consumer brands like Grizzly bypass retail margin stacking.
- Professionals:Full-time woodworkers and restoration specialists demand sealed-bearing systems and rapid blade change mechanisms. OSHA machine-guarding compliance adds engineering cost that filters smaller suppliers from this tier.
- Educational Institutions:Vocational programs in Germany and China standardize on brushless motor platforms to minimize maintenance downtime in high-throughput training environments.
- Artisans:Marquetry and inlay specialists requiring pinless blade compatibility for ultra-intricate fretwork represent a premium niche with extended replacement part procurement cycles.
Home users command absolute unit volume; educational institutions drive the fastest specification upgrade cycles.
Application:
Use-case segmentation aligns blade geometry selection with material thickness and contour complexity tolerances.
- Woodworking:Primary commercial purpose spanning hardwood furniture components to softwood decorative trim. Makerspace networks in the United States concentrate equipment procurement here for member-access programs serving urban hobbyists without home workshop space.
- Crafting:Thin-stock processing for jewelry, ornaments, and seasonal decorations demands minimal throat depth with maximum precision. Chinese export manufacturers supply this segment through Alibaba and Temu channels.
- Model Making:Architectural and scale-model construction requires sub-millimeter tolerance repeatability attracting digital control integration from educational technology budgets.
- Upholstery:Foam and fabric cutting applications utilize specialized skip-tooth blades with aggressive tooth geometry for compressible materials.
Woodworking retains volume leadership; model making climbs the fastest on CAD-to-cut workflow integration.
Technology:
Power delivery architecture segmentation tracks electrification maturity against manual precision preservation and digital convergence.
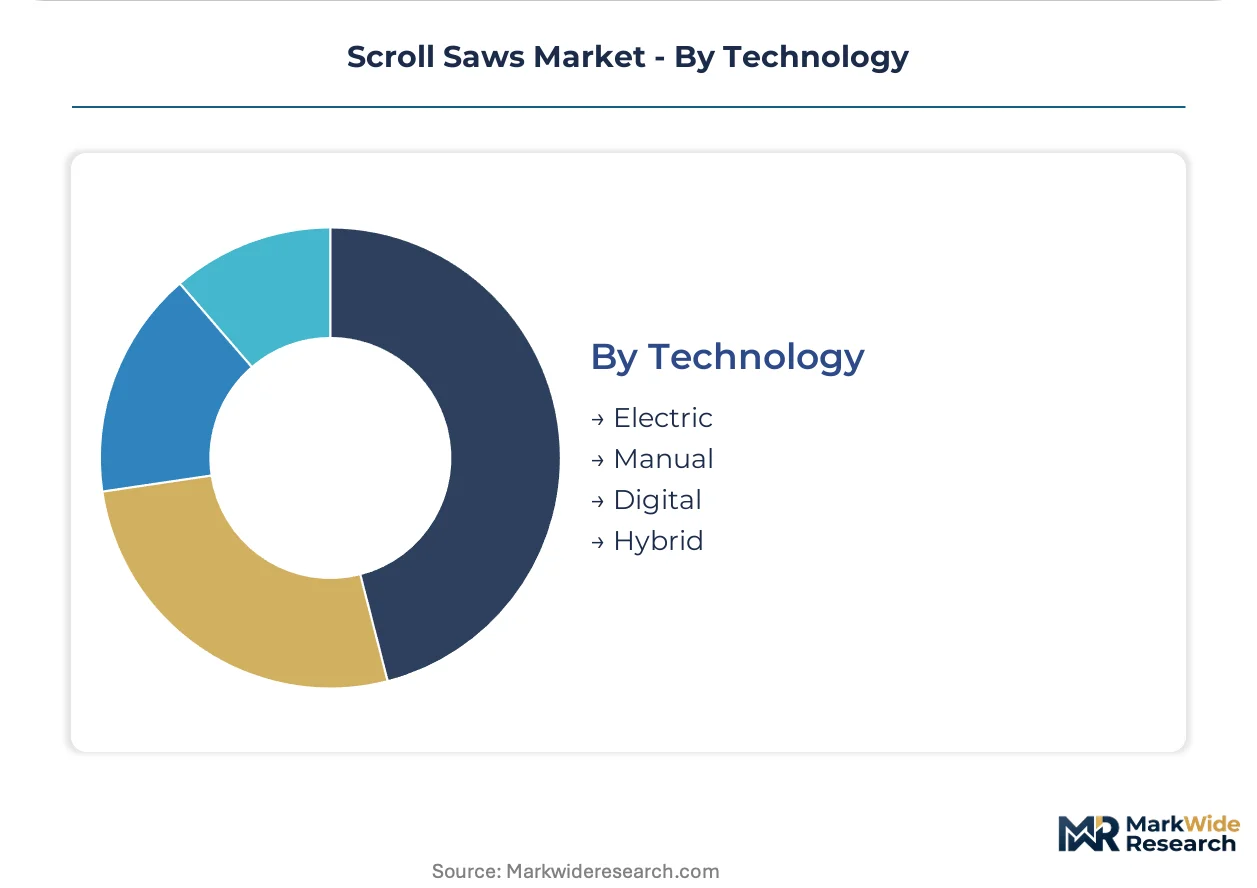
- Electric:AC-powered induction motors and DC brushless platforms constitute the installed base majority. EU Green Deal ecodesign regulations mandate minimum efficiency thresholds that filter non-compliant suppliers from European market access.
- Manual:Spring-powered or treadle-operated mechanisms persist in heritage craft preservation and off-grid workshop scenarios. Artisan communities in Germany maintain niche demand for traditional marquetry instruction.
- Digital:Programmable speed curves, stroke counting, and Bluetooth-connected maintenance alerts attract institutional procurement from vocational curricula seeking repeatable training outcomes. CE machinery directive certification timelines delay European market entry for new electronic control introductions.
- Hybrid:Manual frames with retrofitted DC motor kits serve cost-sensitive upgraders bridging traditional craft and modern convenience.
Electric retains volume leadership; digital gains share fastest on vocational standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases in Germany and China, while the United States absorbs the largest import volume for consumer-grade equipment. Trade flows concentrate on precision-engineered components from European suppliers and cost-optimized benchtop units from Asian production centers.
United States
Makerspace networks in Austin, Brooklyn, and Portland drive institutional procurement for member-access woodworking programs. OSHA machine-guarding standards enforce blade exposure mitigation requirements that filter non-compliant imports from retail channels. Chicago and Los Angeles anchor distribution hubs where vocational training centers source brushless motor platforms for high-throughput educational environments.
Germany
EU Green Deal ecodesign regulations accelerate brushless motor adoption among vocational training centers in Bavaria and North Rhine-Westphalia. CE machinery directive certification timelines delay market entry for electronic speed control modules from non-European suppliers. Stuttgart and Hamburg concentrate artisan marquetry workshops sustaining demand for pinless blade compatibility and heritage craft preservation equipment.
China
Dual carbon goals under MEE oversight pressure motor efficiency improvements in export-bound manufacturing. Domestic vocational curriculum investments in Guangdong and Jiangsu provinces create institutional procurement pipelines for programmable equipment. Shenzhen and Dongguan clusters dominate cost-optimized benchtop production serving North American and European consumer markets through direct-to-consumer channels.
Japan
METI efficiency standards shape premium-tier product specifications for professional woodworkers in Tokyo and Osaka metropolitan areas. JIS certification requirements filter entry-level imports from neighboring Asian suppliers. Nagoya anchors precision component manufacturing for brushless motor systems deployed in educational technology budgets.
United Kingdom
Post-Brexit UKCA marking requirements diverge from CE machinery directives, creating separate conformity assessment costs for European suppliers. Community workshop expansion in London and Manchester concentrates demand for subscription-based equipment access models. Birmingham retains specialized distribution for restoration specialists requiring sealed-bearing systems and rapid blade change mechanisms.
Scroll Saws Market Competitive Landscape
On the supply side, the industry is moderately consolidated around power-tool conglomerates with cross-category manufacturing scale and direct-to-consumer specialists controlling pricing autonomy. Strategic archetypes include battery-platform ecosystem builders, direct-to-consumer fabricators, and multi-category industrial tool suppliers. Competitive moves center on proprietary battery compatibility lock-in and vocational curriculum standardization partnerships.
Among North American power-tool conglomerates, DEWALT and Delta occupy positions anchoring battery-platform ecosystem strategies. Grizzly exemplifies the direct-to-consumer archetype with controlled support channel integration. JPW Industries represents multi-category industrial scale extension into scroll saw production.
| Leading Market Players |
|---|
| WEN Products |
| Grizzly |
| Delta |
| Performance 1 |
| SEG |
| DEWALT |
| JPW Industries |
| Woodcraft |
| Dremel |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese benchtop scroll saw manufacturing is compressing export pricing while simultaneously accelerating supplier consolidation around brushless motor specialists. This utilization imbalance rewards vertically integrated producers with captive neodymium magnet sourcing and pressures pure-play assemblers toward margin erosion or exit.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on brushless motor certification grade and CE machinery directive compliance status. Cost compression in the economy tier is intensifying because of neodymium price volatility and tariff exposure on Chinese-sourced control electronics. Home users exhibit the highest price sensitivity, while educational institutions prioritize total cost of ownership over upfront equipment cost.
Supply Chain Analysis
Neodymium rare-earth processing feeds from Chinese refining infrastructure, with secondary concentration in Japanese magnet fabrication and German motor assembly. Raw material dependencies center on lithium-ion cells from Samsung SDI and LG Chem, aluminum castings from Guangdong foundries, and precision blade steel from Solingen workshops. Single-source vulnerability in Chinese rare-earth processing creates supply chain risk. Distribution runs through direct-to-consumer channels for hobbyist tiers and vocational equipment distributors for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor platform standardization is accelerating market disruption, with EU Green Deal ecodesign mandates compressing upgrade cycles and rewarding early compliance investments.
For Market Incumbents: Build certification moats by securing CE machinery directive pre-approval for electronic speed control modules ahead of competitors. Deepen backward integration into brushless motor production to offset neodymium cost volatility. Lock in vocational curriculum partnerships in Germany and China to anchor institutional demand against emerging cordless entrants. For New Entrants and Emerging Players: Build out subscription-based workshop access models in underserved US metropolitan markets where real estate constraints limit home workshop feasibility. Target the portable cordless segment where lithium-ion energy density improvements are displacing corded legacy units. Pursue direct-to-consumer positioning through controlled e-commerce channels to bypass retail margin stacking. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer specialists with proprietary blade geometry expertise and integrated support infrastructure. Long-term viability over a multi-year horizon favors suppliers with vocational standardization partnerships and modular serviceable construction. Monitor CE machinery directive certification backlog as an inflection indicator for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Proprietary lithium-ion ecosystems from DEWALT lock in recurring accessory revenue and filter non-compatible competitors. |
| CE Machinery Directive Pre-Certification | Early electronic speed control module approval accelerates European market entry ahead of conformity assessment delays. |
| Vocational Curriculum Partnership | German and Chinese technical education standardization creates institutional procurement pipelines with multi-year visibility. |
| Direct-to-Consumer Channel Control | Grizzly's owned support infrastructure eliminates retail margin stacking and enables dynamic pricing responsiveness. |
| Brushless Motor Backward Integration | In-house neodymium magnet sourcing mitigates Chinese processing concentration risk and stabilizes input cost structures. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at vocational training centers, procurement leads at makerspace networks, aftermarket service heads at power-tool distributors, and R&D directors at motor manufacturers and refined through secondary validation against customs trade data, SEC 10-K filings, EU ecodesign regulatory filings, and OSHA machine-guarding compliance records. Bottom-up equipment unit economics were triangulated with top-down addressable market sizing across hobbyist, professional, and institutional demand pools.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by benchtop, portable, stationary, and variable speed configurations alongside end-user tiers and power delivery technology maturity. CAGRs were derived from installed base replacement cycles and vocational curriculum investment trajectories. Key forecast inputs included lithium-ion energy density improvement curves and EU Green Deal implementation timelines for motor efficiency thresholds.
Stress conditions across neodymium price volatility bands, CE certification delay scenarios, and makerspace network expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about brushless motor adoption velocity and institutional procurement standardization. Cross-checking against vocational equipment distributor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Sanders Market
Tools
Deburring Tool Market
Tools
Impact Sockets Market
Tools
Drill Set Market
Tools
Entrenching Tool Market
Tools
Drilling Tools Market
Tools
Air Drills Market
Tools
US Chalk Reel and Line Market
Tools
Boring-Milling Machines Market
Tools
Telescopic Tool Boxes Market
Tools
Sanding Machine Market
Tools
Spindle Shaper Market
Tools
Broaching Tools Market
Tools
Electric Power Tools Market
Tools
Book Binding Machines Market
Tools
Cold and Hot Tool Steel Market