
 Welding Products Market | 2026-2036
Welding Products Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Products Market Intelligence
Specialized European and Japanese manufacturers' production strategy is decoupling from reliance on single-source component suppliers. This shift aims to build supply chain resilience against regional disruptions. Lincoln Electric Holdings, Inc. leverages its extensive distribution network to maintain presence across North America. Concurrently, Kemppi Oy specializes in advanced arc welding solutions for demanding industrial applications, particularly in the European market.
Welding products encompass the equipment and consumables that join materials like steel and aluminum through processes involving heat and pressure. Their industrial purpose is the fabrication, repair, and assembly of structures, utilizing energy sources from electric arcs with specific electrode fluxes to high-powered lasers. While arc welding equipment constitutes the largest product type segment, automated welding systems are seeing significant investment. The automotive and aerospace application segments drive demand for high-precision technologies.
Product design is influenced by regional safety standards, with OSHA in the US focusing on operator safety and the EU's CE marking mandating performance criteria. These regulations, along with China's GB standards, shape equipment features and market entry requirements. Navigating this fragmented regulatory environment requires a strategic choice between developing multi-standard platforms or specializing in region-specific product lines.
Market Dynamics
The market's central dynamic is the industrial push for automation to address skilled labor shortages and meet higher precision demands from sectors like automotive and aerospace for joining advanced lightweight materials.
Growth Catalysts
- Automation in Shipbuilding:Large-scale naval and commercial projects in China and South Korea require automated welding to improve productivity and meet strict delivery schedules for massive vessel construction.
- Aerospace Material Demand:The fabrication of components from titanium and advanced aluminum alloys drives adoption of precision technologies like laser and electron beam welding for defect-free joints.
- Infrastructure Modernization:Global initiatives to upgrade bridges, pipelines, and railways necessitate advanced welding for ensuring structural integrity and long-term durability against environmental stress.
Market Restraints
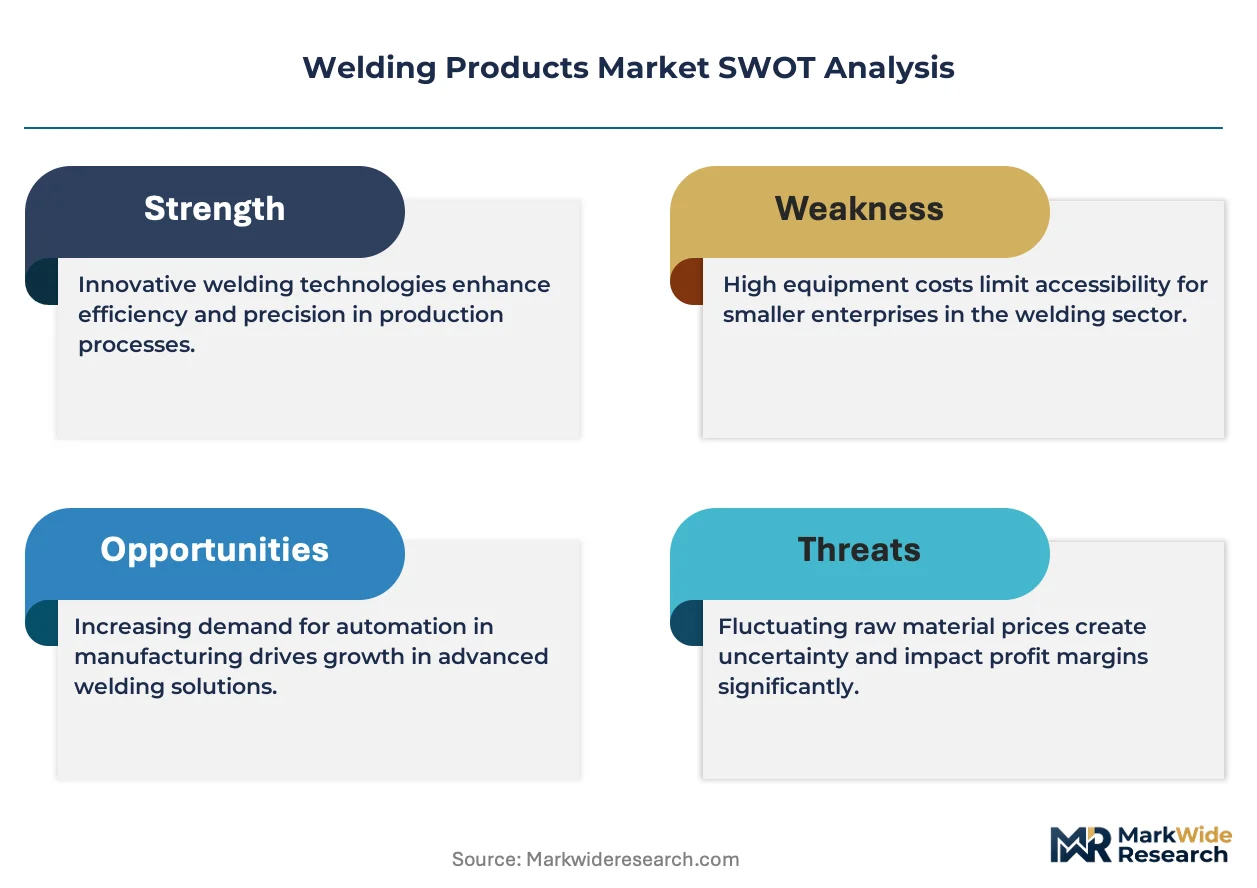
- Input Cost Volatility:Price fluctuations for raw materials like steel plate and consumables such as shielding gases and alloy filler metals create significant margin pressure.
- Regulatory Fragmentation:Adhering to disparate safety standards from OSHA, the EU's CE marking, and China's GB standards complicates global product development and market access.
- Adhesive Substitution:High-strength structural adhesives are a growing alternative for joining lightweight composites in automotive body-in-white applications, displacing some welding tasks.
Strategic Opportunities
- Renewable Energy Sector:The fabrication of wind turbine towers and offshore oil and gas foundations demands heavy-duty automated and submerged arc welding systems.
- Software-Enabled Services:Weld process monitoring and data logging software offers new subscription-based revenue streams beyond traditional, cyclical equipment sales.
- Additive Manufacturing:Wire Arc Additive Manufacturing (WAAM) opens applications for rapid prototyping and on-site repair of large metal parts in heavy industry.
Industry Challenges
- Skilled Labor Shortage:A persistent deficit of certified welders and technicians qualified to program and maintain robotic welding systems constrains the pace of industrial automation.
- High Capital Outlay:The substantial initial investment required for robotic welding systems and high-power laser sources can be a barrier for small and medium-sized enterprises (SMEs).
- System Integration Complexity:Integrating new automated welding cells with legacy factory networks and enterprise resource planning systems remains a significant technical hurdle for adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Products Market |
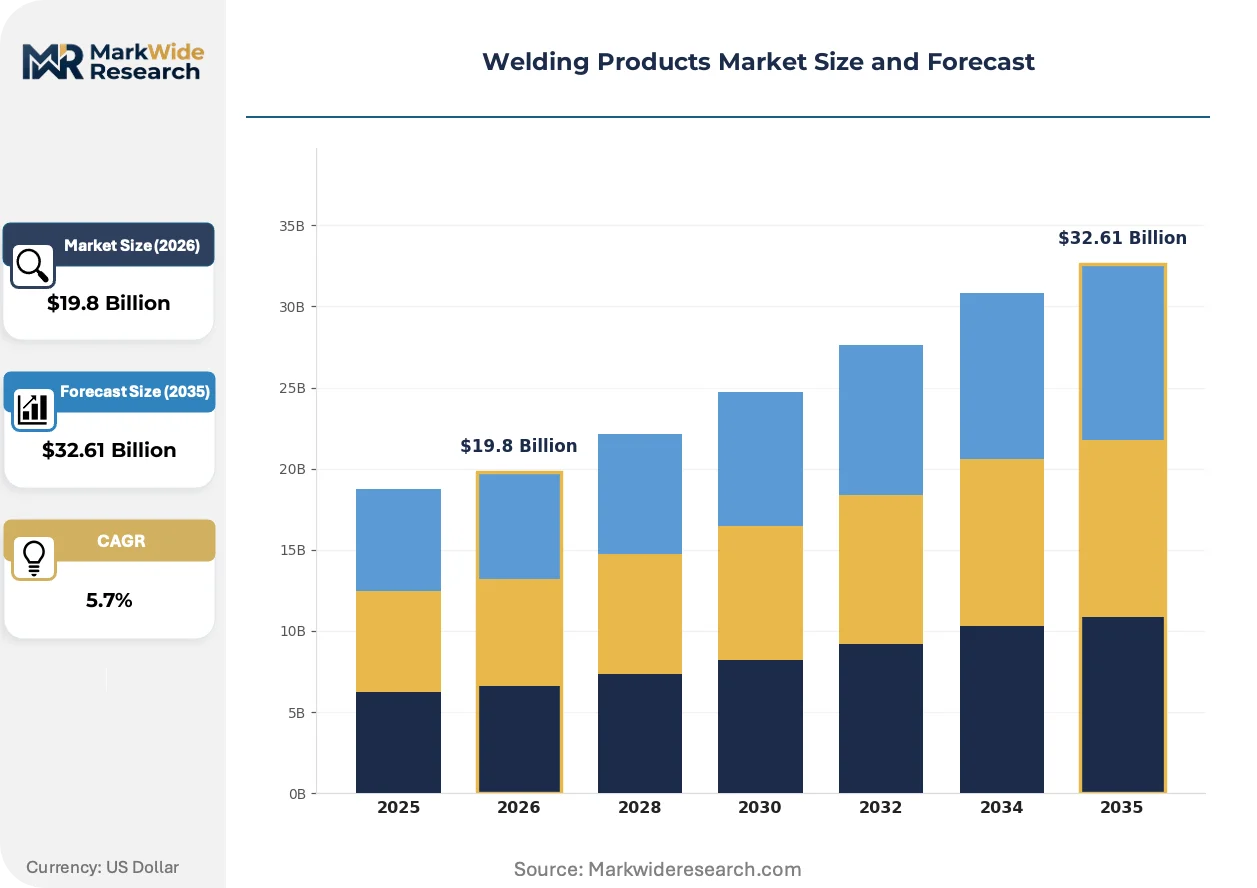
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Welding Equipment, Resistance Welding Equipment, Plasma Cutting Equipment, Gas Welding Equipment Application: Construction, Automotive Manufacturing, Aerospace Industry, Shipbuilding End User: Fabricators, Construction Firms, Manufacturing Plants, Repair Shops Technology: Automated Welding Systems, Manual Welding Techniques, Hybrid Welding Solutions, Laser Welding Technology |
| Companies Covered | Fronius International GmbH, AMADA WELD TECH Inc., Lincoln Electric Holdings, Inc., Kemppi Oy, Daihen Corporation, ESAB, Hobart Welding Products, Miller Electric Mfg. LLC, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Products Market Strategic Shifts & Innovations
A fundamental shift toward data-driven processes is defining the next generation of welding technology. This evolution moves beyond simple automation, focusing on intelligent systems that use real-time data to optimize quality, ensure consistency, and reduce material waste.
Digital twin technology for welding processes creates virtual models to simulate and optimize parameters before physical execution. Automotive and aerospace manufacturers adopt this to reduce costly trial-and-error prototyping. This approach is consolidating process design, simulation, and quality assurance into a single digital workflow, shortening development timelines for complex assemblies.
European Union regulations, particularly the updated Machinery Regulation, are intensifying focus on operator health and safety. These rules mandate more effective fume extraction and promote ergonomic designs to reduce worker strain. Consequently, equipment manufacturers are engineering integrated fume capture solutions and lightweight torches to comply with stricter CE marking criteria in the EU.
Service-based models augment traditional capital equipment sales, especially for automated systems. Customers are exploring contracts based on uptime or weld-per-part, shifting financial risk to the equipment provider. This trend, most visible in North American automotive manufacturing, favors suppliers offering IoT-enabled remote monitoring and predictive maintenance.
Welding Products Market Segmentation
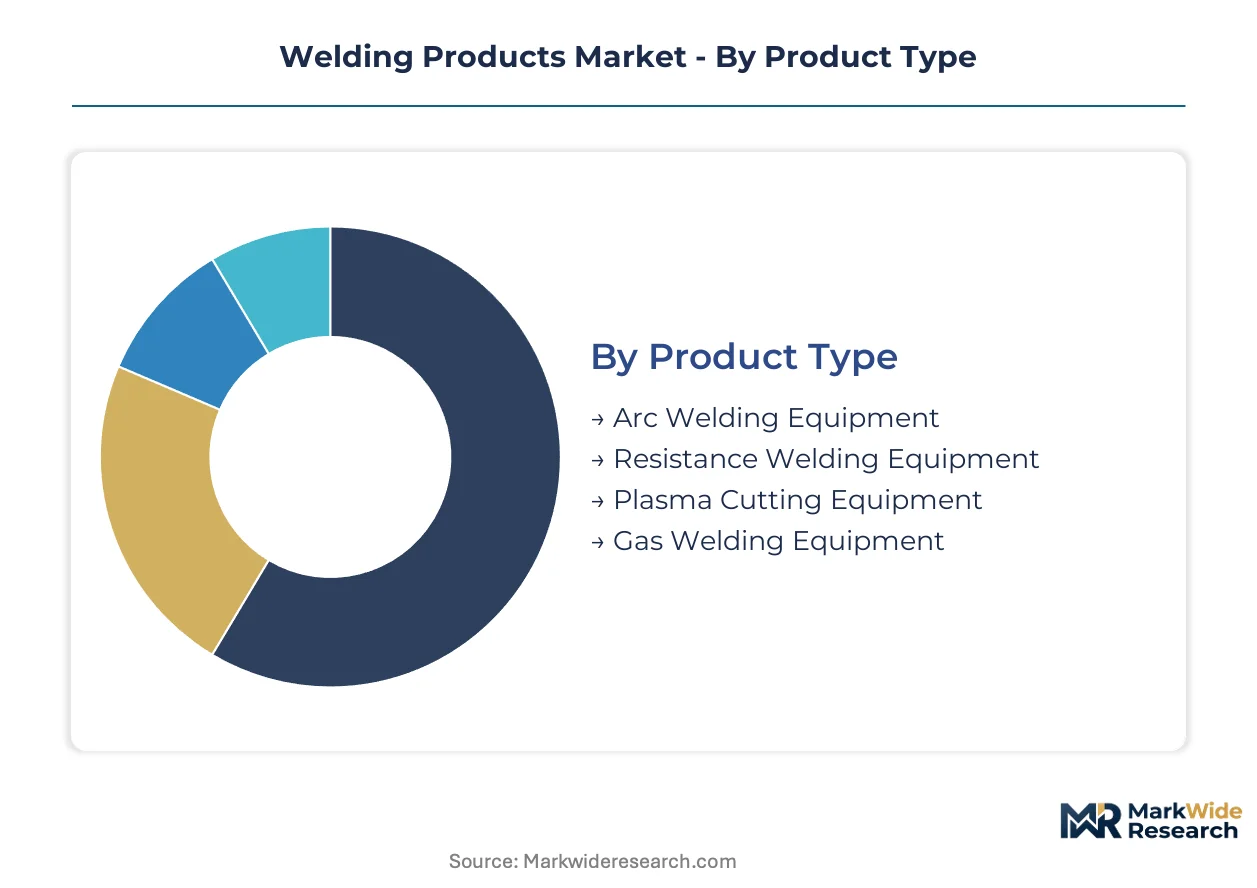
Understanding the Welding Products Market through segmentation reveals how capital intensity, application-specific demands, and technological advancements shape procurement strategies. This structured view helps identify where investment is concentrated and where specialized solutions are gaining traction across diverse industrial landscapes.
Product Type:
The capital expenditure required for welding equipment varies significantly across product types, with advanced systems demanding substantial upfront investment from manufacturing plants.
- Arc Welding Equipment:This category includes various processes like Shielded Metal Arc Welding (SMAW) and Gas Metal Arc Welding (GMAW), known for their versatility and widespread use across fabrication and construction. Demand concentrates in the shipbuilding sector, where large-scale structural joining requires robust and efficient processes.
- Resistance Welding Equipment:This equipment joins metals by applying pressure and passing a current through the joint, commonly used for spot and seam welding in high-volume production lines. The automotive manufacturing sector drives demand for resistance welding to achieve precise and strong bonds in vehicle body assembly.
- Plasma Cutting Equipment:Plasma cutting systems utilize an accelerated jet of hot plasma to cut through electrically conductive materials like steel and aluminum. Fabricators and repair shops employ these systems for their speed and ability to cut various metal thicknesses.
- Gas Welding Equipment:This equipment, including oxy-fuel welding and cutting, uses a fuel gas and oxygen to heat and join metals, often favored for maintenance, repair, and artistic metalwork.
Most installed capacity flows through Arc Welding Equipment. Expansion is steepest in Resistance Welding Equipment.
Application:
Application segments dictate the level of precision and material compatibility required from welding products, influencing technology adoption and specialized equipment demand.
- Automotive Manufacturing:This segment demands high-precision welding solutions for joining lightweight alloys such as aluminum and high-strength steels, crucial for vehicle weight reduction and fuel efficiency. The push for electric vehicles further accelerates the adoption of advanced joining technologies.
- Aerospace Industry:Aerospace applications require defect-free welds in exotic materials like titanium and advanced superalloys, driving the adoption of highly controlled processes such as laser and electron beam welding for critical structural components. Stringent safety standards from the FAA influence technology choices.
- Construction:The construction sector utilizes welding for structural steel frameworks, bridges, and infrastructure projects, emphasizing durability and strength in large-scale fabrication.
- Shipbuilding:Shipbuilding requires robust welding solutions for constructing hulls and complex internal structures, often involving automated processes to manage large volumes of steel.
Automotive Manufacturing consistently drives innovation in welding technology. Aerospace Industry applications require the most stringent quality assurance.
End User:
The scale and nature of operations for different end-users significantly impact their procurement patterns and the types of welding products they require.
- Manufacturing Plants:These facilities demand high-volume, often automated, welding solutions for continuous production lines, prioritizing throughput and consistency. The automotive sector's assembly plants represent a major consumer of automated systems.
- Fabricators:Fabrication shops perform custom metalwork and structural assembly for various industries, requiring versatile welding equipment capable of handling diverse materials and project specifications. Small and medium-sized enterprises often comprise this segment.
- Construction Firms:Construction companies utilize welding for on-site structural assembly and repair, often requiring portable and robust equipment suitable for outdoor and challenging environments.
- Repair Shops:Repair shops focus on restoring damaged metal components and structures, needing flexible welding tools for a variety of materials and repair tasks.
Manufacturing Plants represent the largest volume consumers of welding consumables. Fabricators exhibit the most diverse equipment needs.
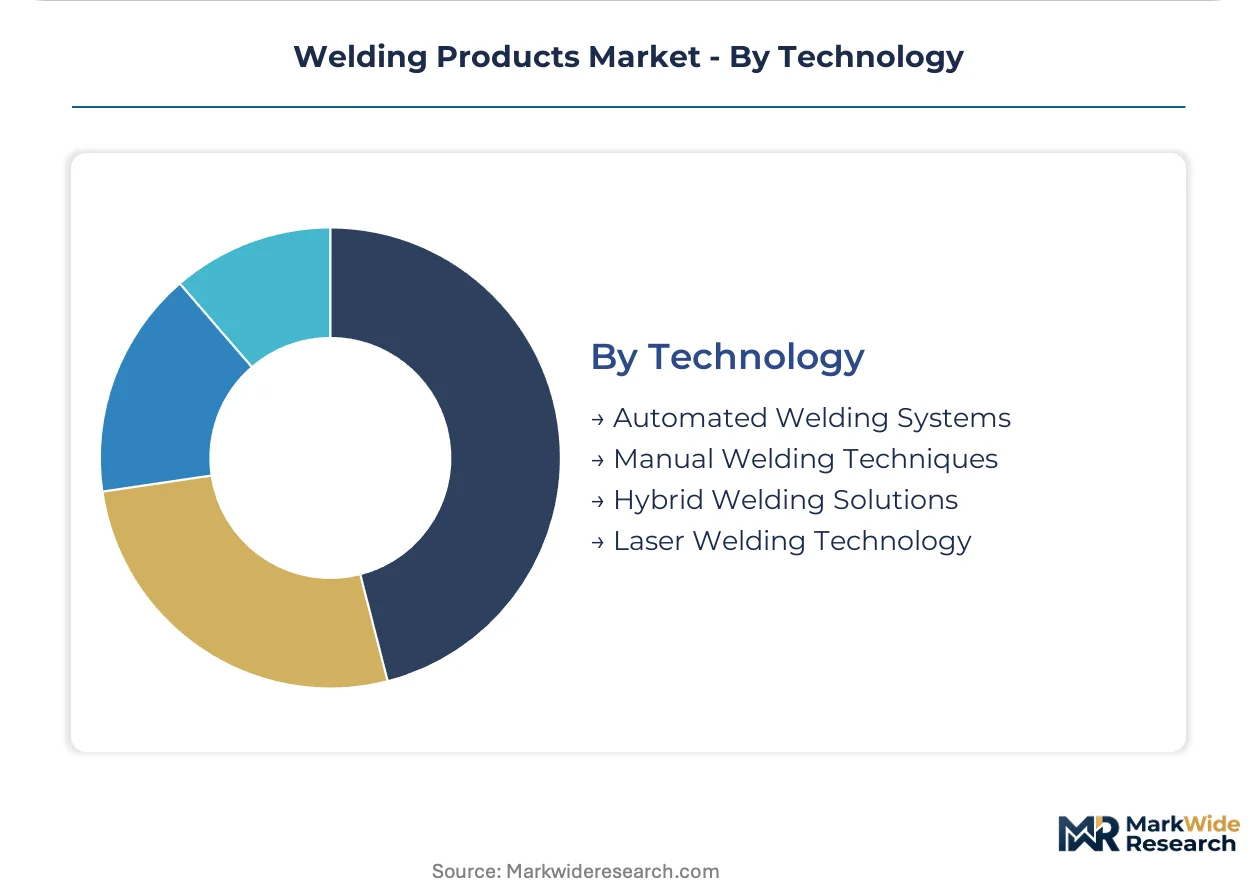
Technology:
Investment in welding technology is driven by the need for increased precision, productivity, and solutions to skilled labor shortages across various industrial sectors.
- Automated Welding Systems:These systems, including robotic and mechanized solutions, address skilled labor shortages and deliver consistent, high-precision welds at increased speeds for mass production. China's shipbuilding industry is a significant adopter of automated welding systems.
- Laser Welding Technology:Laser welding offers high-speed, low-distortion joining for thin and thick materials with excellent precision, making it essential for critical applications in automotive and aerospace. This technology is gaining traction for joining advanced lightweight materials.
- Manual Welding Techniques:Manual processes rely on operator skill for execution, remaining critical for custom fabrication, repair, and situations where automation is not feasible or cost-effective. These techniques are foundational across vocational training programs.
- Hybrid Welding Solutions:Hybrid welding combines two or more welding processes, such as laser-arc welding, to achieve enhanced penetration, speed, and quality compared to individual processes.
Automated Welding Systems are experiencing the highest investment. Laser Welding Technology demonstrates the most rapid technological advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing plants prioritize automated welding systems for large-scale projects, while United States industries demand high-precision solutions for automotive and aerospace applications. This regional divergence shapes technology adoption and equipment procurement. European manufacturers also push for advanced solutions to meet stringent regulatory requirements.
China
China's shipbuilding and construction sectors drive substantial demand for automated welding systems. The country's GB standards influence equipment design and safety features for local market entry. Major manufacturing hubs in the Yangtze River Delta concentrate equipment procurement for massive fabrication needs.
United States
Automotive manufacturing and the aerospace industry in the United States require precise welding for lightweight alloys. OSHA regulations emphasize operator safety, influencing ergonomic designs and fume extraction systems. Detroit's automotive cluster and Seattle's aerospace sector consistently adopt advanced joining technologies.
Germany
Germany's advanced manufacturing base and automotive sector demand sophisticated welding solutions for high-quality production. The EU's CE marking and updated Machinery Regulation mandate stringent performance and safety criteria. Industrial centers like Bavaria drive innovation in automated and laser welding applications.
Japan
Japanese automotive and precision manufacturing industries focus on high-speed, low-distortion welding for complex assemblies. JIS standards guide product development, ensuring reliability and quality in equipment. Production facilities in Aichi Prefecture actively integrate robotic welding systems for efficiency.
South Korea
Shipbuilding and automotive production in South Korea necessitate robust and automated welding processes for large-scale fabrication. National quality standards ensure the integrity of welds in heavy industries. Ulsan's industrial complexes lead in adopting advanced welding for marine and vehicle construction.
Welding Products Market Key Industry Players
European producers anchor one tier of the welding products market; North American specialists hold another. The market exhibits a tiered structure, encompassing global conglomerates and niche technology innovators. Strategic archetypes include full-range equipment providers, advanced process developers, and consumable specialists. Companies pursue strategic partnerships for technology co-development and actively expand their distribution networks globally.
Lincoln Electric Holdings, Inc. exemplifies a North American market leader, leveraging its extensive distribution network to maintain a strong presence across the continent. Kemppi Oy represents a European specialist, focusing on advanced arc welding solutions tailored for demanding industrial applications within its home region. Fronius International GmbH also occupies a significant position as a technology innovator, particularly in advanced power sources and digital welding solutions that cater to high-precision manufacturing. These companies collectively anchor different segments, from broad market coverage to specialized technological leadership, illustrating the diverse competitive approaches within the industry.
| Leading Market Players |
|---|
| Fronius International GmbH |
| AMADA WELD TECH Inc. |
| Lincoln Electric Holdings, Inc. |
| Kemppi Oy |
| Daihen Corporation |
| ESAB |
| Hobart Welding Products |
| Miller Electric Mfg. LLC |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
High-precision performance tiers in welding products create a significant divergence in both pricing and supply chain configurations. This stratification separates advanced automated systems from versatile manual equipment, impacting component sourcing and market access strategies.
Pricing Analysis
Distributor margins significantly influence the final cost of welding products for end-users. The market primarily operates on a value-based pricing model, with differentiation driven by technology sophistication, such as laser welding capabilities, and compliance with stringent regional safety standards like the EU's CE marking. Pricing softness reflects intense competition in the arc welding equipment segment from Asian manufacturers. Manufacturing plants, demanding high-volume automated systems, exhibit lower price sensitivity compared to repair shops seeking cost-effective manual tools.
Supply Chain Analysis
Logistics and freight costs heavily impact the landed price of welding equipment, especially for specialized components. Supply concentration centers on manufacturing hubs in China, Germany, and Japan for advanced systems and consumables. The industry relies on specialized electronic components for automated systems and specific alloy filler metals for consumables. Commodity price volatility for these inputs creates significant margin pressure. Distribution runs through a mix of direct sales to large manufacturing plants and an extensive network of regional distributors serving fabricators and repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Welding Products Market presents a geographic-arbitrage opportunity, particularly leveraging lower manufacturing costs in Asian countries against the higher regulatory compliance requirements for advanced systems in European markets.
For Market Incumbents: Anchor market share through strategic acquisitions of niche technology innovators specializing in laser welding. Intensify R&D investment in software-enabled services to counter margin pressure from commodity arc welding equipment. This defends against displacement by high-strength structural adhesives in automotive applications. Expand captive supply of critical electronic components to mitigate single-source vulnerability.
For New Entrants and Emerging Players: Launch via direct-to-customer e-commerce platforms targeting small and medium-sized fabricators with specialized plasma cutting equipment. Focus on underserved regional markets in Southeast Asia for manual welding solutions, where capital outlay remains a barrier for automated systems. The repair shops segment represents the most penetrable application due to diverse equipment needs. Offer subscription-based models for software-enabled weld process monitoring.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional regulatory fragmentation creates market entry barriers for smaller players. The long-term viability of this market over the next decade is strong, driven by infrastructure modernization and renewable energy projects. Target vertically integrated mid-cap specialists with strong intellectual property in automated welding systems and digital twin technology. The signal to watch is the adoption rate of additive manufacturing in heavy industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-powered weld quality assurance | Enhances precision for aerospace components and reduces defect rates. |
| Expand automated welding system production capacity | Addresses skilled labor shortages in Chinese shipbuilding and manufacturing plants. |
| Develop ergonomic fume extraction solutions | Meets stricter EU Machinery Regulation and OSHA operator safety standards. |
| Form partnerships for advanced material joining | Accelerates adoption of laser welding for lightweight automotive alloys. |
| Acquire software firms specializing in data analytics | Integrates predictive maintenance into equipment offerings, creating new revenue streams. |
Research Approach
Multiple input streams — primary interviews, industry reports, and trade statistics — were reconciled to build a robust market view. This involved conversations with plant managers, R&D directors, and procurement leads from major automotive and shipbuilding companies. Secondary validation drew from public company filings, international trade databases, and regulatory body publications like OSHA and EU CE marking guidelines. A combination of bottom-up and top-down triangulation ensured data consistency.
Data-stream reconciliation formed the basis of the analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and technology, alongside regional regulatory adherence. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included infrastructure spending projections and automotive production forecasts for lightweight materials.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid material science breakthroughs. Forecasts inherently reflect assumptions about future economic stability and regulatory evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Diamond Tools Market
Tools
Mechanical Puller Market
Tools
Land Survey Equipment Market
Tools
Tension Tester Market
Tools
L Allen Wrench Market
Tools
Europe Power Tools Market
Tools
Handheld Pipe Cutter Market
Tools
Oxy-Fuel Torches Market
Tools
Taps and Dies Market
Tools
Portable Rolling Toolbox Market
Tools
Coil Thread Insert Market
Tools
Rebar Cutter Market
Tools
Machining Centers Market
Tools
Hydraulic Torque Wrench Market
Tools
Machine Vise Market
Tools
Rivet Busters Market