
 Mortiser Market | 2026-2036
Mortiser Market Size, Share, and Industry Trends Forecast 2026-2036
Mortiser Market Foresight
The capital-intensity gap between European precision builders and Asian volume producers is collapsing. Felder Group leverages Austrian engineering heritage and captive spindle production to command premium positioning in floor mortiser systems. SCM Group anchors southern European demand through integrated service networks spanning Portugal to Slovenia. CHANG TYPE Industrial competes on scale economics in benchtop and portable units shipped through hardware distributors.
A mortiser is a specialized woodworking machine that cuts square or rectangular holes (mortises) into timber to receive tenons, typically employing chisel-and-auger mechanisms operating at 1,450–3,450 RPM with plunge depths up to 150mm for structural joinery. Floor mortisers dominate commercial furniture and construction contractor workflows where repeatability and depth capacity justify capital outlay, while portable mortisers capture renovation-site demand from trades requiring jobsite mobility. CNC mortisers represent the fastest-expanding technology segment as programmable axis control eliminates setup time for complex rail-and-stile configurations in batch-one production.
CE marking under the EU Machinery Directive and adherence to EN 848 safety standards for woodworking machines govern product access across European member states, with ECHA REACH compliance additionally constraining lubricant and surface-coating chemistries in manufactured units. Germany's KBA-equivalent woodworking safety inspectorates and Austria's regional trade associations enforce operator-certification requirements that sustain replacement demand for guard-integrated modern equipment. Stakeholders must monitor how the EU Green Deal's embodied-carbon tracking extends to capital machinery procurement criteria.
Market Dynamics
CNC-controlled mortising units are decomposing the traditional floor-versus-portable equipment hierarchy as programmable axis control enables batch-one production without setup penalties. German and Austrian furniture manufacturers now specify CE-marked structural timber standards that demand repeatability impossible with manual benchtop models, forcing capital redeployment across European precision joinery clusters.
Growth Catalysts
- EU Green Deal embodied-carbon tracking:Procurement criteria for capital machinery now include lifecycle emissions metrics, favoring guard-integrated modern equipment with documented energy efficiency over legacy assets.
- Timber-frame construction revival:Structural joinery specifications in alpine European markets require plunge depths exceeding 120mm, pulling demand toward floor mortisers with augmented spindle capacity.
- EN 848 safety standard harmonization:Cross-border equipment certification reduces regulatory friction for Austrian and German manufacturers exporting precision mortising systems to adjacent member states.
Market Restraints
- Cast-iron bed casting supply:European foundry capacity constraints limit floor mortiser frame production, creating 14-18 week lead times for heavy-duty units from specialized Italian and Czech suppliers.
- REACH lubricant chemistry compliance:ECHA restrictions on mineral oil formulations force reformulation of spindle bearing greases, adding certification costs without performance differentiation.
- Manual benchtop substitution ceiling:Hobbyist and small-shop segments retain preference for chisel-and-auger hand mortising in restoration and one-off craft applications, capping portable electric unit penetration.
Strategic Opportunities
- Renovation-site battery mobility:Cordless brushless motor platforms from adjacent power-tool categories enable portable mortiser development for construction contractors working historic timber retrofit projects.
- CE marking consultancy bundling:Machinery directive compliance services packaged with equipment sales create recurring revenue streams as smaller Austrian and German workshops navigate operator-certification mandates.
- CNC-mortiser retrofit kits:Axis control modules compatible with existing floor mortiser frames address installed-base upgrade demand without full replacement capital outlay.
Industry Challenges
- Mechatronics technician scarcity:Servo motor calibration and PLC troubleshooting skills lag CNC mortiser deployment rates in Black Forest furniture clusters, extending commissioning timelines.
- Legacy pneumatic integration:Hybrid shops running compressed-air clamping systems face pneumatic-to-electric interface complexity when adding programmable mortising cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortiser Market |
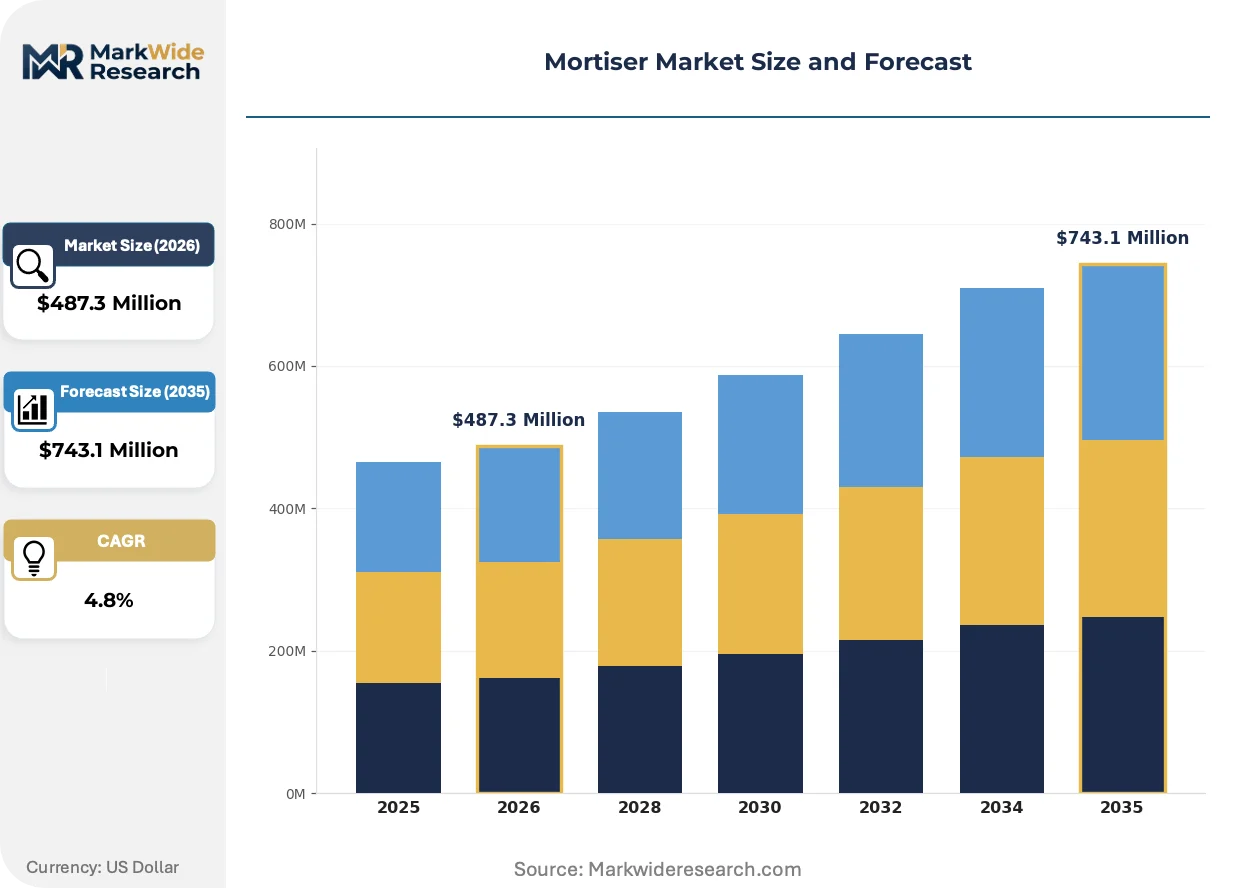
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Mortiser, Floor Mortiser, Portable Mortiser, Pneumatic Mortiser End User: Woodworking Shops, Furniture Manufacturers, Construction Contractors, DIY Enthusiasts Technology: Manual Mortisers, Electric Mortisers, Hydraulic Mortisers, CNC Mortisers Distribution Channel: Online Retailers, Direct Sales, Hardware Stores, Specialty Shops |
| Companies Covered | Felder Group, CHANG TYPE Industrial, Wadkin Woodworking Machines, DMT Holdings, China National Building Material Group, SCM Group, OAV Equipment and Tools, Rockler, Otto Martin Maschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortiser Market Shifts & Advancements
Mechanical control interfaces are yielding to software-defined operation models as spindle positioning and feed-rate optimization migrate to touch-panel parameter entry. This shift compresses operator training curves while expanding the addressable user base beyond traditional machinist skill profiles.
Direct-drive spindle technology is decomposing the gearbox-and-pulley transmission architecture that has dominated floor mortiser construction since the 1970s. German precision furniture manufacturers are adopting torque-dense permanent-magnet motors for plunge depths exceeding 150mm, eliminating backlash-induced tolerance drift and enabling real-time load feedback that protects chisel edges during knot penetration.
CE marking under the EU Machinery Directive now incorporates EN ISO 19085 woodworking machinery safety requirements that mandate two-hand controls and emergency stop Category 1 performance. Austrian equipment builders are redesigning guard interlock systems to satisfy both the directive and regional trade association operator-certification programs, with southern European markets lagging adoption due to fragmented national inspectorate enforcement.
Certification-driven purchasing patterns now dominate procurement in Germany's structural timber sector. Buyers specify EN 848-compliant machines with documented spindle runout tolerances below 0.02mm, displacing price-based selection criteria that previously favored standard-duty units. This behavioral shift concentrates demand among precision-engineered equipment categories and extends replacement cycles for non-compliant installed assets.
Mortiser Market Segmentation
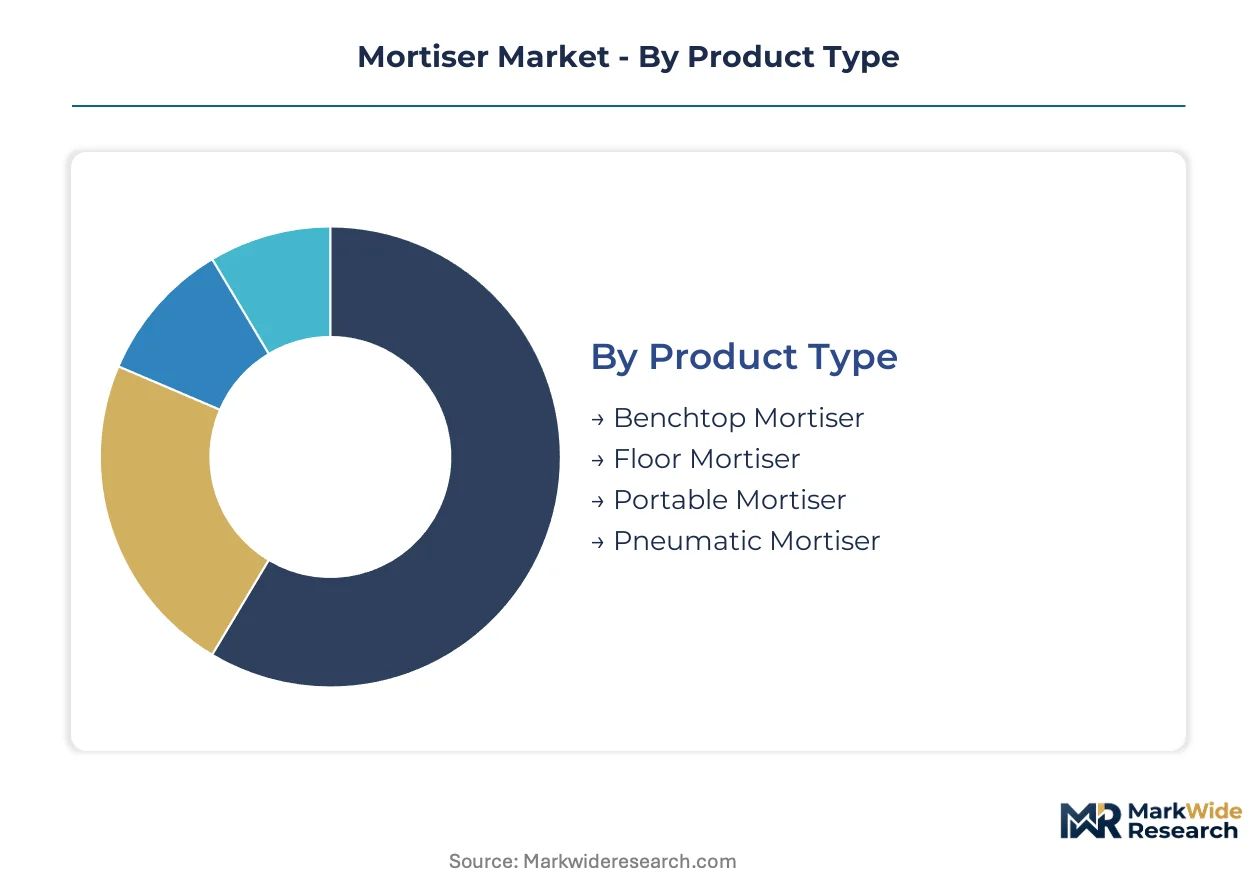
Mortiser procurement patterns diverge sharply between precision-engineered European furniture clusters and volume-driven Asian export manufacturing. Segmentation reveals how CE-marked structural timber standards reshape equipment specification across German and Austrian production lines while battery mobility opens new contractor workflows.
Product Type:
Floor mortisers dominate export-led demand from Austrian precision builders serving alpine European markets, while portable units concentrate in domestic German renovation contracting.
- Benchtop Mortiser:Compact chisel-and-auger systems operating at 1,450–2,800 RPM with plunge depths to 80mm serve hobbyist woodworkers and small restoration shops. Demand concentrates in Germany's Black Forest furniture cluster where CE marking compliance costs disadvantage manual equipment against CNC alternatives.
- Floor Mortiser:Heavy cast-iron frame machines with direct-drive spindles achieve 150mm plunge depths and sub-0.02mm runout tolerances for structural joinery. Austrian manufacturers export these units across alpine European markets where timber-frame construction specifications mandate repeatability impossible with portable equipment.
- Portable Mortiser:Corded and emerging cordless brushless motor platforms deliver jobsite mobility for construction contractors working historic timber retrofits.
- Pneumatic Mortiser:Compressed-air actuated systems persist in hybrid shops with legacy clamping infrastructure, though electric integration complexity constrains new adoption.
Floor mortisers command the established base. The steepest expansion runs through portable battery platforms.
End User:
Application requirements split between precision repeatability mandates in commercial manufacturing and mobility priorities in field construction.
- Woodworking Shops:Independent craft workshops and mid-scale joinery operations balance capital constraints against EN 848 safety standard compliance, driving retrofit kit demand rather than full replacement cycles.
- Furniture Manufacturers:German and Austrian precision builders specify CNC-controlled units for batch-one rail-and-stile production without setup penalties, with CE-marked structural timber standards eliminating manual benchtop options from certified supply chains.
- Construction Contractors:Timber-frame and historic renovation specialists in alpine European markets require plunge depths exceeding 120mm with jobsite portability, pulling development toward battery-powered floor-stand hybrids.
- DIY Enthusiasts:Hobbyist segments retain preference for chisel-and-auger hand mortising in one-off craft applications, capping electric portable penetration.
Furniture manufacturers anchor precision equipment demand. The steepest climb in specification intensity is occurring among construction contractors.
Technology:
Control architecture migration from mechanical to software-defined operation redistributes value across transmission and axis-control component tiers.
- Manual Mortisers:Hand-operated chisel-and-auger systems persist in restoration craft and heritage timber work where operator certification programs sustain residual demand.
- Electric Mortisers:AC induction and brushless DC motor platforms dominate installed capacity, though gearbox-and-pulley transmission architectures face displacement by direct-drive alternatives.
- Hydraulic Mortisers:Fluid-power actuation delivers high torque for dense hardwood penetration in specialized industrial applications, with maintenance complexity limiting adoption outside heavy production environments.
- CNC Mortisers:Programmable axis control with touch-panel parameter entry eliminates setup time for complex joinery configurations, expanding the addressable user base beyond traditional machinist skill profiles while commanding premium positioning.
Electric systems hold the installed base majority. CNC platforms are gaining share fastest among new capital deployment.
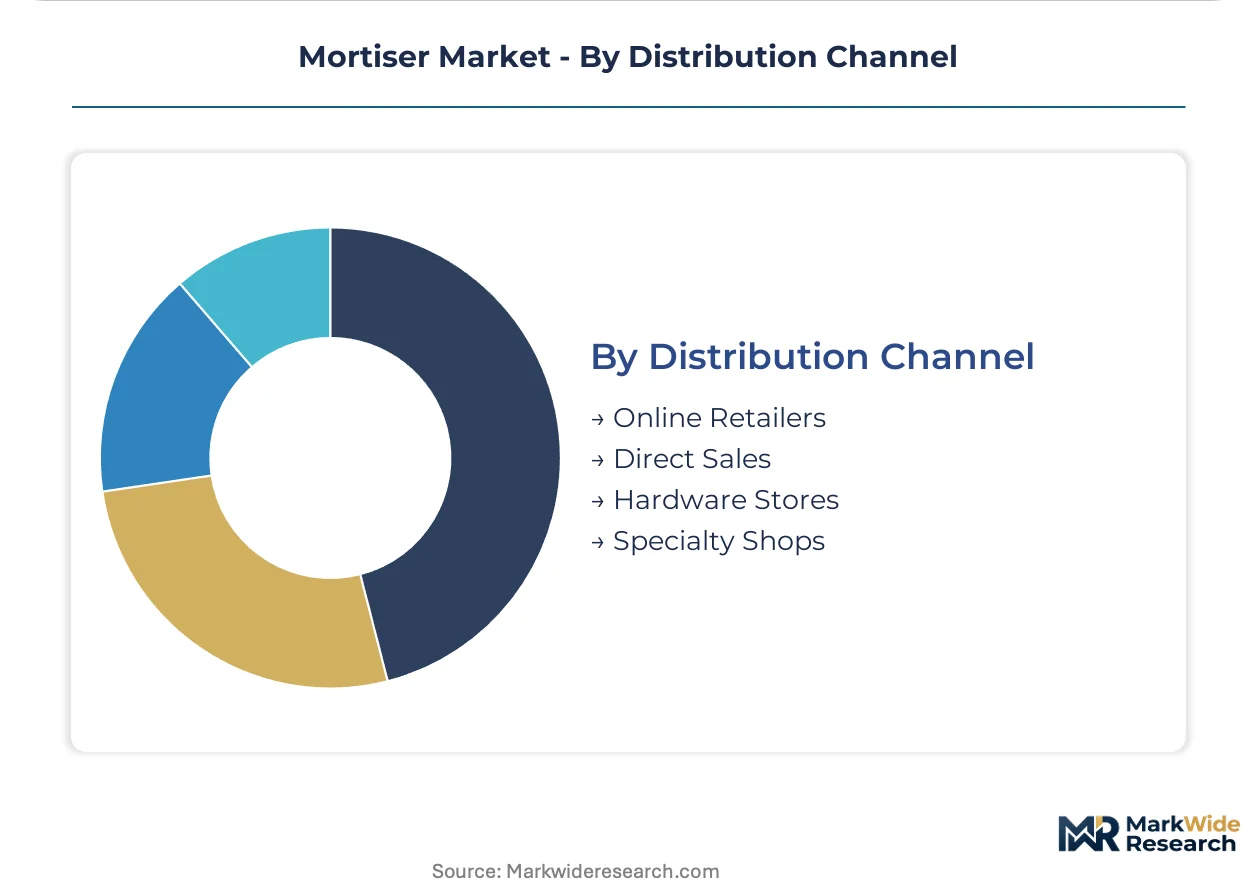
Distribution Channel:
Sales pathway selection correlates with equipment complexity and compliance documentation requirements.
- Online Retailers:E-commerce platforms capture benchtop and portable unit volume through hardware distributor networks, though CE marking documentation gaps constrain structural timber sector penetration.
- Direct Sales:Manufacturer-direct relationships dominate floor mortiser and CNC system procurement for German and Austrian furniture manufacturers requiring integrated operator-certification support and lifecycle emissions documentation under EU Green Deal criteria.
- Hardware Stores:Brick-and-mortar distributors serve trades contractor demand for portable electric units with immediate availability requirements.
- Specialty Shops:Woodworking-focused retailers provide demonstration and training services that reduce commissioning timelines for CNC mortiser deployment in mechatronics technician-scarce regions.
Direct sales channels command premium equipment flows. Online retail is expanding most quickly in portable and benchtop categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German furniture manufacturers deploy floor mortisers for CE-marked structural timber, while Austrian precision builders export CNC-controlled units across alpine Europe. Asian volume producers concentrate on benchtop and portable equipment for hardware distribution channels.
Germany
Black Forest furniture clusters demand EN 848-compliant machines with sub-0.02mm spindle runout for certified joinery. KBA-equivalent woodworking safety inspectorates enforce operator-certification requirements that sustain replacement demand for guard-integrated equipment. Precision manufacturers in Baden-Württemberg specify CNC mortisers for batch-one rail-and-stile production without setup penalties.
Austria
Alpine woodworking belt producers export floor mortisers with direct-drive spindles achieving 150mm plunge depths for timber-frame construction. Regional trade associations mandate compliance documentation under EU Machinery Directive, favoring domestic manufacturers with integrated certification support. Felder Group leverages captive spindle production in Vorarlberg to command premium positioning in structural joinery equipment.
Italy
Foundry capacity constraints in northern Italy create 14-18 week lead times for heavy cast-iron bed castings used in floor mortiser frames. SCM Group anchors southern European demand through integrated service networks spanning Portugal to Slovenia. Emilia-Romagna equipment builders redesign guard interlock systems to satisfy both CE marking and fragmented national inspectorate enforcement.
United States
Timber-frame construction contractors in Pacific Northwest and Appalachian regions require portable mortisers for historic renovation workflows. OSHA woodworking machinery standards govern operator safety without the certification mandates seen in European markets. Rockler distributes benchtop units through specialty retail channels serving hobbyist woodworkers and small restoration shops.
China
Volume producers in Zhejiang and Guangdong manufacture benchtop and portable mortisers for hardware distributor export networks. GB standards for woodworking machinery safety lag EN 848 harmonization, constraining penetration into European structural timber sectors. CHANG TYPE Industrial competes on scale economics in electric mortiser platforms shipped through global hardware channels.
Mortiser Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in mortiser manufacturing. Austrian and German precision builders command premium positioning through captive component production and CE marking integration services. Asian volume producers compete on scale economics in portable and benchtop categories. Strategic moves concentrate on CNC retrofit kit development for installed-base upgrades and battery mobility platforms for construction contractor workflows.
Among Austrian integrated manufacturers, Felder Group and Otto Martin Maschinenbau exemplify the precision-engineered tier with heritage engineering capabilities and regional trade association alignment. SCM Group represents the southern European service-network archetype with cross-border coverage from Italy into Slovenia and Portugal. CHANG TYPE Industrial occupies the scale-driven position in benchtop equipment, while OAV Equipment and Tools anchors Taiwanese specialist production for hardware distribution channels.
| Leading Market Players |
|---|
| Felder Group |
| CHANG TYPE Industrial |
| Wadkin Woodworking Machines |
| DMT Holdings |
| China National Building Material Group |
| SCM Group |
| OAV Equipment and Tools |
| Rockler |
| Otto Martin Maschinenbau |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85% in northern Italy and the Czech Republic compress margins for floor mortiser frames while elevating price floors for precision-engineered Austrian and German equipment. CE marking compliance costs and direct-drive spindle technology premiums stratify pricing across three performance tiers, with battery mobility platforms introducing new cost structures in portable categories.
Pricing Analysis
After-sales service contracts and spindle replacement programs generate lifetime value multiples exceeding initial equipment sales for floor mortiser manufacturers. Three-tier pricing structure across premium CNC-controlled, standard electric, and economy benchtop levels reflects certification grade and spindle runout tolerance differentiation. Pricing pressure stems from Asian scale producers competing on portable unit cost in hardware distribution channels. DIY enthusiasts and small restoration shops exhibit highest price sensitivity, while German furniture manufacturers prioritize EN 848 compliance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for cast-iron bed castings and permanent-magnet motor components. Supply concentrates in Italy and the Czech Republic for heavy frames, Austria and Germany for precision spindles, and China for brushless motor platforms. Raw material dependencies include nodular cast iron, rare-earth magnets, and REACH-compliant bearing greases. Single-source vulnerability persists in European foundry capacity for structural joinery equipment. Distribution runs through manufacturer-direct relationships for CNC systems and hardware distributor networks for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
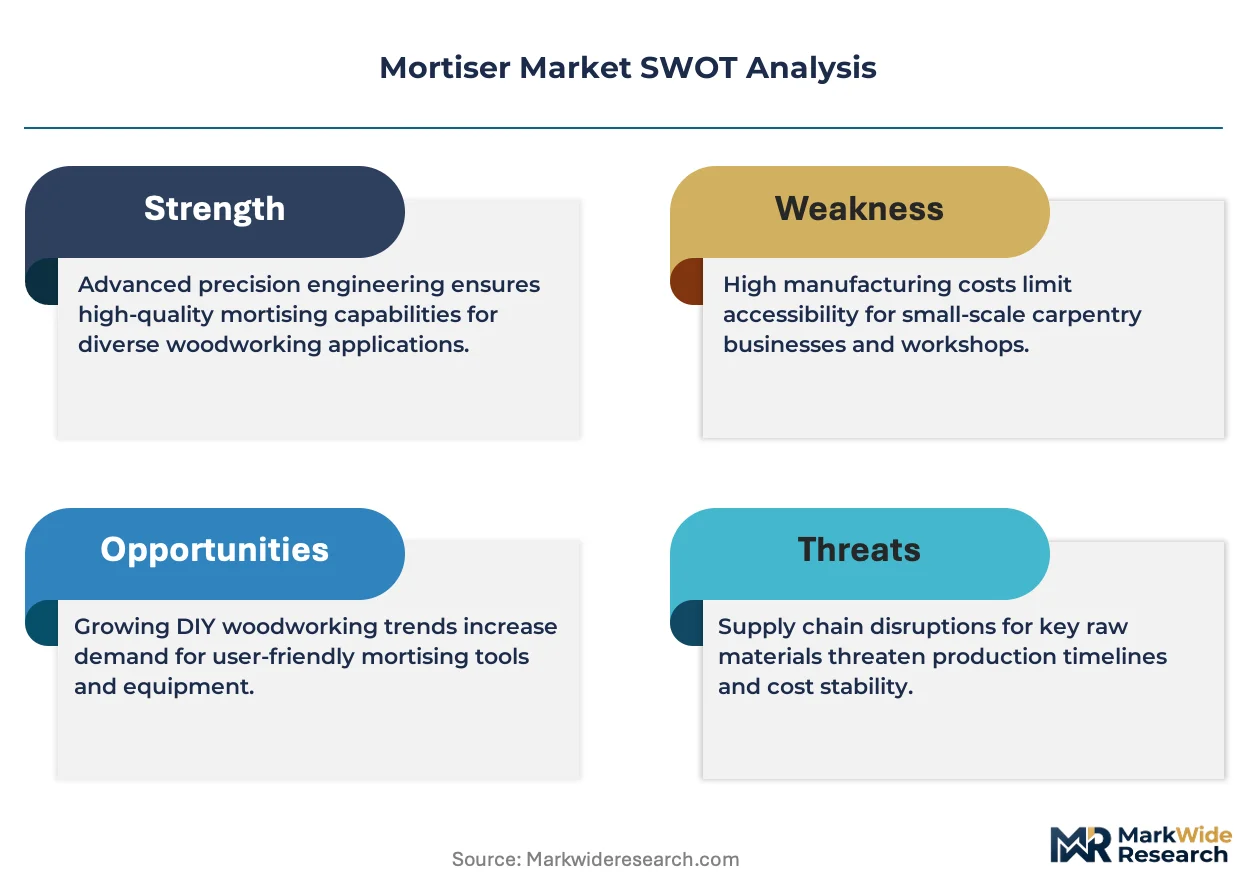
This market rewards regulatory entrenchment as a defensive moat, with CE marking and operator-certification mandates creating switching costs that protect incumbent positioning in German and Austrian precision clusters.
For Market Incumbents: Secure captive spindle production capacity in Vorarlberg and Baden-Württemberg to defend against Asian motor-platform substitution. Deepen backward integration into cast-iron frame supply through long-term offtake agreements with Italian foundries, insulating against lead time volatility that threatens delivery commitments to alpine timber-frame contractors. For New Entrants and Emerging Players: CE marking fast-track services bundled with benchtop equipment sales unlock white-space opportunity among Austrian and German small workshops navigating Machinery Directive compliance. Target battery-powered portable mortisers for Pacific Northwest timber-frame contractors where OSHA standards lack European certification complexity. Pursue demonstration-based go-to-market through woodworking specialty retailers to compress commissioning timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CNC retrofit kit providers serving installed-base upgrade demand without full replacement cycles. Five-to-ten year viability favors precision-engineered equipment categories with documented lifecycle emissions under EU Green Deal procurement criteria. Monitor mechatronics technician training program expansion in Black Forest clusters as inflection indicator for CNC deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CNC Retrofit Kit Development | Axis control modules address installed-base upgrade demand without full capital replacement in German precision clusters. |
| Battery Mobility Platform Launch | Cordless brushless motor systems capture historic timber retrofit workflows among alpine European contractors. |
| CE Marking Consultancy Bundling | Compliance services packaged with equipment sales create recurring revenue from Austrian workshop certification mandates. |
| Direct-Drive Spindle Integration | Torque-dense permanent-magnet motors eliminate backlash drift for plunge depths exceeding 150mm in structural joinery. |
| Foundry Capacity Partnership | Long-term frame supply agreements with Italian and Czech suppliers mitigate 14-18 week lead time risks. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at German furniture manufacturers, plant engineers in Austria's alpine woodworking belt, aftermarket service heads at Italian equipment builders, and procurement teams at hardware distribution networks, then refined against secondary validation from EN 848 safety standard documentation, EU Machinery Directive filings, ECHA REACH substance restrictions, customs trade data for woodworking machinery, and SEC filings from publicly traded industrial equipment manufacturers. Bottom-up equipment shipment estimates and top-down construction spending allocation models were triangulated to converge on segment-level outputs.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in floor versus portable equipment categories. Segmentation dimensions modeled include product type, end-user application, control technology architecture, and distribution channel structure, with additional granularity on CE marking compliance tier. CAGRs were derived from equipment replacement cycle analysis and timber-frame construction demand elasticity. Industry-specific forecast inputs incorporate foundry capacity utilization rates and mechatronics technician pipeline data from regional trade associations.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal embodied-carbon tracking expansion and stable EN 848 safety standard harmonization; material deviation in regulatory enforcement intensity or foundry capacity constraints would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Grinding Machines Market
Tools
Global Table Saws Market
Tools
Sand Control Tools Market
Tools
Press Machine Market
Tools
Global DC Torque Tool Market
Tools
Multi Spindle Machines Market
Tools
Ripper Market
Tools
Tool Pliers Market
Tools
Ratchet Wringer Market
Tools
Reamer Market
Tools
Cold and Hot Tool Steel Market
Tools
Screw Fastener Market
Tools
Collated Screws Market
Tools
Squeegee Market
Tools
Automatic Lathe Machines Market
Tools
Lathe Machines Market