
 Piling Machine Market | 2026-2036
Piling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Piling Machine Market Intelligence
Modular piling rig configurations is expanding buyer choice across foundation projects, letting contractors scale hammer and drill attachments to site-specific soil profiles without full fleet replacement. Bauer Group leverages in-house manufacturing of rotary drives and kelly bars to sustain vertical integration advantages in European infrastructure tenders. SANY Group anchors its position through domestic supply chain density in China's high-speed rail corridor. Junttan Oy differentiates via specialized hydraulic impact hammers for Nordic bedrock conditions.
A piling machine is a heavy foundation engineering device that drives, drills, or vibrates structural piles into subsurface strata to transfer building loads to stable soil or rock layers, typically generating impact energies from 50 kNm to over 1,000 kNm depending on hammer type and soil resistance. Crawler-mounted rigs dominate marine and offshore applications where tracked mobility across uneven quay surfaces proves essential, while truck-mounted units capture urban construction sites demanding rapid inter-site relocation. Hydraulic technology leads the technology dimension due to precise stroke control and fuel efficiency, though electric drive architectures gain traction in European noise-restricted zones.
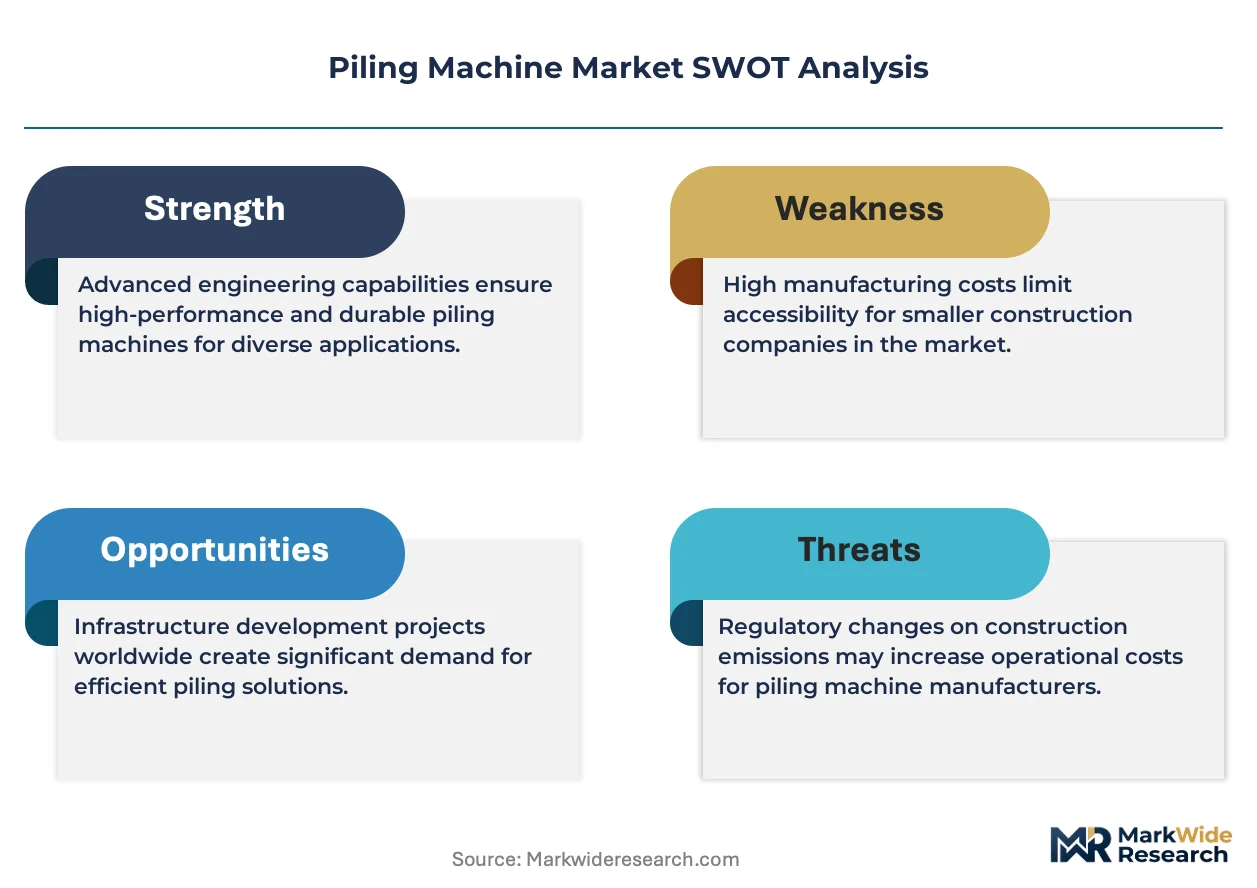
China's MIIT enforces GB emission standards that compel engine retrofits on crawler rigs operating near urban centers, while India's CEA mandates geotechnical certification for foundation equipment deployed on public dam and power projects. The EU F-Gas Regulation restricts hydraulic fluid formulations used in imported rigs, altering maintenance protocols for contractors operating across member states. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking reshape capital allocation toward lower-emission piling platforms.
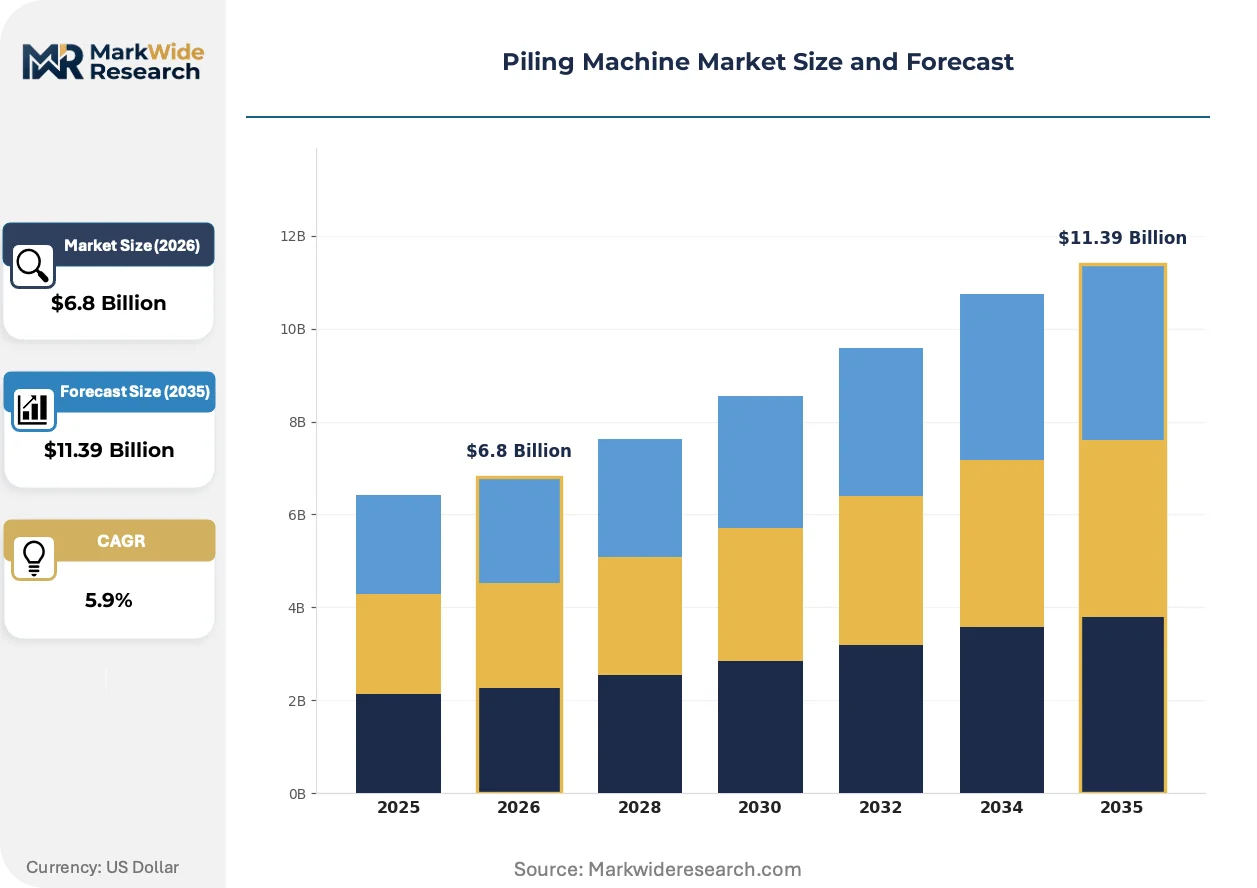
Market Dynamics
Foundation contractors face a structural squeeze between China's GB emission mandates requiring crawler rig engine retrofits and the capital intensity of modular attachment systems that promise fleet flexibility without full replacement cycles.
Growth Catalysts
- Port Modernization in India:Western coastal states Maharashtra and Gujarat accelerate piling procurement for container terminal expansion and offshore wind jacket foundations, creating sustained equipment demand through 2035.
- EU F-Gas Regulation:Restrictions on hydraulic fluid formulations force maintenance protocol upgrades that favor newer rig imports with sealed-system designs, advantaging OEMs with compliant architectures.
- Rotary Drive Electrification:Battery-hybrid power packs for kelly bar rotation cut fuel consumption by 30-40% in urban noise-restricted zones, aligning with municipal construction hour extensions.
Market Restraints
- High-Strength Steel Input Volatility:Kelly bar and mast fabrication depends on quenched-and-tempered plate grades subject to energy-intensive production curbs under China's dual carbon goals.
- European Hydraulic Component Concentration:Precision pump and valve supply clusters in Germany and Italy create vulnerability when marine logistics disrupt just-in-time delivery to Asian rig assemblers.
- Sheet Pile Substitution:Vibratory extraction technologies for temporary cofferdams reduce driven pile counts in urban basement projects, compressing hammer utilization rates.
Strategic Opportunities
- Saudi Giga-Project Pipeline:NEOM and Red Sea coastal developments specify European-standard geotechnical certification for foundation equipment, opening premium positioning for compliant OEMs.
- Telematics-Enabled Performance Contracts:Real-time pile depth and blow-count data streams allow contractors to unbundle equipment from operator labor, selling guaranteed capacity rather than machine-hours.
- India's PLI Scheme for Construction Equipment:Domestic component manufacturing incentives reduce import dependency for hydraulic power packs and rotary heads, lowering landed cost for regional fleet operators.
Industry Challenges
- Geotechnical Engineer Scarcity:Site-specific soil analysis for hammer energy calibration requires certified specialists concentrated in Mumbai, Shanghai, and Rotterdam, creating project bottlenecks.
- Multi-Standard Certification Timelines:Rig designs must simultaneously satisfy China's GB/T, EU's CE machinery directive, and India's CEA dam-project protocols, extending validation cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piling Machine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck Mounted, Static, Crawler, Spiral Application: Construction, Foundation, Soil Stabilization, Marine End User: Contractors, Engineers, Developers, Government Technology: Hydraulic, Mechanical, Electric, Pneumatic |
| Companies Covered | Bauer Group, Liebherr Group, Soilmec S.p.A., Casagrande Group, XCMG Group, SANY Group, Junttan Oy, Vermeer, Epiroc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piling Machine Market Strategic Shifts & Innovations
Electrification architectures and data-centric service models are compressing the traditional boundaries between equipment OEMs and foundation contractors, shifting value capture toward outcome guarantees rather than asset ownership.
Integrated battery-electric powertrains for crawler undercarriages and rotary drives are consolidating the previously separate domains of diesel engine suppliers and hydraulic system vendors. European urban contractors in Rotterdam and Hamburg adopt these configurations to secure extended construction permits in noise-restricted zones. The technology is consolidating procurement decisions around total energy cost rather than upfront capital expenditure, compressing the addressable market for conventional diesel-hydraulic platforms.
China's MIIT enforcement of GB 36886 non-road emission standards compels engine retrofits or replacement on crawler rigs operating within 50 kilometers of urban centers. The regulation forces contractors to accelerate fleet turnover or invest in selective catalytic reduction systems, raising operating cost baselines. Domestic OEMs with captive engine manufacturing respond faster than import-dependent competitors, reshaping competitive positioning in coastal urban corridors.
Rental and leasing penetration for modular rig configurations is displacing outright purchase among mid-tier foundation contractors facing project volume uncertainty. Equipment financiers in India and Southeast Asia now structure contracts around guaranteed pile-meter output rather than machine availability, transferring productivity risk from contractor to lessor. This shift concentrates most visibly in India's western coastal states where port project timelines fluctuate with monsoon windows and environmental clearance cycles.
Piling Machine Market Segmentation
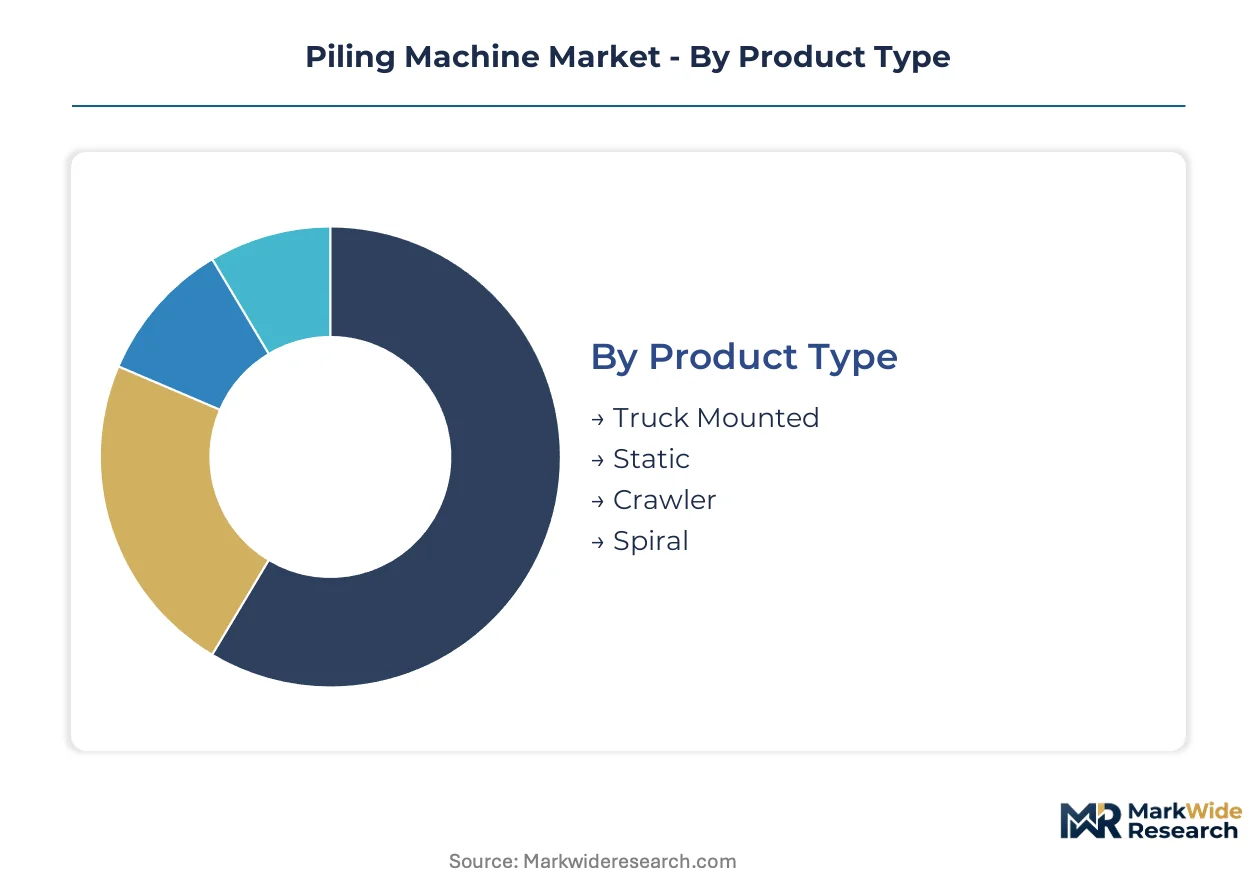
Piling machine procurement decisions fragment across mobility requirements, energy sources, and project ownership structures. Contractors optimize fleet composition against soil conditions, emission zones, and capital deployment cycles.
Product Type:
Mobility architecture determines site access economics and inter-project relocation speed.
- Crawler:Tracked undercarriages distribute machine weight across uneven quay surfaces and soft marine substrates. India's western coastal states—Maharashtra and Gujarat—drive procurement for port terminal expansion where ground bearing pressure limits exclude rubber-tired alternatives.
- Truck Mounted:Highway-legal chassis enable same-day relocation between urban foundation sites. European contractors in Rotterdam and Hamburg favor these units for noise-restricted zones where rapid exit from residential proximity matters.
- Static:Fixed-position rigs anchor to pre-cast foundations for high-capacity vertical drilling. These configurations dominate dam and power project work under India's CEA certification requirements.
- Spiral:Continuous flight auger systems eliminate casing requirements in cohesive soils. The technology concentrates in urban basement projects where vibration restrictions prohibit impact driving.
Mature deployment sits with Crawler rigs in marine and offshore corridors. Newer deployment is concentrated in Truck Mounted configurations for urban emission zones.
Application:
Subsurface intervention objectives separate temporary stabilization from permanent load transfer.
- Foundation:Structural pile installation for buildings, bridges, and energy infrastructure generates the highest equipment utilization rates. China's high-speed rail corridor sustains demand for rotary bored piles exceeding 60-meter depths.
- Marine:Offshore wind jacket foundations and container terminal quay walls require corrosion-resistant mast specifications. The EU F-Gas Regulation shapes maintenance protocols for hydraulic systems operating in salt-air environments.
- Construction:General building projects span residential high-rises to industrial facilities. Modular attachment systems let contractors switch between driven and bored methods without fleet duplication.
- Soil Stabilization:Ground improvement through vibro-compaction or stone columns addresses liquefaction risk in seismic zones. Japan's METI building codes drive specification for specialized vibratory heads.
Foundation work commands the steepest expansion trajectory as urban density increases vertical construction. Soil Stabilization is gaining share fastest in Pacific Ring of Fire corridors.
End User:
Capital access and risk tolerance stratify across project ownership models.
- Contractors:Equipment-heavy balance sheets favor rental and leasing structures. India's PLI scheme for construction equipment components is lowering landed costs for regional fleet operators.
- Developers:Vertical integration into foundation work is accelerating among large real estate platforms. Saudi Arabia's NEOM and Red Sea projects specify European-standard geotechnical certification, filtering supplier eligibility.
- Government:Public dam, highway, and port authorities mandate certified equipment pools. China's MIIT emission enforcement compels engine retrofits on crawler rigs within 50 kilometers of urban centers.
- Engineers:Design-consultant procurement concentrates in specialized geotechnical consultancies. Certified specialists for hammer energy calibration cluster in Mumbai, Shanghai, and Rotterdam, creating project bottlenecks.
Capital deployment concentrates with Contractors through output-guaranteed leasing. Risk absorption is shifting fastest toward Government entities under extended infrastructure concession models.
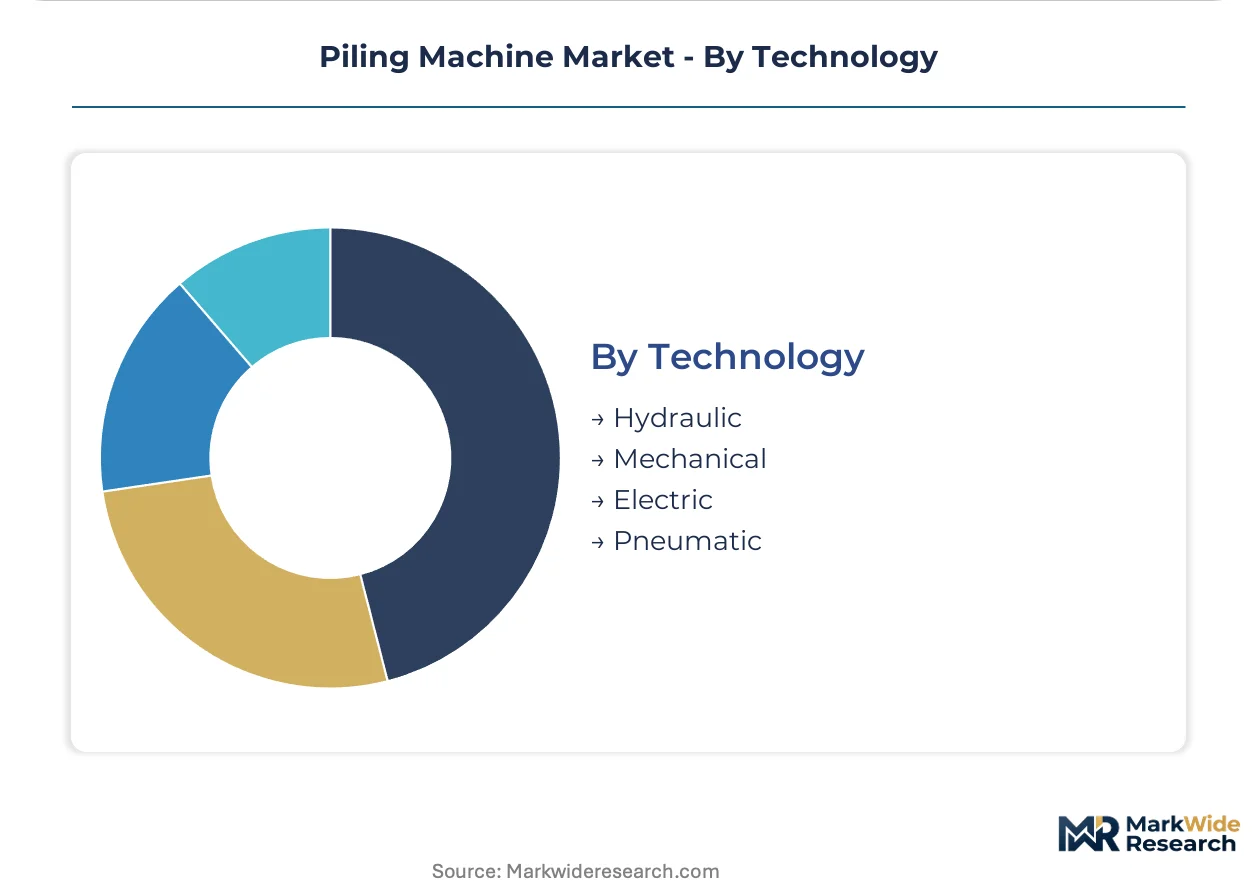
Technology:
Power transmission methods determine fuel efficiency, precision control, and noise emissions.
- Hydraulic:Pressurized fluid systems deliver precise stroke control for impact hammers and rotary drives. The EU F-Gas Regulation restricts hydraulic fluid formulations, advantaging sealed-system designs from compliant OEMs.
- Electric:Battery-hybrid power packs for kelly bar rotation cut fuel consumption in European noise-restricted zones. Extended construction permits in Rotterdam and Hamburg reward these configurations.
- Mechanical:Direct-drive systems persist in emerging markets where maintenance simplicity outweighs efficiency premiums. These units dominate temporary cofferdam and sheet pile extraction work.
- Pneumatic:Compressed air hammers operate in explosive atmospheres where electrical spark risk is prohibitive. Deployment concentrates in oil and gas facility foundations and mining infrastructure.
Installed base concentrates with Hydraulic systems across diesel-dependent fleets. Technology transition is accelerating fastest in Electric architectures for municipal noise regulation compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of piling rig components while India and the Middle East absorb the fastest fleet expansion. This production-consumption split forces OEMs to balance captive supply advantages against localization mandates in target markets.
China
High-speed rail corridor extensions and coastal urban renewal sustain demand for rotary bored piles exceeding 60-meter depths. MIIT enforces GB 36886 non-road emission standards within 50 kilometers of urban centers, compelling engine retrofits or fleet turnover. Shanghai and the Yangtze River Delta concentrate domestic OEM assembly capacity with captive engine manufacturing.
India
Western coastal states Maharashtra and Gujarat accelerate container terminal expansion and offshore wind jacket foundations. CEA mandates geotechnical certification for equipment deployed on public dam and power projects. Mumbai anchors specialist engineering talent pools for hammer energy calibration, creating project bottlenecks during peak construction windows.
Germany
Precision hydraulic component manufacturing clusters around Stuttgart and Munich supply pump and valve systems to Asian rig assemblers. EU F-Gas Regulation restricts hydraulic fluid formulations, advantaging sealed-system designs from compliant OEMs. Hamburg contractors adopt battery-hybrid configurations to secure extended construction permits in noise-restricted zones.
Saudi Arabia
NEOM and Red Sea coastal developments specify European-standard geotechnical certification for foundation equipment. SFDA and municipal regulators align procurement protocols with EU machinery directives. The Eastern Province concentrates port modernization activity while Riyadh drives high-rise foundation demand.
United States
Offshore wind lease auctions along the Atlantic coast generate demand for jacket foundation installation capacity. EPA emission standards for non-road diesel engines shape crawler rig fleet specifications. The Gulf Coast petrochemical corridor sustains pneumatic hammer deployment for explosive atmosphere foundations.
Piling Machine Market Key Industry Players
The competitive structure tilts toward diversified machinery conglomerates with captive hydraulic component supply. Bauer Group and Liebherr Group anchor the premium tier through in-house manufacturing of rotary drives and kelly bars, while Chinese state-backed enterprises leverage domestic supply chain density for cost positioning. Three archetypes dominate: European specialists with vertical integration advantages, Asian scale players with government-supported export financing, and regional fabricators serving emerging market price sensitivity. Consolidation pressure concentrates in hydraulic system vendors seeking battery-electric partnerships, and in rental fleet operators bundling telematics-enabled performance contracts.
Among European-anchored specialists, Bauer Group exemplifies the integrated engineering archetype with captive production of critical subsystems. SANY Group and XCMG Group occupy positions within the state-supported scale tier, leveraging domestic component density to compress landed costs in target export markets. Junttan Oy represents the geographic-specialist model with concentrated expertise in Nordic bedrock conditions.
| Leading Market Players |
|---|
| Bauer Group |
| Liebherr Group |
| Soilmec S.p.A. |
| Casagrande Group |
| XCMG Group |
| SANY Group |
| Junttan Oy |
| Vermeer |
| Epiroc |
| Others |
Cost & Logistics Intelligence
Sovereign-backed Chinese OEMs with captive engine manufacturing compress landed costs for rotary drive systems while European family-owned hydraulic specialists defend margin structures through sealed-system architectures. This ownership bifurcation concentrates pricing power with state-supported scale players in high-volume export corridors and with vertically integrated engineering houses in premium certification tiers.
Pricing Analysis
Margin tightening in mid-tier crawler rigs reflects China's dual carbon enforcement curbing energy-intensive quenched-and-tempered steel production. Project-based contract pricing dominates foundation work, with differentiation anchored in CE machinery directive compliance and GB/T certification grade. India's PLI scheme for construction equipment components intensifies cost-down pressure on hydraulic power pack imports. Government fleet operators show lowest price sensitivity due to extended infrastructure concession models, while mid-tier contractors in Southeast Asia exhibit highest sensitivity to landed cost fluctuations.
Supply Chain Analysis
Refurbishment flows for kelly bars and rotary drives concentrate in Germany's Stuttgart precision component cluster and Shanghai's Yangtze River Delta assembly corridors. Kelly bar fabrication draws from quenched-and-tempered plate grades, precision pump systems, and sealed hydraulic fluid formulations. Single-source vulnerability sits with European hydraulic valve suppliers concentrated in Italy and Germany. Distribution runs through OEM-direct sales for large foundation contractors and rental fleet operators for mid-tier project-based demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piling machine sector occupies a technology-transition phase as battery-hybrid powertrains displace diesel-hydraulic architectures in European noise-restricted zones. This substitution rewires procurement criteria toward total energy cost ownership and away from upfront capital expenditure metrics.
For Market Incumbents:Extend sealed-system hydraulic architectures to preempt EU F-Gas Regulation maintenance protocol upgrades. Accelerate in-house production of battery-hybrid rotary drives to defend against Chinese OEMs with captive powertrain manufacturing. Consolidate aftermarket service networks around telematics-enabled performance contracts that transfer productivity risk from contractors to lessors.
For New Entrants and Emerging Players:Begin with modular attachment systems for India's western coastal port modernization corridor, where project volume uncertainty favors rental penetration over fleet purchase. Target CEA-certified static rig configurations for public dam and power projects where geotechnical certification barriers filter incumbent competition. Structure go-to-market through equipment financiers offering guaranteed pile-meter output contracts rather than machine-hour leasing.
For Investors and Strategic Acquirers:Distressed-cycle entries favor European hydraulic component specialists with sealed-system IP and established CE marking pathways in Germany and Italy. Long-term viability hinges on battery-electric transition readiness across the 5-10 year infrastructure replacement window. Monitor MIIT enforcement intensity in China's Yangtze River Delta and CEA certification timeline extensions in Mumbai as inflection indicators for fleet turnover velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Powertrain Integration | Secures extended construction permits in Rotterdam and Hamburg noise-restricted zones. |
| Sealed-System Hydraulic Architecture | Preempts EU F-Gas Regulation maintenance protocol upgrades for salt-air marine deployments. |
| Telematics-Enabled Performance Contracting | Unbundles equipment from operator labor, selling guaranteed pile-meter output to Indian contractors. |
| CE/GB/T Multi-Standard Certification Investment | Accelerates validation cycles for Saudi Giga-Project tenders specifying European geotechnical standards. |
| Domestic Component Manufacturing Under PLI | Reduces import dependency for hydraulic power packs in India's western coastal states. |
Research Approach
Multi-period observation of crawler rig fleet turnover rates, emission retrofit compliance costs, and port project award timelines anchored the trend analysis, supplemented by interviews with foundation contractors, equipment financiers, and geotechnical engineering consultants. Primary fieldwork engaged maintenance directors at rental fleet operators, OEM procurement teams in Shanghai and Stuttgart, and CEA certification specialists in Mumbai. Secondary validation drew from EU F-Gas Regulation implementation bulletins, India's PLI scheme component manufacturing disclosures, MIIT non-road emission enforcement records, and customs trade data for hydraulic component flows. Bottom-up project pipeline aggregation triangulated against top-down OEM shipment disclosures.
Segment-weighting applied mobility architecture, energy source, and end-user ownership structure as primary dimensions, with technology transition velocity as an industry-specific overlay. CAGRs derived from equipment replacement cycle modeling and infrastructure investment commitment trajectories across the projection horizon. Forecast inputs incorporated GB 36886 enforcement zone expansion, offshore wind jacket foundation procurement schedules, and telematics penetration rates in rental fleet contracts.
Steel input cost volatility, emission standard acceleration timelines, and geotechnical engineer availability bottlenecks are the dominant revision risks to modeled fleet expansion. Practitioners should monitor MIIT urban center enforcement radius extensions, CEA certification backlog durations, and European hydraulic component logistics disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Global Welding Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Latin America Construction Equipment Market