
 Rotary Knife Cutters Market | 2026-2036
Rotary Knife Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Knife Cutters Market Analytics
Modular cutter head configurations is rebalancing procurement patterns across packaging and textile operations. RotoMetrics leverages its die-cutting specialization to anchor high-volume flexible packaging contracts in North America. Kocher+Beck sustains competitive positioning through precision-ground circular knife technology serving European label converters. Eastman Machine Company dominates manual and automated textile cutting systems with century-old brand recognition in apparel manufacturing centers.
Rotary knife cutters are cylindrical cutting tools mounted on rotating shafts, typically manufactured from tool steel or tungsten carbide with hardness ratings exceeding 60 HRC, designed to perform continuous slitting, scoring, or perforating operations on webs and sheets moving at high line speeds. Their primary industrial purpose centers on maintaining clean edge quality and dimensional repeatability across paper, film, fabric, and food substrate processing lines. Fixed blade systems currently lead installed base volumes due to lower maintenance requirements in stable production environments, while adjustable blade configurations represent the fastest-expanding category as converters seek format flexibility without complete tooling changeovers. The food processing application segment commands premium margin pools because sanitary design standards and FDA-compliant material certifications add measurable value to blade assemblies.
FDA material compliance requirements and EU REACH substance restrictions directly shape blade alloy selection and surface coating specifications for cutters contacting food and pharmaceutical packaging substrates. OSHA machine guarding standards in the United States and CE machinery directives in Europe mandate integrated safety enclosures and emergency stop systems on new rotary cutter installations, elevating total system cost but reducing liability exposure for operators. Stakeholders must monitor evolving PFAS restrictions in Europe and pending FDA guidance on recycled content contact materials, as these regulatory trajectories will determine next-generation blade coating investments and retrofit obligations across existing equipment fleets.
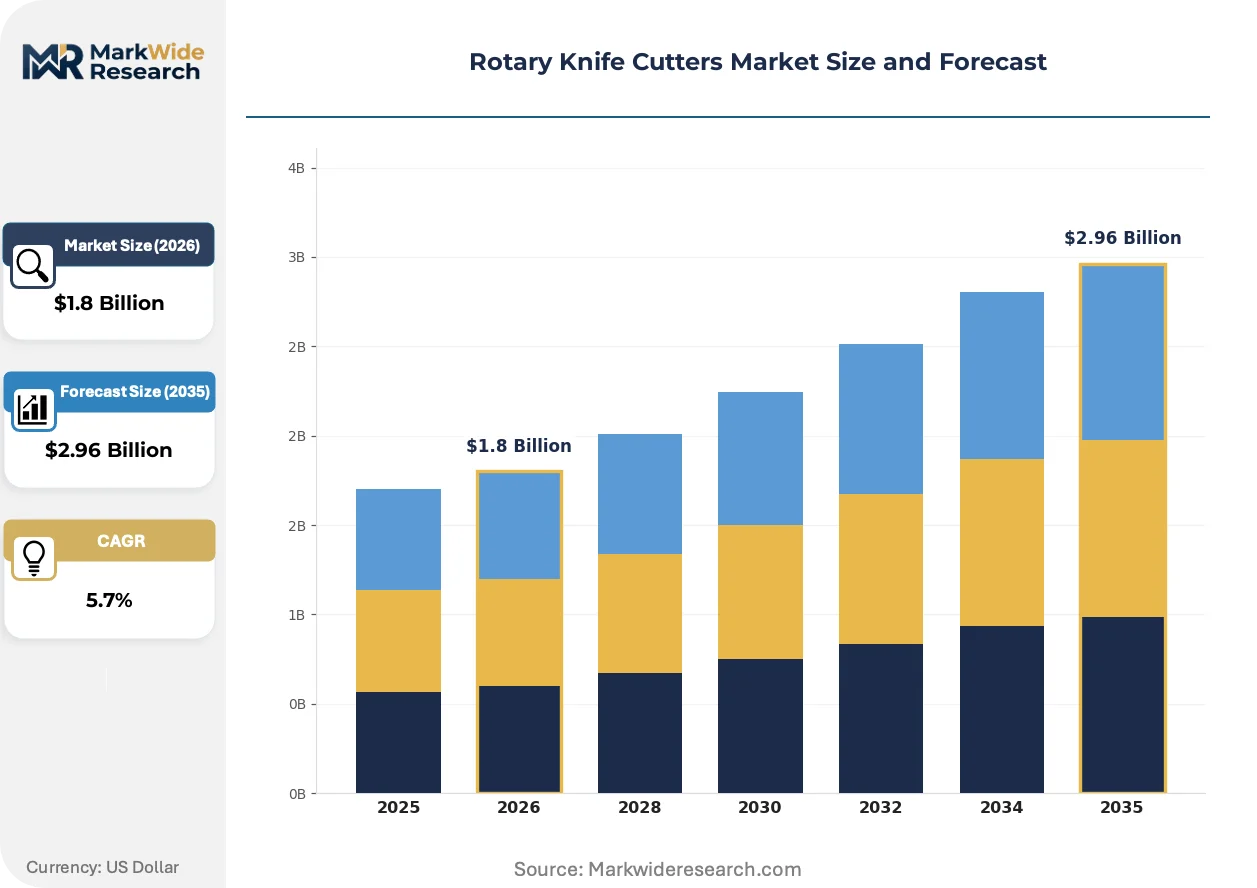
Market Dynamics
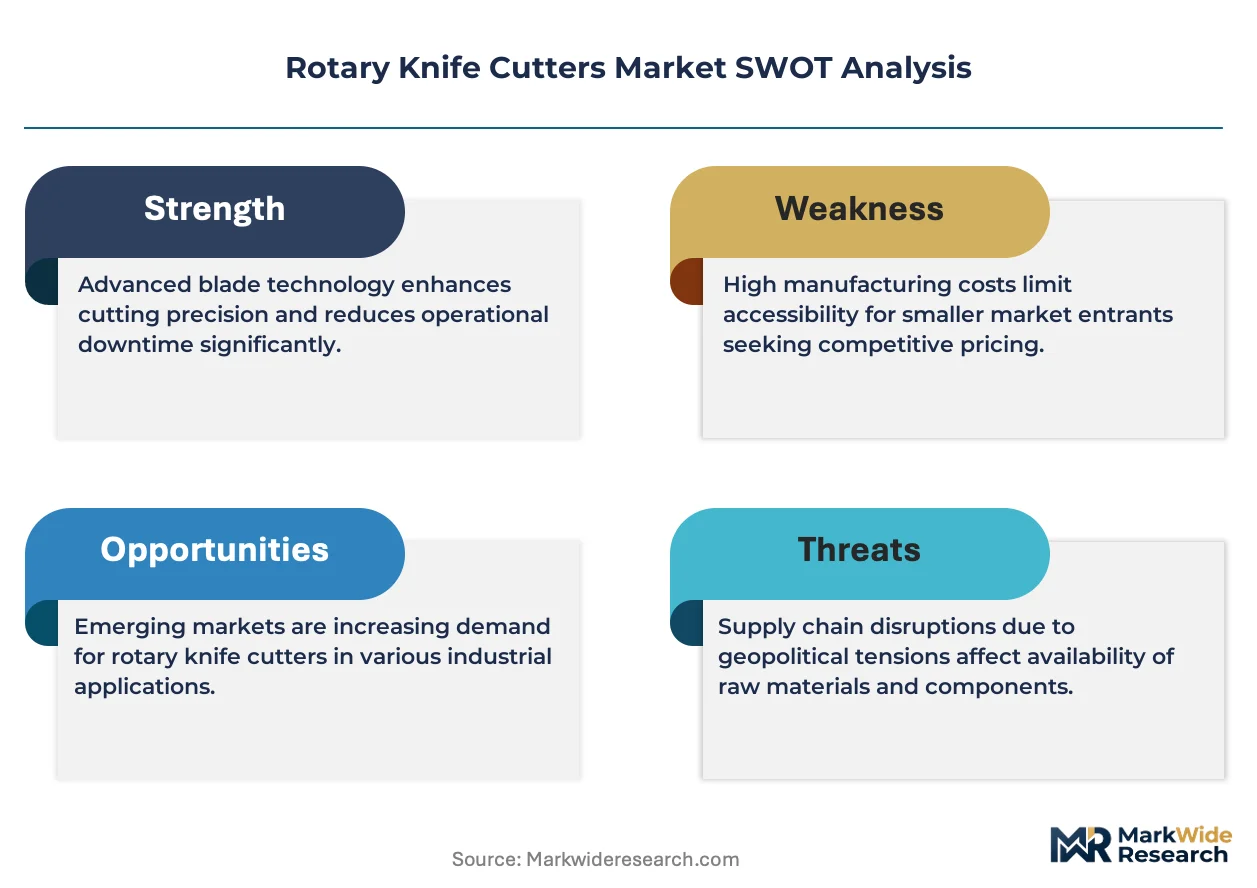
REACH substance restrictions and FDA material compliance mandates are compressing blade alloy selection cycles, forcing manufacturers to requalify coating formulations and surface treatments ahead of equipment replacement schedules. This regulatory compression accelerates R&D spend while creating differentiation gaps between certified and non-certified suppliers.
Growth Catalysts
- EU REACH compliance deadlines:Tightened substance restrictions on blade coatings contacting food substrates are driving replacement demand across European converter fleets. Manufacturers holding ECHA pre-registrations capture specification advantages.
- Flexible packaging automation:High-speed web processing lines in snack and pharmaceutical packaging are standardizing on rotary knife configurations for slit-seal operations. Format changeover demands favor adjustable blade systems.
- German precision engineering clusters:Stuttgart and Solingen manufacturing centers concentrate carbide grinding and heat-treatment expertise. Proximity to automotive and textile OEMs accelerates prototyping cycles for custom cutter geometries.
Market Restraints
- Tungsten carbide supply concentration:Primary carbide powder production concentrates in Chinese state-controlled mining operations. Price volatility in hardmetal feedstocks compresses blade margin structures for European fabricators.
- CE machinery directive compliance costs:Integrated safety enclosures and emergency stop systems elevate system-level pricing. Small converter operations defer capacity expansion due to total installed cost thresholds.
- Laser cutting substitution:Fiber laser systems achieve comparable edge quality on thin-gauge films without mechanical tooling wear. Capital-rich packaging groups pilot laser slitting for volume-stable SKUs.
Strategic Opportunities
- India food processing modernization:FSSAI enforcement of sanitary equipment standards creates certified-blade demand in dairy and spice grinding operations. Domestic cutter fabricators lack REACH-equivalent coating capabilities.
- PFAS-free coating development:Pending EU restrictions on fluorinated blade coatings open substitution windows for ceramic and diamond-like carbon alternatives. First-movers secure pharmaceutical packaging qualifications.
- Predictive maintenance integration:Blade wear sensors converging with IoT platforms enable condition-based replacement scheduling. System integrators capture recurring revenue through monitoring subscriptions.
Industry Challenges
- Precision grinding skill scarcity:Master carbide grinders with 60+ HRC hardness expertise are aging out of Solingen and Sheffield workshops. Apprenticeship pipelines fail to replenish specialized labor pools.
- Legacy equipment retrofit complexity:Adjustable blade head retrofits on fixed-spindle frames require custom shaft modifications. Engineering validation cycles delay upgrade revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Knife Cutters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Blade, Adjustable Blade, Circular Knife, Scalloped Knife Application: Packaging, Food Processing, Textile Cutting, Paper Conversion End User: Manufacturers, Food Industries, Textile Industries, Printing Industries Size: Small, Medium, Large, Extra Large |
| Companies Covered | Eastman Machine Company, Forsstrom High Frequency AB, RotoMetrics, Atlas Die (Bernal), Wilson Manufacturing, Kocher+Beck, Spilker, Wink, Drohmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Knife Cutters Market Evolving Landscape
Blade surface engineering and digital process monitoring are compressing maintenance intervals while expanding the addressable substrate range for rotary cutting systems. Equipment buyers now prioritize total cost-per-cut metrics over initial tooling expenditure.
Diamond-like carbon coatings are converging with tungsten carbide substrates to extend blade life in abrasive food contact applications. European meat processing cooperatives are piloting these treatments for poultry skinning operations. The technology is compressing blade changeover frequency from weekly to monthly intervals in high-volume facilities.
EU F-Gas Regulation phase-down schedules are pressuring cooling systems in blade heat-treatment furnaces. German heat-treatment service providers are retrofitting hydrogen-based quenching to maintain process temperatures. Medical device packaging cutters face the tightest compliance timelines due to validated process change requirements.
Converter procurement teams are consolidating vendor relationships around full-service blade management contracts. North American flexible packaging groups now specify blade sharpening, coating restoration, and inventory management as bundled deliverables. This bundling is most advanced in Wisconsin and Illinois converting corridors where equipment uptime penalties dominate sourcing decisions.
Rotary Knife Cutters Market Segmentation
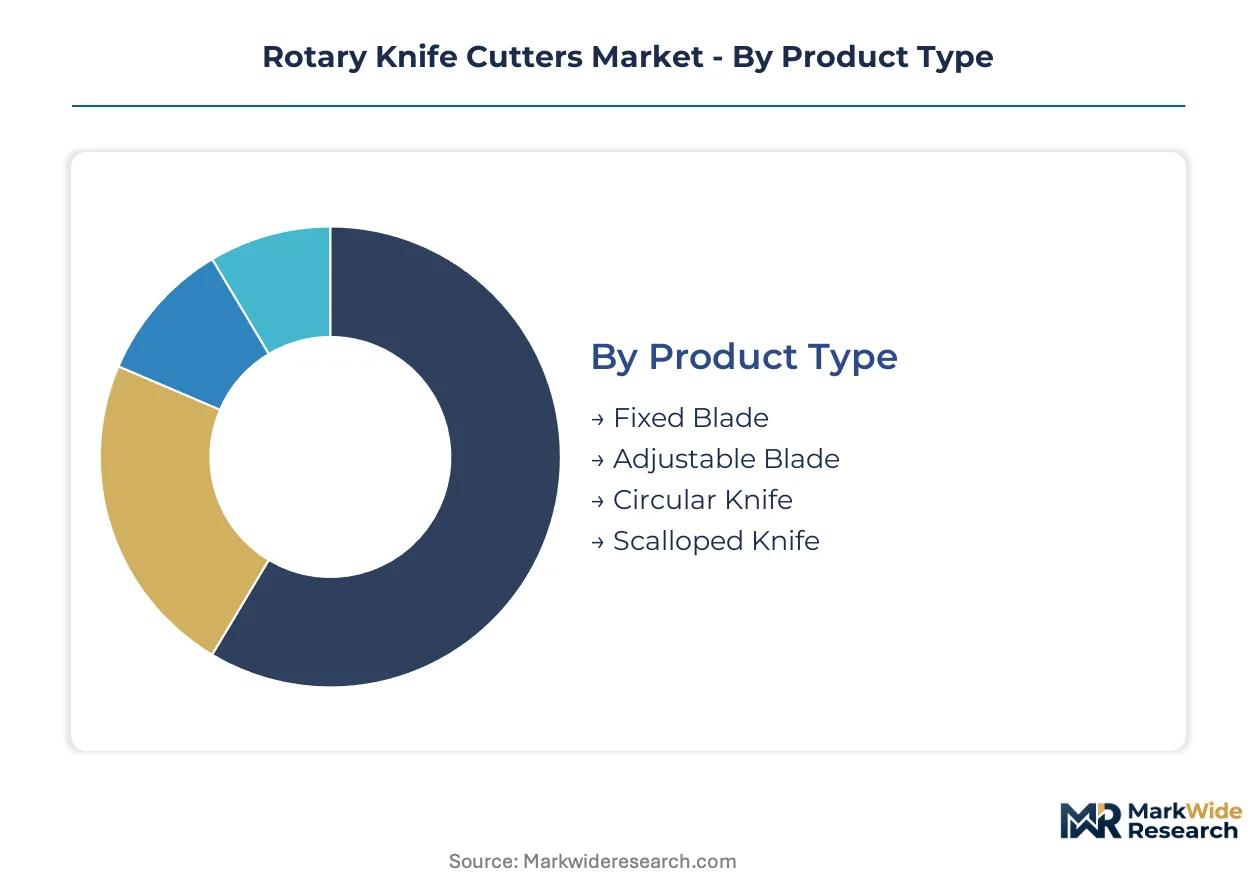
Segmentation in rotary knife cutters reveals how regulatory burden and operational intensity concentrate demand across distinct equipment categories. Procurement teams align blade specifications with substrate abrasiveness, line speed requirements, and compliance exposure in food-contact environments.
Product Type:
FDA material certifications and EU REACH substance registrations divide blade procurement into certified and non-certified supply tiers, with food-contact applications commanding premium coating qualifications.
- Fixed Blade:Single-geometry cutters machined from tool steel or solid carbide with hardness exceeding 60 HRC. Demand concentrates in German automotive textile operations and Wisconsin paper converting corridors where format stability eliminates changeover labor. CE machinery directive compliance elevates system pricing but reduces liability exposure for operators running 24-hour production schedules.
- Adjustable Blade:Modular head configurations enabling radial or axial position changes without shaft removal. Flexible packaging converters in Illinois and pharmaceutical web processors in New Jersey prioritize these systems for SKU proliferation environments. Format agility without complete tooling changeover compresses downtime costs.
- Circular Knife:Precision-ground disc cutters for longitudinal slitting operations.
- Scalloped Knife:Perforating edge geometries for tear-line applications in snack packaging.
Leading the category by volume: Fixed Blade. Expanding most quickly: Adjustable Blade.
Application:
End-use abrasiveness and sanitary design requirements create three distinct margin tiers across converter operations.
- Packaging:Slit-seal and perforating operations on film, foil, and paperboard webs. High-volume snack and pharmaceutical packaging lines in North America standardize on rotary configurations for speed consistency. FDA compliance on recycled content contact materials shapes next-generation blade coating investments.
- Food Processing:Sanitary-design blade assemblies for meat, poultry, and dairy slicing operations. EU EFSA material approvals and FDA dairy contact certifications create specification barriers. Diamond-like carbon coatings are compressing changeover intervals from weekly to monthly in high-volume European meat cooperatives.
- Textile Cutting:Continuous slitting of woven and nonwoven fabrics.
- Paper Conversion:Scoring and perforating for folding carton production.
Highest margin pool: Food Processing. Steepest expansion trajectory: Packaging automation.
End User:
Capital intensity and in-house maintenance capability determine whether buyers specify full systems or blade-only procurement.
- Manufacturers:OEM equipment builders integrating cutters into converting lines. German precision engineering clusters in Stuttgart supply carbide grinding expertise to automotive textile equipment. Proximity accelerates prototyping cycles for custom cutter geometries.
- Food Industries:Dairy cooperatives and meat processors with direct regulatory exposure. FSSAI enforcement in India creates certified-blade demand that domestic fabricators cannot satisfy with REACH-equivalent coatings.
- Textile Industries:Apparel and technical fabric converters.
- Printing Industries:Label and flexible packaging converters.
Dominant procurement volume: Manufacturers. Fastest qualification requirements: Food Industries.
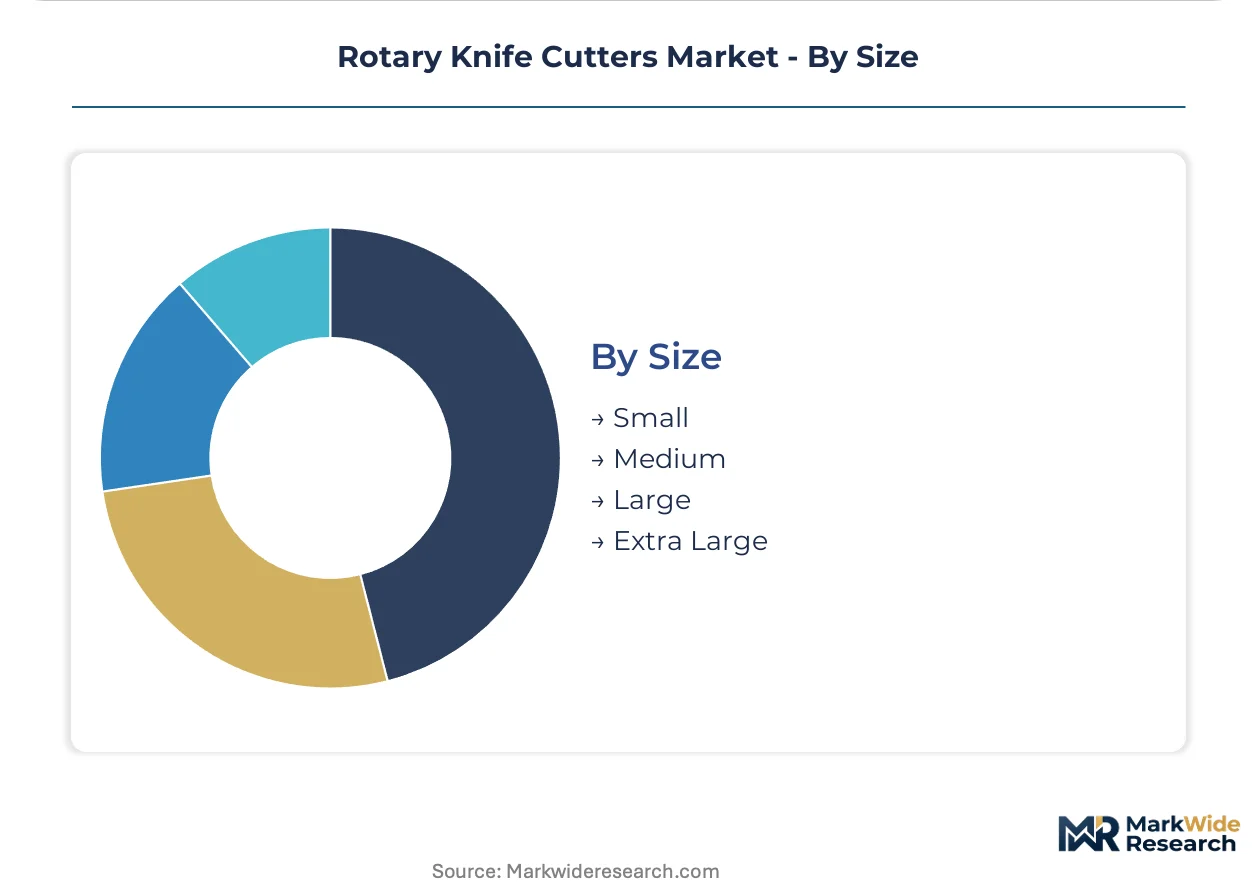
Size:
Shaft diameter and blade diameter scale with web width and substrate thickness across converting operations.
- Small:Precision cutters for narrow-web label converting and medical device packaging.
- Medium:Standard duty configurations for mid-width flexible packaging lines.
- Large:Heavy-duty assemblies for wide-format textile and paper converting.
- Extra Large:Custom-engineered systems for specialty nonwoven and composite material processing.
Volume concentration: Medium. Specification complexity: Extra Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters supply carbide grinding expertise to converter operations worldwide, while US flexible packaging automation drives blade replacement cycles. Chinese tungsten carbide feedstock concentration shapes cost structures for fabricators across importing economies.
United States
Flexible packaging automation in Wisconsin and Illinois converting corridors sustains demand for adjustable blade systems. OSHA machine guarding standards elevate total installed costs for new rotary cutter deployments. Eastman Machine Company anchors textile cutting equipment supply from Buffalo, New York manufacturing roots.
Germany
Automotive textile operations and pharmaceutical web processors in Stuttgart and Solingen drive specification-intensive procurement. EU REACH substance restrictions and CE machinery directives compress alloy selection cycles for blade coatings. Kocher+Beck exemplifies precision-ground circular knife fabrication from Solingen grinding expertise.
China
Domestic food processing modernization and export-oriented packaging machinery production expand cutter demand. State-controlled tungsten carbide mining operations concentrate hardmetal feedstock supply. Zhengzhou and Shanghai manufacturing centers supply blade assemblies to Southeast Asian converter markets.
India
FSSAI enforcement of sanitary equipment standards creates certified-blade demand in dairy and spice grinding operations. Domestic fabricators lack REACH-equivalent coating capabilities, opening import substitution windows. Maharashtra and Gujarat food processing clusters pilot automated slicing line upgrades.
Japan
Medical device packaging and precision electronics film processing sustain premium blade specifications. METI industrial standards and PMDA quality system requirements shape supplier qualification protocols. Chubu region machine tool builders integrate rotary cutters into automated converting lines for export markets.
Rotary Knife Cutters Market Competitive Landscape
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. German and US fabricators dominate precision-ground blade tiers while Asian suppliers capture volume-driven packaging segments. Strategic archetypes include precision engineering specialists, full-service blade management providers, and carbide substrate integrators. Capacity expansion in tungsten carbide grinding and strategic partnerships for coating technology access represent dominant competitive moves.
Among US-based equipment builders, Eastman Machine Company and RotoMetrics occupy distinct positioning vectors. Eastman exemplifies century-old brand recognition in textile cutting systems. RotoMetrics anchors high-volume flexible packaging contracts through die-cutting specialization. German fabricators Kocher+Beck and Spilker represent precision-ground circular knife expertise serving European label converters with REACH-registered coating formulations.
| Leading Market Players |
|---|
| Eastman Machine Company |
| Forsstrom High Frequency AB |
| RotoMetrics |
| Atlas Die (Bernal) |
| Wilson Manufacturing |
| Kocher+Beck |
| Spilker |
| Wink |
| Drohmann |
| Others |
Value Network & Pricing Analysis
Captive tungsten carbide sourcing through Chinese state-controlled mining operations anchors blade fabricators' supply positions while compressing their pricing power against feedstock volatility. This upstream concentration forces European and North American cutter manufacturers to absorb cost fluctuations or pass them through to packaging converters already sensitive to total installed system costs.
Pricing Analysis
Margin tightening in REACH-certified blade tiers reflects ECHA pre-registration costs and specialized coating formulation investments. Three-tier pricing structure across certified-premium, standard-industrial, and economy-import levels separates food-contact qualified suppliers from general packaging fabricators. Pricing pressure intensifies in adjustable blade systems as SKU proliferation demands compress converter capital budgets. Small Wisconsin and Illinois flexible packaging operations exhibit highest price sensitivity; pharmaceutical web processors in New Jersey demonstrate lowest due to validated process change costs.
Supply Chain Analysis
Dual-sourcing requirements from major North American flexible packaging groups mandate qualified backup suppliers for carbide grinding and coating restoration services. Raw material flows concentrate in Chinese tungsten carbide mining, German precision grinding clusters in Solingen, and Indian domestic blade fabrication lacking REACH-equivalent capabilities. Supply chain risk hinges on single-source vulnerability in hardmetal feedstock concentration. Distribution runs through OEM equipment builders, direct converter procurement in established corridors, and emerging third-party blade management contractors bundling sharpening and inventory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into carbide substrate production represents the decisive competitive race, with coating technology access and precision grinding capability as the primary levers separating margin leaders from price-takers.
For Market Incumbents: To counter laser cutting substitution in thin-gauge film applications, anchor customer relationships through full-service blade management contracts bundling sharpening, coating restoration, and predictive maintenance subscriptions. Deepen captive tungsten carbide sourcing through long-term offtake agreements with Chinese state-controlled mining operations to insulate margin structures from feedstock volatility. For New Entrants and Emerging Players: Capture FSSAI-certified blade demand in Maharashtra and Gujarat dairy processing clusters where domestic Indian fabricators lack REACH-equivalent coating capabilities. Target pharmaceutical web processing specifications in New Jersey and Illinois where validated process change costs deter incumbent switching. Lead with PFAS-free ceramic and diamond-like carbon coating alternatives to secure first-mover qualifications ahead of pending EU restrictions. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial tooling conglomerates seeking precision grinding capabilities and pharmaceutical packaging qualifications. Five-to-ten year viability favors fabricators with integrated coating technology and established ECHA pre-registrations. Watch for inflection in EU PFAS restriction enforcement timelines as the signal determining next-generation coating investment winners.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Development | First-movers secure pharmaceutical packaging qualifications ahead of EU ECHA restriction deadlines. |
| Backward Integration into Carbide Sourcing | Captive tungsten carbide supply insulates German and US fabricators from Chinese state-controlled price volatility. |
| Predictive Maintenance Platform Launch | Blade wear sensors converging with IoT platforms enable recurring revenue through monitoring subscriptions. |
| REACH-Equivalent Certification Investment | ECHA pre-registrations create specification barriers protecting premium margin pools in food-contact applications. |
| Full-Service Blade Management Contracts | North American flexible packaging groups in Wisconsin and Illinois prioritize bundled sharpening and inventory services. |
Research Methodology
Multi-period observation of blade replacement cycles, coating qualification timelines, and converter capital expenditure patterns anchored the trend analysis, supplemented by interviews with maintenance directors at flexible packaging operations, procurement leads at pharmaceutical web processors, precision grinding specialists in Solingen and Sheffield, and aftermarket service heads at OEM equipment builders. Secondary validation drew from FDA material compliance filings, ECHA substance registration databases, SEC 10-K disclosures from industrial tooling conglomerates, and trade data on tungsten carbide powder imports. Bottom-up blade unit demand estimates triangulated against top-down converting line installation forecasts.
Segment-weighting across product type, application abrasiveness, and end-user capital intensity shaped the analytical framework across the projection horizon. Fixed blade, adjustable blade, circular knife, and scalloped knife categories were modeled separately against food processing, packaging, textile cutting, and paper conversion demand. CAGRs derived from equipment replacement cycles, regulatory compliance retrofit obligations, and automation adoption curves in snack packaging and pharmaceutical web processing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU PFAS restriction enforcement timing, Chinese tungsten carbide export policy shifts, and laser cutting technology cost curves in thin-gauge film applications. Deviation in REACH substance restriction scope or FDA recycled content contact material guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Telescopic Tool Boxes Market
Tools
Nail Gun Market
Tools
Pliers Market
Tools
Mallets and Sledgehammers Market
Tools
Welding Guns Market
Tools
Machine Bench Vices Market
Tools
Global Vertical Grinding Machine Market
Tools
Multi Spindle Machines Market
Tools
US Hitter Based Hand Tools Market
Tools
Striking Tools Market
Tools
Woodworking Circular Saw Blades Market
Tools
Mechanical Springs Market
Tools
Wood Floor Grinding Machine Market
Tools
Gear Honing Machines Market
Tools
Self-Clinching Fasteners Market
Tools
Sanding Machine Market