
 Cutting Tools Market | 2026-2036
Cutting Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Tools Market Intelligence
Premium coated-carbide specification tiers is unwinding legacy high-speed steel volumes across metalworking supply chains. Sandvik AB leverages captive powder-metallurgy capacity to anchor European aerospace demand for thermal-barrier-coated inserts. Kennametal Inc. competes through ceramic-grade specialization in heat-resistant superalloy machining. Mitsubishi Materials Corporation dominates East Asian distribution networks for multi-flute end mills serving automotive transfer lines.
Cutting tools are machine elements with defined cutting-edge geometries, typically manufactured from cemented tungsten carbide, cobalt-enriched high-speed steel, or silicon-nitride ceramic substrates, engineered to remove material through shearing, abrasion, or fracture mechanisms at controlled surface speeds and feed rates. Carbide material grades now capture the dominant margin pool as coating technologies extend tool life in hardened-steel and titanium applications. Metalworking application demand outpaces woodworking in absolute volume, though aerospace-grade reamers and drills command the highest per-unit value within the product-type matrix.
ISO standards govern cutting-tool geometry interchangeability across CNC platforms, while REACH in Europe restricts cobalt and tungsten supply-chain exposure, pushing ceramic and cermet alternatives. OSHA machine-guarding mandates in the United States elevate demand for predictable-wear inserts that reduce catastrophic tool-failure incidents. Stakeholders must weigh raw-material substitution timelines against certification costs for new substrate formulations entering regulated end-use channels.
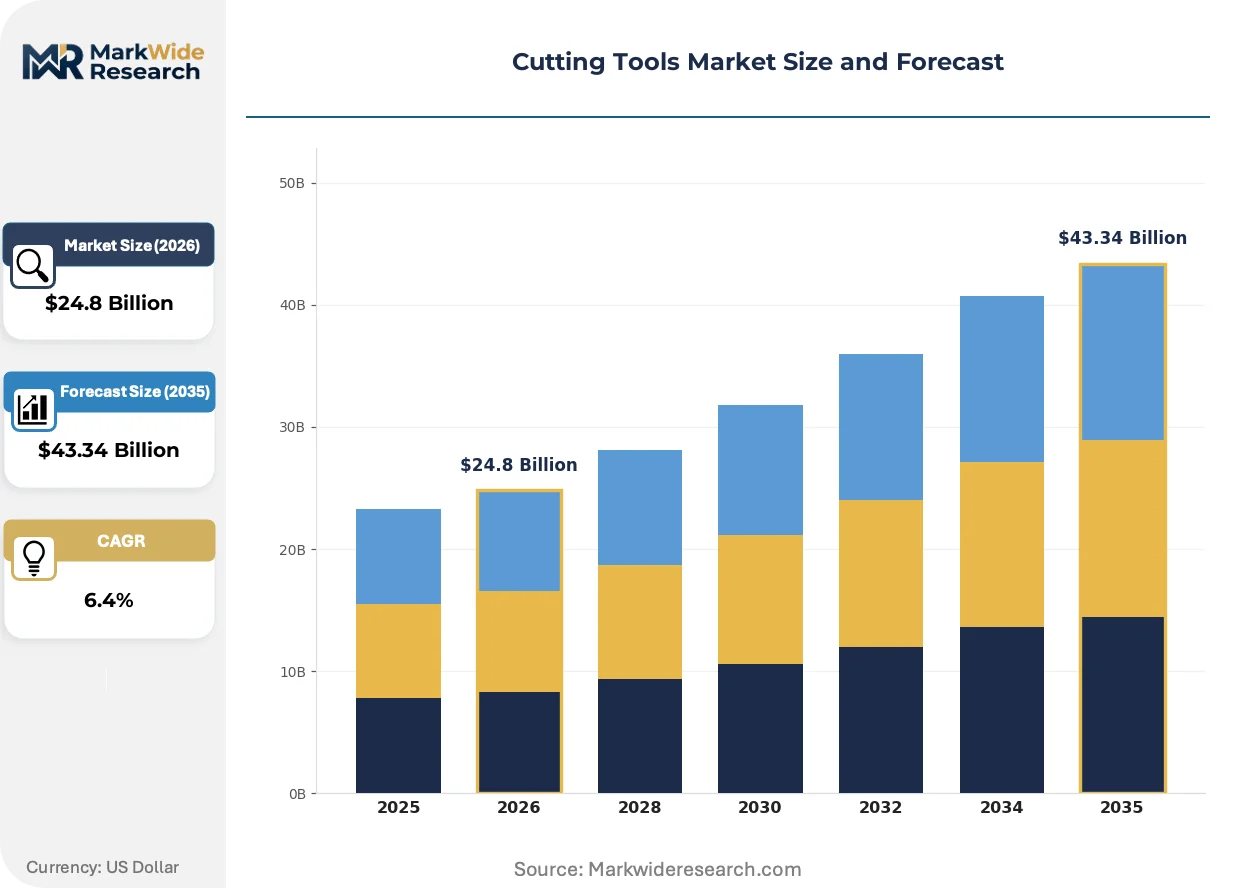
Market Dynamics
Coated carbide technology is compressing high-speed steel volumes across aerospace and automotive supply chains, while REACH compliance costs accelerate raw-material substitution timelines for tungsten-dependent grades.
Growth Catalysts
- ISO 13399 Digital Tool Cataloging:Aerospace manufacturers in Germany and Japan now mandate digitally interoperable insert geometries, forcing suppliers to retool specification databases and capturing premium pricing for certified data packages.
- Titanium Machining Intensity:Heat-resistant superalloy workpiece demand from commercial aviation OEMs is pulling multi-flute coated carbide specifications into machine shop upgrade cycles across East Asian precision clusters.
- OSHA Machine-Guard Mandates:United States metalworking facilities face elevated liability exposure from catastrophic tool failures, driving predictable-wear insert specifications that reduce unplanned spindle downtime.
Market Restraints
- Tungsten Supply Concentration:Chinese state-controlled mining entities dominate raw carbide powder supply, exposing European and Japanese insert manufacturers to export quota volatility and price spikes.
- Cobalt Substitution Friction:REACH Annex XVII restrictions on cobalt exposure in metalworking fluids are forcing reformulation of cemented carbide binders, with cermet alternatives failing to match toughness in interrupted cuts.
- Ceramic Brittleness Ceiling:Silicon-nitride grades cannot yet match carbide reliability in roughing applications with variable chip loads, limiting penetration beyond finishing operations in hardened steel.
Strategic Opportunities
- India Precision Manufacturing Expansion:PLI scheme incentives for domestic aerospace component production are creating first-mover advantage for coated-carbide distributors establishing local technical service centers.
- Hybrid Additive-Subtractive Workflows:Near-net-shape metal printing from EOS and SLM Solutions is generating demand for specialized finishing end mills with optimized edge geometries for as-printed surfaces.
- EU Green Deal Carbon Border Adjustments:Embedded emissions accounting for imported cutting tools will favor European powder-metallurgy producers with renewable energy-intensive captive tungsten reduction capacity.
Industry Challenges
- Grinding Technician Scarcity:Precision insert edge preparation requires skilled operators fluent in diamond wheel selection and spark-out protocols, with vocational pipeline gaps acute in Midwestern United States manufacturing zones.
- Multi-Substrate Certification Timelines:Aerospace OEM qualification protocols for new cermet or ceramic grades demand 18-24 month validation cycles, locking capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Tools Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
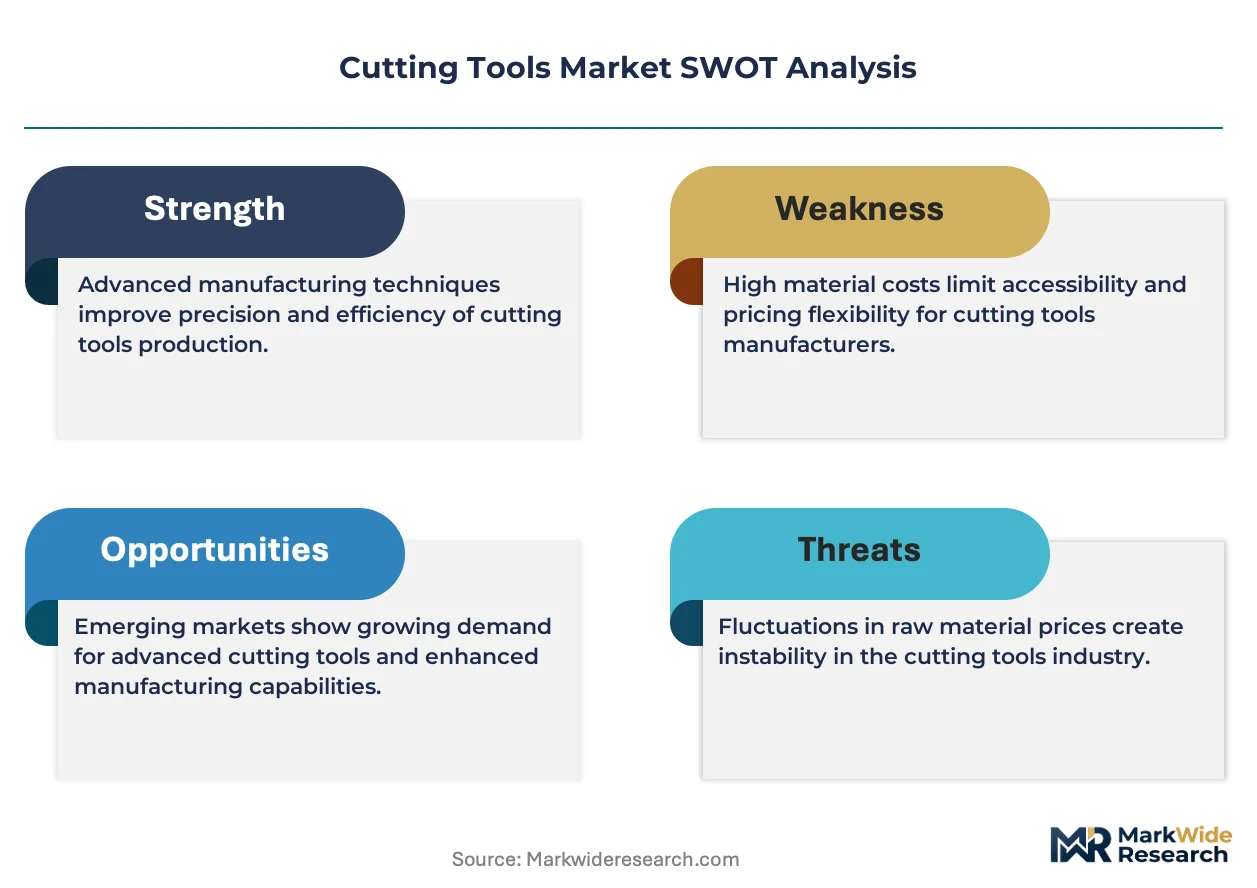
| Segmentation | Product Type: End Mills, Drills, Taps, Reamers Material: High-Speed Steel, Carbide, Cobalt, Ceramic Application: Aerospace, Automotive, Woodworking, Metalworking End User: Manufacturers, OEMs, Machine Shops, Fabricators |
| Companies Covered | Kyocera Corporation, Iscar Ltd., Sandvik AB, Ceratizit S.A., Tungaloy Corporation, Kennametal Inc., Seco Tools AB, Guhring KG, Mitsubishi Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Tools Market Strategic Shifts & Innovations
Physical vapor deposition coating architectures are fragmenting the premium insert tier, while digital thread integration between CAM systems and tool databases compresses specification-to-spindle lead times.
Multi-layer CVD-Al2O3 thermal barrier coatings is bifurcating the high-performance insert segment. Aerospace turbine component manufacturers now specify these grades exclusively for Inconel roughing, while general machining shops retain uncoated or single-layer PVD alternatives for mild steel. The technology is bifurcating margin pools between thermal-fatigue-resistant premium tiers and commodity finishing grades.
REACH authorization requirements for cobalt compounds are tightening supply-chain due diligence obligations across European metalworking distributors. ECHA's 2024 updated guidance on occupational exposure limits is forcing coolant system upgrades and accelerating ceramic-grade trials in German automotive transfer lines. Tier-two suppliers without captive powder capacity face exclusion from qualified vendor lists.
Tool-as-a-service contracting is displacing transactional insert procurement in high-volume automotive applications. Tier-one suppliers now bundle per-component pricing with predictive wear monitoring, capturing multi-year sole-source relationships. This model concentrates fastest in Japanese and South Korean precision machining clusters where OEMs demand guaranteed uptime commitments.
Cutting Tools Market Segmentation
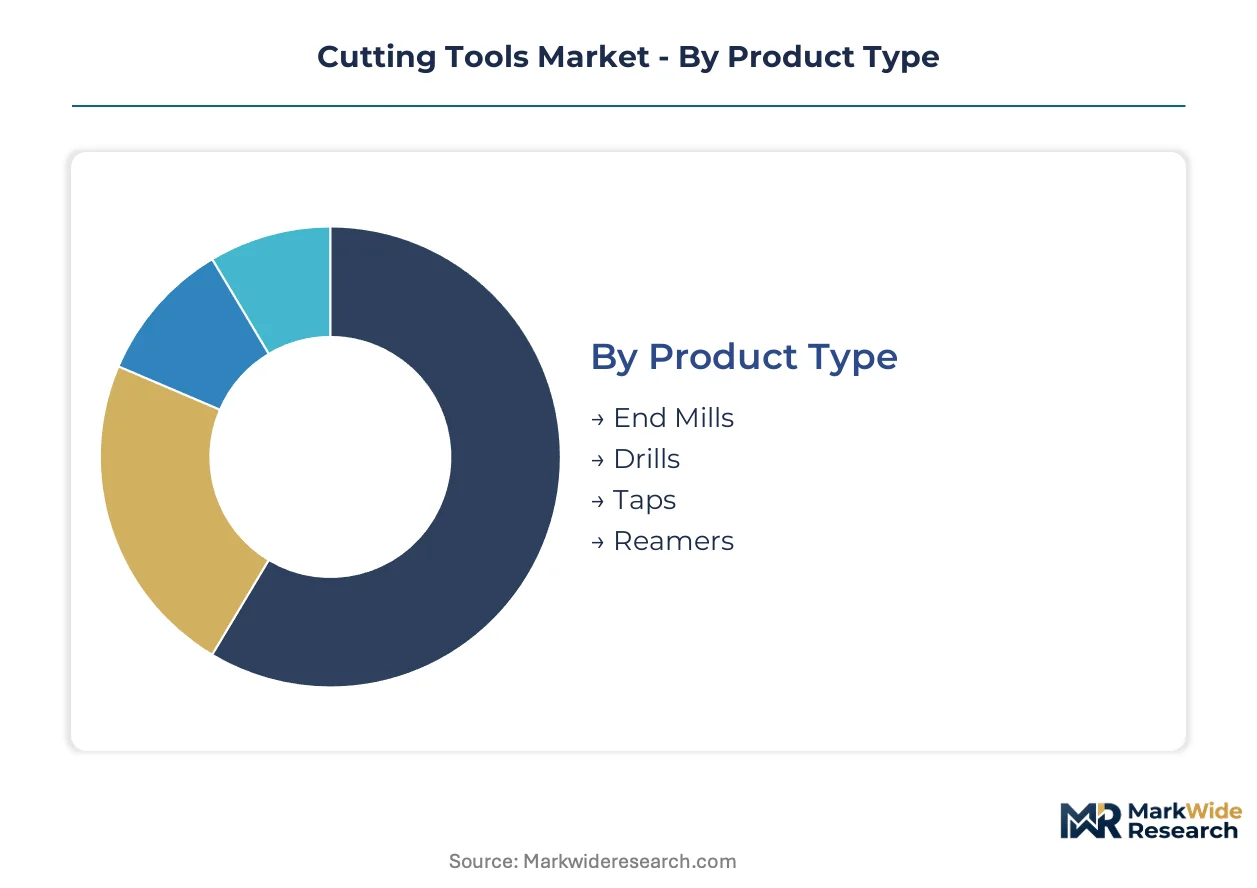
Cutting tools exhibit pronounced specification fragmentation across substrate chemistry, edge geometry, and end-use certification tiers. Channel economics vary sharply: aerospace-grade inserts flow through distributor technical-service networks, while commodity HSS drills move via industrial catalog houses. Understanding segment-channel coupling reveals where margin pools concentrate and where volume scales.
Product Type:
Distribution channels diverge by tool complexity and regrind economics, with indexable inserts commanding dedicated sales engineering while solid round tools flow through broader industrial distribution.
- End Mills:Multi-flute geometries in coated carbide dominate titanium and Inconel roughing cycles in East Asian precision machining clusters. Mitsubishi Materials anchors distribution networks for automotive transfer line specifications, while specialized coating architectures from European suppliers capture aerospace finishing margins.
- Drills:Solid carbide and replaceable-tip designs split between high-volume automotive production and job-shop flexibility requirements. Sandvik AB leverages captive powder-metallurgy capacity to supply German aerospace manufacturers with coolant-fed deep-hole geometries certified to ISO 13399 digital standards.
- Taps:Thread-forming and cutting variants serve differentiated workpiece hardness ranges, with coated HSS-Co retaining share in mild steel applications where carbide economics fail.
- Reamers:Precision finishing tools command highest per-unit value in aerospace landing gear and engine component machining, with multi-diameter expansion designs favored for tight-tolerance bores.
End mills dominate installed base by cutting-edge count. Drills represent where expansion concentrates as near-net-shape additive workflows multiply finishing operations per component.
Material:
Cost tiers stratify sharply between commodity high-speed steel and premium coated-carbide specifications, with ceramic grades occupying an emerging premium position for superalloy finishing.
- High-Speed Steel:Cobalt-enriched M35 and M42 grades retain volume in woodworking and mild steel applications where tool cost dominates life-cycle economics. Kennametal Inc. competes through specialized HSS-Co taps for automotive powertrain transfer lines.
- Carbide:Cemented tungsten carbide with multi-layer CVD-Al2O3 thermal barrier coatings now anchors aerospace roughing specifications. REACH compliance costs and Chinese tungsten supply concentration are accelerating raw-material substitution timelines for European and Japanese insert manufacturers.
- Cobalt:Binder-phase chemistry faces ECHA occupational exposure limit tightening, forcing reformulation toward nickel and iron alternatives with reduced toughness in interrupted cuts.
- Ceramic:Silicon-nitride grades penetrate hardened-steel finishing where thermal stability outweighs brittleness constraints, with silicon-carbide whisker-reinforced variants gaining trials in German automotive heat-resistant superalloy machining.
Carbide dominates installed base by revenue contribution. Ceramic grades represent where expansion concentrates as coating technologies extend thermal-fatigue resistance.
Application:
Customer maturity and certification requirements fragment procurement patterns, with aerospace mandating qualified supplier lists while automotive favors tool-as-a-service contracting.
- Aerospace:Commercial aviation OEMs specify thermal-barrier-coated inserts exclusively for Inconel and titanium turbine component machining, with 18-24 month qualification protocols locking out unproven substrate formulations.
- Automotive:High-volume transfer lines in Japan and South Korea drive predictive-wear monitoring bundles and per-component pricing models that displace transactional insert procurement.
- Woodworking:PCD-tipped and solid carbide routers serve furniture and construction material processing, with uncoated HSS retaining share in softwood roughing.
- Metalworking:General machining shops span the full specification range, with East Asian clusters upgrading from HSS to coated carbide for hardened-steel workpieces.
Metalworking dominates installed base by absolute volume. Aerospace represents where expansion concentrates as narrow-body production rates recover and engine OEMs outsource precision component machining.
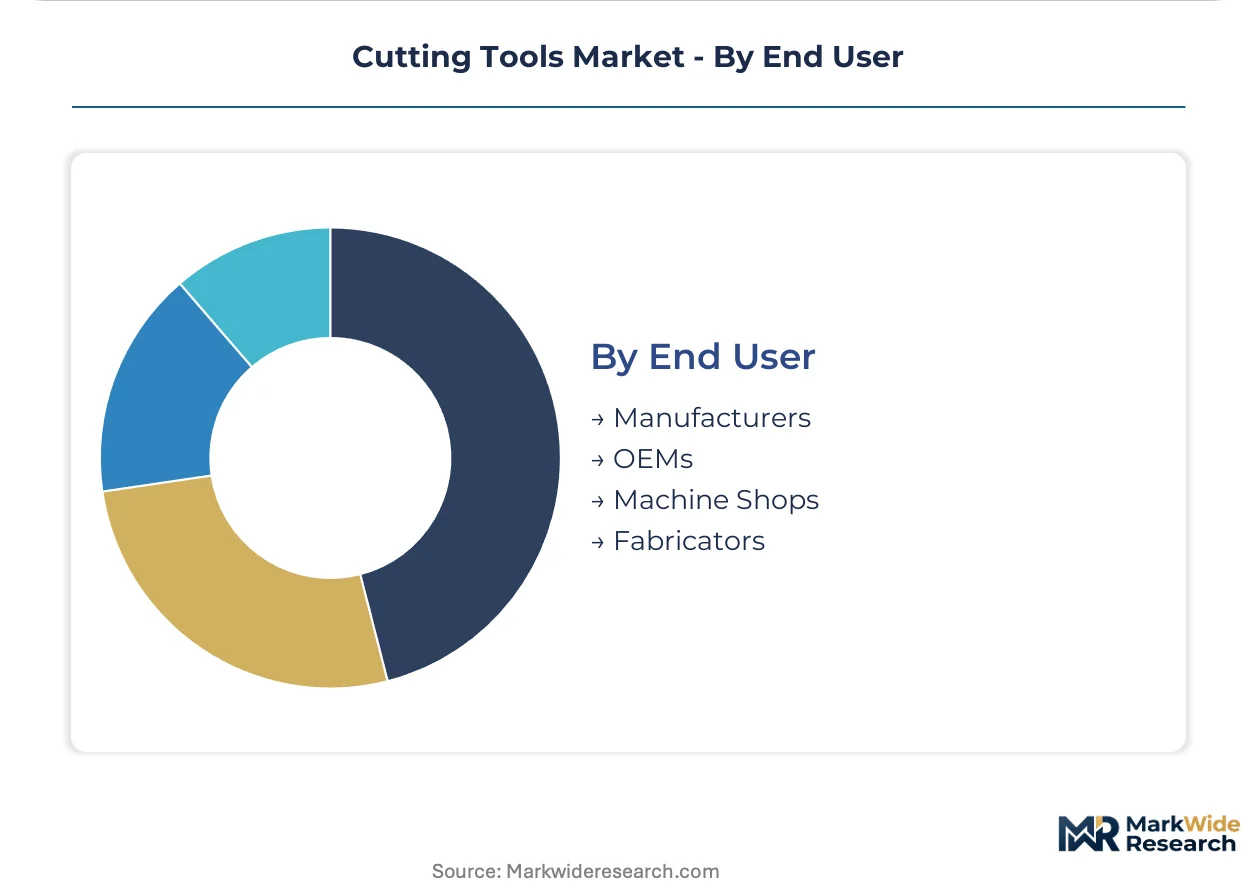
End User:
Procurement sophistication varies by scale and in-house metrology capability, with OEMs demanding digital tool data interoperability while job shops prioritize local distributor inventory availability.
- Manufacturers:Tier-one aerospace and automotive component producers mandate ISO 13399-compliant tool databases and captive regrind facilities to control specification consistency.
- OEMs:Original equipment manufacturers in commercial aviation and power generation specify qualified cutting tool suppliers through approved vendor lists with multi-year sole-source commitments.
- Machine Shops:Independent precision machining facilities in Germany and Japan upgrade spindle capabilities to accommodate multi-flute coated carbide specifications for titanium workpieces.
- Fabricators:Structural metal and plate processing operations favor indexable milling systems with quick-change adaptors over solid tool investments.
Machine shops dominate installed base by facility count. OEMs represent where expansion concentrates as outsourcing trends concentrate precision machining demand at qualified tier-one suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese state-controlled mining entities dominate raw carbide powder supply, exposing European and Japanese insert manufacturers to export quota volatility. Aerospace manufacturers in Germany and Japan are expanding orders for carbide-grade inserts as stricter ISO 13399 tool data standards push suppliers toward digitally cataloged geometries.
Germany
Aerospace turbine component manufacturers specify multi-layer CVD-Al2O3 thermal barrier coatings exclusively for Inconel roughing. REACH Annex XVII restrictions on cobalt exposure in metalworking fluids are forcing coolant system upgrades across Baden-Württemberg precision clusters. Machine shops in Stuttgart and Aalen upgrade spindle capabilities to accommodate multi-flute coated carbide specifications for titanium workpieces.
Japan
Commercial aviation OEMs pull multi-flute coated carbide specifications into machine shop upgrade cycles across precision machining clusters. METI industrial standards govern cutting-tool geometry interchangeability across CNC platforms, accelerating digital tool database adoption. Nagoya-based automotive transfer lines drive predictive-wear monitoring bundles and per-component pricing models that displace transactional insert procurement.
United States
OSHA machine-guarding mandates elevate demand for predictable-wear inserts that reduce catastrophic tool-failure incidents in metalworking facilities. The Department of Labor enforces elevated liability exposure protocols from unplanned spindle downtime events. Midwestern manufacturing zones in Michigan and Ohio face acute vocational pipeline gaps for grinding technicians fluent in diamond wheel selection.
China
East Asian precision machining clusters upgrade from high-speed steel to coated carbide for titanium and hardened-steel workpieces. MIIT industrial policy supports domestic powder-metallurgy capacity expansion to reduce import dependence for aerospace-grade substrates. Shenzhen and Suzhou machine tool builders integrate ISO 13399-compliant tool databases into native CAM platforms for export markets.
India
PLI scheme incentives for domestic aerospace component production create first-mover advantage for coated-carbide distributors establishing local technical service centers. BIS certification requirements for imported cutting tools favor suppliers with captive metrology facilities. Bangalore and Hyderabad precision manufacturing parks attract tier-one suppliers seeking qualification for narrow-body engine component outsourcing contracts.
Cutting Tools Market Key Industry Players
Concentration sits with diversified materials conglomerates and specialized cutting-tool engineering houses. The vendor base spans captive powder-metallurgy operators, coating-technology licensors, and regional distribution specialists. Two strategic archetypes dominate: integrated substrate-to-insert manufacturers controlling tungsten supply chains, and application-focused engineering houses anchoring aerospace qualified vendor lists. Competitive moves center on M&A for powder-metallurgy capacity and strategic partnerships for digital tool data interoperability.
Within the integrated materials tier, Sandvik AB and Mitsubishi Materials Corporation exemplify archetypes of European and East Asian supply chain control. Among specialized engineering houses, Kennametal Inc. and Tungaloy Corporation occupy positions in ceramic-grade and coated-carbide specialization vectors. Guhring KG represents German precision tool engineering with distribution network depth. These named entities anchor competitive dynamics without exhausting the field of active participants.
| Leading Market Players |
|---|
| Kyocera Corporation |
| Iscar Ltd. |
| Sandvik AB |
| Ceratizit S.A. |
| Tungaloy Corporation |
| Kennametal Inc. |
| Seco Tools AB |
| Guhring KG |
| Mitsubishi Materials Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month aerospace qualification cycles concentrate pricing power among incumbent suppliers with captive powder-metallurgy capacity, while REACH compliance costs and Chinese tungsten export quotas compress margins for tier-two distributors dependent on spot-market carbide powder. This lead-time asymmetry rewards backward-integrated manufacturers commanding sole-source relationships with German and Japanese OEMs.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European cutting-tool markets, forcing three-tier pricing stratification across premium certified-grade, standard coated-carbide, and economy high-speed-steel specifications. Price differentiation rests on ISO 13399 digital certification status and thermal-barrier coating architecture, with aerospace-grade inserts commanding substantial premiums over general-machining alternatives. Cost compression in commodity HSS tiers is intensifying because East Asian precision clusters upgrade spindle capabilities en masse. Job shops in metalworking applications exhibit highest price sensitivity, while commercial aviation OEMs prioritize predictable-wear performance over unit economics.
Supply Chain Analysis
Chinese state-controlled mining entities dominate raw carbide powder supply, exposing European and Japanese insert manufacturers to export quota volatility and price spikes. Tungsten concentrate, cobalt binder alloys, and silicon-nitride ceramic precursors draw from geographically concentrated extraction and processing nodes. Single-source vulnerability concentrates in tungsten powder supply chains, where alternative sourcing timelines stretch across multiple qualification cycles. Distribution runs through technical-service networks for aerospace-grade specifications and industrial catalog houses for commodity solid-round tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cutting-tools market sits in a cyclical recovery phase driven by narrow-body production rate normalization and outsourced precision component machining demand from commercial aviation OEMs.
For Market Incumbents: Secure captive tungsten reduction capacity to defend against Chinese export quota volatility and REACH-driven raw-material substitution timelines. Deepen technical-service infrastructure in Indian precision manufacturing parks to capture PLI scheme-driven aerospace component outsourcing. Prioritize ISO 13399 digital database certification to maintain premium pricing in German and Japanese qualified vendor lists.
For New Entrants and Emerging Players: Anchor in Indian technical-service center establishment, where BIS certification requirements and domestic aerospace incentives create first-mover whitespace absent entrenched distributor networks. Target hybrid additive-subtractive finishing end mills for near-net-shape metal printing workflows, a segment lacking specialized edge geometry suppliers. Pursue tool-as-a-service contracting models to displace transactional procurement in South Korean automotive transfer lines.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because powder-metallurgy capacity scarcity and 18-24 month aerospace qualification protocols erect structural barriers against new substrate formulations. Acquisition candidates include regional distributors with captive metrology facilities and ceramic-grade specialization engineering houses. Monitor Chinese tungsten export quota announcements as the critical inflection signal for raw-material cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Powder Metallurgy | Captive reduction capacity insulates Sandvik AB and Mitsubishi Materials from Chinese export quota volatility. |
| ISO 13399 Digital Tool Database Certification | Aerospace OEMs in Germany and Japan mandate interoperable geometries, locking out uncertified competitors. |
| Technical Service Center Expansion in India | PLI scheme incentives for domestic aerospace production reward first-mover distributors with local qualification capabilities. |
| Hybrid Additive-Subtractive Finishing End Mill Development | EOS and SLM Solutions near-net-shape printing generates demand for specialized edge geometries on as-printed surfaces. |
| Predictive Wear Monitoring Bundle Launch | Tool-as-a-service contracting displaces transactional procurement in Japanese and South Korean automotive transfer lines. |
Research Approach
A spread of perspectives from powder-metallurgy plant managers, aerospace procurement leads at tier-one suppliers, distributor technical-service directors, and grinding technician training coordinators converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of diversified materials conglomerates, ECHA REACH authorization databases, and customs records of tungsten concentrate trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include substrate chemistry tiers, edge geometry specifications, end-use certification requirements, and regional regulatory clusters. CAGRs were derived from installed base evolution and replacement cycle intensity across the projection horizon. Forecast inputs incorporated machine-tool spindle capability upgrade rates in East Asian precision clusters and commercial aviation OEM outsourcing contract awards.
Material uncertainties — Chinese tungsten export quota policy shifts, ECHA cobalt exposure limit revisions, and ceramic-grade aerospace qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions documented in stakeholder interviews and secondary source triangulation. Practitioners should keep alternative scenarios live as REACH authorization requirements and MIIT industrial policy directives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cutting Tool Inserts Market
Tools
Vinyl Bending Machine Market
Tools
Screw Fastener Market
Tools
Global Tool Holder Adapters Market
Tools
Surface Levelling Equipment Market
Tools
L Allen Wrench Market
Tools
Oxy-Fuel Torches Market
Tools
Structural Wood Screws Market
Tools
GCC Machine Tools Market
Tools
Tile Cutter Market
Tools
Metal Cutting Machine Market
Tools
Drain Cleaning Equipment Market
Tools
Edging Tool Market
Tools
China Power Tools Market
Tools
Blowing Torch Market
Tools
Hydraulic Tools and Equipment Market