
 Step Ladder Market | 2026-2036
Step Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Step Ladder Market Analytics
Aluminum is restructuring step ladder economics as manufacturers reduce unit weight by fifteen to twenty percent versus traditional steel counterparts. Werner Co. leverages captive extrusion capacity across North American facilities to control alloy sourcing costs. Louisville Ladder anchors its position through specialized fiberglass formulations targeting electrical utility contractors. ZARGES competes on precision-engineered folding mechanisms designed for European trade professionals.
A step ladder constitutes a self-supporting, A-frame climbing apparatus with flat steps and a hinged spreader lock, typically manufactured through aluminum extrusion, fiberglass pultrusion, or hardwood lamination, and rated by duty capacity to enable safe elevated access in maintenance, construction, and household tasks. Fiberglass models command premium positioning due to dielectric properties essential for electrical work, while telescopic ladders represent the fastest-expanding product type as urban storage constraints intensify. Multi-purpose ladders concentrate margin pools through attachment ecosystems that extend utility across residential and commercial end users.
OSHA establishes duty ratings and labeling mandates that determine commercial procurement eligibility, while ANSI Type IAA standards define load-bearing thresholds for industrial applications. The EU Machinery Directive and CE marking requirements shape export compliance costs for Asian manufacturers serving European distribution channels. Stakeholders must monitor evolving material certification protocols and duty-rating harmonization across jurisdictions to sustain product line profitability.
Market Dynamics
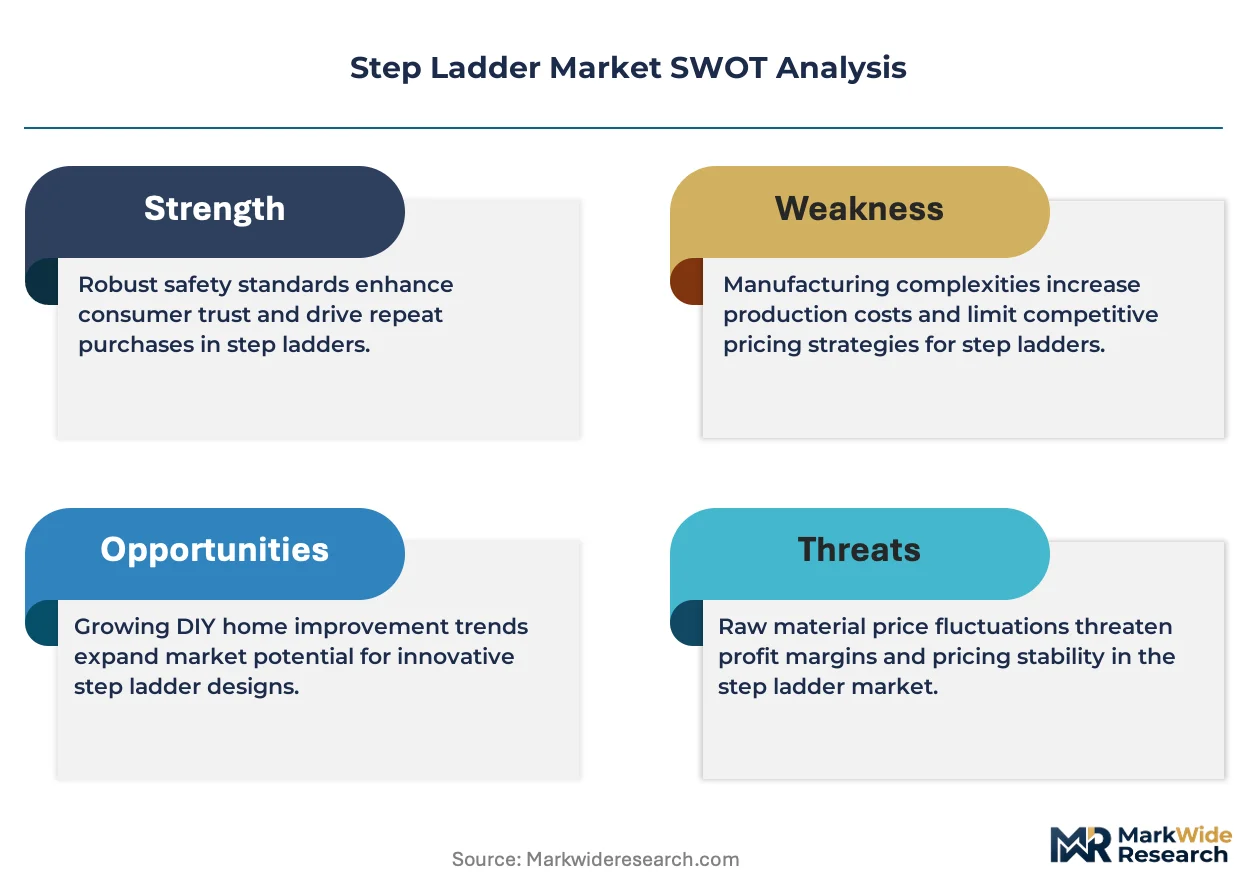
OSHA duty-rating certification tightening is compressing commercial procurement eligibility, forcing manufacturers to reconfigure alloy specifications and testing protocols to maintain contractor channel access.
Growth Catalysts
- ANSI Type IAA load-bearing mandates:Industrial facilities across the United States face stepped-up inspection schedules, compelling fleet replacement cycles that favor certified fiberglass and aluminum models with documented duty ratings.
- Residential renovation surge:Home improvement contractors in suburban markets are procuring lightweight aluminum variants for interior finishing work, expanding the addressable base beyond traditional commercial buyers.
- Telescopic mechanism adoption:Urban apartment dwellers facing storage constraints are absorbing compact folding designs, opening incremental volume in the consumer segment previously served by fixed-frame alternatives.
Market Restraints
- Aluminum alloy price volatility:Extrusion-grade 6061-T6 billet costs fluctuate with energy-intensive smelting economics, compressing margin stability for manufacturers without captive metal supply.
- Fiberglass resin supply concentration:Pultrusion-grade epoxy and vinyl ester formulations depend on petrochemical feedstocks concentrated in Gulf Coast refining corridors, exposing producers to hurricane-season disruption.
- Wood ladder substitution persistence:Heritage craftsmen and specialty finish carpenters in premium residential segments continue specifying hardwood lamination for aesthetic compatibility, limiting full conversion to engineered materials.
Strategic Opportunities
- Electrical utility contractor specialization:Dielectric fiberglass formulations targeting transmission line maintenance crews offer premium positioning insulated from commodity aluminum competition.
- Multi-purpose attachment ecosystems:Modular platforms, tool trays, and stabilizer bars extend single-ladder utility across painting, HVAC, and gutter maintenance applications, capturing share-of-wallet expansion.
- EU Machinery Directive compliance services:Asian manufacturers serving European distribution channels require CE marking navigation support, creating advisory and testing revenue streams for certification specialists.
Industry Challenges
- Welding technician scarcity:Precision aluminum extrusion joint fabrication and robotic seam welding require skilled labor pools that regional manufacturing clusters struggle to replenish.
- OSHA recertification timeline compression:Duty-rating label renewal cycles and third-party load-testing documentation create administrative bottlenecks that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Step Ladder Market |
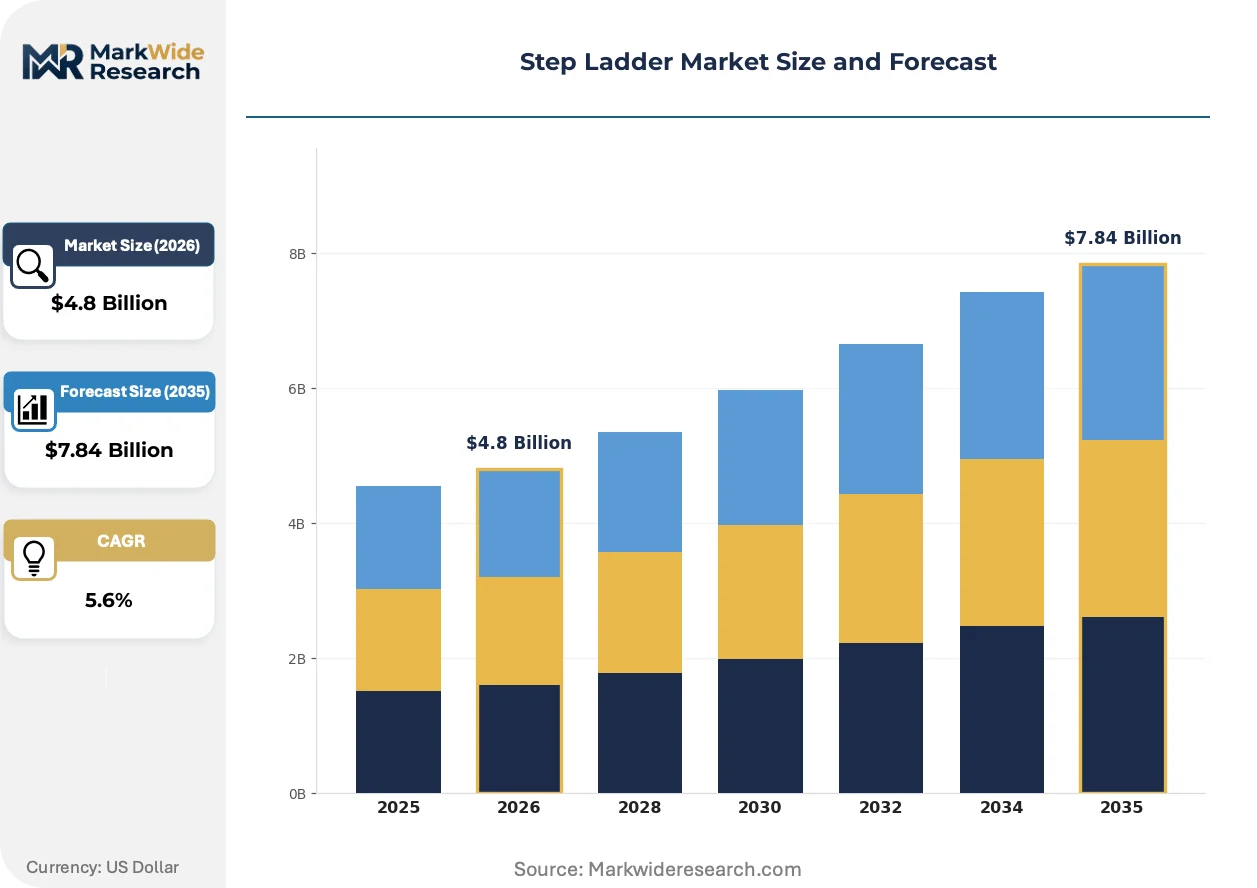
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Ladders, Multi-Purpose Ladders, Telescopic Ladders, Step Stool Ladders Material: Aluminum, Fiberglass, Wood, Steel End User: Residential, Commercial, Industrial, DIY Enthusiasts Height: 4 Feet, 6 Feet, 8 Feet, 10 Feet |
| Companies Covered | Gorilla Ladders, ZARGES, Werner Co., ShangShuo Ladder, Altrex, Louisville Ladder, Hailo, AOPENG, Little Giant Ladder Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Step Ladder Market Evolving Landscape
Material science convergence and regulatory precision are redefining competitive advantage, shifting differentiation from basic load capacity toward certified safety integration and space-efficient engineering.
Carbon fiber hybrid layups are absorbing structural loads in premium telescopic ladder segments, reducing packed dimensions by one-third compared to conventional aluminum equivalents. Electrical contractors in high-voltage environments are specifying these models despite cost premiums, compressing the addressable market for basic fiberglass alternatives in specialized applications.
REACH substance restrictions on hexavalent chromium surface treatments are forcing European manufacturers to convert to trivalent passivation and ceramic coating alternatives. The transition adds process steps and capital requirements, most acutely affecting mid-tier producers serving German and French distribution networks who lack scale to absorb compliance costs.
Specification-driven procurement through contractor purchasing cooperatives is consolidating buyer power in the United States commercial segment. Independent hardware distributors face margin compression as national accounts negotiate direct manufacturer relationships, shifting volume through centralized procurement platforms serving multi-state construction firms.
Step Ladder Market Segmentation
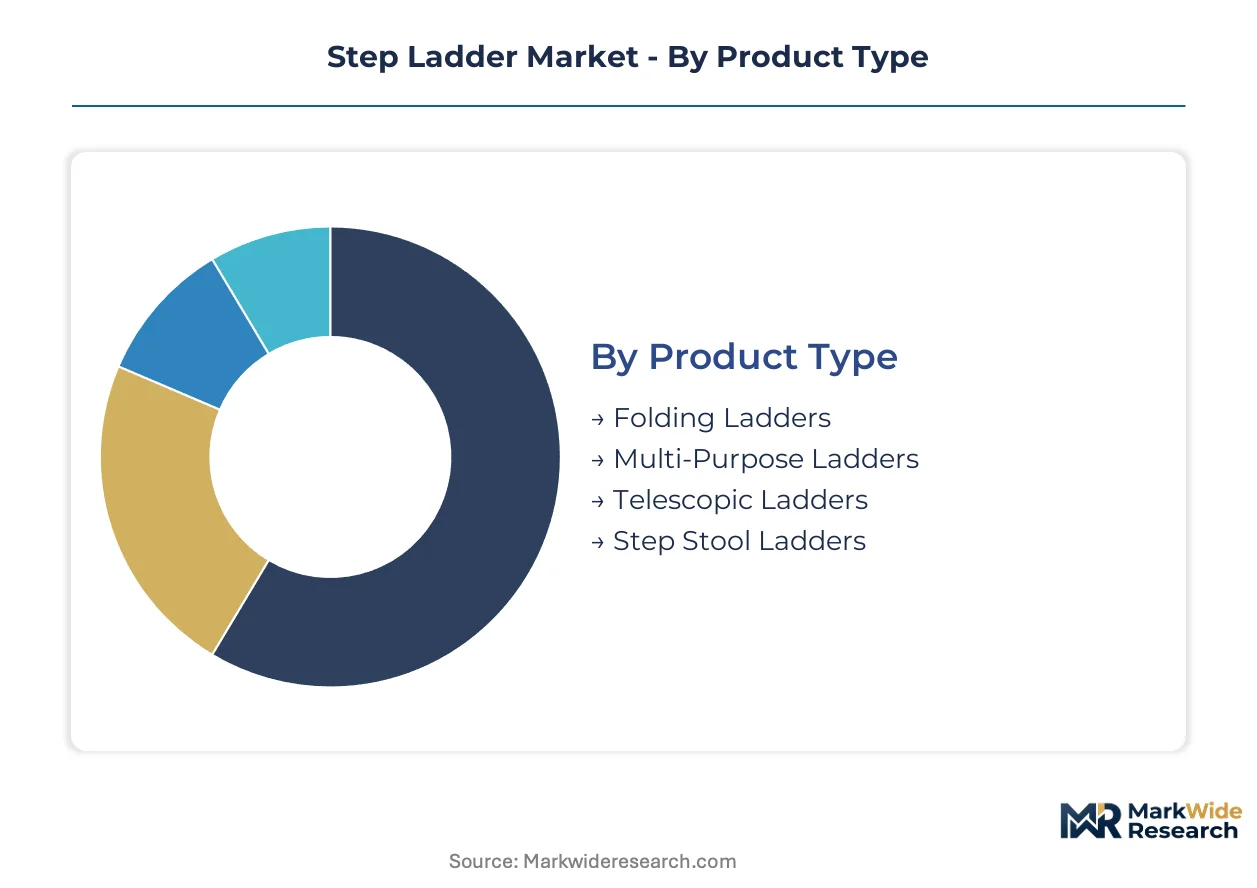
Step ladder purchasing decisions split sharply between specification-driven commercial procurement and convenience-oriented residential selection. Material certification requirements and duty ratings create tiered qualification barriers that reshape competitive dynamics across each segment boundary.
Product Type:
Volume concentrates in fixed-frame folding designs, while premium positioning clusters around transformable and compact mechanisms.
- Folding Ladders:Traditional A-frame hinged construction dominates contractor fleet procurement due to proven stability and straightforward OSHA duty-rating compliance. Residential renovation contractors in United States suburban markets specify these for interior finishing work where setup speed matters.
- Telescopic Ladders:Collapsible rung mechanisms reduce packed dimensions by two-thirds versus conventional frames, enabling storage in urban apartments and service vehicle compartments. Demand concentrates among electrical contractors and apartment-dwelling DIY users facing space constraints.
- Multi-Purpose Ladders:Hinged rail systems convert between A-frame, extension, and scaffolding configurations.
- Step Stool Ladders:Compact two-to-three-rung designs target kitchen and closet access tasks.
Mature deployment sits with Folding Ladders. Newer deployment is concentrated in Telescopic Ladders.
Material:
Cost tier separation runs from commodity steel through mid-market aluminum to premium fiberglass and heritage wood.
- Aluminum:Extruded 6061-T6 alloy delivers fifteen-to-twenty percent weight reduction against steel while maintaining structural integrity for residential and light commercial duty ratings. United States home improvement contractors favor these for interior work where transport frequency justifies the weight savings.
- Fiberglass:Pultruded resin systems provide dielectric insulation essential for electrical utility work near energized transmission infrastructure. Premium positioning reflects both material costs and specialized certification requirements under OSHA electrical safety mandates.
- Wood:Hardwood lamination serves heritage craftsmen and premium finish carpentry where aesthetic compatibility with interior millwork determines specification.
- Steel:Tubular welded construction persists in price-sensitive commercial fleet procurement and heavy-duty industrial applications.
Margin concentration sits with Fiberglass. Volume expansion is concentrated in Aluminum.
End User:
Procurement authority separates institutional buyers with technical specifications from discretionary purchasers prioritizing convenience and price.
- Commercial:Contractor purchasing cooperatives and facility maintenance departments drive specification-compliant procurement with documented duty ratings and batch testing records.
- Residential:Homeowners select through retail channels based on height rating, weight capacity, and storage footprint rather than certification documentation.
- Industrial:Plant maintenance departments require ANSI Type IAA load-bearing ratings and fleet tracking compliance for elevated work platform integration.
- DIY Enthusiasts:Hobbyist woodworkers and home renovators purchase through specialty retailers and direct-to-consumer channels.
Specification rigor sits with Industrial. Channel expansion is concentrated in Residential.
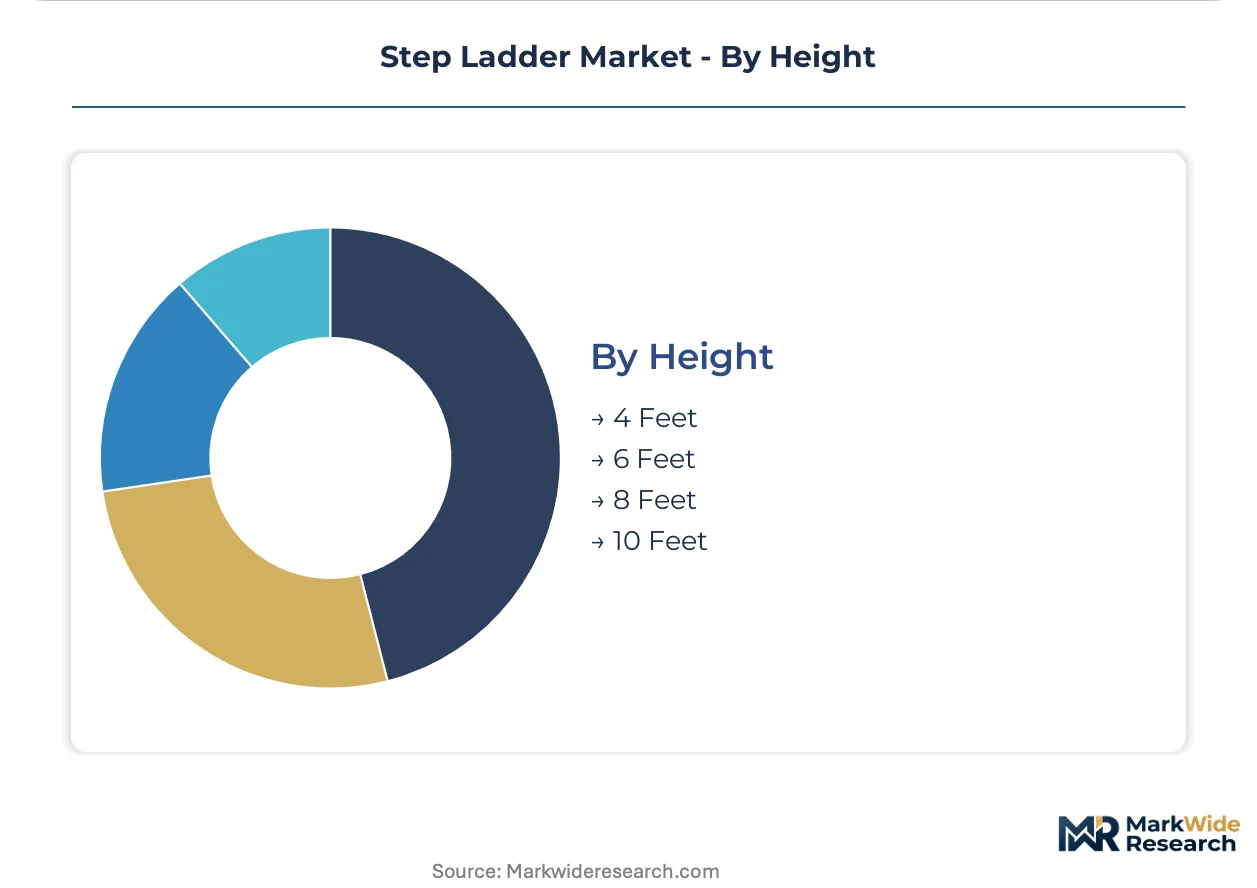
Height:
Application scope determines rung count, with interior residential tasks clustering at lower heights and exterior commercial work demanding extended reach.
- 6 Feet:Standard ceiling height compatibility makes this the default specification for residential painting, fixture installation, and HVAC filter replacement.
- 8 Feet:Commercial maintenance and light construction applications favor this reach for gutter cleaning and second-story exterior access.
- 4 Feet:Compact designs suit kitchen cabinetry and closet organization tasks.
- 10 Feet:Extended reach serves commercial painting crews and industrial facility maintenance requiring access to elevated infrastructure.
Replacement frequency sits with 6 Feet. Incremental growth is concentrated in 8 Feet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Fujian and Guangdong provinces concentrate aluminum extrusion capacity serving ladder fabricators with duty-exempt alloy sourcing. These coastal manufacturing clusters export finished units through Shenzhen and Xiamen ports to North American and European distribution channels.
United States
Residential renovation contractors in Texas and Florida metro areas drive aluminum step ladder procurement for interior finishing work. OSHA duty-rating enforcement compels fleet replacement cycles among commercial buyers. Werner Co. anchors manufacturing capacity in Pennsylvania and Illinois facilities serving contractor purchasing cooperatives.
Germany
REACH substance restrictions on hexavalent chromium surface treatments force trivalent passivation conversion among metal fabricators. The EU Machinery Directive shapes CE marking compliance costs for ladder exports. Bavarian industrial clusters around Nuremberg specialize in precision-engineered folding mechanisms for trade professionals.
China
Yangtze River Delta manufacturing bases supply extruded aluminum components to domestic and export markets. GB standards govern structural safety requirements for domestic sales. Zhejiang province hosts pultrusion operations serving fiberglass ladder assembly for electrical utility applications.
India
Maharashtra and Gujarat construction activity expands demand for lightweight aluminum variants among residential contractors. BIS certification requirements determine commercial procurement eligibility for institutional buyers. Pune industrial corridors concentrate metal fabrication capacity serving western India distribution networks.
Japan
Tokyo and Osaka metro area apartment dwellers absorb compact telescopic designs addressing storage constraints. METI industrial standards define load-bearing thresholds for commercial applications. Aichi prefecture manufacturing clusters specialize in precision aluminum extrusion for domestic and export markets.
Step Ladder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier dielectric products consolidating around certified fiberglass formulators while aluminum variants fragment across price-sensitive channels. Three strategic archetypes dominate: integrated extrusion specialists controlling alloy supply, pultrusion-focused dielectric manufacturers, and contract assemblers serving private-label retail programs. Capacity expansion and certification-driven portfolio diversification represent the dominant competitive moves as duty-rating compliance costs reshape procurement eligibility.
Among European precision-engineered specialists, ZARGES GmbH and Altrex B.V. exemplify the premium-tier folding mechanism segment, while Werner Co. anchors the North American integrated manufacturing archetype with captive extrusion capacity. Louisville Ladder occupies a position within the dielectric specialization tier serving electrical utility contractor channels.
| Leading Market Players |
|---|
| Gorilla Ladders |
| ZARGES |
| Werner Co. |
| ShangShuo Ladder |
| Altrex |
| Louisville Ladder |
| Hailo |
| AOPENG |
| Little Giant Ladder Systems |
| Others |
Value Network & Pricing Analysis
Welding technician scarcity in Pennsylvania and Illinois extrusion clusters compresses margin stability for aluminum ladder fabricators, widening spreads between captive-alloy producers and contract assemblers sourcing billet on spot markets. Labor-cost differentials between certified robotic seam-welding specialists and general metalworkers translate directly into pricing-tier separation across residential, commercial, and industrial duty ratings.
Pricing Analysis
Volume concentrates in aluminum folding ladders where commodity-grade 6061-T6 extrusions compete on transport efficiency and setup speed, while margin pools cluster in dielectric fiberglass formulations serving electrical utility contractors. Pricing stratifies across premium dielectric certification, standard ANSI-compliant commercial grades, and economy residential tiers without documented duty ratings. Cost compression in mid-market aluminum runs through energy-intensive smelting economics and extrusion-grade billet volatility. Residential renovators via home improvement retailers exhibit highest price sensitivity, while transmission line maintenance crews purchasing through contractor cooperatives prioritize dielectric certification over unit cost.
Supply Chain Analysis
Reverse logistics for damaged fiberglass pultrusions and aluminum extrusion scrap flows through regional metal recyclers in Guangdong and Zhejiang provinces, feeding secondary alloy markets. Primary manufacturing concentrates in China, the United States, and Germany. Raw material inputs draw from Gulf Coast epoxy resin corridors for fiberglass pultrusion, Yangtze River Delta aluminum smelters, and Appalachian hardwood laminators. Single-source vulnerability sits with pultrusion-grade vinyl ester formulations concentrated in hurricane-exposed refining infrastructure. Distribution runs through contractor purchasing cooperatives and national home improvement retail chains serving divergent buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive extrusion capacity and in-house alloy sourcing represent the dominant vertical-integration levers as duty-rating compliance costs reshape procurement eligibility across commercial channels.
For Market Incumbents: Cement market position through captive 6061-T6 billet supply agreements and Pennsylvania-based robotic welding automation that reduces technician dependency. Defend against carbon fiber hybrid telescopic entrants by accelerating ANSI Type IAA certification timelines and locking contractor cooperative purchasing agreements before specification-driven procurement consolidates further. For New Entrants and Emerging Players: Launch via direct-to-consumer telescopic mechanisms targeting Tokyo and Osaka apartment dwellers facing acute storage constraints. White-space sits in REACH-compliant trivalent passivation services for mid-tier European producers lacking ceramic coating conversion capital. Target advisory revenue from Asian manufacturers navigating CE marking complexity under the EU Machinery Directive. For Investors and Strategic Acquirers: Re-rating potential sits with dielectric specialization archetypes given OSHA electrical safety mandate tightening and transmission infrastructure maintenance backlog. Long-term viability favors pultrusion-focused manufacturers with captive resin formulations and utility contractor channel relationships. Monitor carbon fiber hybrid adoption rates among high-voltage electrical contractors as inflection signal for fiberglass displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Extrusion Capacity | Werner Co.'s Pennsylvania and Illinois facilities control alloy sourcing costs against volatile billet markets. |
| Dielectric Certification Investment | Louisville Ladder's specialized fiberglass formulations lock electrical utility contractor procurement specifications. |
| REACH Compliance Conversion | European manufacturers adopting trivalent passivation capture German and French distribution network access. |
| Telescopic Mechanism Patenting | ZARGES precision-engineered folding systems defend premium positioning among Bavarian trade professionals. |
| Contractor Cooperative Direct Relationships | National account procurement platforms serving multi-state construction firms bypass independent hardware distributors. |
Research Methodology
Trade association filings, customs export records, and OSHA certification databases formed the secondary backbone, supplemented by primary interviews with plant engineers at aluminum extrusion facilities, procurement leads at contractor purchasing cooperatives, electrical safety compliance officers, and aftermarket service heads at national home improvement retailers. Bottom-up unit shipment estimates triangulated against top-down construction spending allocation models.
Historical trendline analysis of residential renovation permit data, commercial construction starts, and electrical utility maintenance fleet replacement cycles informed demand trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, material grade, end-user procurement authority, and height specification dimensions. CAGRs derived from weighted average of replacement cycle frequencies and new construction penetration rates, with aluminum alloy price indices and resin feedstock cost curves as key forecast inputs.
Aluminum smelting energy cost spikes, hurricane-season resin supply disruptions, and OSHA duty-rating timeline compression are the dominant revision risks to shipment forecasts. Practitioners should monitor Gulf Coast refining corridor weather patterns, LME aluminum volatility, and third-party load-testing documentation backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Floor Scraper Market
Tools
Cordless Long Neck Grinder Market
Tools
Core Shooter Machine Market
Tools
Structural Wood Screws Market
Tools
Saw Blades Market
Tools
Dumpy Level Market
Tools
Digital Cutting Machine Market
Tools
Bar Clamp Market
Tools
Mechanical Hand Tools Market
Tools
Industrial Ladder Market
Tools
Cordless Planer Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Grinding Discs Market
Tools
Hydraulic Torque Wrench Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Cutting Tool Inserts Market