
 Indexable Tool Inserts Market | 2026-2036
Indexable Tool Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Indexable Tool Inserts Market Foresight
Modular insert packaging is expanding as suppliers unbundle traditional assortment kits into single-SKU configurations matched to specific machine-tool pairings. Sandvik Coromant dominates digital tool selection platforms that simplify this unbundled procurement. Kennametal Inc. leverages direct-to-factory distribution to control pricing on individually cataloged geometries. Iscar Ltd. specializes in quick-change modular systems that reduce setup time in multi-spindle environments.
Indexable tool inserts are replaceable cutting edges, typically cemented carbide or ceramic substrates with multi-layer PVD or CVD coatings such as TiAlN or diamond-like carbon, designed for mechanical clamping into reusable tool holders rather than brazed or solid-tool configurations. Their primary purpose is to restore cutting performance at lower cost than replacing complete tools, while enabling grade optimization per workpiece material. Turning inserts anchors the largest installed base due to universal application across cylindrical machining, though drilling inserts represents the fastest-growing category as deep-hole production in energy sector components demands specialized geometries. Carbide substrates concentrate the deepest margin pools because powder metallurgy scale and cobalt supply contracts create defensive cost positions.
ISO standards for tool designation and ANSI B212.4 dimensional specifications govern insert interchangeability and market access across North American and European supply chains. EPA hazardous waste rules for cobalt-containing grinding sludge shape recycling infrastructure investments and influence coating chemistry R&D priorities. OSHA silica exposure limits in carbide powder processing affect manufacturing location decisions. Stakeholders must monitor how carbon border adjustments and conflict mineral tracing requirements will reshape raw material sourcing economics for tungsten and cobalt supply chains.
Market Dynamics
ISO 13399 standardization for cutting tool data exchange is compressing procurement cycles and forcing suppliers to restructure digital catalogs around machine-readable geometry specifications rather than legacy paper-based ordering systems.
Growth Catalysts
- Multi-axis machining expansion:Aerospace manufacturers in Germany and Japan are deploying five-axis centers for turbine blade finishing, creating demand for specialized insert geometries with extended reach capabilities and through-coolant delivery.
- REACH cobalt traceability:European Union conflict mineral disclosure requirements are accelerating investments in certified tungsten supply chains, rewarding suppliers with verified smelter documentation.
- Deep-hole energy components:Drilling inserts for oilfield downhole tools and geothermal wellheads are experiencing demand pull from Texas and North Sea exploration contractors.
Market Restraints
- Cobalt price volatility:Democratic Republic of Congo concentrates 70% of global cobalt ore extraction, exposing carbide substrate producers to concentrate supply disruptions and London Metal Exchange price swings.
- Silica exposure compliance:OSHA permissible exposure limits for respirable crystalline silica in carbide powder pressing operations are constraining US-based greenfield manufacturing investments.
- Ceramic substitution ceiling:Silicon nitride inserts remain limited to nickel superalloy finishing due to fracture toughness constraints below 6.5 MPa·m½, blocking penetration into roughing applications.
Strategic Opportunities
- India automotive powertrain:PLI scheme incentives for advanced manufacturing are drawing tool holder producers to Pune and Chennai clusters, creating localized insert demand for crankshaft and camshaft machining.
- AI-assisted tool selection:Machine learning platforms trained on ISO 13399 parameter libraries are converging with shop-floor ERP systems to automate grade recommendations based on real-time spindle load data.
- Direct-to-factory distribution:Kennametal and Iscar are bypassing industrial distributors to capture margin on individually cataloged geometries through proprietary e-commerce portals.
Industry Challenges
- Grinding sludge disposal:EPA hazardous waste rules for cobalt-containing swarf require specialized recycling infrastructure that smaller insert resellers cannot economically access.
- Coating chemistry R&D timelines:Development of next-generation AlCrN-TiSiN nanolayer stacks requires 18-24 month validation cycles against ISO 3685 tool life testing protocols.
- Legacy machine compatibility:Quick-change modular systems from Iscar and Sandvik Coromant demand tool holder investments that job shops with 1990s-era lathes cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indexable Tool Inserts Market |
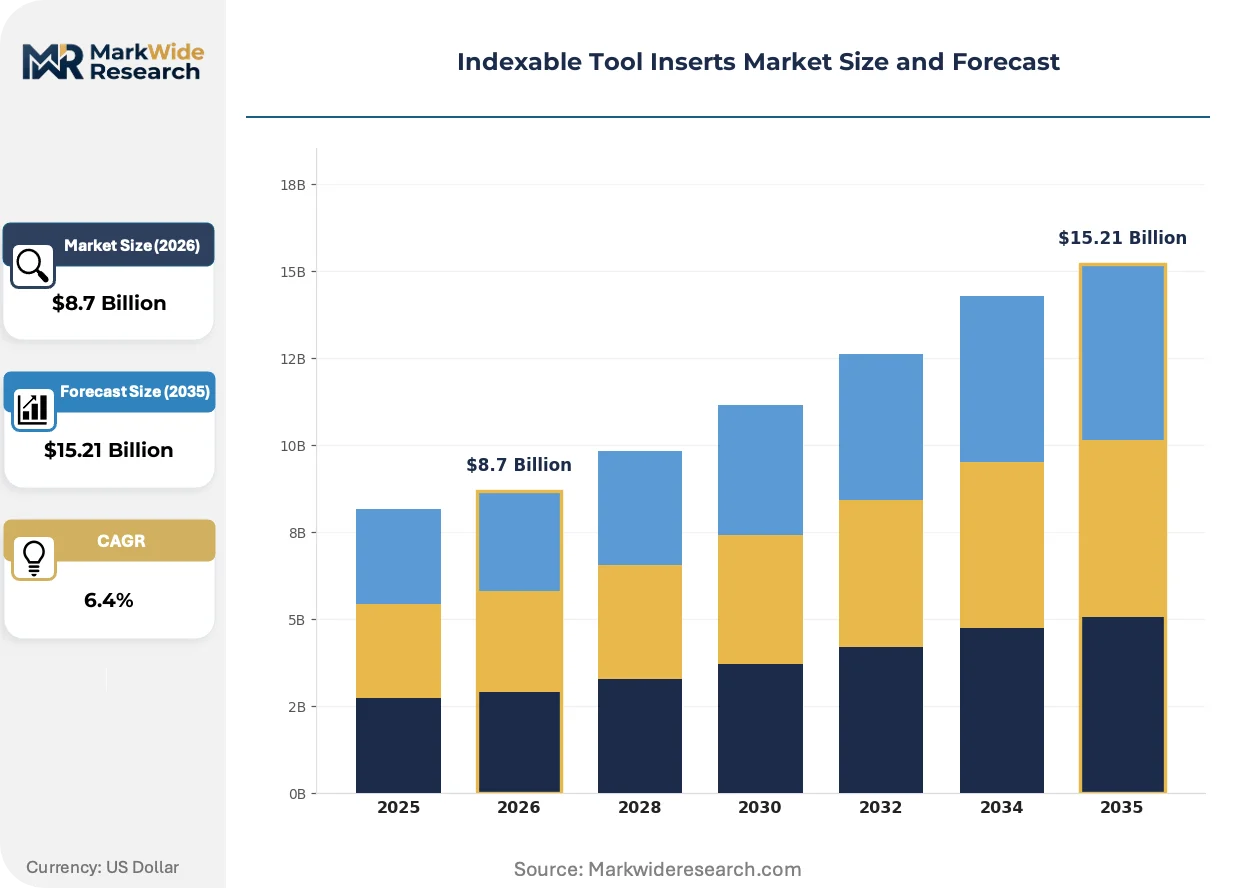
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turning Inserts, Milling Inserts, Drilling Inserts, Specialized Inserts Material: Ceramics, Carbide, Cobalt Alloys, High-Speed Steel Coating Type: TiN, TiAlN, TiCN, Diamond Coated End User: Aerospace, Automotive OEMs, Energy Sector, Metal Fabrication |
| Companies Covered | Mitsubishi Materials Corporation, Walter AG, Sandvik Coromant, Tungaloy Corporation, Kyocera Corporation, Kennametal Inc., Seco Tools, Sumitomo Electric Industries, Ltd., Iscar Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indexable Tool Inserts Market Shifts & Advancements
Digital thread integration between CAD/CAM systems and tool management databases is eliminating manual insert specification errors while compressing programming time for complex part families.
Diamond-like carbon coatings with sub-2 GPa modulus and friction coefficients below 0.1 are electrifying aluminum aerospace component machining. Tier-1 suppliers in Toulouse and Wichita are specifying DLC-finished inserts for wing rib pocketing to eliminate built-up edge and extend tool life in high-silicon alloys. The technology is compressing cost-per-part calculations for airframe manufacturers facing A320 and 737 production rate hikes.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are indirectly pressuring coating deposition processes. PVD chambers using SF₆ etching chemistry must retrofit to fluorine-free plasma cleaning to maintain operating permits in German and Austrian manufacturing zones. Carbide substrate producers with captive coating lines in Saxony are accelerating capital plans for alternative ion bombardment surface preparation.
Buyers are consolidating vendor relationships around suppliers offering integrated tool holder, insert, and digital inventory management contracts. Automotive powertrain engineers at BMW and Toyota are eliminating secondary tool crib operators by adopting vendor-managed consignment programs with RFID-enabled dispensing cabinets. This pattern is most visible in high-volume cylinder head and transmission case machining lines where insert consumption predictability supports just-in-time logistics.
Indexable Tool Inserts Market Segmentation
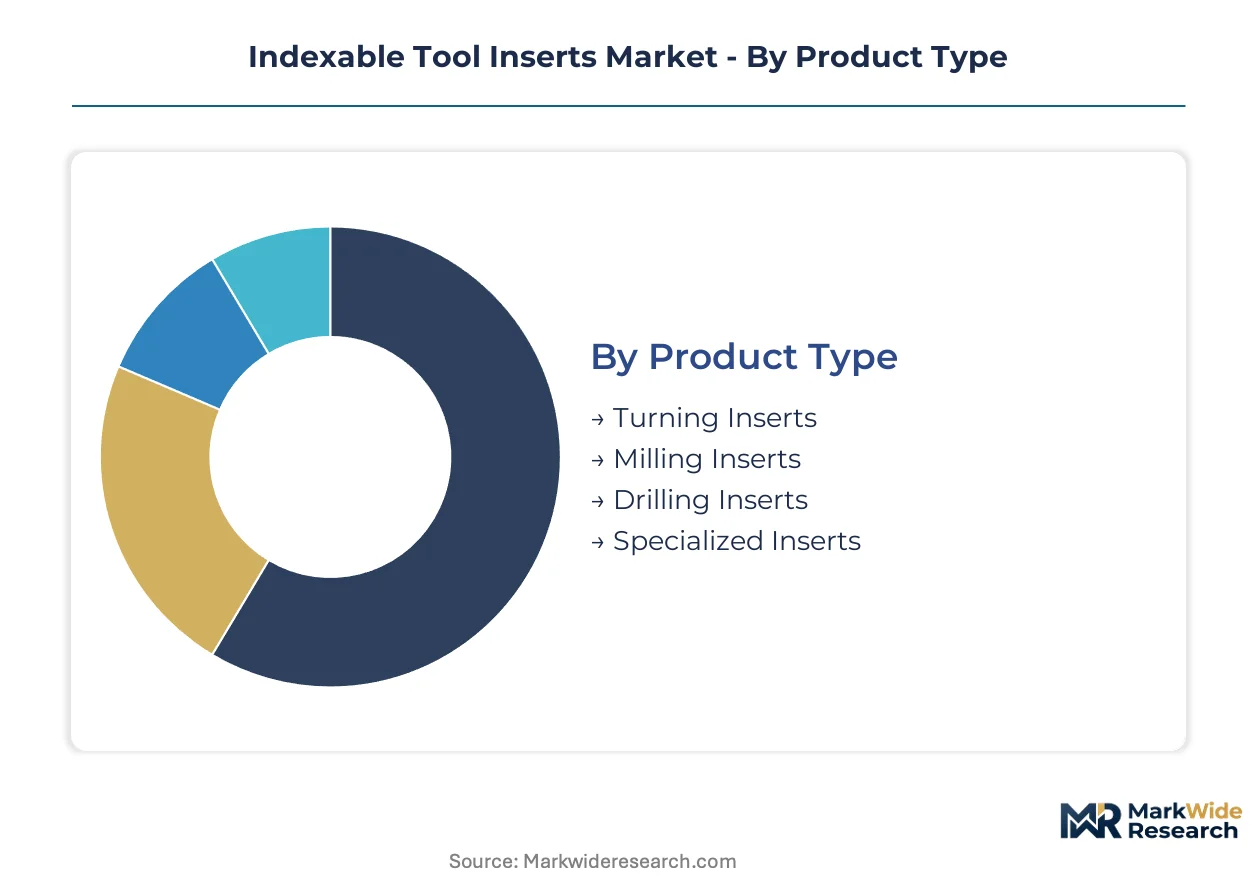
Segmentation in indexable tool inserts reveals how substrate chemistry, geometry design, and coating architecture align with distinct machining economics. Buyers optimize procurement by matching insert specifications to workpiece material hardness, cutting speed requirements, and tool life targets rather than defaulting to universal grades.
Product Type:
Supply concentration for finished geometries clusters around producers with captive powder metallurgy and precision grinding capabilities in Germany, Japan, and the United States.
- Turning Inserts:Cylindrical machining applications including OD/ID turning, facing, and grooving operations dominate installed machine tool bases. BMW and Toyota powertrain lines in Bavaria and Aichi Prefecture standardize on ISO-standard rhombic and triangular geometries for crankshaft finishing, with through-coolant designs commanding premium placement.
- Drilling Inserts:Indexable drill bodies with replaceable peripheral and center cutting edges address deep-hole production in energy sector components. North Sea contractors and Texas oilfield equipment manufacturers specify specialized geometries for downhole tool machining, with extended reach designs penetrating hardened steel wellhead forgings.
- Milling Inserts:Face milling and shoulder milling configurations serve die/mold and general engineering sectors with lower volume concentration than turning.
- Specialized Inserts:Thread turning, parting/grooving, and custom form tools address niche applications with limited standardization.
Turning Inserts absorbs the bulk of installed capacity; Drilling Inserts is expanding most quickly.
Material:
Cost tier stratification follows raw material intensity, with cobalt-containing grades occupying premium positions and ceramic alternatives pressing from below in finishing applications.
- Carbide:Cemented tungsten carbide with cobalt binder (6-12% Co) provides the baseline substrate for 80%+ of metalcutting inserts. Sandvik Coromant and Kennametal secure long-term cobalt concentrate contracts from verified smelters to defend margin positions against London Metal Exchange volatility.
- Ceramics:Silicon nitride and alumina-based inserts penetrate nickel superalloy finishing in aerospace turbine blade machining where carbide fails at elevated temperatures. Toulouse and Wichita airframe suppliers specify ceramic grades for Inconel pocketing to eliminate built-up edge.
- Cobalt Alloys:Stellite and similar cast alloys serve specialized high-temperature cutting where carbide binder softening occurs.
- High-Speed Steel:Legacy substrate retained for low-speed interrupted cuts and regrindable tool configurations in job shop environments.
Carbide commands the deepest margin pools; Ceramics is climbing the fastest on aerospace thermal management requirements.
Coating Type:
Application-specific coating selection determines wear resistance and thermal barrier performance across workpiece material categories.
- TiAlN:Aluminum-rich titanium aluminum nitride dominates high-speed steel and stainless steel machining with oxidation resistance to 800°C. PVD deposition chambers in Saxony and Tyrol specialize in nanolayer TiAlN-TiSiN stacks for extended tool life in automotive powertrain production.
- Diamond Coated:CVD polycrystalline diamond and DLC variants electrify aluminum aerospace component machining. Wichita wing rib producers specify sub-2 GPa modulus coatings to eliminate built-up edge in high-silicon 7xxx series alloys.
- TiN:Entry-level gold-colored coating for general-purpose machining with lower thermal stability.
- TiCN:Carbonitride formulations for improved hardness in medium-speed applications.
TiAlN holds the broadest application footprint; Diamond Coated is gaining share fastest on airframe production rate hikes.
End User:
Customer type segmentation tracks capital equipment intensity and insert consumption predictability, with automotive and aerospace commanding dedicated supply chain investments.
- Automotive OEMs:High-volume powertrain machining lines in Germany, Japan, and the United States consume predictable insert volumes supporting vendor-managed inventory programs. BMW cylinder head lines in Munich operate with RFID-enabled dispensing cabinets supplied through consignment contracts.
- Aerospace:Five-axis turbine blade finishing centers in Stuttgart and Nagoya drive demand for extended-reach geometries with through-coolant delivery. Tier-1 suppliers specify DLC-finished inserts for aluminum wing components to meet A320 and 737 production schedules.
- Energy Sector:Oilfield downhole tool and geothermal wellhead manufacturers in Texas and the North Sea pull specialized drilling insert geometries.
- Metal Fabrication:General engineering job shops with mixed batch production and legacy machine tools represent price-sensitive volume.
Automotive OEMs anchor procurement scale; Aerospace is expanding most quickly on multi-axis machining deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbide substrate production concentrates in Germany, Japan, and the United States, while consumption spreads across precision manufacturing clusters in aerospace and automotive corridors. Tool insert demand tracks capital equipment deployment in multi-axis machining centers rather than raw material extraction geography.
United States
Aerospace manufacturers in Wichita and Seattle deploy five-axis centers for wing rib and turbine component finishing, pulling specialized insert geometries with through-coolant delivery. EPA hazardous waste rules for cobalt-containing grinding sludge shape recycling infrastructure investments in Ohio and Illinois carbide processing zones. Kennametal operates direct-to-factory distribution channels from its Latrobe, Pennsylvania base to capture margin on individually cataloged geometries.
Germany
BMW and Volkswagen powertrain lines in Bavaria consume predictable carbide insert volumes through vendor-managed inventory programs with RFID-enabled dispensing cabinets. EU F-Gas Regulation phase-down schedules pressure PVD coating facilities in Saxony to retrofit fluorine-free plasma cleaning systems. Sandvik Coromant dominates digital tool selection platforms from its Düsseldorf-region technical center, streamlining procurement for Stuttgart-area automotive suppliers.
Japan
Toyota and Honda machining centers in Aichi Prefecture standardize on ISO-standard rhombic geometries for crankshaft finishing, with through-coolant designs commanding premium placement. METI industrial standards govern insert interchangeability certification for domestic machine tool builders. Mitsubishi Materials and Sumitomo Electric anchor carbide substrate supply from captive powder metallurgy operations in Tokyo and Osaka industrial corridors.
India
PLI scheme incentives for advanced manufacturing draw tool holder producers to Pune and Chennai clusters, creating localized insert demand for crankshaft and camshaft machining lines. BIS standards adoption accelerates for cutting tool data exchange compatibility with ISO 13399 frameworks. Domestic automotive powertrain expansion at Maruti Suzuki and Tata Motors facilities drives consumption of TiAlN-coated grades for high-speed steel machining.
China
MIIT industrial upgrading programs accelerate five-axis machining center deployment in Yangtze River Delta aerospace component shops, generating demand for extended-reach insert geometries. GB standards convergence with ISO 13399 specifications streamlines import substitution strategies for domestic carbide producers. Shenzhen and Chengdu precision manufacturing zones concentrate consumption of diamond-coated inserts for aluminum airframe pocketing operations.
Indexable Tool Inserts Market Competitive Landscape
The competitive structure tilts toward integrated substrate-coating specialists with captive powder metallurgy capabilities. Three to five conglomerate-affiliated manufacturers control premium-grade carbide supply through long-term cobalt concentrate contracts. Two strategic archetypes dominate: diversified materials conglomerates with aerospace-automotive dual channel presence, and focused cutting tool specialists with modular quick-change system expertise. Competitive moves concentrate on digital catalog restructuring around ISO 13399 machine-readable specifications and direct-to-factory distribution bypass of industrial distributors.
Among diversified materials conglomerates, Mitsubishi Materials Corporation and Sumitomo Electric Industries, Ltd. represent the integrated substrate-to-coating archetype with conglomerate-backed capital access. Sandvik Coromant occupies a distinct position as a standalone tooling specialist with digital platform dominance. These three exemplify how competitive positioning stratifies between scale-driven raw material security and agility-focused modular system innovation.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| Walter AG |
| Sandvik Coromant |
| Tungaloy Corporation |
| Kyocera Corporation |
| Kennametal Inc. |
| Seco Tools |
| Sumitomo Electric Industries, Ltd. |
| Iscar Ltd. |
| Others |
Supply & Pricing Matrix
Captive powder metallurgy operations in Germany, Japan, and the United States anchor both supply security and pricing power for carbide substrate producers. Long-term cobalt concentrate contracts with verified smelters defend margin positions against London Metal Exchange volatility while creating tiered access to premium-grade insert supply.
Pricing Analysis
Cost compression in economy-grade carbide inserts accelerates as Chinese domestic producers expand ISO-standard geometry output for automotive powertrain lines. Three-tier pricing structure across premium, standard, and economy levels separates cobalt-rich substrates with certified smelter documentation from generic grades. Price differentiation traces to REACH traceability compliance and volume-scale procurement contracts. Job shops with legacy machine tools exhibit highest price sensitivity; aerospace Tier-1 suppliers with vendor-managed inventory programs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Democratic Republic of Congo concentrate supply, where 70% of global cobalt ore extraction concentrates geographic risk. Carbide substrate production draws from captive powder metallurgy in Germany, Japan, and the United States, with coating deposition capacity clustering in Saxony and Tyrol. Tariff exposure on tungsten concentrates threatens margin stability for non-integrated producers. Distribution runs through direct-to-factory portals and industrial distributors serving high-volume automotive lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt supply concentration props pricing power for integrated producers, constraining capacity expansion for non-vertically qualified entrants.
For Market Incumbents: Lock in smelter certification documentation to defend margin positions against REACH disclosure requirements. Expand captive coating capacity in German and Austrian manufacturing zones to capture fluorine-free plasma cleaning retrofit demand. Secure long-term cobalt concentrate contracts before London Metal Exchange volatility accelerates.
For New Entrants and Emerging Players: Capture vendor-managed inventory contracts with Pune and Chennai automotive clusters as PLI scheme incentives localize tool holder production. Target drilling insert geometries for Texas and North Sea energy sector contractors where specialized deep-hole applications limit price competition. Lead with quick-change modular systems that reduce setup time in multi-spindle environments.
For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate-backed materials specialists with aerospace-automotive dual channel presence. Five-to-ten year viability favors producers with ISO 13399-compliant digital catalog infrastructure. Watch for carbon border adjustment implementation as inflection indicator for tungsten and cobalt sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cobalt Supply | Long-term concentrate contracts with verified smelters defend margins against price volatility. |
| ISO 13399 Digital Catalog Restructuring | Machine-readable geometry specifications streamline procurement for automotive powertrain engineers. |
| Fluorine-Free Coating Deposition Retrofit | EU F-Gas Regulation compliance maintains operating permits in German manufacturing zones. |
| Vendor-Managed Inventory Expansion | RFID-enabled dispensing cabinets eliminate secondary tool crib operators at BMW and Toyota lines. |
| Direct-to-Factory Distribution Channel | Proprietary e-commerce portals capture margin on individually cataloged geometries. |
Research Methodology
Document review covered SEC filings from carbide producers, customs trade data for tungsten concentrate flows, and ISO certification databases, complemented by interviews with plant managers at powder metallurgy operations, procurement leads at automotive OEMs, coating R&D directors in Saxony and Tyrol, and aftermarket service heads at industrial distributors. Secondary validation drew from ECHA REACH registration data, EPA hazardous waste disposal records, and METI industrial standards documentation. Bottom-up insert consumption modeling triangulated against top-down machine tool deployment data.
Historical capacity utilization rates cross-referenced against expert panel input on coating chemistry R&D timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate material tier, coating architecture, geometry application, end-use industry vertical, and regional production cluster. CAGRs derived from insert consumption intensity per machine tool hour and replacement cycle frequencies. Forecast inputs incorporated PLI scheme incentive disbursement patterns and aerospace production rate assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cobalt supply disruptions, carbon border adjustment implementation, and ceramic substitution advances in nickel superalloy finishing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Pneumatic Marking Machines Market
Tools
Press Machine Market
Tools
Woodcarving Tool Market
Tools
Woodpecker Tools Market
Tools
Taps and Dies Market
Tools
Horizontal Milling Machine Market
Tools
Pliers Market
Tools
Floor Polishing Machine Market
Tools
Wood-Burning Tool Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Cold and Hot Tool Steel Market
Tools
Set Screw Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Cutting Tools Market
Tools
Digital Cutting Machine Market
Tools
Forging Press Market