
 Metal Cans and Glass Jars Market | 2026-2036
Metal Cans and Glass Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cans and Glass Jars Market Outlook
Foodservice distribution channels is reconfiguring procurement patterns for rigid packaging across developed markets. Ball Corporation leverages its integrated aluminum supply chain to dominate North American beverage can supply. Crown Holdings anchors European demand through specialized steel aerosol and food can operations. Owens Illinois sustains glass jar leadership via furnace technology investments in multiple production hubs.
Metal cans and glass jars comprise rigid primary packaging fabricated from aluminum, tinplate, or soda-lime glass, formed through draw-and-iron, three-piece welding, or blow-molding processes, designed to provide hermetic sealing, UV protection, and extended shelf stability for consumable and industrial goods. The food industry end-user segment retains the largest volume share, though beverage industry demand for aluminum containers is expanding fastest as brands abandon single-use plastics. Glass jars command premium margin pools in personal care and specialty food applications where material aesthetics and chemical inertness justify higher unit economics.
FDA food-contact substance notifications and EPA emissions standards govern U.S. manufacturing compliance, while REACH and the EU Packaging and Packaging Waste Directive shape European material restrictions and recycling mandates. BIS certification requirements in India and GB standards in China add complexity for multinational suppliers seeking market access across jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and aluminum alloy cost volatility as decisive variables for capital allocation and regional production strategy.
Market Dynamics
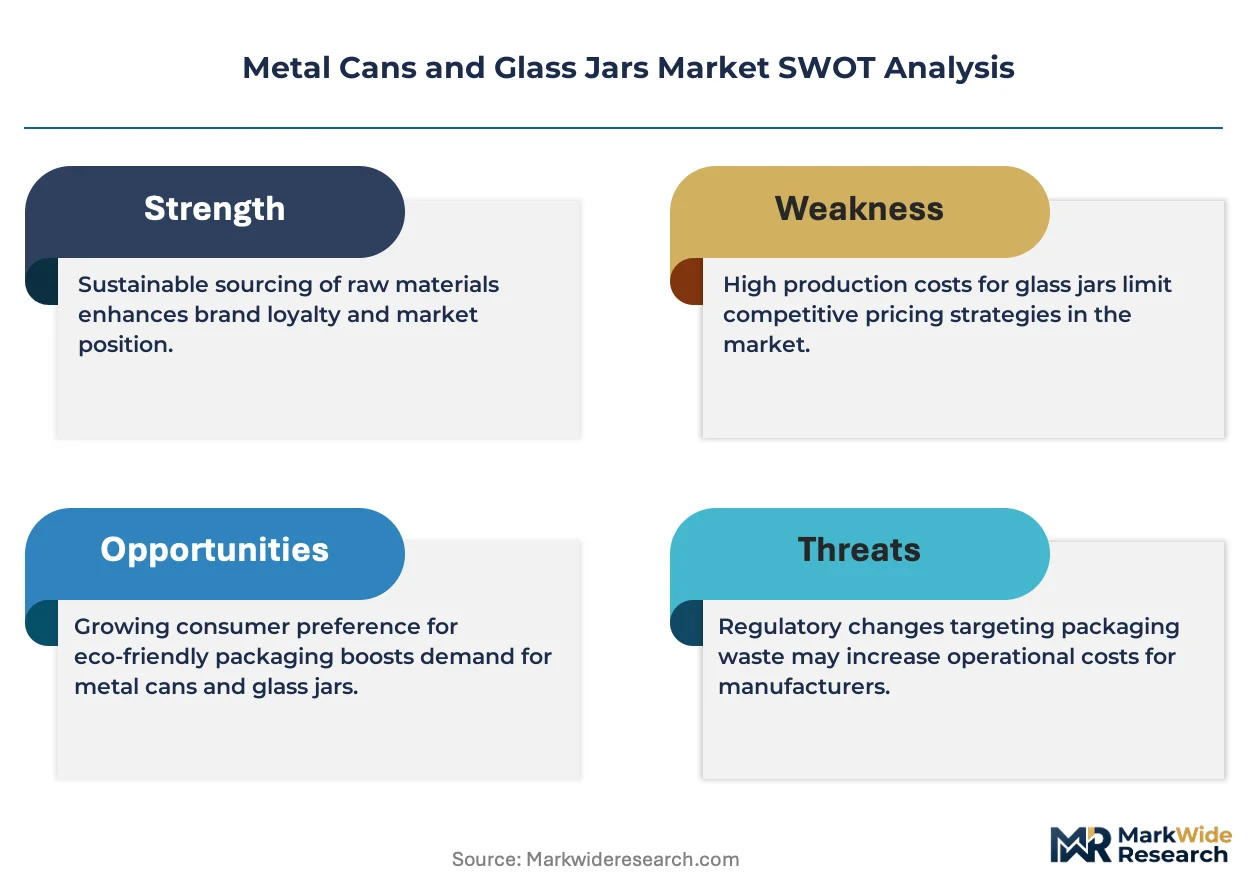
Aluminum alloy cost volatility and extended producer responsibility frameworks are forcing capital reallocation across production networks. Manufacturers must balance furnace technology investments against shifting beverage brand procurement patterns that favor lightweight, infinitely recyclable containers.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Mandatory recycling targets are accelerating demand for infinitely recyclable aluminum beverage containers across German and French bottling operations.
- Refillable glass systems:German deposit-return infrastructure anchors premium craft beverage packaging demand, creating pull-through for specialized furnace capacity.
- Draw-and-iron aluminum forming:Thin-walling technology reduces material input per unit while maintaining structural integrity for carbonated beverage pressure requirements.
Market Restraints
- Aluminum ingot price volatility:LME aluminum contract fluctuations compress margin predictability for can manufacturers without captive smelter access.
- Soda-lime glass furnace restart costs:Cold repair cycles require 45-60 day production halts, constraining supply elasticity during demand surges.
- Steel tinplate substitution threat:Two-piece aluminum cans displace three-piece welded steel containers in food applications, stranding legacy welding line investments.
Strategic Opportunities
- India BIS certification pathways:Standardized food-contact material approvals create entry channels for compliant aluminum and glass suppliers into organized retail distribution.
- Aerosol personal care applications:Aluminum monobloc cans capture fragrance and skincare volumes from plastic alternatives seeking premium shelf differentiation.
- Digital printing convergence:Direct-to-can inkjet decoration enables micro-batch customization for craft beverage brands without plate changeover costs.
Industry Challenges
- Furnace engineering talent scarcity:Specialized glass melting expertise concentrates with retiring European technician cohorts, constraining new plant commissioning timelines.
- REACH SVHC compliance documentation:Extended safety data sheet requirements for coating chemistries delay new product introductions by 8-14 months.
- Legacy three-piece can line integration:Welding equipment retrofits for lighter gauge tinplate demand capital deployment without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cans and Glass Jars Market |
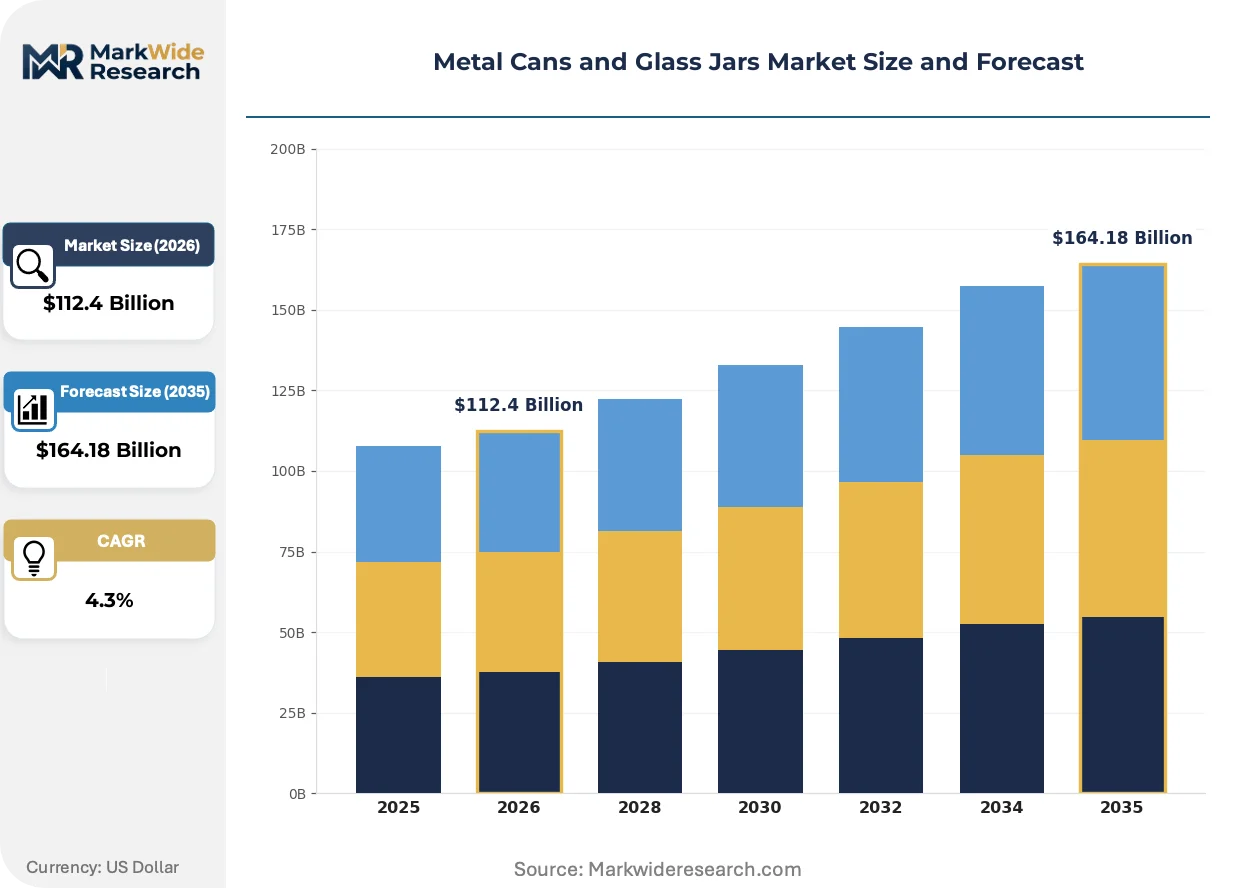
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $164.18 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
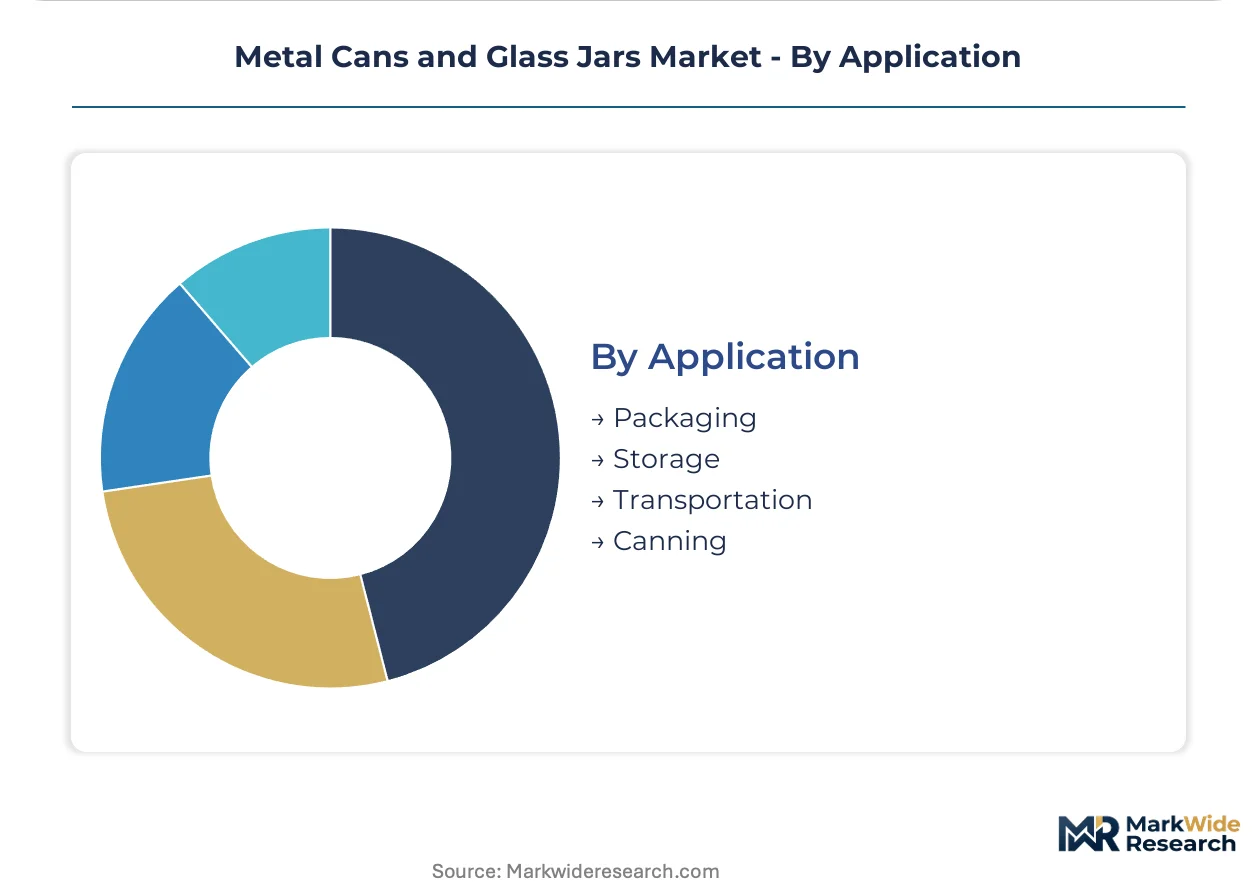
| Segmentation | Product Type: Metal Cans, Glass Jars, Aluminum Containers, Steel Containers Material: Aluminum, Glass, Tinplate, BPA-free Plastic End User: Food Industry, Beverage Industry, Household Products, Personal Care Products Application: Packaging, Storage, Transportation, Canning |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Silgan Holdings, Amcor, Owens Illinois, Bormioli Rocco, Gerresheimer, Piramal Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cans and Glass Jars Market Strategic Shifts
Material science advances and regulatory tightening are compressing traditional production cycles. Manufacturers are deploying digital infrastructure and lightweighting technologies to meet concurrent demands for sustainability verification and cost containment.
Digital twin simulation is virtualizing furnace thermal profiling and blow-molding parameter optimization before physical commissioning. Owens-Illinois and Ardagh deploy these tools across European and North American glass plants to reduce defect rates and energy consumption. The technology is virtualizing decades of empirical glass-forming expertise into reproducible algorithmic protocols.
REACH authorization requirements for chromium-based coatings are compelling migration to organosol and epoxy-phenolic alternatives in European food can manufacturing. The regulation is forcing reformulation investments across tinplate and aluminum substrate suppliers. Aerosol and general line can segments face compressed compliance timelines as sunset dates approach for legacy coating chemistries.
Beverage brand direct sourcing contracts are consolidating procurement relationships with integrated aluminum suppliers, bypassing traditional merchant converter networks. North American craft brewers and hard seltzer brands negotiate directly with smelter-affiliated can manufacturers for volume commitments and decoration flexibility. This pattern concentrates most visibly in the United States, where Ball Corporation and Crown Holdings have established dedicated craft beverage sales divisions.
Metal Cans and Glass Jars Market Segmentation
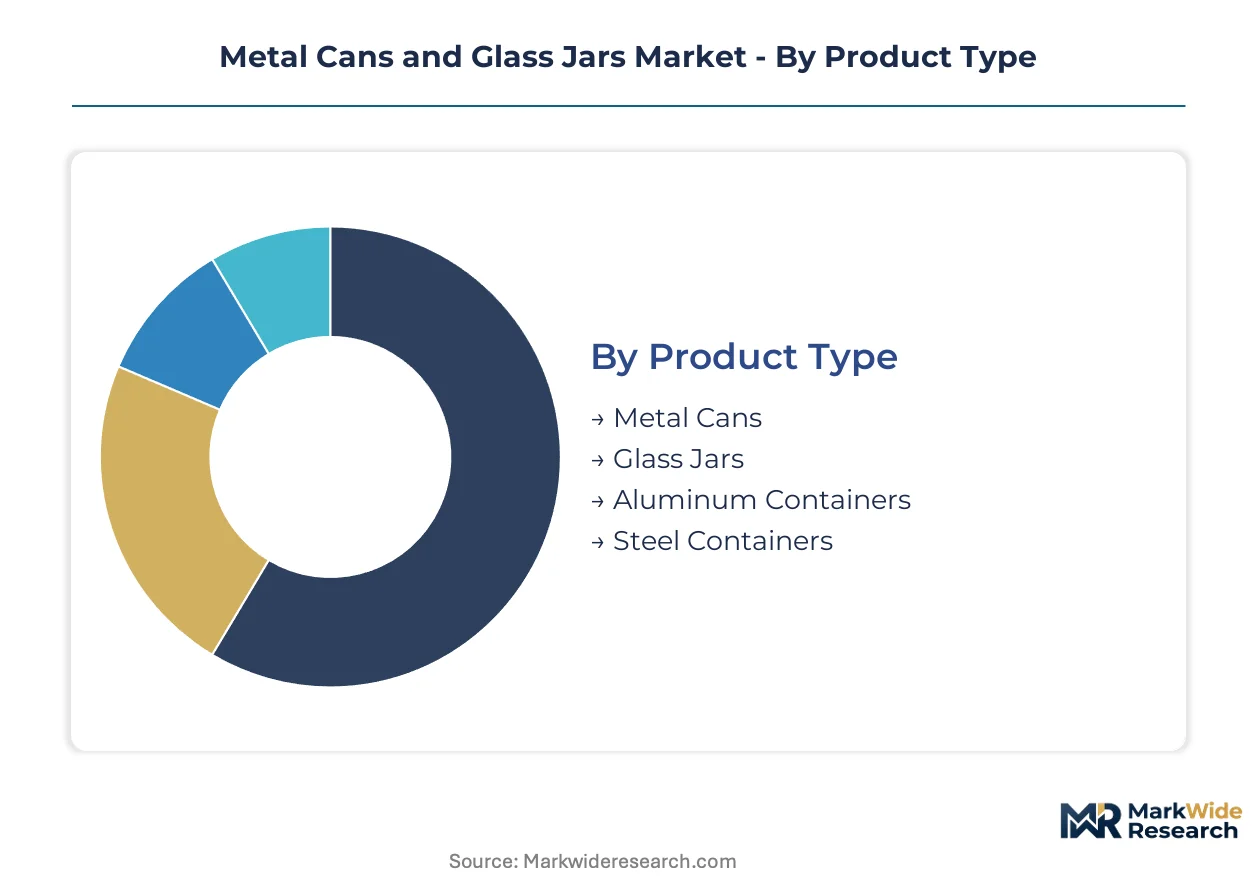
Segmentation in rigid packaging reveals divergent capital intensity and margin profiles across material systems. Aluminum beverage containers turn inventory weekly while glass furnace operations lock capital for decades, creating fundamentally different investment horizons for procurement strategists.
Product Type:
Cycle times vary dramatically: two-piece aluminum cans achieve sub-second forming speeds while glass jar production requires 24-hour furnace residence times, creating order-of-magnitude differences in volume elasticity.
- Metal Cans:Two-piece draw-and-iron aluminum construction dominates beverage applications with sub-100-micron wall thicknesses. North American craft brewers and hard seltzer brands concentrate procurement through direct smelter-affiliated contracts, bypassing traditional merchant networks.
- Glass Jars:Soda-lime silica composition with hermetic lug or continuous thread closures anchors premium food and personal care positioning. German refillable deposit-return systems sustain specialized furnace capacity for craft beverage packaging with higher unit economics.
- Aluminum Containers:Monobloc aerosol and general line formats capture fragrance and skincare volumes from plastic alternatives seeking shelf differentiation.
- Steel Containers:Three-piece welded tinplate construction retains foothold in processed food applications where cost minimization outweighs lightweighting priorities.
Metal Cans anchors the volume base while Aluminum Containers gains share at the steepest rate.
Material:
Cost tier stratification separates commodity feedstocks from certified food-contact grades with divergent compliance documentation burdens.
- Aluminum:LME-linked ingot pricing drives margin volatility for converters without captive smelter access. Thin-walling technology reduces material input per unit while maintaining carbonated beverage pressure integrity.
- Glass:Batch composition precision determines thermal shock resistance and chemical durability for acidic food contents. Furnace cold repair cycles require 45-60 day production halts, constraining supply elasticity.
- Tinplate:Chromium-based coating migration to organosol alternatives accelerates under REACH authorization timelines.
- BPA-free Plastic:Substitution threat from aluminum and glass intensifies as beverage brands abandon single-use formats.
Glass commands premium margin pools while Aluminum expands most quickly across beverage applications.
End User:
Application maturity separates established food preservation demand from emerging personal care aerosol conversion opportunities.
- Food Industry:Hermetic sealing requirements for thermal processing drive specification rigidity. Extended shelf stability demands concentrate procurement with integrated suppliers capable of coating chemistry compliance.
- Beverage Industry:Aluminum can demand accelerates as brands exit single-use plastics, with direct sourcing contracts consolidating relationships around decoration flexibility and micro-batch capabilities.
- Household Products:Aerosol propellant compatibility requirements sustain specialized monobloc demand.
- Personal Care Products:Material aesthetics and chemical inertness justify higher unit economics for fragrance and skincare applications.
Food Industry retains the largest volume position while Beverage Industry climbs the fastest on plastic substitution momentum.
Application:
Supply concentration patterns align with end-use technical requirements and regulatory exposure intensity.
- Packaging:Primary containment function with hermetic sealing and UV protection specifications dominates value capture.
- Storage:Extended shelf stability requirements concentrate demand with furnace technology leaders.
- Transportation:Structural integrity under stacking load drives gauge and alloy selection.
- Canning:Thermal processing compatibility with acidic contents requires specialized coating formulations.
Packaging dominates value concentration while Canning shows steepest expansion trajectory on premium food preservation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube canal network and North Sea port infrastructure underwrite European supply chain primacy for aluminum and glass packaging movements. German refillable glass systems and Dutch transshipment hubs anchor continental distribution efficiency.
Germany
Deposit-return infrastructure for refillable glass bottles sustains specialized furnace capacity across Bavarian and North Rhine-Westphalian production clusters. REACH authorization timelines for chromium-based coatings compel reformulation investments at tinplate processors in the Ruhr industrial belt. Ball Corporation maintains integrated aluminum supply operations serving German beverage bottlers directly.
United States
Direct sourcing contracts between craft brewers and smelter-affiliated can manufacturers bypass traditional merchant converter networks. FDA food-contact substance notifications govern coating chemistry approvals for domestic food can production. Crown Holdings anchors steel aerosol operations through specialized facilities in the Midwest manufacturing corridor.
China
GB standards for food-contact materials and dual carbon policy targets reshape aluminum and glass production compliance burdens. Yangtze River Delta glass furnace clusters face emissions retrofit mandates under MEE enforcement protocols. Silgan Holdings positions within imported equipment supply chains serving coastal beverage packaging expansion.
India
BIS certification requirements for food-contact aluminum and glass materials create standardized entry channels into organized retail distribution. FSSAI packaging safety regulations concentrate procurement with integrated suppliers capable of documentation compliance. Piramal Glass anchors western Indian glass jar supply serving domestic pharmaceutical and food preservation demand.
Brazil
ANVISA pharmaceutical packaging regulations sustain specialized glass demand for sterile liquid containment applications. Aluminum beverage can consumption accelerates as major soft drink brands exit refillable glass formats. Amcor maintains South American metal packaging operations serving Andean and Mercosur export corridors.
Metal Cans and Glass Jars Market Competitive Environment
On the supply side, the industry is bifurcated between integrated aluminum smelter-converter networks and specialized glass furnace operators with decades-locked capital cycles. The competitive terrain separates high-volume beverage can manufacturers from premium-positioned glass jar specialists serving personal care and specialty food applications. Two dominant archetypes prevail: integrated aluminum suppliers with captive smelter access and furnace technology leaders with batch composition expertise. Capacity expansion and direct brand sourcing consolidation represent the primary competitive vectors reshaping procurement relationships.
Among North American integrated suppliers, Ball Corporation and Crown Holdings occupy positions exemplifying the smelter-affiliated archetype, while Owens Illinois anchors the furnace technology leadership tier for glass containment systems. These three entities represent distinct strategic postures within material-specific competitive arenas.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Holdings |
| Amcor |
| Owens Illinois |
| Bormioli Rocco |
| Gerresheimer |
| Piramal Glass |
| Others |
Value Chain & Pricing Dynamics
German furnace operators and Ruhr industrial belt tinplate processors anchor upstream concentration, directing margin capture toward coating chemistry compliance specialists and direct-sourcing aluminum converters serving craft beverage brands.
Pricing Analysis
Volume-discount tiering separates direct smelter-affiliated contracts for North American craft brewers from merchant converter spot purchases. Price differentiation rests on coating certification grade and decoration flexibility. Pricing pressure stems from LME aluminum contract volatility compressing converter margins. Food industry procurement teams show highest price sensitivity; personal care aerosol buyers prioritize material aesthetics over unit cost.
Supply Chain Analysis
Tariff exposure between United States and primary aluminum-producing jurisdictions dominates supply chain risk assessment. Raw material flows draw from German tinplate processing clusters, Chinese Yangtze River Delta glass furnace networks, and North American integrated smelter operations. Cold repair cycles for soda-lime glass furnaces create 45-60 day supply interruptions. Distribution runs through Rhine-Main-Danube canal networks and Dutch transshipment hubs serving European bottling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum beverage container demand is accelerating as brands abandon single-use plastics, positioning this market for early-cycle expansion on plastic substitution tailwinds.
For Market Incumbents: Build captive smelter access moats through backward integration into primary aluminum supply. Ball Corporation and Crown Holdings demonstrate this archetype. Defend against steel tinplate substitution threats by accelerating thin-walling technology deployment. Prioritize furnace technology investments in German refillable glass corridors where deposit-return infrastructure sustains premium unit economics. For New Entrants and Emerging Players: Establish a beachhead in Indian organized retail distribution channels where BIS certification requirements create standardized entry pathways. Target aerosol personal care applications for aluminum monobloc cans capturing fragrance volumes from plastic alternatives. Lead with digital printing capabilities enabling micro-batch customization for craft beverage brands without plate changeover costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed glass furnace operators holding decades-locked capital cycles in European production clusters. Five-to-ten year viability hinges on REACH coating chemistry compliance capabilities and extended producer responsibility framework positioning. Watch aluminum alloy cost volatility inflections as signal for converter margin compression versus smelter-affiliated supplier resilience.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captive smelter access insulates Ball Corporation and Crown Holdings from LME contract volatility. |
| Furnace Technology Modernization | Digital twin deployment at Owens-Illinois reduces defect rates and energy consumption across European plants. |
| Coating Chemistry Reformulation | REACH authorization timelines for chromium-based coatings compel organosol migration at Ruhr tinplate processors. |
| Direct Sourcing Contract Consolidation | Craft brewer and hard seltzer brand procurement bypasses traditional merchant converter networks in North America. |
| Digital Printing Infrastructure | Direct-to-can inkjet decoration enables micro-batch customization without plate changeover costs for beverage brands. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with aluminum smelter procurement directors, glass furnace operations managers, beverage brand packaging strategists, and coating chemistry formulators; and secondary validation through customs trade data, SEC filings from integrated packaging suppliers, EPA emissions disclosures, and EU Packaging and Packaging Waste Directive implementation reports. Bottom-up volume modeling triangulated against top-down value chain analysis anchored the forecast framework.
Forecast inputs across the projection horizon included product type segmentation, material grade tiers, end-user industry demand patterns, and regional regulatory cluster variations. CAGRs were derived from historical volume trajectories adjusted for plastic substitution momentum and extended producer responsibility framework implementation timelines. Aluminum alloy cost volatility scenarios and furnace cold repair cycle frequencies shaped sensitivity bands.
Stress conditions across LME aluminum contract fluctuations, REACH authorization timeline accelerations, and German deposit-return infrastructure policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about beverage brand procurement consolidation and coating chemistry migration timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Food Grade Stainless Steel Container Market
Containers
Tottle Containers Market
Containers
Thermoformed Containers Market
Containers
Flexible Water Tanks Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Screw Top Pails Market
Containers
Composite Ibcs System Market
Containers
Die Cut Display Container Market
Containers
Collapsible Food Packaging Containers Market
Containers
Corrugated Bin Boxes Market
Containers
Single Wall Jars Market
Containers
Takeaway Containers Market
Containers
Pails Market
Containers
Foam Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Carboy Market