
 Middle East and Africa Metal Cans Market | 2026-2036
Middle East and Africa Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Metal Cans Market Foresight
Distributor networks across the Gulf Cooperation Council are tilting toward direct-to-bottler supply contracts as beverage volume scales. Crown Holdings, Inc. leverages its regional coil-coating infrastructure to anchor long-term contracts with Saudi bottling groups. Ball Corporation competes through lightweighting technology leadership in aluminum beverage formats. Nampak Limited sustains its southern African footprint via integrated steel and tinplate operations.
Middle East and Africa metal cans are cylindrical containers fabricated from aluminum alloy, tinplate, or steel substrate, typically ranging from 150 mL to 5 L in filled volume, formed through draw-and-iron or three-piece welding processes and sealed with double-seamed ends to provide hermetic preservation of shelf-stable contents. The beverage industry segment dominates value generation through high-volume aluminum can demand for carbonated and non-carbonated drinks. Steel cans retain structural importance in the food industry segment where retort processing and extended shelf life requirements persist. Biodegradable cans represent an incipient technology category with concentrated R&D activity but limited commercial scale.
Saudi Arabia's SFDA and South Africa's NRCS enforce food-contact material standards that dictate internal lacquer specifications and migration limits for metal packaging. The UAE's MOHAP aligns with Gulf Standardization Organization protocols for canned food imports, creating harmonized compliance thresholds across major trade corridors. Stakeholders must monitor evolving extended producer responsibility mandates and substrate price volatility to calibrate capacity commitments and material substitution strategies.
Market Dynamics
Aluminum substrate price volatility and extended producer responsibility mandates across Gulf Cooperation Council states are compressing converter margins while forcing material substitution decisions at integrated beverage packaging facilities.
Growth Catalysts
- Carbonated Beverage Volume Expansion:Bottlers across Saudi Arabia and the UAE are scaling aluminum can procurement as per-capita consumption of soft drinks climbs. High-volume filling lines demand reliable domestic coil supply.
- South Africa's Extended Producer Responsibility Framework:The NRCS-backed regulations mandate minimum recycled content thresholds. Converters are investing in closed-loop recycling infrastructure to secure compliance certification.
- Retort-Ready Food Can Demand:Nigeria's food processing sector requires three-piece tinplate containers for shelf-stable tomato paste and cooking sauces. Local canneries are qualifying regional steel substrate suppliers.
Market Restraints
- Aluminum Ingot Price Volatility:Smelter capacity constraints in the GCC expose converters to London Metal Exchange price swings that compress quarterly contract margins.
- Tinplate Import Dependency:Regional food can production relies on European and Asian steel coil suppliers, creating lead time exposure and currency hedge costs.
- Substitution by PET Bottles:Lightweight plastic formats are capturing share in non-carbonated beverage segments where barrier requirements permit flexible packaging.
Strategic Opportunities
- Underpenetrated East African Markets:Ethiopia and Kenya lack indigenous two-piece aluminum can manufacturing. Import substitution through greenfield coil coating investments could capture beverage bottler procurement.
- Biodegradable Can R&D Convergence:Startups combining mycelium-based substrates with metal barrier layers are targeting premium organic beverage segments willing to fund pilot scale-up.
- Direct-to-Bottler Distribution Channels:Gulf distributors are bypassing traditional trading houses to contract coil supply directly, compressing working capital cycles and improving lot traceability.
Industry Challenges
- Double-Seam Technician Scarcity:Retort food can manufacturing requires specialized setup skills that regional technical institutes do not currently train at sufficient throughput.
- SFDA Compliance Timeline Compression:Saudi food-contact material approvals now demand accelerated migration testing that strains third-party laboratory capacity during new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Metal Cans Market |
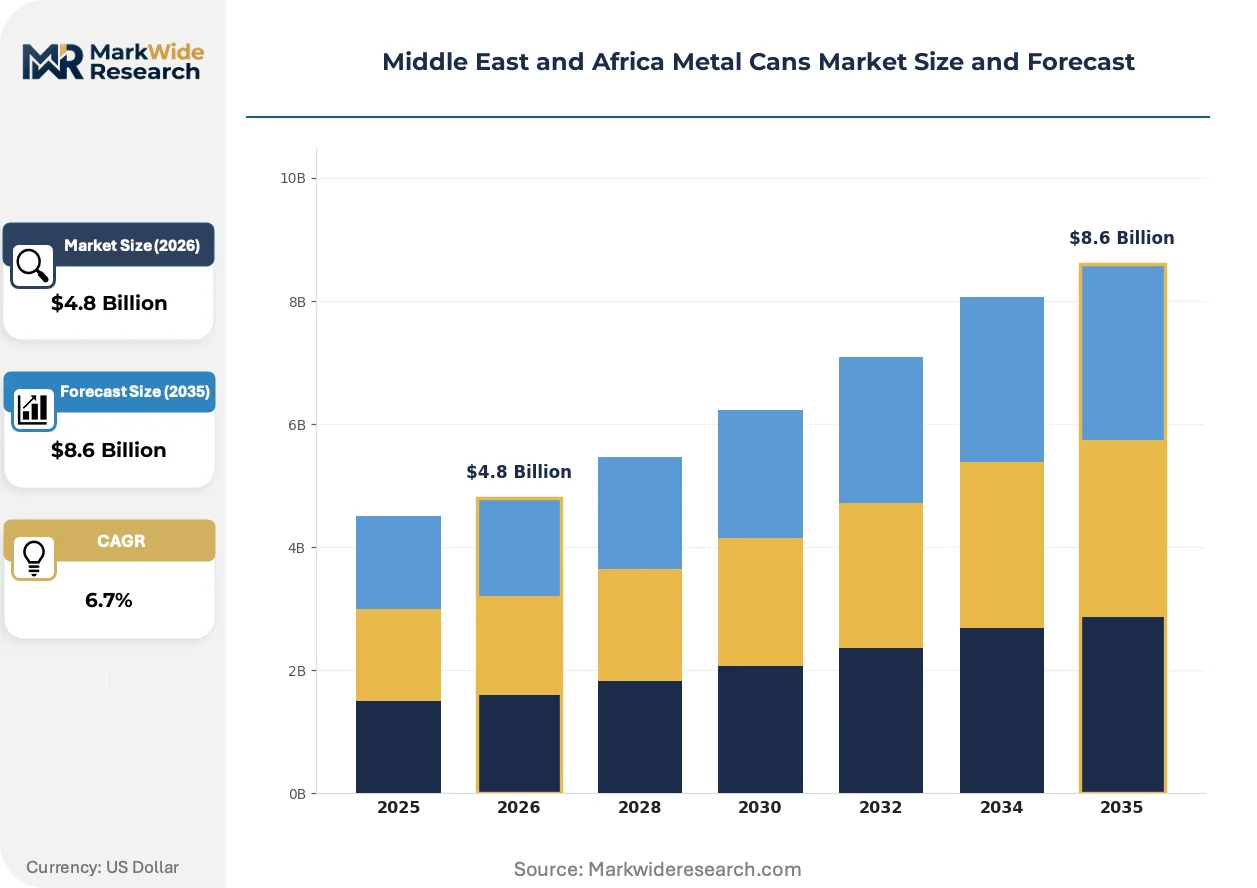
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Tinplate Cans, Biodegradable Cans End User: Food Industry, Beverage Industry, Personal Care, Chemical Industry Application: Canned Food, Soft Drinks, Paint, Oil Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Distributors |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group S.A., SAPIN Saudi Arabian Packaging Industry, CANPACK S.A., Nampak Limited, Middle East Metal Can LLC, Gulf Cans Industries, Avon Crowncaps & Containers Nigeria Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Metal Cans Market Shifts & Advancements
Digital manufacturing controls and regulatory alignment pressures are converging to reshape substrate sourcing and end-use qualification protocols across Middle East and Africa metal can production.
Lightweighting simulation software is virtualizing traditional trial-and-error die development cycles. Saudi bottling groups are adopting finite-element modeling to optimize wall thickness before physical prototype runs. This compression of R&D lead times is virtualizing the competitive advantage once held by converters with decades of empirical tooling libraries.
South Africa's NRCS has tightened food-contact lacquer migration limits to align with EFSA precautionary thresholds. Local converters must reformulate internal coatings and re-validate existing can dimensions under accelerated aging protocols. The retort-processed vegetable segment faces the steepest compliance cost escalation as shelf-life claims require extended thermal testing documentation.
Beverage bottlers in the UAE are consolidating procurement under single-source aluminum coil contracts with built-in price adjustment mechanisms. Trading houses that historically intermediate GCC metal flows are losing volume to direct mill relationships. This channel compression is most visible among multinational soft drink franchises operating integrated filling and distribution networks across Dubai and Abu Dhabi.
Middle East and Africa Metal Cans Market Segmentation
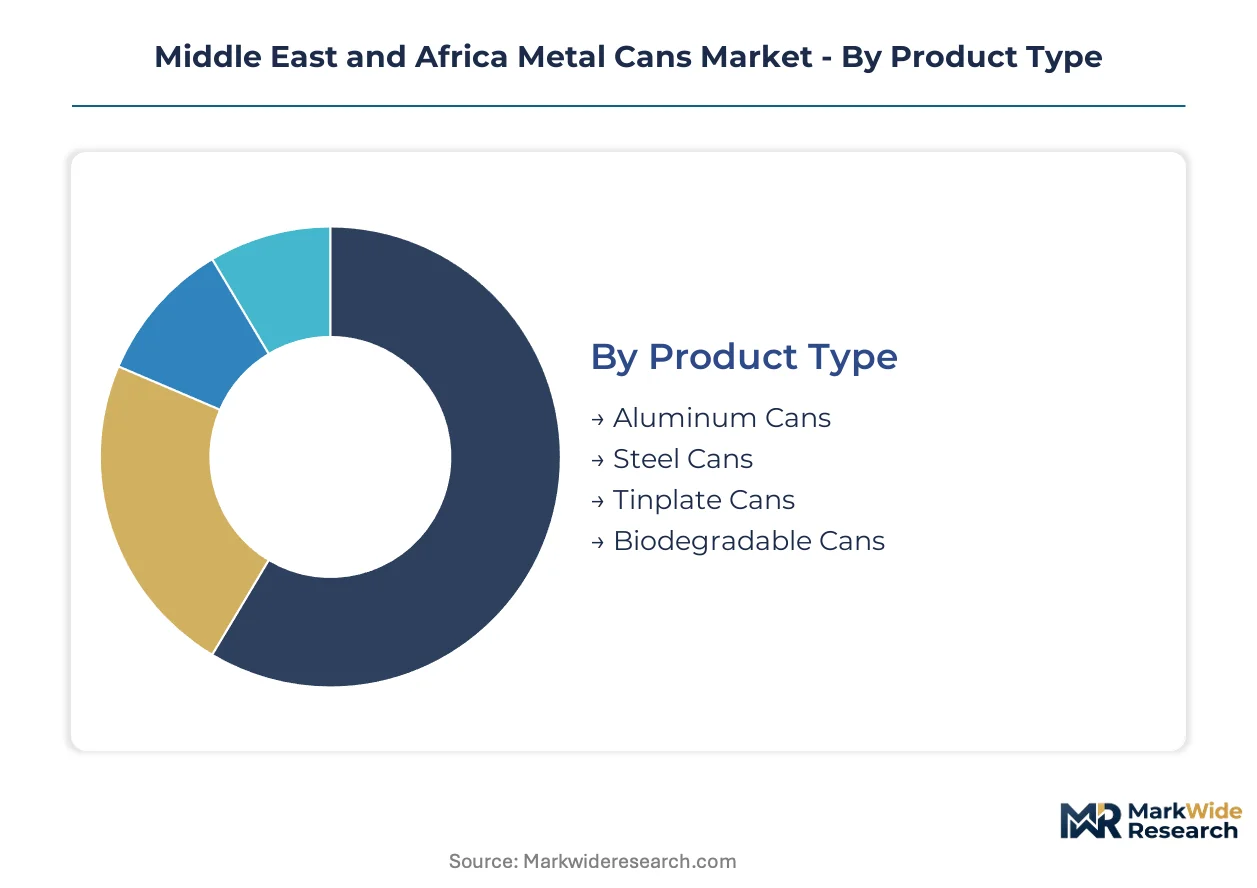
Segmentation in Middle East and Africa metal cans reveals distinct procurement rhythms across substrates and end-uses. Beverage bottlers rotate aluminum stock weekly while food processors commit to tinplate on quarterly cycles. Understanding these velocity differentials calibrates inventory positioning and working capital deployment for converters.
Product Type:
Aluminum cans turn inventory fastest through beverage bottler procurement cycles, while steel and tinplate formats lock capital longer due to food-industry contract structures. Biodegradable alternatives remain pre-commercial with extended qualification timelines.
- Aluminum Cans:Two-piece draw-and-iron construction from alloy 3104-H19 delivers axial load strength above 90 lbf for carbonated filling pressures. Saudi bottling groups and UAE franchises are consolidating procurement under direct mill contracts with price adjustment mechanisms. This segment anchors the volume base while biodegradable cans gain share at the steepest rate.
- Steel Cans:Three-piece welded bodies with tin-free steel or chromium-coated substrates withstand retort temperatures above 121°C for shelf-stable protein products. South African canneries are qualifying regional coil suppliers under NRCS extended producer responsibility mandates.
- Tinplate Cans:Cold-rolled low-carbon steel with electrolytic tin coating between 2.8-5.6 g/m² provides corrosion resistance for acidic food matrices. Nigerian tomato paste processors drive concentrated demand.
- Biodegradable Cans:Mycelium-based substrates laminated with metal barrier layers target premium organic beverage segments in Gulf markets. Pilot scale-up remains funding-constrained.
Aluminum cans dominate procurement velocity while biodegradable formats climb the fastest despite negligible current volume.
End User:
Cost tier stratification separates high-volume beverage procurement from specification-intensive food and chemical applications. Personal care commands premium lacquer specifications that filter supplier pools.
- Food Industry:Retort-processed vegetable and protein segments require internal epoxy-phenolic lacquers with migration limits enforced by Saudi SFDA and South Africa NRCS. Compliance documentation extends qualification cycles.
- Beverage Industry:Carbonated soft drink bottlers across GCC states are expanding aluminum can procurement as per-capita consumption rises. High-speed filling lines demand domestic coil supply reliability.
- Personal Care:Aerosol and cosmetic tins demand cosmetic-grade internal coatings with sensory neutrality. UAE fragrance houses specify gold-passivated tinplate for premium positioning.
- Chemical Industry:Industrial coatings and lubricant packaging requires chemical-resistant linings with UN-certified stacking performance. Paint manufacturers in Egypt and Morocco source through distributor networks.
Beverage industry procurement rotates fastest while food industry contracts deliver margin stability through volume commitments.
Application:
Volume concentration clusters in liquid refreshment while paint and oil applications fragment across industrial customer bases. Canned food specifications diverge by thermal process severity.
- Canned Food:Three-piece tinplate containers for tomato paste and cooking sauces concentrate demand in Nigeria's processing sector. Retort validation protocols strain regional laboratory capacity.
- Soft Drinks:Aluminum two-piece cans for carbonated and non-carbonated beverages scale through GCC bottler procurement. Direct-to-bottler distribution channels are compressing traditional trading house intermediation.
- Paint:Lever-lid steel cans with triple-tite closures serve architectural and industrial coating segments. South African manufacturers supply regional construction markets.
- Oil:Motor oil and edible oil tins require compatibility with hydrocarbon or lipid matrices. Ethiopian and Kenyan markets import finished cans pending indigenous capacity development.
Soft drinks anchor volume throughput while canned food applications expand most quickly through Nigerian processing investment.
Distribution Channel:
Customer type stratification separates high-frequency retail replenishment from project-based industrial procurement. Online retail penetration remains nascent for bulk metal packaging.
- Supermarkets:Hypermarket chains across Saudi Arabia and UAE drive standardized SKU procurement for beverage multipacks. Private-label canned food programs are expanding regional converter contracts.
- Convenience Stores:Small-format retail in urban Gulf clusters demands single-serve aluminum can availability. Chilled distribution requirements filter supplier geography.
- Online Retail:E-commerce beverage sales are scaling through direct-to-consumer fulfillment, though metal can shipping economics favor multi-pack aggregation. Last-mile refrigeration constraints limit penetration.
- Distributors:Traditional trading houses intermediate steel coil and finished can flows across North and East Africa. Gulf markets are bypassing these channels for direct mill relationships.
Supermarkets anchor procurement scale while distributor channel share compresses fastest under direct sourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates across Gulf Cooperation Council states are redirecting capital toward closed-loop recycling infrastructure. South Africa's NRCS framework and Saudi Arabia's SFDA compliance timelines are reshaping converter investment priorities. Substrate price volatility and regulatory divergence create divergent growth trajectories across the region.
Saudi Arabia
Carbonated beverage bottlers in Riyadh and Jeddah are scaling aluminum can procurement as per-capita soft drink consumption climbs. The Saudi Food and Drug Authority enforces accelerated migration testing protocols that strain third-party laboratory capacity during new product launches. The Eastern Province hosts integrated filling and distribution networks where direct-to-bottler coil contracts are displacing traditional trading house intermediation.
United Arab Emirates
UAE beverage franchises operating across Dubai and Abu Dhabi are consolidating procurement under single-source aluminum contracts with built-in price adjustment mechanisms. The Ministry of Health and Prevention aligns with Gulf Standardization Organization protocols for canned food imports, creating harmonized compliance thresholds. Hypermarket chains in urban clusters drive standardized SKU procurement for beverage multipacks while private-label canned food programs expand regional converter contracts.
South Africa
The National Regulator for Compulsory Specifications mandates minimum recycled content thresholds that accelerate closed-loop recycling investments among converters. Nampak Limited sustains its footprint via integrated steel and tinplate operations serving regional canneries. Retort-processed vegetable and protein segments in Gauteng and Western Cape require internal epoxy-phenolic lacquers with tightened migration limits aligned to EFSA precautionary thresholds.
Nigeria
Food processing sector expansion in Lagos and Kano is generating concentrated demand for three-piece tinplate containers for shelf-stable tomato paste and cooking sauces. The country's national food safety regulator enforces food-contact material standards that dictate internal lacquer specifications. Local canneries are qualifying regional steel substrate suppliers to reduce European and Asian import dependency.
Egypt
Paint manufacturers in Cairo and Alexandria source lever-lid steel cans through distributor networks serving architectural and industrial coating segments. The country's standardization body maintains chemical-resistant lining requirements for industrial coatings and lubricant packaging. Construction market recovery is driving regional demand for UN-certified stacking performance in metal packaging applications.
Middle East and Africa Metal Cans Market Competitive Landscape
On the supply side, the industry is consolidating around integrated coil-coating infrastructure and direct mill relationships that compress traditional distribution channels. Tiered competitive positioning separates multinational fabricators with regional coating assets from mid-cap specialists serving single-country demand pockets. Two dominant archetypes define the field: beverage-focused aluminum converters leveraging lightweighting technology leadership, and diversified metal packaging groups sustaining food-can capabilities through tinplate and steel substrate integration. Competitive moves center on backward integration into coil supply and geographic expansion through greenfield coating investments in underpenetrated East African markets.
Among North American-based multinational fabricators, Crown Holdings, Inc. and Ball Corporation exemplify the beverage-focused archetype through their regional infrastructure positioning. Crown Holdings leverages coil-coating assets to anchor long-term contracts with Saudi bottling groups, while Ball Corporation competes through technology leadership in aluminum beverage formats. South Africa's Nampak Limited occupies a distinct position within the diversified metal packaging tier, sustaining integrated steel and tinplate operations that serve food-can demand across southern African markets. These three anchors illustrate how substrate specialization and geographic footprint alignment determine competitive positioning in a market where regulatory compliance and price volatility filter participant economics.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group S.A. |
| SAPIN Saudi Arabian Packaging Industry |
| CANPACK S.A. |
| Nampak Limited |
| Middle East Metal Can LLC |
| Gulf Cans Industries |
| Avon Crowncaps & Containers Nigeria Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in GCC aluminum coil coating is compressing converter margins while amplifying pricing power for integrated mill operators serving Saudi bottling groups. Beverage procurement consolidation under direct contracts is forcing trading houses to absorb volatility or exit intermediation entirely.
Pricing Analysis
Volume-discount tiering structures separate multinational bottler contracts from spot purchases by regional canneries. Three-tier pricing stratifies across premium lacquer specifications for personal care, standard beverage-grade coil, and economy tinplate for processed foods. Pricing pressure stems from London Metal Exchange aluminum volatility that converters cannot fully pass through under long-term offtake agreements. Food processors in Nigeria exhibit highest price sensitivity due to currency exposure, while Gulf beverage franchises prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between European steel mills and Nigerian food processors dominates supply chain risk calculus for tinplate-dependent segments. Raw material flows draw from Saudi aluminum smelters, South African steel producers, and Chinese tinplate exporters. Single-source vulnerability concentrates in European lacquer suppliers for food-contact coatings. Distribution runs through direct mill relationships in Gulf markets while East African demand feeds from Dubai trading hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa metal cans market is entering a cyclical recovery phase as extended producer responsibility mandates across GCC states force capital redeployment into compliant infrastructure. Aluminum price normalization and beverage volume expansion provide the cyclical foundation.
For Market Incumbents: Insulate margin structures through captive coil-coating capacity in Saudi Arabia's Eastern Province. Secure SFDA pre-approval for lacquer formulations to compress new product launch timelines. Defend against biodegradable can substitutes by accelerating lightweighting roadmaps that maintain cost parity with emerging substrate technologies.
For New Entrants and Emerging Players: Pursue greenfield coil coating investments in Ethiopia and Kenya where indigenous two-piece aluminum can manufacturing remains absent. Target beverage bottler procurement consolidation in underpenetrated East African markets. Establish direct-to-bottler distribution channels that bypass Dubai-based trading house intermediation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated steel-tinplate operators serving South African food canneries under NRCS extended producer responsibility contracts. Long-term viability over a 5-10 year window favors converters with backward integration into regional substrate supply. Monitor aluminum price volatility inflection as the signal for margin expansion timing in beverage-focused assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Coating | Crown Holdings anchors Saudi bottler contracts through regional coating infrastructure ownership. |
| Direct-to-Bottler Distribution Expansion | UAE beverage franchises bypass trading houses to compress working capital cycles and improve traceability. |
| Closed-Loop Recycling Infrastructure | South African converters invest under NRCS mandates to secure compliance certification for food-contact applications. |
| Lightweighting Technology Deployment | Ball Corporation competes through finite-element modeling that virtualizes traditional die development cycles. |
| East African Greenfield Capacity | Import substitution opportunities in Ethiopia and Kenya target beverage bottler procurement consolidation. |
Research Methodology
The analysis maps aluminum beverage cans, steel food cans, tinplate processed food containers, and biodegradable substrate prototypes, each validated through converter operations directors, beverage bottler procurement heads, food cannery technical managers, and regulatory compliance officers at SFDA and NRCS. Primary fieldwork combined with secondary validation from customs trade databases, SEC filings of listed packaging groups, Gulf Standardization Organization protocols, and London Metal Exchange price records. Bottom-up volume builds triangulated against top-down substrate consumption estimates.
Assumptions held fixed include regulatory compliance timelines at SFDA and NRCS, aluminum smelter capacity utilization in GCC states, and extended producer responsibility enforcement intensity. Variables modeled across the projection horizon include substrate price volatility bands, beverage volume growth trajectories, and biodegradable can technology maturation. Segmentation dimensions incorporated substrate type, end-use industry, application format, and distribution channel structure. CAGRs derived from regression against historical volume-price relationships with scenario-weighted probability distributions.
Macroeconomic conditions sit as an overlay; deviation in Gulf currency peg stability, Nigerian naira convertibility, or South African electricity grid reliability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and substrate supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Metal Drums Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Aluminum Cans Market