
 Food Grade Stainless Steel Container Market | 2026-2036
Food Grade Stainless Steel Container Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Stainless Steel Container Market Insights
Skilled welders certified for orbital TIG welding of sanitary joints is unwinding capacity expansion at several fabrication yards. THERMOS leverages backward integration into raw steel sourcing to stabilize alloy costs across its Asian production network. Tiger Corporation anchors its competitive stance through precision vacuum insulation technology for temperature-critical food logistics. Zojirushi differentiates via proprietary electropolishing protocols that exceed baseline FDA surface finish requirements.
Food grade stainless steel containers are engineered vessels fabricated from corrosion-resistant austenitic or ferritic alloys, typically containing 10.5% minimum chromium with controlled carbon content below 0.08%, designed to prevent metallic contamination during storage, transport, and processing of consumable products. Manufacturing employs seamless drawing or welded construction with passivation and electropolishing to achieve Ra 0.8 micrometer surface finishes that inhibit bacterial adhesion. Drums and tanks dominate current volume flows, with 316 stainless steel commanding premium positioning due to molybdenum-enhanced pitting resistance in chloride-rich dairy and brine environments. Pharmaceutical packaging applications are gaining structural traction as FDA 21 CFR Part 177 compliance becomes mandatory for drug-contact surfaces.
FDA 21 CFR standards and EU Regulation 1935/2004 govern material migration limits and surface integrity for food-contact applications, while ISO 22000 and 3-A Sanitary Standards dictate fabrication protocols that shape procurement specifications across dairy and beverage end users. REACH compliance in Europe and China's GB 4806.9-2016 national food safety standards further fragment certification burdens for multinational suppliers. Stakeholders must monitor evolving alloy traceability mandates and energy-intensive electropolishing cost structures as sustainability disclosures intensify across downstream buying committees.
Market Dynamics
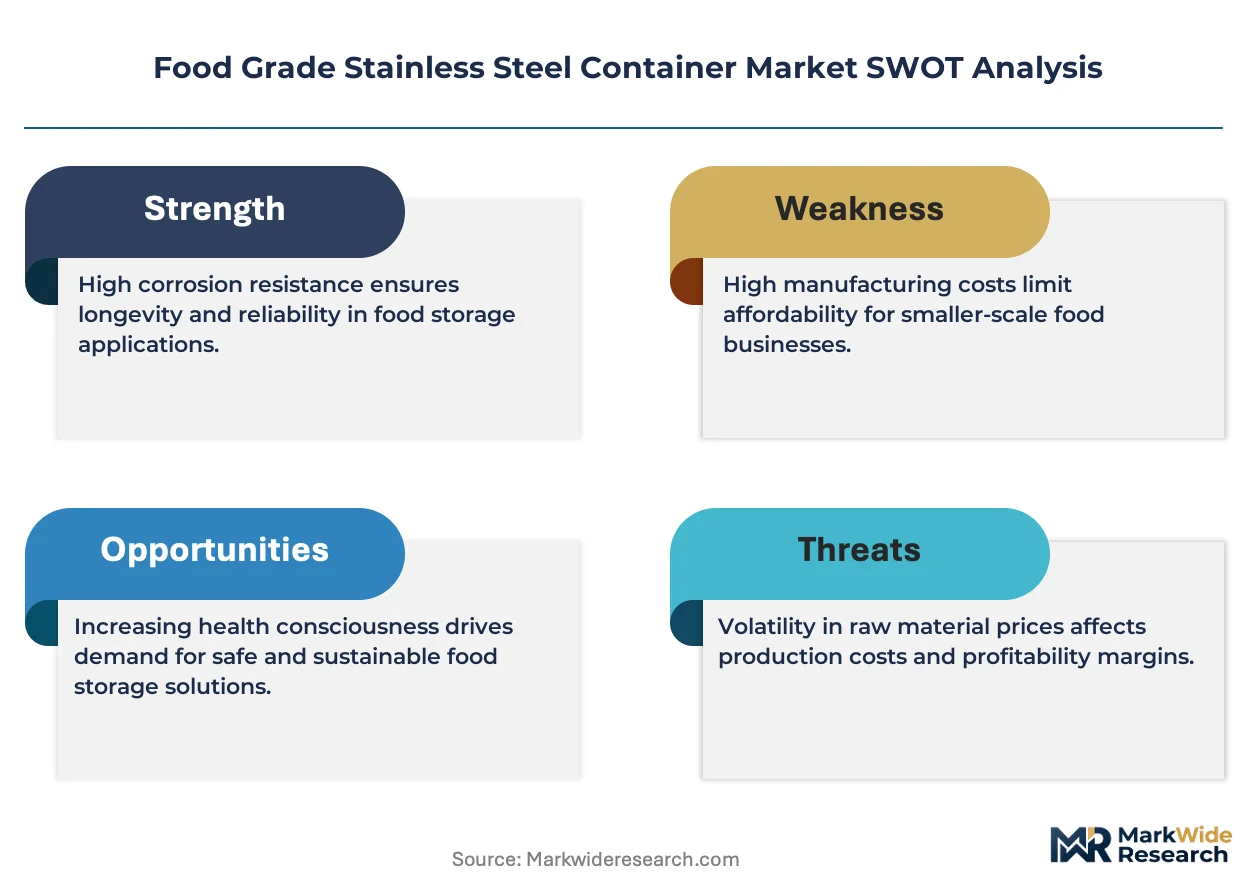
Orbital TIG welding certification shortages are compressing fabrication capacity across European and North American sanitary vessel yards, forcing dairy processors to extend lead times for 316-grade pasteurization tanks.
Growth Catalysts
- EFSA Pasteurization Mandates:German dairy cooperatives are replacing carbon steel infrastructure with electropolished 316L vessels to meet thermal processing integrity requirements.
- Pharmaceutical Packaging Migration:FDA 21 CFR Part 177 compliance is becoming mandatory for drug-contact surfaces, pulling stainless steel drum demand from food into biologics cold chain.
- Electropolishing Automation:Robotic surface finishing lines are reducing Ra 0.8 micrometer achievement costs, expanding accessible supply for mid-scale beverage processors.
Market Restraints
- Nickel Alloy Volatility:Molybdenum and nickel spot price swings are compressing margin predictability for 316-grade fabricators locked into annual supply contracts.
- Welder Certification Bottleneck:ASME IX and 3-A Sanitary Standards orbital welding credentials require 18-month training cycles, constraining European yard expansion.
- Composite Drum Substitution:High-density polyethylene IBC totes are capturing non-thermal liquid food logistics where metallic contamination risk is minimal.
Strategic Opportunities
- Indian Cold Chain Buildout:FSSAI enforcement of hygienic packaging standards is creating first-time stainless steel vessel demand in dairy processing clusters around Pune and Gujarat.
- EU Green Deal Carbon Border Adjustments:Electropolishing energy intensity disclosures are favoring fabricators with captive renewable power in Nordic production zones.
- Smart Container Convergence:Integration of LoRaWAN temperature sensors with vacuum-insulated stainless steel logistics units is opening premium tracking service revenue streams.
Industry Challenges
- Sanitary Welding Talent Scarcity:Pipeline welders lack orbital TIG certification for Ra 0.8 surface continuity, forcing fabricators to poach from aerospace precision shops.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA, EFSA, and GB 4806.9-2016 approval cycles are extending product launch timelines for multinational food brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Stainless Steel Container Market |
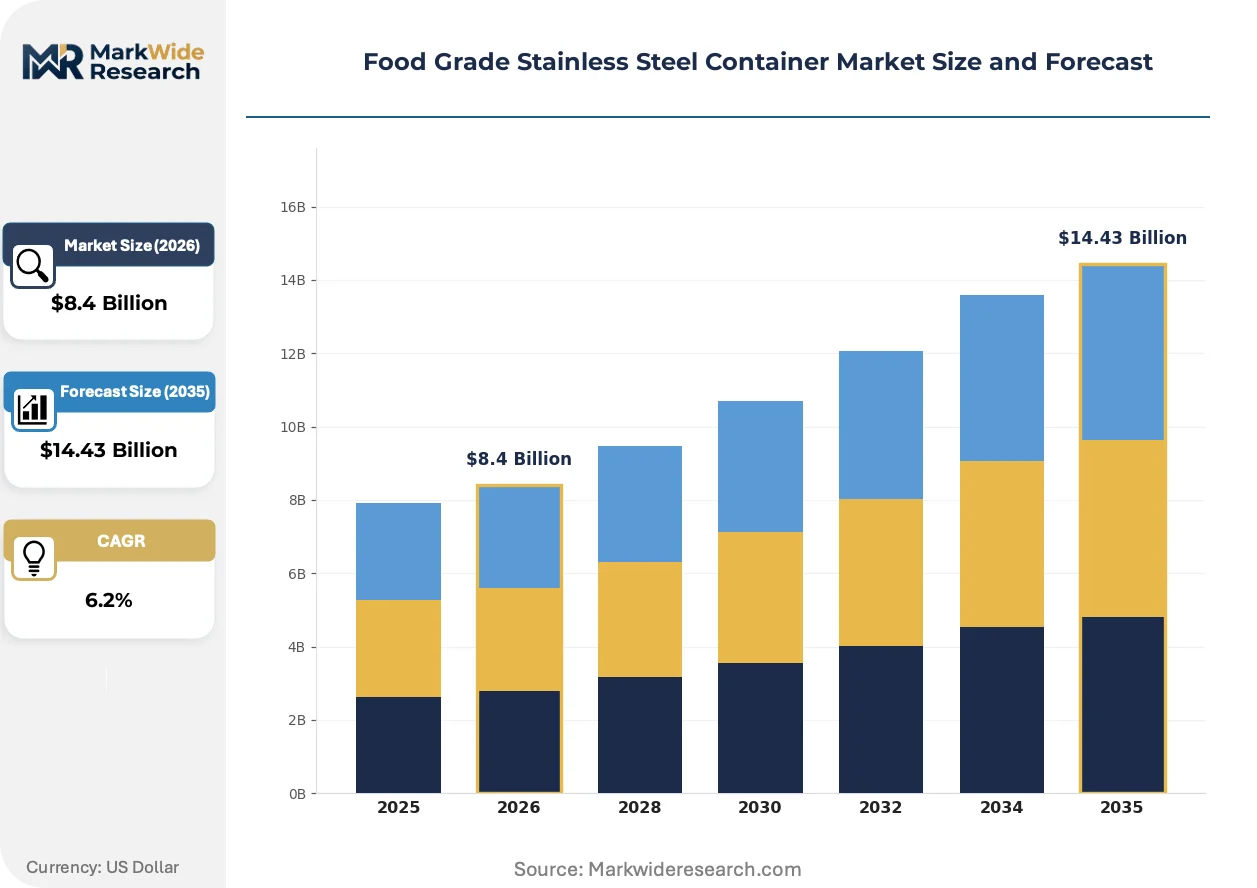
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Grade: 304 Stainless Steel, 316 Stainless Steel, 430 Stainless Steel, 201 Stainless Steel, 310 Stainless Steel Container Type: Drums, Tanks, Jars, Barrels, Pails Application: Food Processing, Beverage Storage, Dairy Handling, Pharmaceutical Packaging, Cosmetic Storage End User Industry: Food Manufacturers, Beverage Producers, Dairy Plants, Pharmaceutical Companies, Cosmetic Manufacturers |
| Companies Covered | THERMOS, Tiger Corporation, Zojirushi, LOCK and LOCK, Klean Kanteen, Aladdin (PMI), Asvel, Stanley, Thielmann - The Container Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Stainless Steel Container Market Trends and Innovations
Surface engineering and traceability technologies are redefining competitive differentiation in sanitary vessel fabrication, compressing traditional cost-based procurement models.
Electropolishing automation is displacing manual finishing across mid-cap fabrication yards. Dairy processors in Wisconsin and Bavaria are specifying robotic Ra 0.8 surface achievement in new tank procurement tenders. This shift is compressing price premiums between European and Asian supply sources.
REACH alloy traceability mandates are forcing upstream documentation investments. ECHA substance of very high concern screening now extends to molybdenum sourcing in 316-grade production. German fabricators are responding by locking multi-year mill certifications from Finnish stainless steel producers.
Buyer consolidation among multinational dairy cooperatives is compressing vendor counts. Procurement committees now mandate single-source accountability for tank fabrication, electropolishing, and installation. This pattern is most visible in Netherlands-based dairy logistics networks standardizing on integrated vessel-service contracts.
Food Grade Stainless Steel Container Market Segmentation
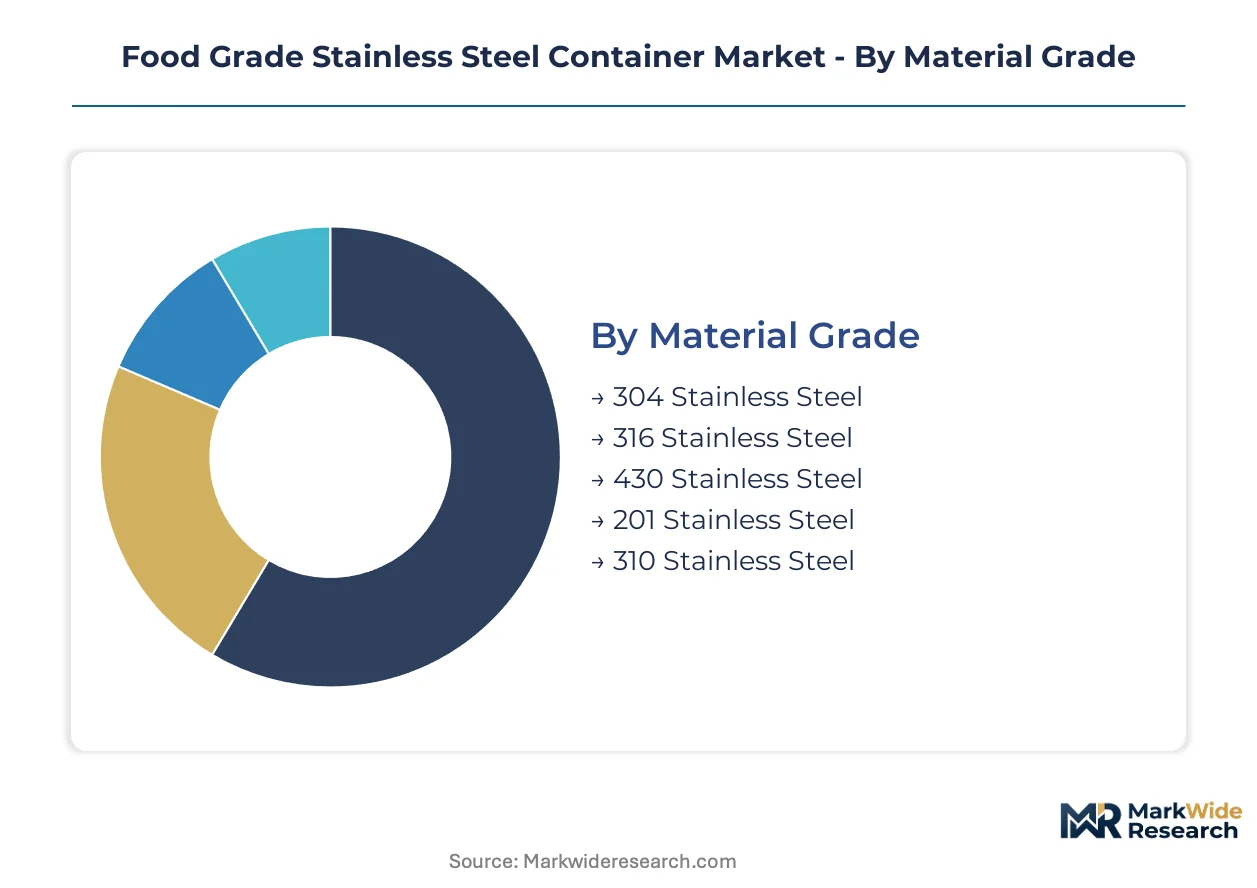
Material grade selection dictates corrosion resistance thresholds and regulatory compliance pathways across food-contact applications. Container geometry and application specificity determine fabrication complexity and surface finish requirements. End-user procurement patterns cluster around pasteurization integrity, cold chain reliability, and multi-jurisdiction certification burdens.
Material Grade:
Domestic demand concentrates on 304-grade for standard food handling, while export-led procurement drives 316-grade specifications for chloride-rich dairy and brine environments.
- 304 Stainless Steel:Austenitic alloy with 18% chromium and 8% nickel content delivers baseline corrosion resistance for dry goods and neutral pH liquid foods. Bavarian beverage processors specify 304-grade for non-chlorinated water storage tanks under EFSA migration limits. Cost positioning enables volume deployment across mid-scale food manufacturers.
- 316 Stainless Steel:Molybdenum-enhanced austenitic formulation provides pitting resistance in salt-laden and acidic food matrices. Wisconsin dairy cooperatives mandate 316L electropolished vessels for HTST pasteurization systems under FDA Grade A Pasteurized Milk Ordinance. Premium positioning reflects ASME IX welding certification requirements.
- 430 Stainless Steel:Ferritic alloy with 16-18% chromium offers magnetic properties for specialized handling equipment.
- 201 Stainless Steel:Manganese-substituted austenitic grade serves cost-sensitive Asian food processing markets.
- 310 Stainless Steel:High-chromium nickel alloy withstands thermal cycling in industrial baking and roasting applications.
304-grade holds the largest share; momentum sits with 316-grade as chloride-exposure applications expand.
Container Type:
Volume concentration favors cylindrical geometries optimized for automated handling and stackable logistics.
- Drums:Standardized 55-gallon cylindrical vessels with rolled rims and clamp-ring closures facilitate liquid and semi-solid food transport. Pharmaceutical cold chain operators in Germany specify UN-certified 316-grade drums for temperature-sensitive biologics under EU GDP guidelines. Robotic seam welding reduces unit cost differentials against composite alternatives.
- Tanks:Vertical and horizontal cylindrical vessels range from 1,000 to 50,000-liter capacities for stationary processing and storage. Indian dairy clusters around Pune deploy 316L vertical tanks with CIP spray balls under FSSAI hygienic packaging enforcement. Vessel fabrication lead times stretch to 24 weeks due to orbital TIG certification scarcity.
- Jars:Wide-mouth cylindrical containers serve high-viscosity food and cosmetic applications.
- Barrels:Traditional cooperage-replacement formats preserve wine and spirits maturation protocols.
- Pails:Tapered-wall containers optimize nesting density for retail and institutional food service distribution.
Tanks dominate stationary processing investment; drums gain share in pharmaceutical logistics migration.
Application:
Regulatory stringency fragments procurement specifications across thermal processing, aseptic filling, and cold chain preservation.
- Food Processing:Vessels for mixing, cooking, and thermal treatment require Ra 0.8 micrometer surface finishes to inhibit biofilm formation. US meat processors specify 316-grade under USDA-FSIS HACCP validation protocols.
- Beverage Storage:Tanks for wine, beer, and soft drinks prioritize flavor neutrality and CIP compatibility. French cooperatives mandate electropolished 304-grade for champagne secondary fermentation.
- Dairy Handling:Pasteurization and cheese-making vessels demand molybdenum-enhanced alloys for chloride resistance. German Molkerei installations accelerate 316L replacement of legacy carbon steel under EFSA thermal integrity mandates.
- Pharmaceutical Packaging:FDA 21 CFR Part 177 compliance for drug-contact surfaces pulls stainless steel demand from food into biologics containment.
- Cosmetic Storage:Surface finish requirements mirror pharmaceutical standards for preservative-free formulation protection.
Dairy handling anchors current volume; pharmaceutical packaging climbs fastest on regulatory compliance migration.
End User Industry:
Procurement consolidation among multinational operators compresses vendor counts and extends contract durations.
- Food Manufacturers:Diversified processors specify grade-flexible vessel fleets across dry goods, sauces, and ready-to-eat categories. Nestlé procurement standardization drives integrated fabrication-electropolishing-installation contracts.
- Beverage Producers:Wineries and breweries prioritize vintage-dated tank traceability and oxygen transfer rate control. Champagne houses specify mill-certified 304-grade from Finnish stainless producers.
- Dairy Plants:Cooperative-owned processing facilities mandate 316L for pasteurization and CIP systems. Wisconsin and Bavarian clusters concentrate tank installation demand.
- Pharmaceutical Companies:Biologics manufacturers require ASME BPE-compliant surface finishes and full alloy documentation.
- Cosmetic Manufacturers:Clean beauty formulators adopt pharmaceutical-grade specifications for preservative-free product protection.
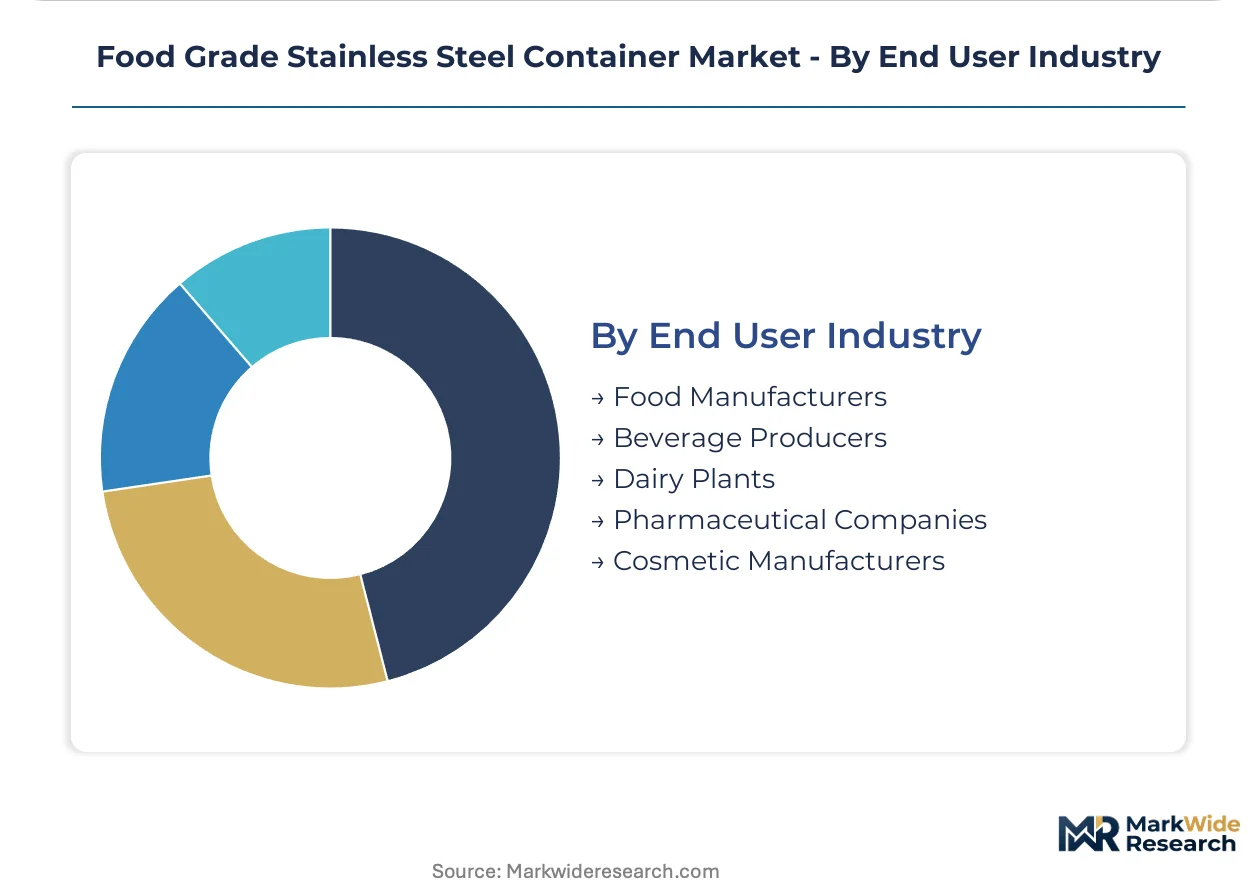
Dairy plants command the largest installed base; pharmaceutical companies drive specification escalation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pasteurization mandates anchor North American demand, while EFSA thermal integrity protocols and FSSAI hygienic packaging standards fragment procurement specifications across Germany, India, and Japan. Alloy traceability requirements under REACH and GB 4806.9-2016 further complicate multinational supply chain configurations.
United States
Wisconsin dairy cooperatives mandate 316L electropolished vessels for HTST pasteurization systems under FDA Grade A Pasteurized Milk Ordinance. USDA-FSIS HACCP validation protocols drive specification escalation across meat processing corridors. Fabrication yards in the Upper Midwest face 24-week lead times due to ASME IX orbital TIG certification scarcity.
Germany
Bavarian Molkerei installations accelerate carbon steel replacement with 316-grade pasteurization tanks to meet EFSA thermal processing integrity requirements. ECHA substance of very high concern screening now extends to molybdenum sourcing in 316-grade production. German fabricators lock multi-year mill certifications from Finnish stainless steel producers to satisfy REACH alloy traceability mandates.
India
FSSAI enforcement of hygienic packaging standards creates first-time stainless steel vessel demand in dairy processing clusters around Pune and Gujarat. CDSCO alignment with FDA 21 CFR Part 177 protocols pulls pharmaceutical-grade specifications into domestic biologics containment. Indian cold chain buildout concentrates tank procurement in Maharashtra and Gujarat processing corridors.
Japan
METI industrial standards and JIS certification requirements shape precision fabrication protocols for temperature-critical food logistics. Vacuum insulation technology development clusters in Osaka-Nagoya manufacturing belts. Japanese fabricators prioritize electropolishing automation to achieve Ra 0.8 micrometer surface finishes for export pharmaceutical packaging applications.
China
GB 4806.9-2016 national food safety standards fragment certification burdens for multinational suppliers serving domestic dairy processors. SAMR enforcement intensifies alloy traceability documentation across Yangtze River Delta fabrication networks. Chinese producers leverage backward integration into raw steel sourcing to stabilize molybdenum-enhanced alloy costs.
Food Grade Stainless Steel Container Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sanitary vessel fabrication. The upper tier commands captive alloy sourcing and robotic electropolishing automation, while mid-cap fabricators compete on orbital TIG welding certification depth. Three archetypes dominate: precision vacuum insulation specialists, electropolishing protocol innovators, and backward-integrated steel sourcers. Competitive moves concentrate on M&A for welding talent acquisition and capacity expansion in Nordic renewable-powered production zones.
Among Asia-Pacific-based fabricators, THERMOS exemplifies backward-integrated raw steel sourcing archetypes, Tiger Corporation anchors precision vacuum insulation positioning for temperature-critical logistics, and Zojirushi occupies electropolishing protocol differentiation. These three represent divergent competitive vectors within the premium sanitary vessel tier. European and North American yards compete through ASME IX certification depth rather than cost positioning.
| Leading Market Players |
|---|
| THERMOS |
| Tiger Corporation |
| Zojirushi |
| LOCK and LOCK |
| Klean Kanteen |
| Aladdin (PMI) |
| Asvel |
| Stanley |
| Thielmann - The Container Company |
| Others |
Pricing and Supply Chain Analysis
Composite drum substitution into non-thermal liquid food logistics simultaneously redistributes procurement geography toward Asian polymer converters and compresses pricing power at European 304-grade fabricators serving cost-sensitive beverage processors. This displacement dynamic forces stainless steel producers to defend position through 316-grade certification premiums while molybdenum price volatility erodes margin predictability on locked annual contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational dairy cooperatives and integrated fabricators, insulating 316-grade pasteurization tank supply from spot nickel volatility while compressing margins for mid-cap yards without captive mill relationships. Price differentiation separates ASME IX-certified orbital welding premiums from standard fabrication, with Wisconsin dairy processors least sensitive due to regulatory compliance mandates and Asian dry goods handlers most responsive to alloy cost swings. Pricing pressure intensifies in 304-grade beverage storage as robotic electropolishing automation narrows European-Asian cost gaps.
Supply Chain Analysis
Strategic stockpiling of molybdenum-enhanced alloy feedstock prevails among German and Finnish integrated producers, insulating against nickel spot volatility while just-in-time raw material flows characterize cost-optimized Asian fabrication networks serving standardized drum demand. Geographic supply concentration centers on Finland, Germany, and China for 316-grade mill certifications, with fabrication capacity clustering in Wisconsin, Bavaria, and Maharashtra processing corridors. The supply chain rests on chromium ore sourcing from South Africa and Turkey, molybdenum from Chile and Peru, and nickel from Indonesia and Russia. Single-source vulnerability concentrates in orbital TIG welding certification pipelines. Distribution runs through dairy cooperative procurement committees, pharmaceutical cold chain operators, and beverage processor tender networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FSSAI enforcement of hygienic packaging standards penetrates Indian dairy processing for the first time, creating structural vessel demand without legacy carbon steel replacement dynamics.
For Market Incumbents: Fortify captive mill certification relationships with Finnish and German stainless producers to secure molybdenum traceability documentation under REACH mandates. Deepen orbital TIG welding certification pipelines through aerospace talent poaching and in-house training academies. Defend against composite drum substitution by bundling electropolishing automation with IoT temperature tracking in premium logistics contracts. For New Entrants and Emerging Players: After-sales service integration gaps in mid-scale Indian dairy clusters offer white-space entry where incumbents focus on turnkey installation without localized maintenance networks. Target Pune and Gujarat processing corridors with 316L vertical tank offerings paired with CIP spray ball retrofit services. Pursue FSSAI certification fast-track partnerships with Maharashtra state dairy federations as beachhead positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European fabrication yards holding ASME IX certification depth but lacking robotic electropolishing automation. Long-term viability favors integrated producers with backward steel sourcing and renewable-powered finishing capacity. Monitor Nordic production zone electropolishing energy disclosure compliance as inflection signal for margin compression at carbon-intensive competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Orbital TIG Welding Certification Expansion | ASME IX credential depth separates premium 316-grade fabricators from commodity competitors in pasteurization tank procurement. |
| Robotic Electropolishing Automation | Ra 0.8 micrometer achievement cost compression narrows European-Asian supply price gaps in mid-scale beverage processor tenders. |
| Backward Integration into Raw Steel Sourcing | Captive molybdenum-enhanced alloy supply stabilizes margin predictability against LME nickel volatility for integrated producers. |
| Smart Container IoT Integration | LoRaWAN temperature sensor bundling with vacuum-insulated vessels opens premium service revenue streams in pharmaceutical cold chain logistics. |
| REACH Alloy Traceability Lock-in | Multi-year mill certifications from Finnish producers satisfy ECHA substance screening mandates and defend procurement position in German Molkerei networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, stainless steel mill certification registries, and dairy cooperative procurement disclosures. Primary interviews engaged fabrication yard operations directors, dairy plant engineering managers, pharmaceutical cold chain logistics heads, and FSSAI compliance officers across Maharashtra and Gujarat. Secondary validation drew from EFSA thermal processing guidelines, FDA 21 CFR Part 177 protocols, REACH substance screening databases, and ISO 22000 certification records. Bottom-up vessel installation tracking triangulates against top-down alloy consumption estimates from chromium and molybdenum trade flows.
Segmentation dimensions modeled include material grade tier, container geometry, application specificity, and end-user industry procurement consolidation patterns across the projection horizon. CAGRs derive from installation run-rate analysis, replacement cycle timing, and regulatory compliance mandate phase-ins. Industry-specific forecast inputs incorporate orbital TIG welding certification pipeline constraints and FSSAI enforcement trajectory in Indian dairy processing corridors.
Underlying assumptions cover sustained EFSA and FDA pasteurization integrity mandates, with deviation risk concentrated in composite drum substitution acceleration and nickel alloy price volatility spikes. Forecasts reflect these conditions without scenario-weighted probability adjustments. Revision becomes warranted when composite drum penetration in non-thermal liquid food logistics crosses threshold adoption rates among top-ten multinational dairy cooperatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
APAC Container Technology Market
Containers
Sanitary Cans Market
Containers
Cups and Lids Market
Containers
Wire Containers Market
Containers
Foldable Container Market
Containers
Takeout Containers Market
Containers
Thermoformed Containers Market
Containers
Two Compartment Bottles Market
Containers
Jug Shipper Market
Containers
Lab Storage Container Market
Containers
Disposable Lids Market
Containers
Hinged Lid Tins Market
Containers
Container Stacking Machine Market
Containers
Screw Top Pails Market
Containers
Reconditioned IBC Market
Containers
Popcorn Containers Market