
 Carboy Market | 2026-2036
Carboy Market Size, Share, and Industry Trends Forecast 2026-2036
Carboy Market Outlook
Pharmaceutical lab procurement is pivoting toward plastic carboys as single-use bioprocessing expands across sterile manufacturing lines. Thermo Fisher Scientific leverages its distribution network to dominate North American lab supply channels. Sigma-Aldrich (Merck) anchors European demand through its chemical catalog reach. Corning Inc. specializes in borosilicate glass variants for high-purity applications where thermal resistance commands premium positioning.
A carboy is a rigid, necked container typically manufactured from borosilicate glass, high-density polyethylene, or polyvinyl chloride, designed for storing and transporting liquids in volumes ranging from five to twenty liters. Glass carboys retain dominance in fermentation applications where oxygen permeability must approach zero, while HDPE variants capture transport and storage share due to impact resistance and lighter tare weight. Laboratory use applications generate concentrated margin pools because certification requirements and sterile handling protocols justify premium pricing over commodity beverage and chemical segments.
US FDA 21 CFR Part 177 governs indirect food-contact polymers in beverage and pharma applications, while EPA container regulations under 40 CFR impose design and labeling standards for chemical transport carboys. ISO 4796 specifies dimensional and performance benchmarks for laboratory glassware, creating compliance thresholds that filter low-cost Asian suppliers from certified procurement lists. Stakeholders must monitor evolving biopharma single-use standards and polymer recycling mandates to anticipate material substitution cycles and capacity planning decisions.
Market Dynamics
Single-use bioprocessing is absorbing sterile fluid handling volumes from reusable glass systems, compressing capital equipment cycles and rewiring procurement relationships across pharmaceutical manufacturing networks.
Growth Catalysts
- US FDA 21 CFR Part 177:Indirect food-contact polymer standards are validating HDPE carboy formats for pharmaceutical sterile media, expanding addressable demand in parenteral drug manufacturing.
- Biopharma cluster concentration:Heidelberg-Mannheim corridor demand is scaling certified container procurement for cell culture media storage, creating regional capacity pull for ISO 4796-compliant suppliers.
- Polymer sterilization advances:Gamma-stable HDPE formulations are displacing autoclave-dependent glass in vaccine production workflows, shortening batch turnaround times.
Market Restraints
- Petrochemical feedstock volatility:HDPE resin prices track ethylene cracker margins, compressing converter margins during upstream energy price spikes.
- Asian supplier certification gaps:ISO 4796 dimensional tolerances filter low-cost borosilicate glass imports from uncertified Chinese manufacturers, limiting procurement optionality.
- Glass thermal performance floor:Oxygen permeability near zero in borosilicate formats blocks full polymer substitution in long-duration fermentation applications.
Strategic Opportunities
- India biopharma manufacturing:CDSCO sterile product regulations are mandating certified container traceability, opening procurement windows for ISO-compliant HDPE suppliers.
- Closed-system aseptic connectors:Convergence of single-use bioprocessing with ready-to-use carboy formats is collapsing sterile welding steps in fill-finish operations.
- EU Green Deal polymer recycling:REACH-compliant recycled HDPE streams are creating certified circular material pathways for non-pharma chemical transport segments.
Industry Challenges
- ISO 4796 certification timelines:Laboratory glassware dimensional validation requires 18-24 month testing cycles, delaying new supplier market entry.
- Cleanroom molding capacity:Gamma-sterile HDPE carboy production demands ISO Class 7 injection environments, constraining qualified manufacturing footprint expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboy Market |
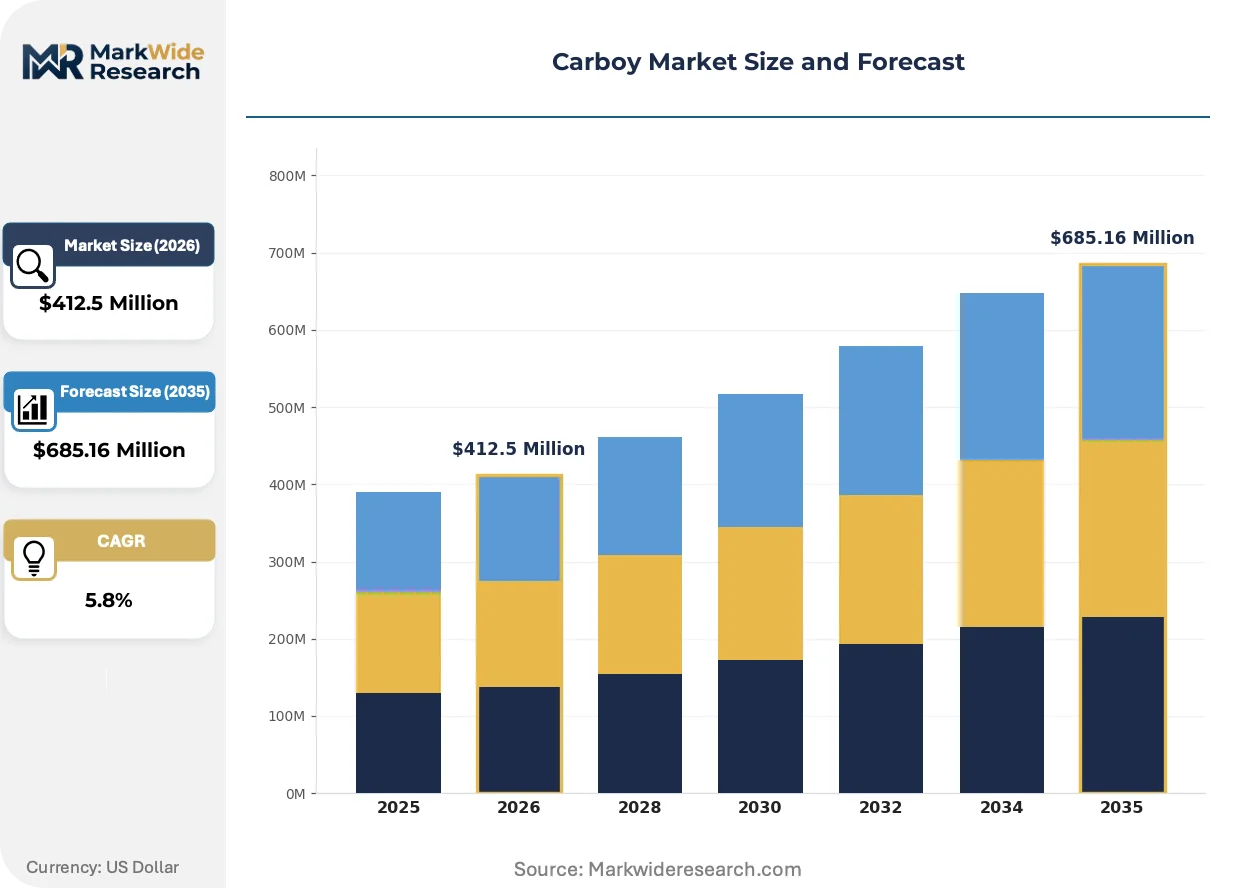
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, HDPE, PVC End User: Beverage Industry, Pharmaceutical Labs, Chemical Manufacturing, Educational Institutions Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters Application: Fermentation, Storage, Transport, Laboratory Use |
| Companies Covered | Sterlitech, Marin Scientific Development, Thermo Fisher Scientific, Sigma-Aldrich (Merck), Metro Ace Innovplas, Veritiv, Deluxe Scientific Surgico, Corning Inc., Globe Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboy Market Strategic Shifts
Material science and regulatory stringency are converging to compress product lifecycles, with sterile handling protocols and sustainability mandates forcing simultaneous performance and environmental upgrades across container formats.
Co-extruded HDPE barrier structures are absorbing oxygen ingress requirements previously served by glass, enabling 18-month shelf stability in cell culture media applications. Biopharma contract manufacturers are adopting these formats at pilot-scale first, with the technology compressing capital intensity in multi-product facilities by eliminating autoclave infrastructure.
EPA 40 CFR chemical container regulations are tightening labeling and closure integrity standards for hazardous material transport, forcing HDPE molders to redesign thread geometries and gasket retention systems. Chemical distributors in the US Gulf Coast corridor are absorbing compliance costs through specification consolidation, reducing qualified supplier pools.
Consolidated buying through group purchasing organizations is collapsing distributor tier counts in North American laboratory supply. Academic research institutions and mid-tier pharma are bypassing catalog intermediaries for direct manufacturer contracts, with the shift most visible in high-volume sterile media procurement across the Boston-Cambridge biotech cluster.
Carboy Market Segmentation
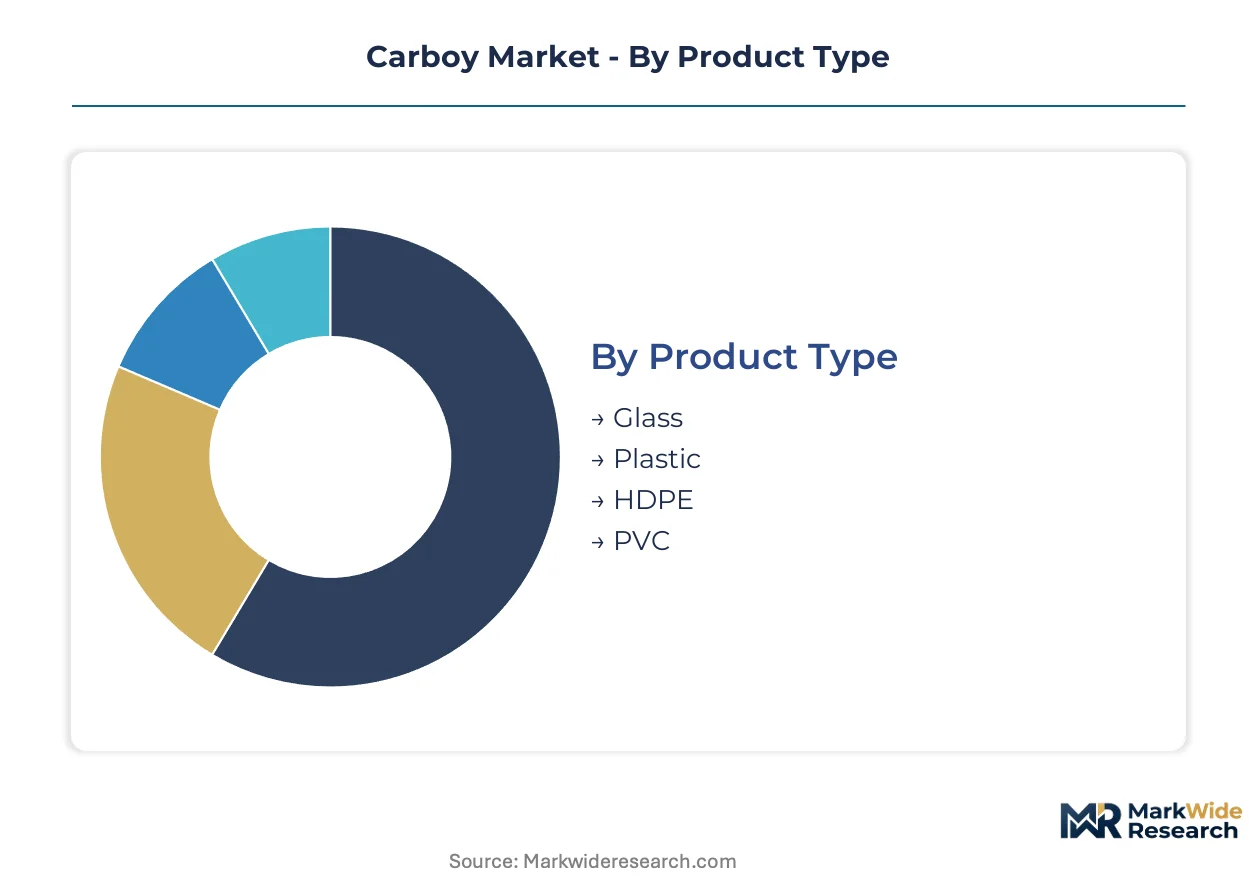
Carboy segmentation reveals distinct performance requirements across material formats and use environments. Material selection drives regulatory compliance pathways, while capacity and application dimensions determine procurement relationships and margin structures.
Product Type:
Glass formats operate as standalone capital equipment in fermentation workflows, while polymer variants embed into single-use disposable systems. HDPE and PVC segments reflect this embedded-system transition most acutely.
- Glass:Borosilicate construction delivers near-zero oxygen permeability for long-duration fermentation. Demand concentrates in craft brewing and vintage wine aging applications across Germany's Baden-Württemberg corridor, where thermal shock resistance commands specification priority.
- Plastic:Polymer blends serve chemical transport and educational procurement where impact resistance outweighs gas barrier requirements. US Gulf Coast chemical distributors specify these formats under EPA 40 CFR closure integrity mandates, consolidating supplier pools through compliance consolidation.
- HDPE:Gamma-sterile formulations displace autoclave-dependent glass in vaccine production. Heidelberg-Mannheim biopharma clusters source ISO 4796-compliant HDPE for cell culture media handling.
- PVC:Cost-sensitive chemical storage applications favor PVC where solvent compatibility permits. Indian chemical distributors adopt these formats for non-hazardous industrial fluid handling.
Glass leads volumes today; HDPE is gaining share fastest.
End User:
Cost tier segmentation separates certified pharmaceutical procurement from commodity beverage and educational purchasing. Premium pricing attaches to sterile handling protocols and regulatory documentation.
- Beverage Industry:Craft breweries and wineries specify glass for secondary fermentation and bulk aging. Oregon and Washington state brewing clusters drive regional demand concentration for 5-10 liter formats.
- Pharmaceutical Labs:Parenteral drug manufacturers mandate gamma-sterile HDPE with lot traceability under FDA 21 CFR Part 177. Boston-Cambridge biotech institutions consolidate procurement through direct manufacturer contracts, bypassing distributor tiers.
- Chemical Manufacturing:Industrial distributors absorb EPA-mandated container redesign costs through specification consolidation. US Gulf Coast petrochemical corridors prioritize HDPE transport formats with redesigned thread geometries.
- Educational Institutions:Universities and secondary schools procure PVC and basic HDPE for introductory laboratory instruction. Budget constraints favor catalog intermediaries over direct manufacturer relationships.
Pharmaceutical labs command premium pricing tiers; chemical manufacturing delivers volume scale.
Capacity:
Volume segmentation aligns with handling ergonomics and batch economics. Smaller formats suit laboratory benchwork; larger capacities serve production-scale fermentation and bulk transport.
- 5 Liters:Bench-scale cell culture and pilot fermentation workflows favor this format. Heidelberg-Mannheim contract manufacturers specify 5-liter HDPE carboys for multi-product facility flexibility.
- 10 Liters:Mid-scale brewing and chemical sampling applications concentrate demand here. German beverage producers specify 10-liter glass for standardized batch sizing.
- 15 Liters:Production fermentation and bulk media storage drive procurement. US biopharma fill-finish operations adopt 15-liter formats with closed-system aseptic connectors.
- 20 Liters:Maximum capacity serves chemical transport and industrial fermentation. EPA 40 CFR labeling requirements apply most stringently to this volume class.
10-liter formats anchor current procurement volumes; 5-liter segments climb fastest on single-use bioprocessing adoption.
Application:
Maturity segmentation distinguishes established fermentation practices from emerging single-use storage and transport modalities. Laboratory use commands certification premiums absent in commodity segments.
- Fermentation:Oxygen impermeability requirements preserve glass dominance in beer, wine, and cell culture propagation. German brewing traditions and US craft beer expansion sustain format loyalty.
- Storage:Cell culture media and chemical reagent warehousing drives HDPE specification. ISO 4796 dimensional compliance filters uncertified Asian suppliers from pharmaceutical procurement lists.
- Transport:EPA 40 CFR closure integrity mandates reshape HDPE mold specifications. Chemical distributors in Texas and Louisiana absorb compliance costs through reduced supplier counts.
- Laboratory Use:Sterile handling protocols and certification documentation justify premium pricing. Academic and commercial labs in Massachusetts and California concentrate demand for documented chain-of-custody formats.
Fermentation retains volume leadership; laboratory use delivers steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with streamlined certification pathways is compressing cost-of-compliance gaps between established and emerging manufacturing bases. Manufacturers are relocating gamma-sterile HDPE molding capacity to regions where cleanroom infrastructure costs and regulatory timelines diverge most sharply.
United States
Biopharma contract manufacturing demand concentrates in the Boston-Cambridge corridor, where direct manufacturer procurement is displacing distributor intermediaries. FDA 21 CFR Part 177 compliance validates HDPE formats for parenteral drug sterile media handling. Texas and Louisiana chemical distributors absorb EPA 40 CFR closure integrity redesign costs through supplier pool consolidation.
Germany
Heidelberg-Mannheim biopharma clusters scale ISO 4796-certified HDPE procurement for cell culture media storage workflows. EU Green Deal polymer recycling mandates under REACH are creating certified circular material pathways for non-pharma chemical transport segments. Baden-Württemberg beverage producers sustain borosilicate glass demand for oxygen-impermeable fermentation applications.
India
CDSCO sterile product regulations mandating container traceability are opening procurement windows for ISO-compliant HDPE suppliers. Maharashtra and Gujarat pharmaceutical manufacturing zones absorb compliance documentation requirements through direct technical partnerships with certified molders. Indian chemical distributors adopt PVC formats for cost-sensitive non-hazardous industrial fluid handling.
China
NMPA biopharma manufacturing standards are tightening sterile container documentation requirements for export-oriented production. Yangtze River Delta contract manufacturers face ISO 4796 dimensional tolerance filters that limit uncertified borosilicate glass supplier participation. MIIT industrial policy is channeling polymer processing investment toward gamma-stable HDPE formulation capacity.
Japan
PMDA sterile product guidelines validate single-use bioprocessing formats in vaccine production workflows. Kanto region pharmaceutical manufacturers source documented chain-of-custody containers for cell culture media handling. METI industrial standards support domestic HDPE molding capacity expansion for medical-grade applications.
Carboy Market Competitive Environment
Capacity expansion dominates the current landscape as qualified cleanroom molding footprints constrain supply responsiveness. The vendor base organizes across three tiers: integrated laboratory supply conglomerates, specialized glassware fabricators, and regional polymer converters. Strategic archetypes include certification-heavy sterile format specialists, scale-driven commodity chemical container producers, and niche fermentation equipment providers. M&A activity and geographic licensing partnerships represent the dominant competitive vectors as players seek ISO 4796 compliance breadth.
Within the integrated laboratory supply tier, Thermo Fisher Scientific and Sigma-Aldrich (Merck) occupy positions anchored by distribution network density and chemical catalog reach. Corning Inc. exemplifies the specialty glassware archetype, with its geographic naming signaling North American manufacturing heritage. These three entities represent distinct competitive positioning vectors: supply chain integration, regulatory documentation depth, and material science specialization respectively.
| Leading Market Players |
|---|
| Sterlitech |
| Marin Scientific Development |
| Thermo Fisher Scientific |
| Sigma-Aldrich (Merck) |
| Metro Ace Innovplas |
| Veritiv |
| Deluxe Scientific Surgico |
| Corning Inc. |
| Globe Scientific |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical lab procurement consolidation through direct manufacturer contracts is compressing distributor margins and forcing ISO 4796-compliant suppliers to absorb certification costs into base pricing. This demand-side pressure concentrates pricing power among gamma-sterile HDPE molders with qualified cleanroom capacity, while uncertified Asian glassware fabricators face exclusion from premium procurement lists.
Pricing Analysis
Distributor tier compression in North American laboratory supply channels is collapsing traditional markups as Boston-Cambridge biotech clusters bypass catalog intermediaries. Three-tier pricing structure across premium gamma-sterile, standard certified, and economy ungraded levels separates pharmaceutical procurement from educational and chemical transport segments. Cost compression in commodity HDPE formats is intensifying because petrochemical feedstock volatility tracks ethylene cracker margins. Educational institutions exhibit highest price sensitivity, while parenteral drug manufacturers prioritize lot traceability over unit cost.
Supply Chain Analysis
ISO 4796 dimensional validation requirements filter uncertified Chinese borosilicate glass suppliers from pharmaceutical procurement lists, creating qualification gating that protects established manufacturers. Supply concentrates in Germany, the United States, and Japan for certified laboratory glassware, while India and China expand gamma-stable HDPE molding capacity. Raw material dependencies center on ethylene-derived resins, borosilicate glass tubing, and gamma-stabilizing additive packages. Single-source vulnerability runs through qualified cleanroom injection molding footprints for sterile formats. Distribution runs through integrated laboratory supply conglomerates and direct technical partnerships with contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioprocessing adoption is expanding margin pools in sterile handling formats as certification requirements justify premium positioning over commodity chemical transport tiers. Cost-down pressure from petrochemical volatility is simultaneously compressing converter margins in non-certified segments.
For Market Incumbents: Anticipate polymer substitution acceleration in vaccine production workflows by securing gamma-sterile HDPE capacity expansion in Heidelberg-Mannheim and Boston-Cambridge corridors. Defensive consolidation through ISO 4796 certification breadth protects against emerging Indian molders with CDSCO compliance documentation. Backward integration into gamma-stabilizing additive formulation reduces feedstock cost exposure. For New Entrants and Emerging Players: E-commerce platform direct procurement channels offer white-space entry for catalog-disintermediated educational and mid-tier chemical segments. Target India's Maharashtra and Gujarat pharmaceutical zones where CDSCO traceability mandates are opening procurement windows for ISO-compliant HDPE suppliers. Specialty fermentation equipment niches in craft brewing present penetrable share points with lower certification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with gamma-sterile HDPE molders possessing dual FDA 21 CFR Part 177 and ISO 4796 compliance documentation across the analysis window. Acquisition targets with qualified cleanroom footprints in Germany or the United States offer structural scarcity value. Watch for NMPA documentation standard tightening in China's Yangtze River Delta as inflection signal for export-oriented capacity consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 4796 Certification Investment | Dimensional validation opens pharmaceutical procurement lists previously blocked to uncertified suppliers. |
| Gamma-Sterile HDPE Capacity Expansion | Cleanroom molding footprint in Heidelberg-Mannheim corridor captures cell culture media demand concentration. |
| Direct Manufacturer Contracting | Bypassing distributor tiers captures margin compression from Boston-Cambridge procurement consolidation. |
| Backward Integration into Additives | In-house gamma-stabilizing formulation reduces ethylene cracker margin volatility exposure. |
| REACH-Compliant Recycling Pathways | EU Green Deal circular material streams create non-pharma chemical transport differentiation. |
Study Parameters
Bottom-up pharmaceutical and chemical end-use modeling reconciled against top-down HDPE and borosilicate glass supply tracking forms the analytical core. Primary interviews with bioprocess engineers, laboratory procurement managers, regulatory affairs specialists at FDA and EMA, and chemical distribution channel heads combined with secondary validation from FDA 21 CFR filings, EPA 40 CFR regulatory updates, ISO certification databases, and customs trade records. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production capacity disclosures.
Historical trendline analysis of sterile container procurement volumes and material substitution rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include material format, capacity tier, end-use industry, certification grade, and regional regulatory cluster. CAGRs derive from weighted average growth of component segments calibrated against macro pharmaceutical production indices and chemical transport volume trends. Forecast inputs incorporate single-use bioprocessing adoption curves and gamma-sterilization technology diffusion patterns.
The model assumes a particular technology adoption path for co-extruded HDPE barrier structures; alternative pathways for glass retention in long-duration fermentation would alter the outlook. Forecasts reflect assumptions about regulatory timeline stability and cleanroom capacity expansion rates. A model refresh is warranted upon material change in FDA polymer contact standards or EPA chemical container redesign mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Lever Lid Cans Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Thin Wall Containers Market
Containers
Asia and Africa Food Cans Market
Containers
Lab Storage Container Market
Containers
Hinged Lid Compostable Container Market
Containers
Single Wall Jars Market
Containers
Container Coating Market
Containers
Algeria Container Glass Market
Containers
Pails Market
Containers
Americas Container Technology Market
Containers
Corrugated Open-Head Drums Market
Containers
North America Plastic Bottles and Containers Market
Containers
EPS Shippers Market
Containers
Half Height Containers Market
Containers
Roll Containers Market