
 Die Cut Display Container Market | 2026-2036
Die Cut Display Container Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cut Display Container Market Outlook
Retail merchandising channels is narrowing as e-commerce fulfillment centers demand display-ready packaging that ships directly to store floors. Smurfit Kappa Group leverages its European corrugated network to control shelf-ready container supply for major grocery banners. DS Smith anchors its position through circular design services that reduce material intensity per display unit. Mondi Group competes with integrated kraft paper and containerboard operations spanning multiple continents.
Die cut display containers are precision-cut corrugated or solid board structures formed to specific product dimensions, typically featuring tuck flaps, locking tabs, and print-ready surfaces for high-visibility retail placement. They serve primarily as self-supporting merchandising vehicles that eliminate separate shelving requirements in high-traffic retail zones. Floor displays dominate volume due to their placement at aisle termini and checkout queues, while eco-friendly materials represent the fastest-expanding material category as brand owners face Scope 3 emissions disclosure pressure. Custom displays command premium positioning where product dimensions or branding requirements deviate from standard retail modular footprints.
FDA food-contact substance regulations govern direct-content applications in the United States, while REACH and the EU Packaging and Packaging Waste Regulation dictate material composition and extended producer responsibility across European markets. These frameworks elevate compliance costs for multi-market suppliers but simultaneously advantage pre-certified manufacturers with established testing protocols. Stakeholders must track evolving state-level recycled-content mandates and retailer-specific packaging scorecards that increasingly determine vendor qualification timelines.
Market Dynamics
Retail chains are consolidating shelf-ready packaging specifications into unified procurement programs, compressing supplier margins while elevating compliance requirements for die cut display containers across European grocery networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating material recovery investments. Brand owners now specify certified recyclable substrates to meet disclosure thresholds.
- Food and beverage retail expansion:Discount supermarket banners in Germany are deploying point-of-purchase displays at checkout zones. This format eliminates separate shelving infrastructure.
- Corrugated substrate innovation:Lightweight flute profiles reduce shipping cube without sacrificing stack strength. Logistics operators are specifying these grades for direct-to-floor fulfillment.
Market Restraints
- Old corrugated containerboard price volatility:Pulp input costs swing with energy and freight indices. Converter margins compress when resin-linked linerboard spikes.
- Supplier concentration in Nordic kraft pulp:Three integrated producers control bleached kraft supply for premium display grades. Buyers face allocation risk during maintenance turnarounds.
- Substitution by reusable plastic crates:Beverage distributors in closed-loop logistics are trialing returnable totes. These displace single-use corrugated floor displays in high-rotation SKUs.
Strategic Opportunities
- Poland and Czech Republic retail modernization:Western European grocery formats are penetrating Central European markets. Local converters lack scale to serve pan-regional banner specifications.
- Pharmaceutical counter displays:OTC brands require tamper-evident, child-resistant die cut structures. This application commands premium pricing versus food-grade equivalents.
- Digital print integration:Single-pass inkjet enables versioned graphics at production speeds. Short-run seasonal campaigns become economically viable for mid-tier brands.
Industry Challenges
- Structural design engineering talent scarcity:CAD specialists who optimize load distribution in variable flute combinations command premium compensation. Smaller converters struggle to retain this capability.
- Food-contact certification timeline compression:FDA and EFSA migration testing protocols require 12-16 week validation cycles. New substrate introductions miss seasonal windows.
- Legacy ERP integration with customer EDI platforms:Retailer scorecard systems demand real-time carbon footprint data. Manual data reconciliation creates invoice disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cut Display Container Market |
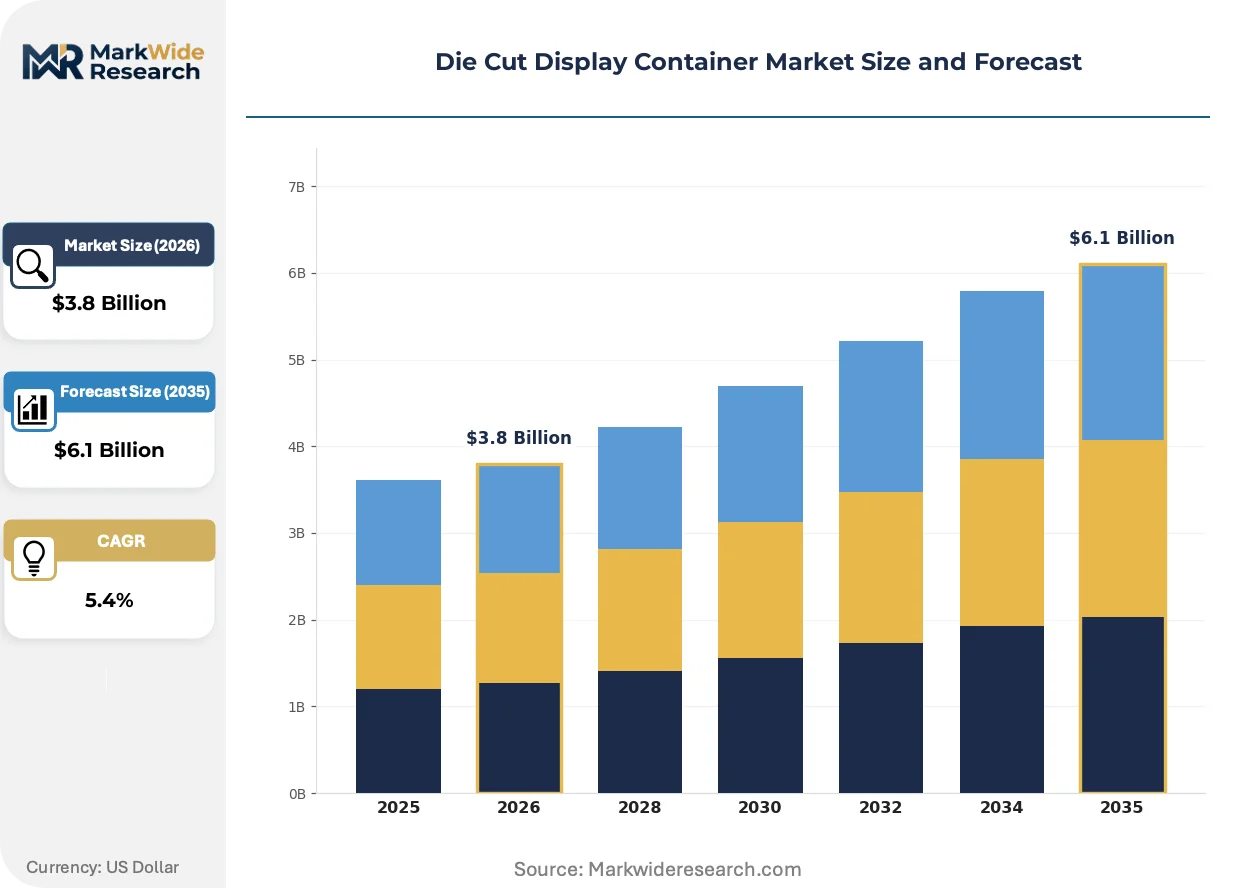
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Displays, Counter Displays, Pallet Displays, Custom Displays Material: Cardboard, Plastic, Metal, Eco-Friendly Materials Application: Retail Stores, Trade Shows, Exhibitions, Events End User: Food & Beverage, Cosmetics, Electronics, Personal Care |
| Companies Covered | Smurfit Kappa Group, DS Smith, International Paper Company, WestRock Company, Mondi Group, RFC Container Company, Visy Glama Pty Ltd, Packaging Corporation of America, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cut Display Container Market Strategic Shifts
Active coating technologies and digital finishing methods are compressing production lead times while enabling mass customization previously restricted to premium display tiers.
Water-based barrier coatings are collapsing the performance gap between polyethylene-laminated and recyclable single-material structures. German discount retailers are specifying these grades for fresh produce displays. The technology eliminates separate film lamination steps, reducing unit costs by a full process stage.
REACH substance restriction updates are tightening formaldehyde and heavy metal thresholds in printed boardstock. Converters serving EU markets are migrating to mineral oil-free ink systems. Food-contact display applications face the steepest compliance cost escalation, pushing smaller decorators toward specialist toll coating partnerships.
Direct-to-store fulfillment from e-commerce distribution centers is displacing traditional wholesaler staging. Retailers are specifying retail-ready packaging that arrives shelf-merchandisable without unpacking labor. This pattern concentrates in UK and German grocery networks where automated sortation systems handle mixed-SKU pallets.
Die Cut Display Container Market Segmentation
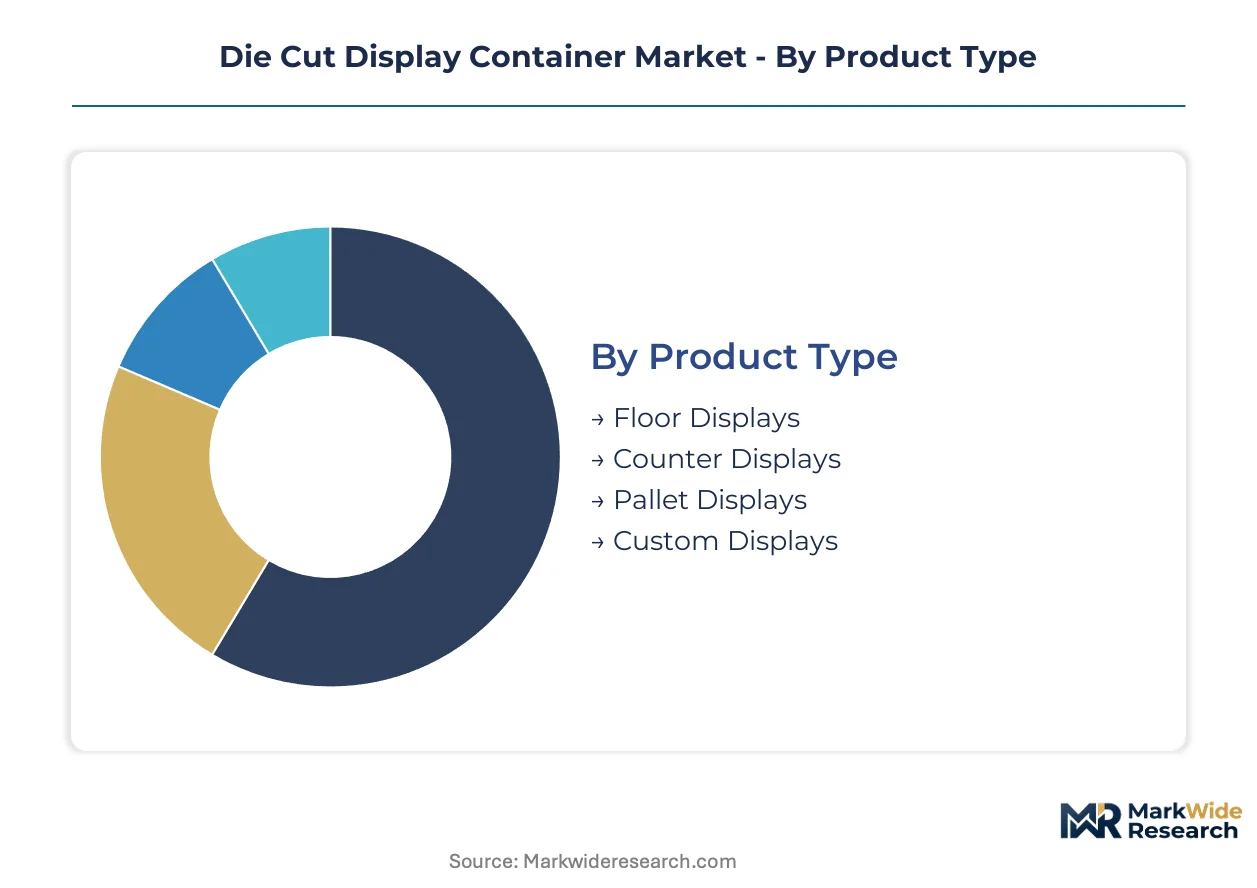
Die cut display containers fragment across four intersecting dimensions that determine procurement specifications, compliance pathways, and margin structures. Product type governs structural engineering requirements and logistics handling protocols. Material selection triggers regulatory jurisdiction and recycling infrastructure dependencies. Application context dictates durability standards and graphic finishing investments. End-user verticals impose sector-specific certification regimes that filter supplier qualification.
Product Type:
Mature formats dominate volume throughput while emerging configurations capture premium positioning through customization depth.
- Floor Displays:Self-supporting corrugated structures engineered for aisle termini and checkout queue placement. German discount retailers specify these for direct-to-floor fulfillment from automated distribution centers. REACH-compliant substrates are now mandatory for EU grocery deployments.
- Counter Displays:Compact die-cut units designed for point-of-sale surfaces with reduced vertical clearance. Cosmetics brands in French pharmacy chains specify these for high-margin impulse categories. Child-resistant locking mechanisms command 15-20% price premiums over standard tuck-flap constructions.
- Pallet Displays:Full-pallet footprint structures integrating base pads, containment sleeves, and top caps for warehouse club formats.
- Custom Displays:Non-modular specifications deviating from standard retail planogram dimensions.
Floor displays retain volume leadership; custom displays hold the steepest expansion curve.
Material:
Cost tiers separate commodity substrates from certified sustainable grades with traceability documentation requirements.
- Eco-Friendly Materials:FSC-certified kraft linerboard and grass-fiber alternatives with carbon footprint disclosures. Brand owners facing EU CSRD Scope 3 mandates specify these for retail-ready packaging programs. Water-based barrier coatings now match polyethylene-laminated performance for fresh produce applications.
- Cardboard:Recycled-content corrugated boardstock ranging from single-wall B-flute to triple-wall EB-flute profiles. German supermarket banners standardize on lightweight C-flute grades to reduce shipping cube without sacrificing 50kg stack strength.
- Plastic:PET, PP, and expanded polystyrene structures for moisture-resistant or reusable applications.
- Metal:Tinplate and aluminum frames for permanent fixture integration in flagship retail environments.
Cardboard retains volume leadership; eco-friendly materials are expanding most quickly.
Application:
Customer type stratification separates recurring programmatic demand from project-based procurement with volatile specification cycles.
- Retail Stores:Permanent and promotional installations within grocery, mass merchandise, and specialty retail footprints. UK supermarket networks now mandate retail-ready packaging that arrives shelf-merchandisable without unpacking labor. Automated sortation systems at distribution centers enforce pallet configuration standards.
- Trade Shows:Temporary structures for industry exhibition environments with 3-5 day duty cycles. Modular reconfigurability commands design premiums over single-use formats.
- Exhibitions:Museum and gallery display applications with conservation-grade material requirements.
- Events:Pop-up and experiential marketing deployments with compressed lead times and disposal logistics.
Retail stores retain volume leadership; events hold the steepest expansion curve.
End User:
Margin profiles diverge sharply across verticals based on certification burden, volume scale, and switching costs.
- Food & Beverage:Direct-contact display applications governed by FDA food-contact substance regulations and EFSA migration testing protocols. German discount retailers deploy these at checkout zones for high-rotation SKUs. 12-16 week validation cycles for new substrate introductions compress seasonal window opportunities.
- Cosmetics:Premium fragrance and skincare brands specifying tactile finishing and precise color matching. French and Italian luxury houses drive demand for soft-touch coatings and foil stamping integration.
- Electronics:Anti-static and shock-absorbing specifications for device merchandising with theft-deterrent features.
- Personal Care:Mass-market shampoo, soap, and oral care displays with high print coverage and moisture resistance.
Food & beverage retains volume leadership; cosmetics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates from ECHA are restructuring procurement specifications across European retail networks. German discount supermarket chains are deploying floor displays at checkout zones to eliminate separate shelving infrastructure. This regulatory and operational convergence is accelerating substrate certification investments in dense grocery markets.
Germany
Aldi and Lidl banners specify lightweight C-flute floor displays for direct-to-floor fulfillment from automated distribution centers. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility for material recovery. Bavarian corrugated converters are expanding water-based barrier coating capacity to serve fresh produce display programs.
United States
FDA food-contact substance regulations govern direct-content applications for snack and beverage displays in warehouse club formats. Retail-ready packaging specifications from Kroger and Walmart compress supplier margins while elevating compliance requirements. Midwest containerboard mills near Chicago anchor supply chains for mass merchandise floor display programs.
France
Cosmetics brands in pharmacy chains specify counter displays with tactile finishing for high-margin impulse categories. ANSM and CNIL oversight extends to packaging material traceability in premium fragrance applications. The Île-de-France region concentrates specialist decorators serving Paris-based luxury houses.
United Kingdom
Tesco and Sainsbury's mandate retail-ready packaging that arrives shelf-merchandisable without unpacking labor. Automated sortation systems at distribution centers enforce pallet configuration standards for mixed-SKU deliveries. Midlands-based converters are integrating digital print lines to serve short-run seasonal campaigns.
Poland
Western European grocery formats are penetrating Central European markets through Biedronka and Żabka expansion. Local converters lack scale to serve pan-regional banner specifications for unified procurement programs. The Warsaw-Łódź corridor is attracting corrugated investment from EU-15 producers seeking cost-advantaged supply positions.
Die Cut Display Container Market Competitive Environment
Integrated multinational converters and regional specialists split the market into distinct capability tiers. Three producers control bleached kraft supply for premium display grades, creating allocation risk during maintenance turnarounds. Strategic archetypes include European corrugated network operators, North American containerboard-integrated players, and Australasian specialty fabricators. Competitive moves concentrate on circular design service expansion and digital print integration for versioned graphics at production speeds.
Among European-based integrated producers, Smurfit Kappa Group and DS Smith exemplify network-scale operators with established testing protocols for multi-market compliance. Mondi Group occupies a position spanning integrated kraft paper and containerboard operations across multiple continents. These three companies represent the tier pre-positioned for EU Packaging and Packaging Waste Regulation acceleration and CSRD Scope 3 disclosure pressure from brand owners.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| International Paper Company |
| WestRock Company |
| Mondi Group |
| RFC Container Company |
| Visy Glama Pty Ltd |
| Packaging Corporation of America |
| Georgia-Pacific |
| Others |
Value Chain & Pricing Dynamics
The Bavarian corrugated cluster around Nuremberg anchors European containerboard capacity for premium display grades, with converter consolidation there feeding pricing leverage downstream toward retail procurement programs. This geographic concentration interacts with EU Packaging and Packaging Waste Regulation compliance costs to stratify margins across certified and non-certified supplier tiers.
Pricing Analysis
Price spreads between Nordic kraft linerboard and recycled-content corrugated grades widen during pulp mill maintenance cycles. Three-tier pricing structure across FSC-certified premium, REACH-compliant standard, and economy recycled-content levels dominates procurement contracts. Cost compression in economy tiers is intensifying because German discount retailers are consolidating specifications into unified programs. Brand owners with CSRD Scope 3 mandates show least price sensitivity; mid-tier converters serving spot markets exhibit highest.
Supply Chain Analysis
Export-control scrutiny on advanced coating chemistries under REACH substance restriction updates limits cross-border flows of mineral oil-free ink systems. Supply concentrates in Germany, Poland, and the Czech Republic for finished display containers, while bleached kraft pulp feeds from Nordic integrated producers. Raw material dependencies span OCC recycled fiber, water-based barrier coatings, and digital print substrates. Single-source vulnerability runs through the three Nordic pulp producers controlling premium grades. Distribution runs through automated fulfillment centers serving pan-regional grocery banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
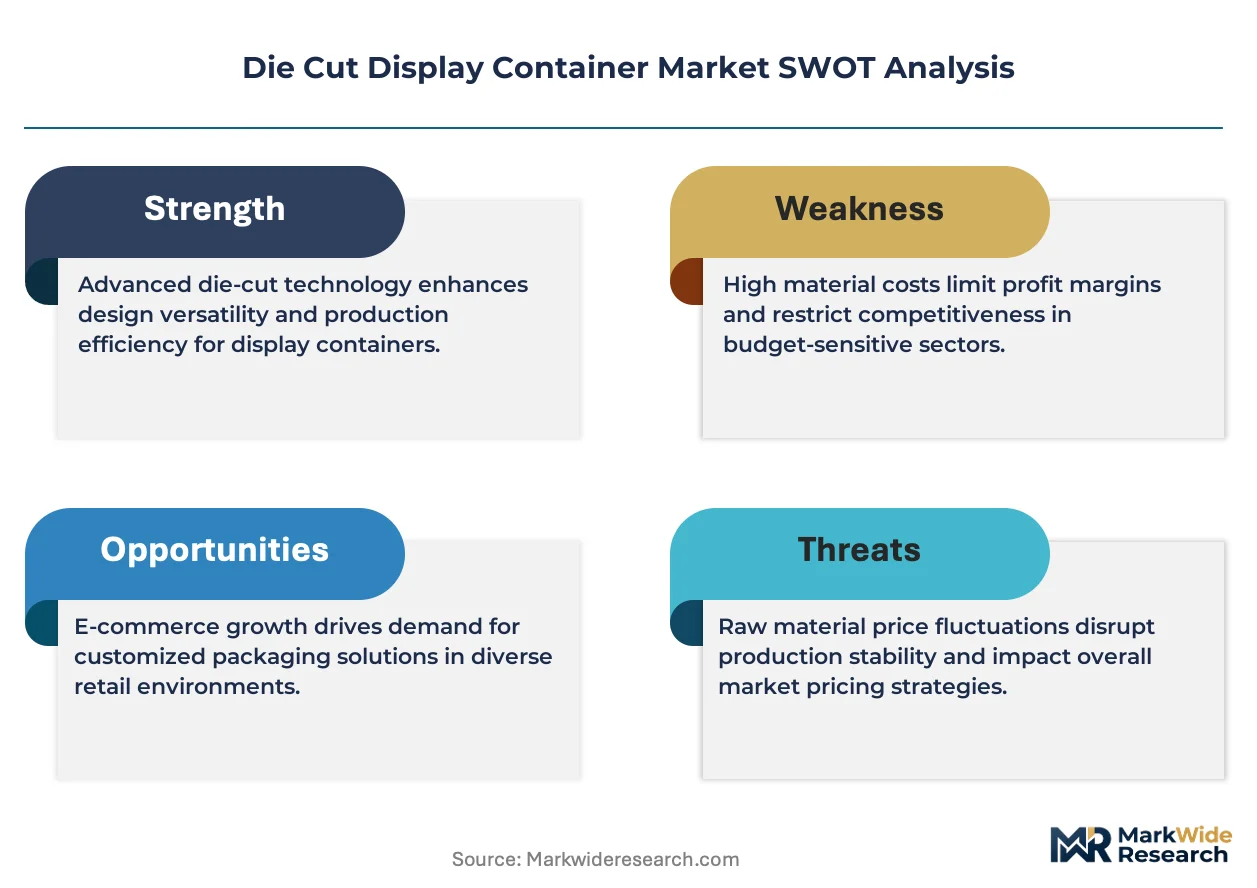
The die cut display container market is accelerating through digital print integration and EU circular economy mandates, with water-based barrier coatings collapsing cost structures previously protected by polyethylene lamination.
For Market Incumbents: Entrench circular design service capabilities to capture CSRD-driven specification upgrades from brand owners facing Scope 3 disclosure pressure. Defend margin position by backward integration into water-based coating capacity in the Nuremberg corridor, neutralizing toll-coating dependency. Counter substitution risk from reusable plastic crates by embedding RFID traceability into corrugated structures for closed-loop retail logistics. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical counter displays where tamper-evident engineering commands premium pricing and FDA validation timelines create incumbent stickiness. Target Polish retail modernization where Western grocery format penetration outpaces local converter scale. Pursue digital print-enabled short-run seasonal campaigns as the go-to-market angle, leveraging single-pass inkjet to serve mid-tier brands excluded from volume-program pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated coating and print finishing capabilities over pure-play structural engineers. Five-to-ten year viability hinges on EU regulatory acceleration toward mandatory recycled-content thresholds. Acquisition target archetype: regional specialists with established EFSA migration testing protocols and underutilized digital print lines. The signal to watch is retailer packaging scorecard adoption velocity, which determines vendor qualification timelines and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Capacity Expansion | Eliminates polyethylene lamination steps, aligning with EU Packaging and Packaging Waste Regulation material recovery targets. |
| Digital Print Line Integration | Enables versioned graphics at production speeds for short-run seasonal campaigns previously uneconomical for mid-tier brands. |
| Circular Design Service Development | Captures CSRD Scope 3 disclosure-driven demand from brand owners requiring carbon footprint documentation per display unit. |
| Central European Manufacturing Footprint | Positions supply adjacent to Polish and Czech retail modernization where local converters lack pan-regional banner scale. |
| Food-Contact Certification Investment | Compresses FDA and EFSA validation cycles to capture seasonal windows and displace smaller decorators facing timeline pressure. |
Study Parameters
Desk research of trade association filings, customs containerboard import records, and EU regulatory impact assessments preceded structured interviews with corrugated plant managers, grocery category buyers, packaging procurement leads, and circular design consultants. Primary fieldwork with Bavarian and Polish converters was cross-referenced against secondary validation from SEC filings of integrated producers and ECHA substance restriction updates. Bottom-up volume builds by product type and material grade were triangulated against top-down market sizing from containerboard consumption trends.
Assumptions held fixed across the analysis window include EU Packaging and Packaging Waste Regulation enforcement timelines, water-based coating performance parity with polyethylene lamination, and German discount retailer format penetration rates in Central Europe. Variables stress-tested encompass OCC price volatility, Nordic kraft pulp allocation during maintenance turnarounds, and substitution elasticity for reusable plastic crates in beverage logistics. CAGRs were derived from segment-level volume projections weighted by end-user vertical growth differentials, with pharmaceutical and cosmetics applications modeled separately from food and beverage mass-market throughput.
Stress conditions across pulp input cost bands, regulatory compliance cost escalation, and digital print adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in EU recycled-content mandate thresholds or breakthrough reusable packaging economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Tottle Containers Market
Containers
Food Grade Stainless Steel Container Market
Containers
Packer Bottle Market
Containers
Takeout Containers Market
Containers
APAC Container Technology Market
Containers
Container Fixed Fittings Market
Containers
EPS Shippers Market
Containers
Cubitainer Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Global Flexitanks Market
Containers
Trays Market
Containers
Light Resistant Containers Market
Containers
Tin Containers Market
Containers
Reconditioned IBC Market
Containers
Hinged Lid Tins Market