
 Tottle Containers Market | 2026-2036
Tottle Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Tottle Containers Market Analytics
Multi-source resin procurement is consolidating across the tottle supply base as converters seek price stability and recycled-content assurance. Greiner Packaging GmbH leverages its European extrusion network to secure rPET supply chains for premium beauty clients. Plastipak Holdings, Inc. anchors North American volume through dedicated pharmaceutical-grade blow-molding lines. ALPLA competes on tool-sharing platforms that reduce minimum order thresholds for mid-tier cosmetics brands.
Tottle containers are inverted, flexible-wall dispensers—typically extrusion-blow-molded HDPE or injection-stretch-blow PET—with calibrated neck finishes that mate with pump, flip-top, or disc-top closures; they store and dispense viscous liquids without air ingress, serving cosmetics, pharmaceutical topicals, and condiment packaging. Plastic dominates current volume owing to drop-test resilience and decoration compatibility, though biodegradable sub-segments are expanding fastest as EU single-use directives harden. Pump dispenser closures command the strongest margin pools due to precision molding tolerances and silicone valve sourcing complexity.
FDA compliance for pharmaceutical tottles governs US market access, while ECHA REACH restrictions on phthalate plasticizers and the EU Green Deal packaging recyclability mandates reshape European material specifications. China's GB standards for food-contact plastics and SAMR labeling rules add compliance layers for export-oriented converters. Stakeholders must monitor how fragmented national Extended Producer Responsibility schemes alter total cost of ownership before committing to capacity expansion or regional hub strategies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for tottle converters, forcing rapid migration from multi-material laminates to mono-material and post-consumer recycled structures before traceability mandates take full effect.
Growth Catalysts
- Refillable format adoption:South Korean and German cosmetics brands are expanding tottle procurement for serums and lotions as refillable packaging gains consumer traction and aligns with circular economy frameworks.
- REACH compliance migration:ECHA restrictions on phthalate plasticizers are accelerating HDPE and rPET substitution in European pharmaceutical tottles, creating specification windows for compliant converters.
- Guangdong manufacturing cluster:Contract manufacturers in China's Guangdong province are scaling blow-molding capacity to serve both domestic beauty brands and Southeast Asian export orders, concentrating supply-side efficiency.
Market Restraints
- rPET supply concentration:Post-consumer recycled resin availability remains tethered to European and North American collection infrastructure, creating input cost volatility for premium beauty clients demanding certified recycled content.
- Silicone valve sourcing:Pump dispenser closures face precision molding tolerance requirements and concentrated silicone valve suppliers, compressing margin pools for mid-tier converters lacking scale.
- Biodegradable performance gap:Drop-test resilience and decoration compatibility in biodegradable alternatives lag HDPE and PET, limiting substitution in pharmaceutical and condiment applications.
Strategic Opportunities
- Tool-sharing platforms:Mid-tier cosmetics brands are accessing reduced minimum order thresholds through shared mold infrastructure, opening volume segments previously captured by larger converters.
- Southeast Asian export channels:Guangdong-based manufacturers are capturing incremental demand from Southeast Asian markets where domestic blow-molding capacity remains underdeveloped for calibrated neck finishes.
- EU Green Deal tailwinds:Packaging recyclability mandates are creating specification premiums for mono-material tottles with verified post-consumer recycled content, rewarding early design migration.
Industry Challenges
- Fragmented EPR scheme navigation:National Extended Producer Responsibility frameworks vary across EU member states, complicating total cost of ownership calculations for converters evaluating regional hub strategies.
- Multi-jurisdiction certification timelines:Simultaneous FDA compliance for US pharmaceutical access, ECHA REACH alignment for Europe, and China's GB standards for food-contact plastics extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tottle Containers Market |
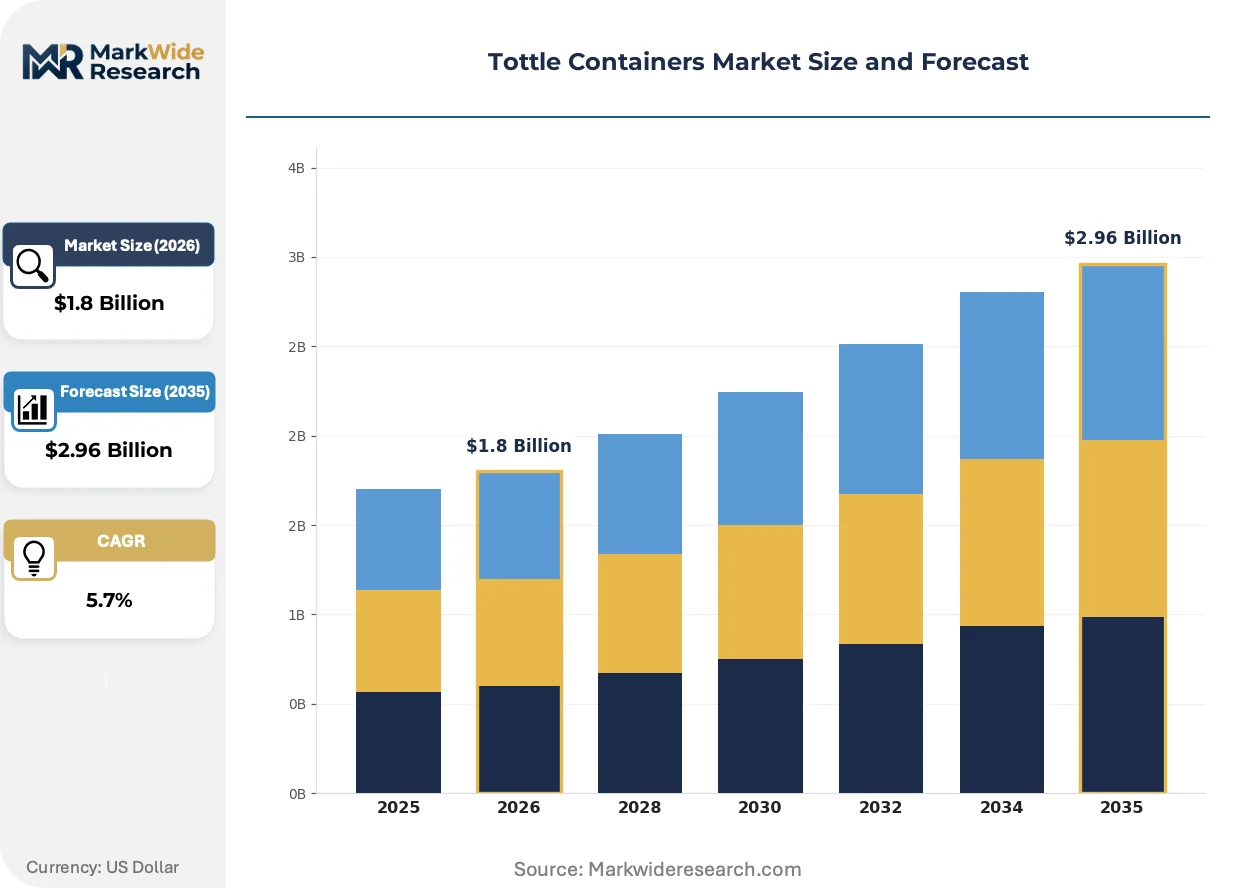
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Biodegradable Closure Type: Screw Cap, Flip Top, Spout, Pump Dispenser Application: Cosmetics, Pharmaceuticals, Food & Beverage, Household Products Volume: Small, Medium, Large, Extra Large |
| Companies Covered | Greiner Packaging GmbH, Plastipak Holdings, Inc., ALPLA, Visy, Greif, Amcor, Graham Packaging, Sæplast, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tottle Containers Market Evolving Landscape
Material science and regulatory architecture are converging to reshape tottle design specifications, with mono-material construction and recycled-content verification becoming baseline requirements rather than premium differentiators.
Mono-material HDPE and rPET tottles are absorbing specification share from multi-layer barrier structures as converters eliminate adhesive lamination layers to satisfy EU recyclability mandates. Premium beauty brands in Germany and South Korea are specifying these structures for serum and lotion packaging to preempt compliance deadlines. The shift is compressing demand for conventional multi-material converters lacking extrusion-blow-molding flexibility.
REACH restrictions on phthalate plasticizers are forcing material substitutions in European pharmaceutical tottles, with converters reformulating HDPE compounds and validating alternative plasticizers for skin-contact applications. ECHA's evolving substance restrictions are extending compliance timelines for existing product lines. Pharmaceutical-grade blow-molding lines in North America and Europe are prioritizing non-phthalate certification to maintain cross-border market access.
Refillable tottle systems are altering procurement patterns as cosmetics brands shift from single-use disposal toward durable base units with replaceable inner cartridges. South Korean beauty brands are leading this specification change, demanding calibrated neck finishes compatible with both permanent pumps and disposable refills. The model concentrates volume with converters capable of precision tolerance control across multiple closure mating cycles.
Tottle Containers Market Segmentation
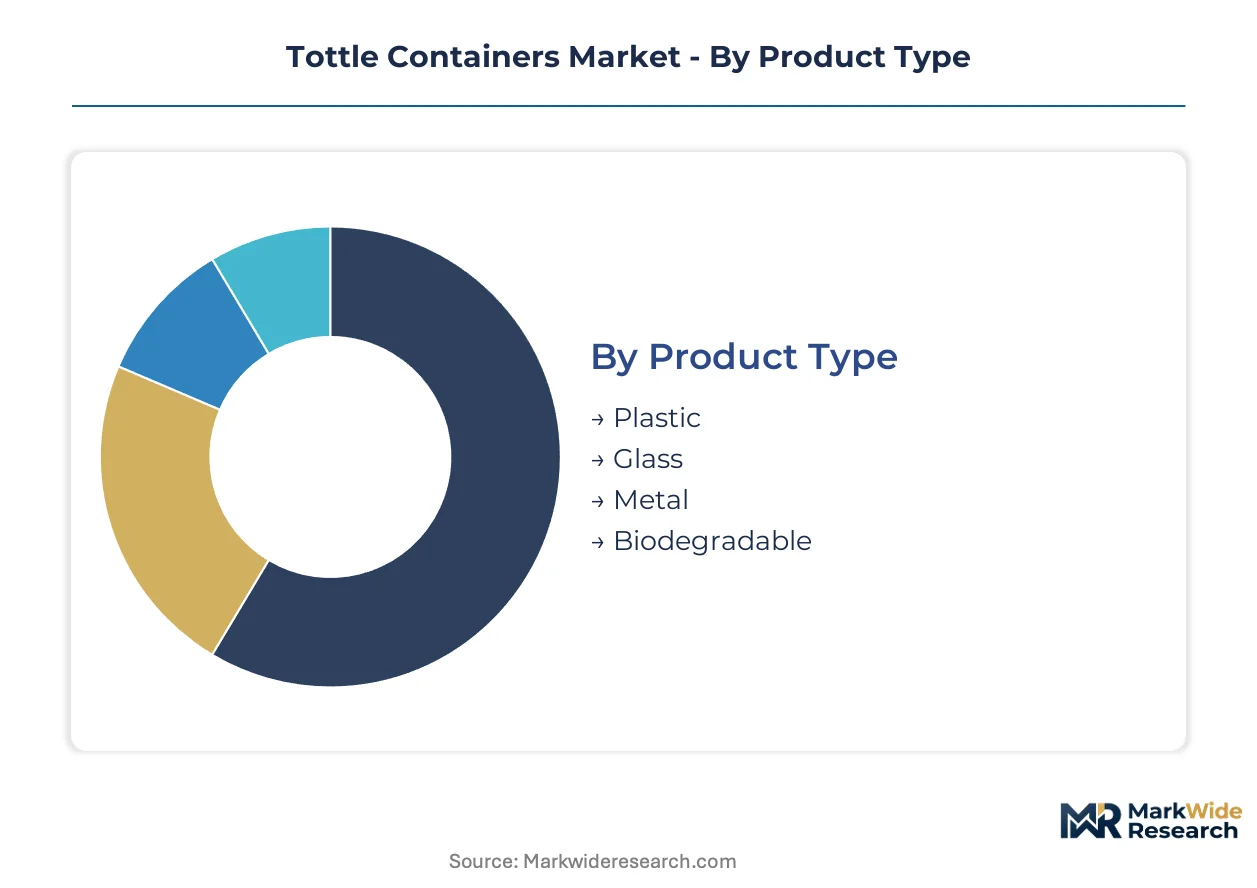
Tottle container segmentation reveals distinct specification clusters where material choice and closure precision determine end-use eligibility. Converters align capacity investments against these divides to capture margin pools in pharmaceutical and premium beauty applications.
Product Type:
Standalone materials dominate high-volume cosmetics and condiment dispensing, while embedded barrier systems serve pharmaceutical applications demanding oxygen exclusion.
- Plastic:Extrusion-blow-molded HDPE and injection-stretch-blow PET deliver drop-test resilience and full-surface decoration compatibility. Guangdong contract manufacturers concentrate blow-molding capacity here for Southeast Asian export orders.
- Biodegradable:PLA and PHA compounds address EU single-use directives but lag in decoration adhesion and impact resistance. South Korean beauty brands pilot these for serum refills where mechanical stress is minimal.
- Glass:Borosilicate and soda-lime variants serve premium fragrance and pharmaceutical applications requiring inert contact surfaces.
- Metal:Aluminum squeeze tubes and tinplate containers occupy niche condiment and industrial lubricant segments.
Volume placements concentrate in Plastic; the faster expansion belongs to Biodegradable.
Closure Type:
Cost tier separation runs through closure complexity, with precision-molded pump systems commanding specification premiums over commodity screw formats.
- Pump Dispenser:Silicone valve assemblies and calibrated neck finishes mate with viscous serum and lotion formulations. ECHA REACH compliance on phthalate plasticizers is forcing compound reformulation in European pharmaceutical specifications.
- Flip Top:Living-hinge polypropylene closures serve food-contact condiments and household cleaners where one-handed operation drives consumer preference.
- Screw Cap:Standard 24/410 and 28/410 thread profiles dominate cost-sensitive shampoo and body wash applications.
- Spout:Directional flow nozzles target precision dispensing in automotive fluids and craft adhesives.
Margin capture clusters in Pump Dispenser; the steepest expansion trajectory sits with Flip Top as refillable formats proliferate.
Application:
Customer type stratification separates batch-certified pharmaceutical converters from cosmetics specialists and food-contact generalists.
- Cosmetics:Serum, lotion, and foundation packaging demands calibrated neck finishes compatible with both permanent pumps and disposable refill cartridges. German and South Korean brands are consolidating procurement with converters offering tool-sharing platforms.
- Pharmaceuticals:FDA compliance for US market access and EMA quality standards govern topical cream and ointment packaging. North American blow-molding lines dedicate pharmaceutical-grade capacity here.
- Food & Beverage:Ketchup, mustard, and sauce dispensing requires migration from multi-material laminates to mono-material structures under EU Packaging and Packaging Waste Regulation traceability mandates.
- Household Products:Surface cleaners and laundry pretreatments prioritize chemical resistance in HDPE formulations.
Specification complexity peaks in Pharmaceuticals; the fastest volume gain belongs to Cosmetics as refillable systems restructure procurement patterns.
Volume:
Supply concentration maps to volume tier, with small-format precision molding clustered in European and North American specialty converters.
- Small:15-50ml capacities serve travel-size cosmetics and pharmaceutical sample dispensing. Precision tolerance requirements concentrate production with converters maintaining dedicated pharmaceutical-grade lines.
- Medium:100-250ml formats dominate standard serum and lotion retail SKUs.
- Large:500ml+ refill cartridges and professional salon sizes.
- Extra Large:Industrial and food-service bulk dispensing above 1 liter.
Capacity utilization runs highest in Medium; the specification premium concentrates in Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer recycled resin availability clusters in Germany and the United States, anchoring supply security for premium beauty converters seeking certified circular content. Guangdong province concentrates blow-molding capacity for Southeast Asian export channels.
United States
FDA compliance requirements for pharmaceutical tottles govern market access for topical cream packaging. Plastipak Holdings anchors North American volume through dedicated pharmaceutical-grade blow-molding lines in the Midwest. The EPA's evolving framework on plastic waste traceability is pressuring converters toward mono-material designs.
Germany
ECHA REACH restrictions on phthalate plasticizers are accelerating HDPE compound reformulation for skin-contact applications. Greiner Packaging leverages its European extrusion network to secure rPET supply chains for premium beauty clients in Baden-Württemberg. The EU Green Deal packaging recyclability mandates are compressing design cycles before traceability requirements take full effect.
China
GB standards for food-contact plastics and SAMR labeling rules add compliance layers for export-oriented converters in Guangdong province. Contract manufacturers in the Pearl River Delta are scaling blow-molding capacity to serve both domestic beauty brands and Southeast Asian export orders. MEE enforcement of dual carbon goals is tightening material traceability requirements for converters.
South Korea
MFDS pharmaceutical standards and K-beauty brand procurement specifications are driving demand for calibrated neck finishes compatible with refillable systems. Seoul-based cosmetics brands are consolidating tottle procurement for serums and lotions as refillable formats gain consumer traction. The national circular economy framework is rewarding mono-material designs with verified recycled content.
India
BIS certification requirements for food-contact plastics are structuring entry barriers for imported tottle specifications. Maharashtra-based contract manufacturers are piloting medium-volume blow-molding for domestic cosmetics brands seeking alternatives to Chinese supply. The PLI scheme for packaging materials is incentivizing localized extrusion capacity.
Tottle Containers Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to install pharmaceutical-grade blow-molding lines and secure rPET supply commitments ahead of EU traceability deadlines. The vendor base organizes around three strategic archetypes: European extrusion specialists with integrated recycling networks, North American pharmaceutical-grade converters with FDA-certified capacity, and Asian contract manufacturers capturing Southeast Asian export volume. M&A activity and tool-sharing platform development represent the dominant competitive moves, with mid-tier brands accessing reduced minimum order thresholds through shared mold infrastructure.
Among European extrusion specialists, Greiner Packaging GmbH and ALPLA exemplify the integrated recycling network archetype, while Plastipak Holdings, Inc. represents the North American pharmaceutical-grade tier. These three companies occupy distinct positioning vectors—Greiner Packaging leverages continental rPET supply security, ALPLA competes on tool-sharing platforms that reduce entry barriers for mid-tier cosmetics brands, and Plastipak anchors scale through dedicated pharmaceutical-grade lines. Each sits within a defensible specialization rather than competing directly across all specification tiers.
| Leading Market Players |
|---|
| Greiner Packaging GmbH |
| Plastipak Holdings, Inc. |
| ALPLA |
| Visy |
| Greif |
| Amcor |
| Graham Packaging |
| Sæplast |
| Berry Global Inc. |
| Others |
Value Network & Pricing Analysis
Premium beauty brands in Germany and South Korea concentrate procurement volumes with converters offering certified recycled content, anchoring a contract-based pricing model where long-term offtake agreements secure rPET supply against spot market volatility. This buyer concentration shifts pricing power toward converters with integrated recycling networks and pharmaceutical-grade certification tiers.
Pricing Analysis
Tool-sharing and mold amortization are unbundled from base unit pricing, with mid-tier cosmetics brands paying separate platform fees to access reduced minimum order thresholds. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pharmaceutical lines from general cosmetics and commodity condiment applications. Price differentiation rests on rPET content verification and ECHA REACH compliance tier, with silicone valve assembly precision commanding additional premiums. Cost compression in standard-grade HDPE tottles is intensifying because Guangdong contract manufacturers are scaling blow-molding capacity for Southeast Asian export orders. Pharmaceutical and premium beauty segments show lowest price sensitivity due to regulatory compliance requirements; commodity condiment applications exhibit highest sensitivity to resin cost fluctuations.
Supply Chain Analysis
Dual-sourcing mandates from EU-based cosmetics brands require qualified suppliers in both Germany and China to mitigate tariff exposure and logistics disruption. Geographic supply concentration centers on Germany for rPET extrusion and pharmaceutical-grade finishing, China for blow-molding capacity and Southeast Asian export logistics, and the United States for FDA-certified pharmaceutical lines. Raw material dependencies draw from post-consumer PET flake collection infrastructure, medical-grade HDPE resin, and precision silicone valve components. Single-source vulnerability runs through concentrated silicone valve suppliers for pump dispenser closures. Distribution runs through regional hub strategies with converters maintaining inventory positions near Guangdong, Baden-Württemberg, and Midwest pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around converters with integrated rPET supply chains and multi-jurisdiction certification capabilities, as EU Packaging and Packaging Waste Regulation traceability deadlines force sub-scale players toward exit or acquisition.
For Market Incumbents: Cement rPET supply security through backward integration into European extrusion networks or captive offtake agreements with certified recyclers. Expand pharmaceutical-grade blow-molding capacity in North America to defend against Plastipak's scale advantages in FDA-certified lines. Prioritize tool-sharing platform investments to capture mid-tier cosmetics brand volume that smaller competitors cannot serve profitably. For New Entrants and Emerging Players: EU Green Deal packaging recyclability mandates in Germany open a window for mono-material tottle specialists with verified post-consumer recycled content. Target Southeast Asian export channels where Guangdong-based manufacturers face logistics cost disadvantages for calibrated neck finish precision. Enter through private-label partnerships with domestic beauty brands in India and South Korea seeking alternatives to Chinese supply concentration. For Investors and Strategic Acquirers: The window for entry favors converters with pharmaceutical-grade certification and established rPET supply chains over greenfield capacity plays. Acquisition targets should demonstrate ECHA REACH compliance migration completion and tool-sharing platform infrastructure. Watch rPET price spreads against virgin resin as the inflection indicator for margin compression timing across premium beauty segments.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Supply Chain Integration | Backward integration into European extrusion networks secures certified recycled content for EU Green Deal compliance. |
| Pharmaceutical-Grade Capacity Expansion | Dedicated FDA-certified blow-molding lines anchor North American market access for topical cream packaging. |
| Tool-Sharing Platform Development | Shared mold infrastructure reduces minimum order thresholds and captures mid-tier cosmetics brand procurement. |
| Mono-Material Design Migration | Elimination of adhesive lamination layers satisfies EU recyclability mandates and preempts traceability deadlines. |
| Southeast Asian Distribution Hub Establishment | Regional inventory positioning near export corridors captures demand from underdeveloped domestic blow-molding capacity. |
Research Methodology
Document review covered FDA 510(k) filings, ECHA REACH substance restriction updates, EU Packaging and Packaging Waste Regulation drafts, and Chinese GB standards for food-contact plastics, complemented by interviews with blow-molding plant managers, procurement leads at German cosmetics brands, pharmaceutical packaging engineers, and Guangdong-based contract manufacturing executives. Secondary validation drew from customs trade data, SEC 10-K disclosures from listed packaging converters, and industry association reports from European Plastics Association and China Plastics Processing Industry Association. Bottom-up capacity assessments and top-down demand modeling were triangulated against primary interview findings.
Segment-level volume and value estimates were produced across material type, closure precision tier, application vertical, and geographic production cluster throughout the forecast period. CAGRs were derived from regression analysis of historical capacity utilization, resin price elasticity, and regulatory compliance cost trajectories. Key forecast inputs included rPET collection infrastructure expansion rates in Germany and the United States, and ECHA substance restriction timelines affecting phthalate plasticizer alternatives.
The model assumes a particular technology adoption path; alternative pathways for biodegradable PLA and PHA compounds achieving decoration adhesion and drop-test parity with HDPE would alter the outlook for material substitution rates. Forecasts reflect assumptions regarding EU traceability mandate enforcement timing and rPET certification standard harmonization. Deviation in silicone valve supplier concentration or Guangdong logistics cost inflation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Foldable Steel Containers Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Vacuum Formed Tray Market
Containers
Roll Containers Market
Containers
Lab Storage Container Market
Containers
Carboy Market
Containers
Foldable Large Containers Market
Containers
Child-Resistant Containers Market
Containers
Essential Oil Containers Market
Containers
Mini Spray Bottles Market
Containers
Stack and Nest Containers Market
Containers
Metal Crates Market
Containers
Foam Containers Market
Containers
Jug Shipper Market
Containers
Collapsible Crate Market
Containers
Hinged Lid Compostable Container Market