
 Corrugated Bin Boxes Market | 2026-2036
Corrugated Bin Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Bin Boxes Market Outlook
North American containerboard mills is rebalancing output toward lighter basis weights that serve automated warehouse systems. International Paper leverages its integrated pulp-to-box network across the southeastern United States to secure linerboard supply for bin box grades. WestRock anchors its position through recycled fiber expertise and national distribution infrastructure. Smurfit Kappa competes with European-designed stackable bin formats optimized for retail backroom replenishment.
Corrugated bin boxes are rigid, paper-based containers manufactured from fluted corrugated medium sandwiched between linerboard facings, typically ranging from 200 to 350 pounds per square inch in burst strength depending on stacking load requirements. These structures organize inventory in warehouses, protect goods during internal logistics, and enable efficient picking in high-velocity distribution environments. Tote boxes lead volume due to standardized footprints that interface with conveyor and automated storage systems, while storage containers command margin premiums through multi-depth designs and reinforced hand holes. Recycled paperboard dominates material demand as buyers prioritize post-consumer content thresholds, though kraft paper variants sustain share in moisture-sensitive agricultural applications.
The EPA regulates corrugated manufacturing emissions under Clean Air Act permits, while OSHA enforces ergonomic standards for manual handling of loaded bins in warehouse settings. The EU Green Deal and national extended producer responsibility schemes in France and Germany mandate recyclability labeling and recycled content minimums that reshape supplier qualification criteria. Stakeholders must monitor how California's SB 54 implementation and forthcoming revisions to the EU Packaging and Packaging Waste Regulation will redefine acceptable material certifications and alter sourcing decisions across multi-national supply chains.
Market Dynamics
The corrugated bin boxes market is undergoing structural reconfiguration as automated warehouse systems impose dimensional tolerances and load-bearing specifications that legacy box designs cannot satisfy. This technological inflection is compressing supplier margins while rewarding integrated manufacturers with captive linerboard supply.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates are disqualifying non-compliant suppliers and consolidating procurement toward certified corrugated converters with verified chain-of-custody documentation.
- E-commerce fulfillment automation:Standardized tote footprints compatible with AS/RS and conveyor systems are displacing irregular container formats in high-velocity distribution centers.
- German automotive parts distributors:Systematic replacement of plastic totes with paper-based alternatives is creating sustained demand for moisture-resistant kraft-lined bin configurations.
Market Restraints
- Recycled fiber supply concentration:Containerboard mills in the southeastern United States control critical linerboard grades, exposing buyers to regional production disruptions and freight cost volatility.
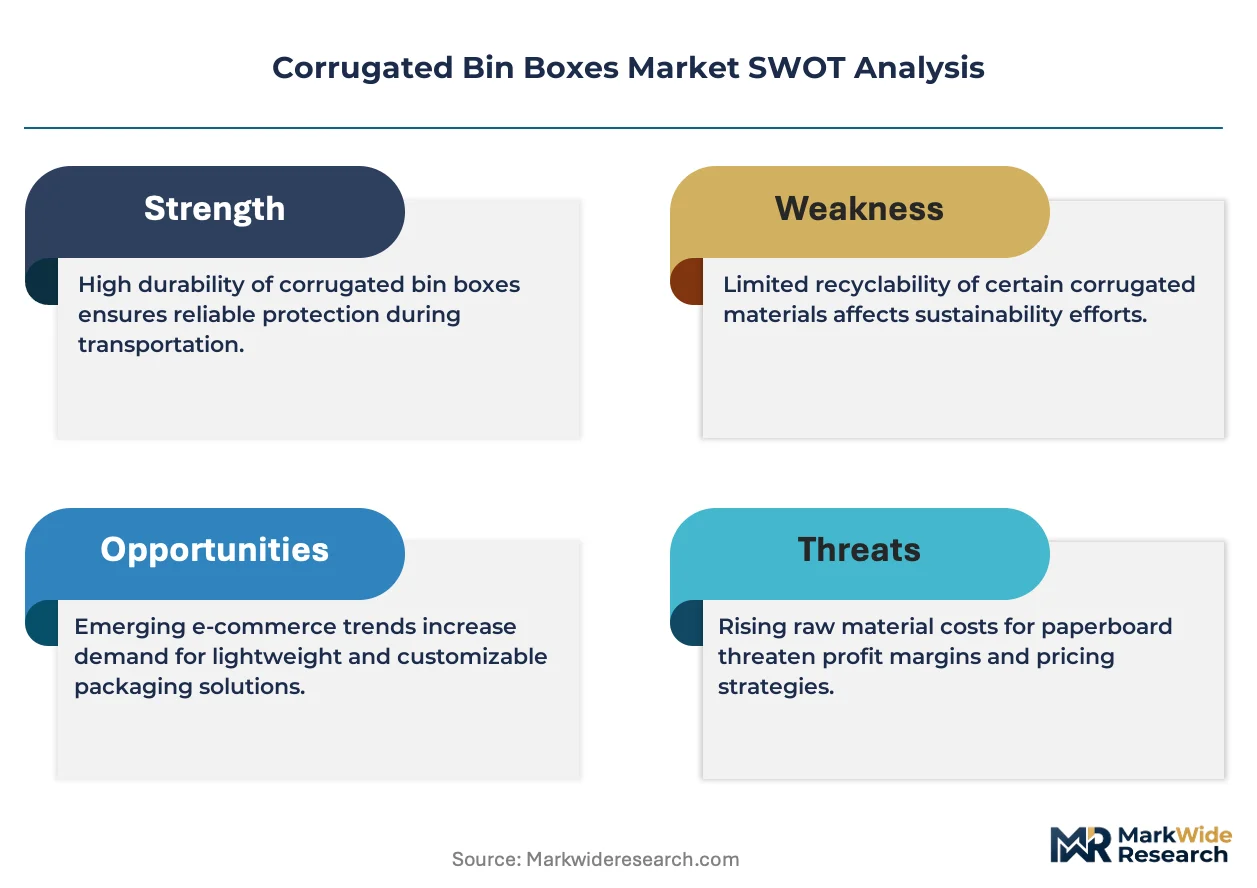
- Moisture sensitivity threshold:Standard recycled-content corrugated fails in cold-chain and agricultural applications, limiting addressable market penetration despite sustainability preferences.
- OSHA ergonomic enforcement:Manual handling weight limits for loaded bins are constraining single-wall designs and forcing investment in reinforced hand-hole configurations that elevate unit costs.
Strategic Opportunities
- Retail backroom replenishment:European-designed stackable bin formats with multi-depth adjustability are penetrating grocery and mass merchant operations seeking to reduce shelf-stocking labor.
- California SB 54 implementation:Extended producer responsibility requirements for recyclable packaging are creating qualification advantages for suppliers with post-consumer content verification systems.
- RFID-integrated smart bins:Convergence of printed electronics with corrugated substrate is enabling real-time inventory tracking in pharmaceutical and aerospace component warehouses.
Industry Challenges
- Automated line integration:Case erectors and sealers in legacy distribution centers require retooling to handle variable-depth bin designs, extending implementation timelines and capital recovery periods.
- Recycled content certification lag:Third-party verification of post-consumer fiber thresholds for EU Green Deal compliance is creating 90-120 day supplier qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Bin Boxes Market |
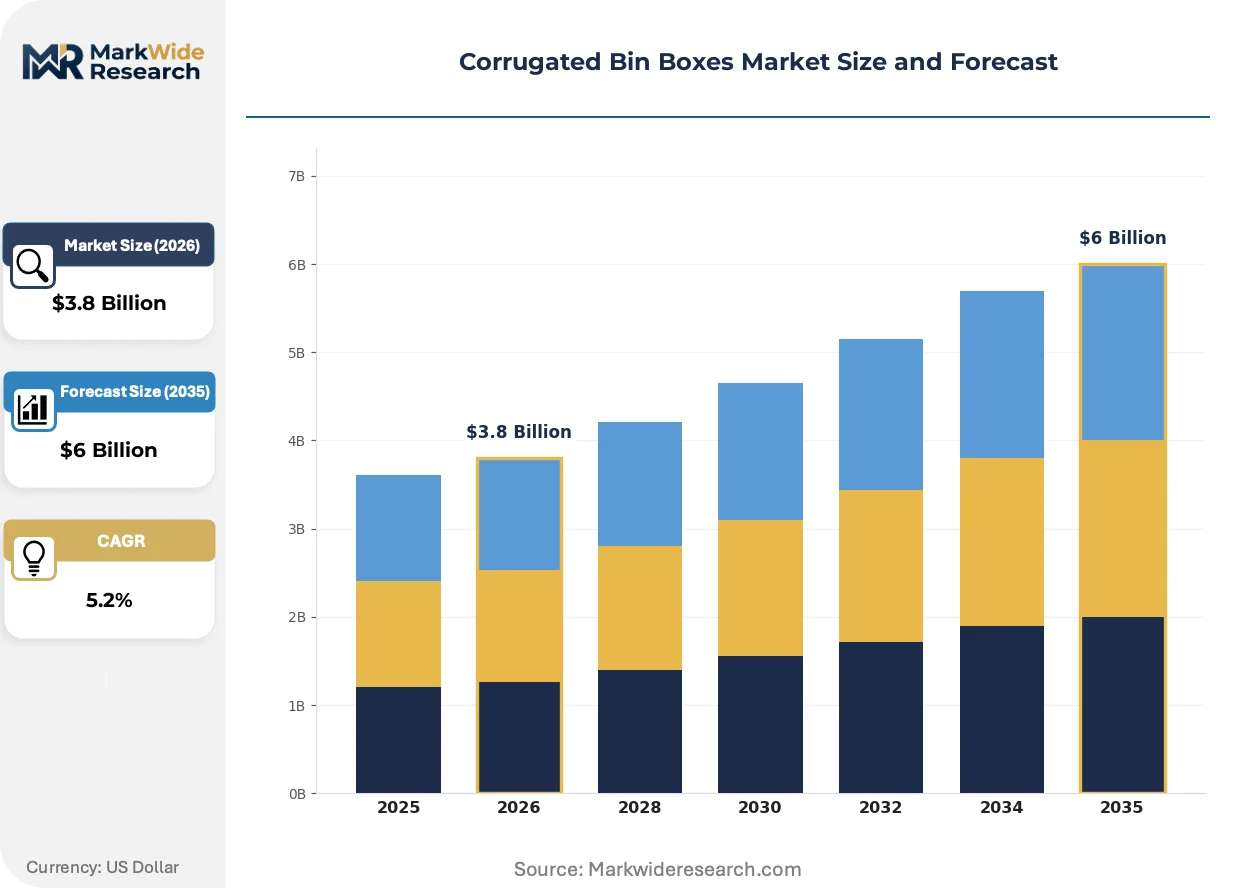
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Large Bins, Small Bins, Storage Containers, Tote Boxes Material: Recycled Paperboard, Kraft Paper, Coated Paper, Corrugated Cardboard Application: Retail Storage, E-Commerce Packaging, Industrial Use, Agricultural Supplies End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Georgia-Pacific, Mondi Group, Packaging Corporation of America, Rengo Co., Ltd., Pratt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Bin Boxes Market Strategic Shifts
Digital printing and structural design software are collapsing prototyping cycles and enabling lot-size-one production economics previously incompatible with corrugated manufacturing scale. These capabilities are redefining competitive differentiation beyond commodity linerboard specifications.
Variable-depth corrugated bin designs with reinforced corner posts and modular insert systems are expanding into pharmaceutical distribution and aerospace component logistics. Third-party logistics providers operating multi-tenant warehouses are adopting these configurations to reduce SKU-specific packaging inventories. The technology is expanding into temperature-controlled applications through integration of insulating liners and phase-change material compartments.
The EU Green Deal's recyclability labeling mandates and France's extended producer responsibility scheme are reshaping supplier qualification protocols across continental distribution networks. Industrial buyers now require documented chain-of-custody for post-consumer fiber content before contract award. German automotive tier-one suppliers are most affected, with procurement departments embedding recycled-content minimums into supplier scorecards and conducting unannounced mill audits.
Consolidated procurement through national distribution networks is compressing regional converter margins and elevating the importance of logistics density. Direct relationships between end-users and integrated producers are displacing traditional merchant broker channels in high-volume tote applications. This concentration is most visible in the southeastern United States, where pulp-to-box integrated mills are capturing automotive and appliance manufacturer contracts through captive supply guarantees and just-in-time delivery commitments.
Corrugated Bin Boxes Market Segmentation
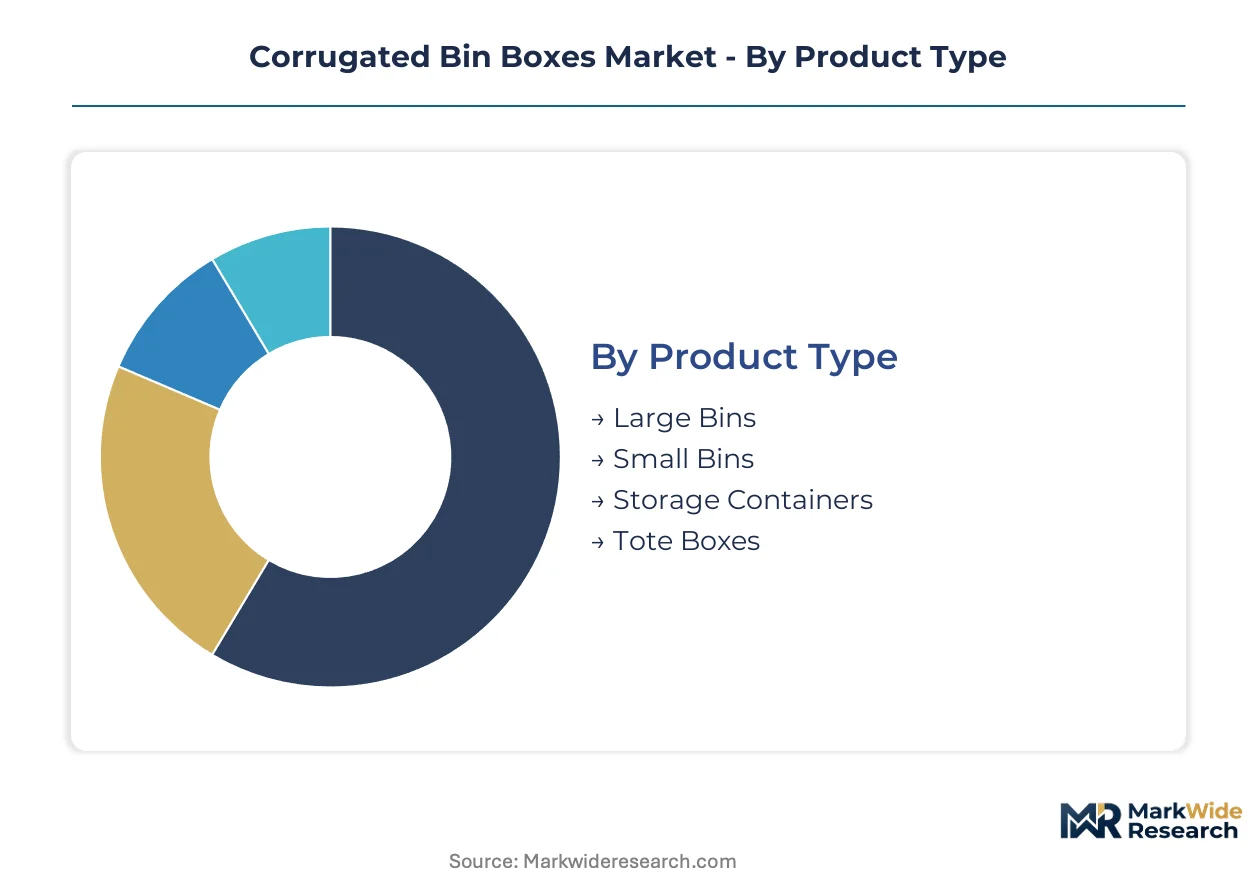
Corrugated bin box procurement varies sharply across customer profiles and use environments. Specification requirements diverge on burst strength, moisture resistance, and dimensional tolerances for automated handling systems. Suppliers must configure production assets to serve these distinct demand clusters without sacrificing linerboard yield.
Product Type:
Capital intensity escalates with structural complexity and tooling requirements for automated forming lines.
- Tote Boxes:Standardized footprints from 12x12 to 24x24 inches interface directly with AS/RS racking and conveyor systems. E-commerce fulfillment centers in Germany and the United States are specifying these configurations for high-velocity picking operations where dimensional consistency prevents jamming.
- Storage Containers:Multi-depth designs with reinforced corner posts and modular insert systems accommodate variable SKU dimensions. Pharmaceutical distributors and aerospace component warehouses are adopting these to reduce packaging inventories across temperature-controlled environments.
- Large Bins:Triple-wall constructions for bulk agricultural and industrial applications require heavy-duty flute profiles and extended curing cycles.
- Small Bins:Single-wall formats for retail backroom replenishment prioritize printability and hand-hole ergonomics over load-bearing capacity.
Most installed capacity flows through Tote Boxes. Expansion is steepest in Storage Containers.
Material:
Raw material sourcing strategy determines compliance eligibility and moisture performance thresholds.
- Recycled Paperboard:Post-consumer content exceeding 80% satisfies EU Green Deal and California SB 54 procurement mandates. Automotive parts distributors in Germany are embedding recycled-content minimums into supplier scorecards with unannounced mill audit provisions.
- Kraft Paper:Virgin fiber construction delivers burst strength and moisture resistance for cold-chain agricultural applications where standard recycled-content corrugated fails. Pulp-to-box integrated mills in the southeastern United States anchor supply for these premium grades.
- Coated Paper:Polymer or wax barriers extend shelf life in humidity-exposed environments such as produce distribution.
- Corrugated Cardboard:Commodity-grade linerboard for low-specification industrial buffering and dunnage applications.
Recycled Paperboard commands the largest production footprint. Kraft Paper is gaining share fastest in moisture-sensitive segments.
Application:
End-use environment dictates certification requirements and performance specifications.
- E-Commerce Packaging:Standardized tote configurations with RFID integration enable real-time inventory tracking. Third-party logistics providers operating multi-tenant warehouses are adopting these to reduce SKU-specific packaging inventories across pharmaceutical and consumer goods distribution.
- Industrial Use:Heavy-duty triple-wall bins for automotive and appliance manufacturing require burst ratings above 300 pounds per square inch. International Paper and WestRock compete for these contracts through captive linerboard supply guarantees.
- Retail Storage:European-designed stackable formats with multi-depth adjustability penetrate grocery and mass merchant backroom operations seeking to reduce shelf-stocking labor.
- Agricultural Supplies:Moisture-resistant kraft-lined configurations sustain demand for produce harvesting and cold-chain distribution.
E-Commerce Packaging absorbs the highest volume of automated-grade production. Industrial Use carries the steepest specification escalation trajectory.
End User:
Procurement scale and technical sophistication separate volume buyers from price-sensitive intermediaries.
- Distributors:National networks with consolidated procurement compress regional converter margins and elevate logistics density requirements. Direct relationships with integrated producers are displacing traditional merchant broker channels.
- Manufacturers:Automotive and appliance producers in the southeastern United States negotiate just-in-time delivery commitments and captive supply guarantees from pulp-to-box integrated mills.
- Retailers:Grocery and mass merchant chains specify European-designed stackable formats for backroom replenishment efficiency.
- Wholesalers:Price-sensitive buyers accepting commodity-grade specifications with limited customization and extended lead times.
Distributors concentrate the most contracted capacity. Manufacturers are expanding specification requirements fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with lower compliance costs for recycled-content certification, creating arbitrage between EU-regulated markets and North American manufacturing zones. Containerboard mills in the southeastern United States capture volume from European buyers seeking to bypass extended producer responsibility fees. German automotive distributors absorb premium pricing for verified chain-of-custody documentation.
United States
E-commerce fulfillment centers in Georgia and Tennessee drive demand for standardized tote configurations compatible with automated storage systems. EPA Clean Air Act permits regulate emissions from linerboard mills in the Southeast. International Paper operates integrated pulp-to-box facilities across the region, securing supply contracts with appliance manufacturers.
Germany
Automotive parts distributors systematically replace plastic totes with paper-based alternatives, creating sustained demand for moisture-resistant configurations. The EU Packaging and Packaging Waste Regulation mandates material traceability that disqualifies non-certified suppliers. Stuttgart-based tier-one suppliers embed recycled-content minimums into procurement scorecards with unannounced mill audit provisions.
China
Domestic e-commerce platforms accelerate adoption of corrugated bin configurations for warehouse automation projects. GB standards and MIIT regulations govern packaging material specifications for cross-border shipments. Yangtze River Delta manufacturing clusters source lighter basis weight grades optimized for robotic handling systems.
Japan
Pharmaceutical distributors adopt RFID-integrated smart bins for real-time inventory tracking in temperature-controlled warehouses. METI efficiency standards encourage lightweight packaging designs that reduce logistics emissions. Osaka-based third-party logistics providers specify multi-depth storage containers to reduce SKU-specific packaging inventories.
India
Organized retail expansion in Maharashtra and Karnataka drives demand for retail backroom replenishment formats. BIS certification requirements for corrugated packaging materials reshape supplier qualification protocols. Mumbai and Pune distribution hubs consolidate procurement toward converters with verified post-consumer fiber content.
Corrugated Bin Boxes Market Competitive Environment
North American producers anchor one tier through captive linerboard supply and integrated mill networks; European specialists hold another through design-intensive stackable formats optimized for retail backroom operations. The market structures around three strategic archetypes: pulp-to-box integrated giants, recycled-fiber specialists with national distribution infrastructure, and regional converters serving price-sensitive wholesale channels. Capacity expansion and backward integration into linerboard production represent the dominant competitive moves as suppliers defend margin position against resin price volatility.
Within the integrated tier, International Paper and WestRock exemplify the North American model of captive supply chains spanning southeastern mill complexes. Smurfit Kappa occupies a position representing European design leadership in stackable bin configurations. These three entities anchor the competitive structure, with International Paper and WestRock emphasizing supply security through in-house linerboard production while Smurfit K competes through format innovation and continental logistics density.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| DS Smith |
| Georgia-Pacific |
| Mondi Group |
| Packaging Corporation of America |
| Rengo Co., Ltd. |
| Pratt Industries |
| Others |
Value Chain & Pricing Dynamics
Integrated pulp-to-box producers anchored in the southeastern United States exert outsized pricing discipline through captive linerboard supply, while family-owned regional converters absorb margin compression from freight volatility and recycled fiber certification costs. This ownership concentration rewards scale buyers with contract stability and punishes fragmented procurement with spot-market exposure.
Pricing Analysis
Distributor margins compress as direct relationships between end-users and integrated mills displace traditional merchant broker channels. Three-tier pricing structure across premium, standard, and economy levels separates moisture-resistant kraft-lined configurations from commodity recycled-content grades. Cost compression in standard tote segments is intensifying because containerboard mills rebalance output toward lighter basis weights for automated systems. Automotive parts distributors in Germany exhibit the lowest price sensitivity due to EU Green Deal compliance mandates, while wholesalers accepting commodity-grade specifications face the steepest erosion.
Supply Chain Analysis
Regional distribution centers in Georgia and Tennessee anchor hub-and-spoke patterns serving e-commerce fulfillment clusters. Supply draws from the United States, Germany, and China, with linerboard production concentrated in southeastern mill complexes. Raw material dependencies include post-consumer recycled fiber, virgin kraft pulp, and wax-coated barrier substrates. Single-source vulnerability runs through containerboard mills controlling critical burst-strength grades. Distribution runs through national networks with just-in-time delivery commitments to automotive and appliance manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated bin boxes market functions as a geographic-arbitrage play where EU extended producer responsibility fees create cost differentials favoring North American sourcing for continental European buyers seeking certified chain-of-custody documentation.
For Market Incumbents: Deepen backward integration into linerboard production to defend against resin price volatility and secure captive supply for moisture-resistant kraft grades. Expand capacity in Tennessee and Georgia to capture automotive manufacturer contracts requiring just-in-time delivery commitments. Invest in RFID-integrated smart bin R&D to counter emerging printed electronics specialists.
For New Entrants and Emerging Players: Begin with retail backroom replenishment formats in India's Maharashtra and Karnataka distribution hubs, where organized retail expansion outpaces converter capacity. Target pharmaceutical third-party logistics providers in Japan seeking multi-depth storage containers with temperature-controlled specifications. Pursue white-label partnerships with European grocery chains requiring stackable bin configurations.
For Investors and Strategic Acquirers: Packaging distributors with national logistics infrastructure are the most active acquirer in this space, consolidating regional converters to capture procurement scale advantages. Over the medium-term horizon, vertically integrated mid-caps with verified post-consumer fiber content systems present the strongest acquisition profile. Watch for EU Packaging and Packaging Waste Regulation enforcement actions as the inflection signal for supplier qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Production | Captive supply secures burst-strength grades for automotive contracts against regional production disruptions. |
| RFID-Integrated Smart Bin Development | Printed electronics convergence enables real-time tracking in pharmaceutical and aerospace warehouses. |
| Multi-Depth Storage Container Expansion | Variable SKU accommodation reduces packaging inventories for third-party logistics providers. |
| EU Green Deal Certification Investment | Verified chain-of-custody documentation qualifies suppliers for German automotive procurement scorecards. |
| Direct End-User Relationship Building | Bypassing merchant brokers captures automotive and appliance manufacturer just-in-time delivery commitments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with containerboard mill operations directors, automotive procurement managers, third-party logistics warehouse supervisors, and corrugated converter plant managers with secondary validation. Sources included EPA Clean Air Act permit filings, EU Packaging and Packaging Waste Regulation documentation, SEC 10-K disclosures from integrated producers, and customs trade data for linerboard imports. Bottom-up demand modeling across end-use segments triangulated against top-down capacity assessments from mill complex announcements.
The forecast window anchored to historical containerboard production cycles and e-commerce fulfillment center buildout patterns across the analysis window. Segmentation dimensions modeled include product type complexity, material certification tier, application environment, and end-user procurement scale. CAGRs derived from regression analysis of linerboard price indices against automated warehouse capital expenditure trends, incorporating moisture-resistance specification escalation and recycled content mandate compliance costs as industry-specific inputs.
Caveats apply where EU regulatory enforcement timing, recycled fiber supply disruptions from southeastern United States mill maintenance cycles, or cold-chain agricultural demand shifts could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Europe Plastic Bottles and Containers Market
Containers
Trigger Sprayer Market
Containers
Lever Lid Cans Market
Containers
Slotted Containers Market
Containers
EMEA Container Technology Market
Containers
Injection Molding Containers Market
Containers
Shipping Container Liners Market
Containers
Snap Secure Containers Market
Containers
Sample Containers Market
Containers
Child-Resistant Containers Market
Containers
Container Mouth Inner Seal Market
Containers
Foldable Large Containers Market
Containers
Container Stacking Machine Market
Containers
Roll Containers Market
Containers
Pail Lids Market
Containers
Grab and Go Containers Market