
 Takeaway Containers Market | 2026-2036
Takeaway Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Takeaway Containers Market Analytics
Plant-based fiber molding and advanced barrier coating technologies are reshaping how takeaway containers achieve grease resistance without plastic linings. Huhtamäki Oyj leverages its European production footprint to supply fiber-based solutions at scale. Faerch AS specializes in crystallized polyethylene terephthalate trays that withstand oven reheating. Dart Container Corporation anchors North American foam and alternative-material production through extensive manufacturing infrastructure.
Takeaway containers are rigid or semi-rigid vessels engineered from plastic resins, molded pulp, aluminum, or expanded polystyrene, with wall thicknesses and closure tolerances calibrated to maintain food temperature and prevent leakage during transport. Their primary commercial purpose is to enable off-premise food consumption while preserving product integrity from kitchen to consumer. Plastic containers still dominate volume across quick-service chains, though biodegradable materials represent the fastest-expanding margin pool as operators seek compliance-ready packaging. Paper formats command premium positioning in cafe and catering channels where brand aesthetics influence repeat purchase behavior.
The EU F-Gas Regulation and REACH chemical standards constrain fluorinated barrier treatments in fiber packaging sold across Europe, while the FDA maintains indirect food contact requirements that govern coating migrations in the United States. India's BIS certification mandates and China's GB standards for food packaging materials create additional compliance thresholds for exporters. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific bans to align capacity investments with jurisdictions where enforcement is tightening fastest.
Market Dynamics
Regulatory bans on polystyrene and fluorinated barriers are forcing material substitutions faster than coating chemistry can mature, compressing margins for converters while opening volume for fiber-based alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates phased elimination of expanded polystyrene food containers, redirecting quick-service restaurant procurement toward molded fiber and biopolymer substitutes.
- Cloud kitchen proliferation:Ghost kitchen operators in United States metropolitan clusters require standardized, brandable packaging at volume, pulling demand for custom-printed paperboard solutions.
- Advanced barrier coatings:Water-based and PLA-laminated treatments now achieve grease resistance comparable to polyethylene, removing performance barriers to fiber adoption in hot-food applications.
Market Restraints
- Pulp cost volatility:Bleached kraft pulp prices swing with Nordic and Brazilian supply disruptions, squeezing converter margins on fixed-price annual contracts with foodservice chains.
- Barrier coating performance gaps:Current bio-based liners fail in extended hot-hold applications above 85°C, limiting fiber container penetration in fried chicken and barbecue segments.
- Composting infrastructure scarcity:Industrial composting facilities remain concentrated in Germany, Netherlands, and select US West Coast metros, leaving certified compostable packaging without end-of-life pathways in most jurisdictions.
Strategic Opportunities
- India quick-service expansion:Organized foodservice penetration in tier-2 and tier-3 Indian cities remains below 15%, creating first-mover advantage for sustainable packaging suppliers establishing local converting partnerships.
- Reusable container pooling:Loop-style return systems for workplace catering and university foodservice are piloting in France and United Kingdom, opening hardware-plus-service revenue models.
- Extended Producer Responsibility schemes:France's Citeo and Italy's CONAI packaging taxes reward fiber content with lower fee schedules, incentivizing material substitution ahead of mandatory targets.
Industry Challenges
- Migration testing bottlenecks:FDA and EFSA notification timelines for novel barrier coatings stretch 18-24 months, delaying product launches and freezing R&D roadmaps.
- Thermoforming equipment retooling:Converters shifting from polystyrene to PLA or crystallized PET face $2-4 million per line in mold and dryer modifications, straining mid-cap balance sheets.
- Food contact certification fragmentation:Divergent BIS, GB, and FDA testing protocols force redundant analytical spend for exporters serving multiple regulatory zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Takeaway Containers Market |
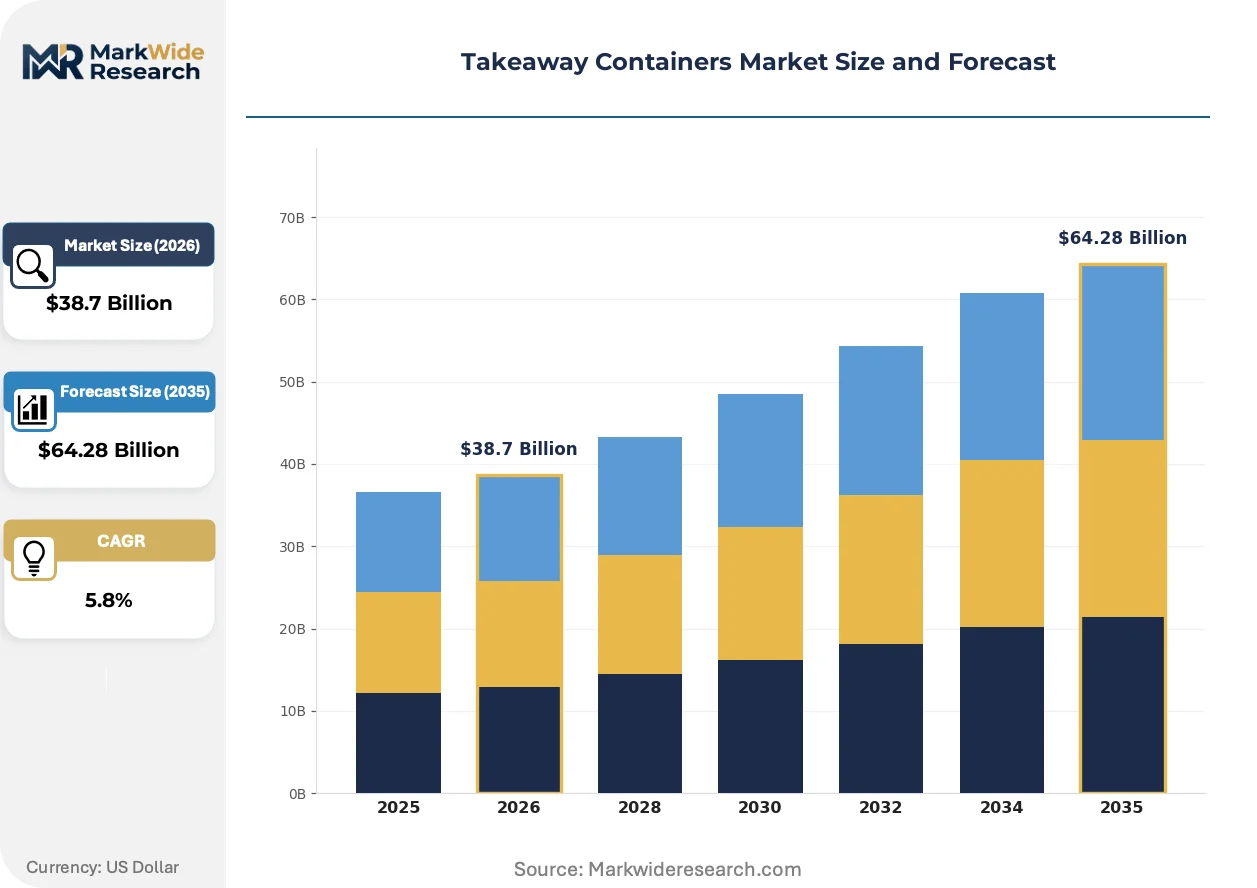
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Foam, Metal Material: Biodegradable, Non-Biodegradable, Recyclable, Composite End User: Restaurants, Food Trucks, Cafes, Catering Services Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Berry Global, Amcor plc, Dart Container Corporation, Karat Packaging, Sealed Air Corporation, Sabert Corporation, Huhtamäki Oyj, Faerch AS, Genpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Takeaway Containers Market Evolving Landscape
Barrier coating chemistry and forming precision are advancing faster than end-of-life infrastructure, creating a capability gap that favors suppliers with integrated material science and regulatory affairs functions.
Water-based fluorine-free grease barriers are collapsing the performance gap between fiber and plastic in hot-food applications. Quick-service chains in Germany and California are qualifying these treatments for fried items previously restricted to polypropylene. The collapse of this technical barrier removes the final material obstacle to fiber dominance in casual dining takeaway.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating reformulation timelines across European fiber packaging. ECHA's proposed ban on all PFAS in food contact materials forces converters to validate alternative barrier chemistries by 2026. Hot-fill and greasy-food segments face the steepest compliance curves, with some suppliers exiting the market rather than absorbing retooling costs.
Direct sourcing from packaging technologists is displacing distributor intermediaries among multi-brand cloud kitchen operators. These buyers consolidate specification authority at headquarters, demanding custom structural designs and real-time inventory visibility. The United States and United Kingdom host the most advanced procurement centralization, with operators like REEF Technology and Karma Kitchen driving vendor consolidation.
Takeaway Containers Market Segmentation
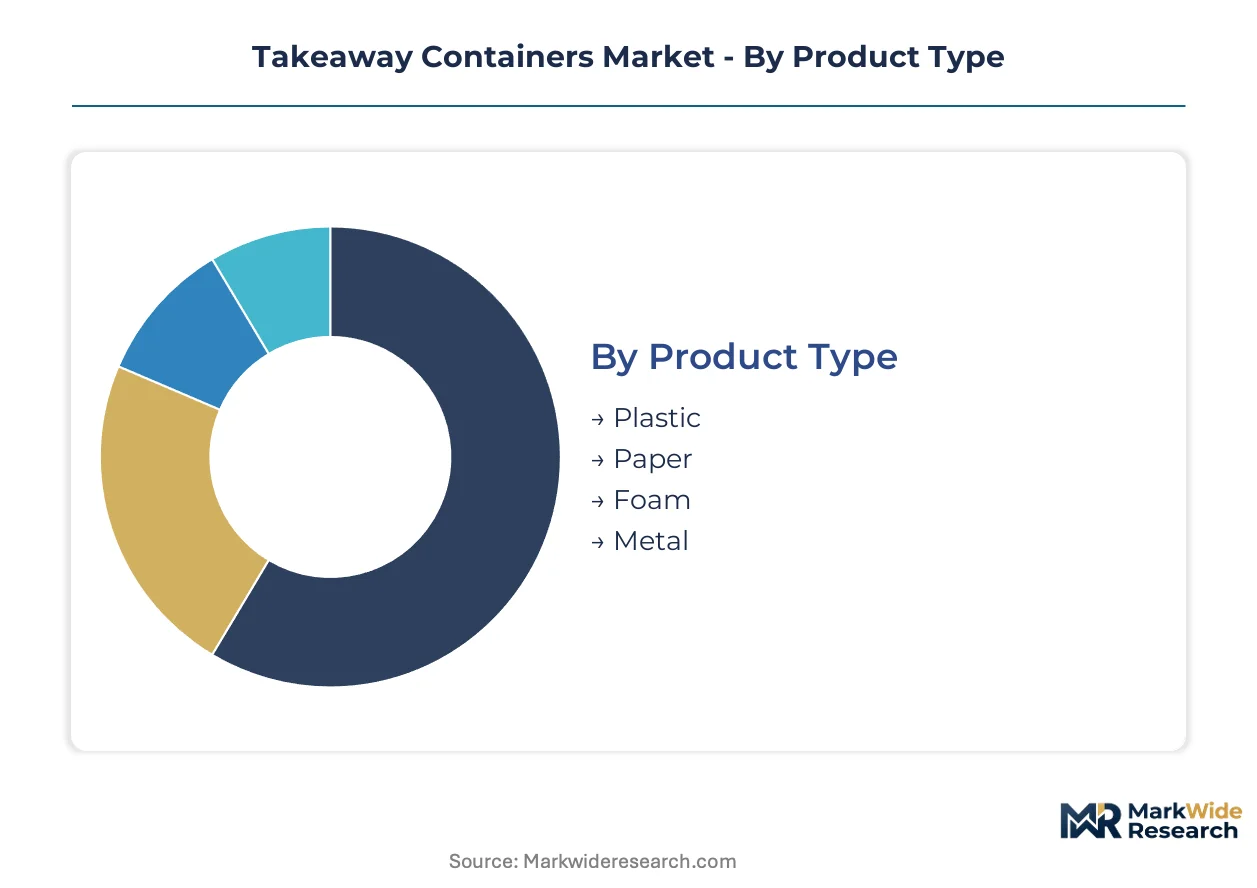
Takeaway container purchasing patterns diverge sharply across end-use contexts, with quick-service chains prioritizing unit economics and cloud kitchens demanding brand-customizable formats. Understanding these segment-specific trade-offs between performance, compliance, and total landed cost determines supplier positioning and capacity allocation.
Product Type:
After-sales service intensity varies dramatically by substrate, with fiber-based formats requiring technical support for barrier coating qualification and foam alternatives needing regulatory compliance consulting.
- Plastic:Polypropylene and polyethylene terephthalate containers dominate quick-service fried chicken and barbecue segments where grease resistance above 85°C is mandatory. United States quick-service chains specify these for extended hot-hold applications where fiber barriers still fail.
- Paper:Molded fiber and paperboard formats with water-based or PLA-laminated barrier coatings are capturing California and Germany quick-service procurement as polystyrene bans tighten. Cloud kitchen operators in United States metropolitan clusters pull custom-printed paperboard at volume for brand differentiation.
- Foam:Expanded polystyrene clamshells retain cost advantage in price-sensitive independent restaurants though EU Single-Use Plastics Directive and state-level United States bans are compressing addressable market.
- Metal:Aluminum trays serve premium catering and airline meal segments where oven reheating and structural rigidity justify material cost premium.
By volume, plastic leads. By growth pace, paper is expanding most quickly.
Material:
Cost tier stratification separates certified compostable substrates from conventional alternatives, with compliance premiums widening as extended producer responsibility schemes mature.
- Biodegradable:PLA, bagasse, and molded pulp formulations certified to industrial composting standards command price premiums in France and Netherlands where Citeo fee schedules reward fiber content. Limited composting infrastructure in most United States jurisdictions outside West Coast metros constrains end-of-life value proposition.
- Non-Biodegradable:Conventional polypropylene and polystyrene retain unit cost advantage in developing quick-service markets where regulatory enforcement remains uneven.
- Recyclable:Crystallized polyethylene terephthalate trays engineered for oven reheating qualify for existing curbside recycling streams in Germany and United Kingdom, reducing operator waste management complexity.
- Composite:Multi-layer paper-plastic laminates balance printability with barrier performance though recycling incompatibility triggers higher extended producer responsibility fees in France and Italy.
Non-biodegradable substrates still dominate unit shipments. Biodegradable alternatives are gaining share fastest where enforcement infrastructure exists.
End User:
Customer type determines specification authority concentration, with multi-brand cloud kitchen operators consolidating procurement at headquarters while independent restaurants rely on distributor intermediaries.
- Restaurants:Full-service and quick-service chains generate highest volume demand, with United States and Germany operators driving qualification of fluorine-free grease barriers for fried food applications.
- Food Trucks:Mobile operators prioritize lightweight, stackable formats with secure closure tolerances for transport vibration. California food truck clusters are early adopters of molded fiber as polystyrene bans expand to municipal permitting requirements.
- Cafes:Premium positioning in United Kingdom and France cafe channels emphasizes brand aesthetics and tactile substrate quality, pulling custom-printed paperboard with embossed finishes.
- Catering Services:Event and workplace catering in France and United Kingdom are piloting Loop-style reusable container pooling systems, opening hardware-plus-service revenue models.
Restaurants command the largest volume share. Catering services are climbing the fastest as workplace foodservice formats evolve.
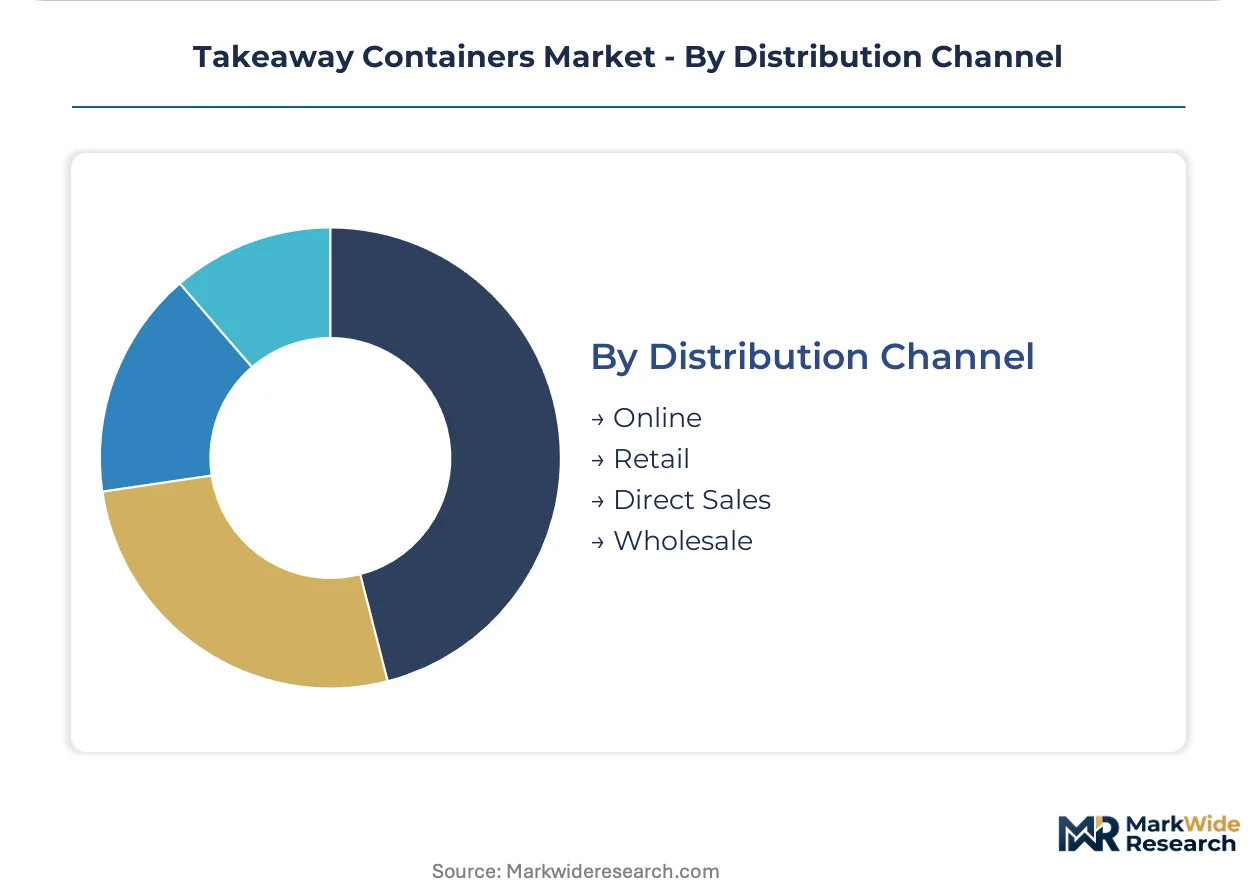
Distribution Channel:
Supply concentration shapes channel economics, with direct relationships capturing cloud kitchen volume and wholesale distributors retaining fragmented independent restaurant access.
- Online:E-procurement platforms aggregate small-restaurant demand in India and United States, enabling price transparency and consolidated shipping for biodegradable formats.
- Retail:Cash-and-carry outlets serve independent United States and Germany restaurants requiring immediate availability without contract minimums.
- Direct Sales:National quick-service chains and cloud kitchen operators in United States and United Kingdom consolidate specification authority at headquarters, demanding real-time inventory visibility and custom structural design.
- Wholesale:Broadline foodservice distributors retain intermediation role for mid-tier restaurant groups lacking procurement infrastructure.
Direct sales channels are expanding most quickly among organized foodservice. Wholesale retains the largest volume footprint across fragmented independents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented fiber packaging producers in Germany and China supply converters across jurisdictions with tightening single-use plastic restrictions. Import dependency for molded pulp technologies concentrates in markets lacking domestic thermoforming capacity.
United States
Cloud kitchen operators in New York and Los Angeles metropolitan clusters pull custom-printed paperboard at volume for brand differentiation. The FDA maintains indirect food contact requirements governing coating migrations. California and New York state-level bans on polystyrene redirect procurement toward fiber-based alternatives in quick-service chains.
Germany
Industrial composting infrastructure concentration supports premium pricing for certified compostable packaging in quick-service procurement. The EU F-Gas Regulation and REACH chemical standards constrain fluorinated barrier treatments in fiber packaging. The Rhine-Ruhr industrial corridor hosts converting capacity serving pan-European foodservice distribution.
China
Domestic cloud kitchen expansion in Shanghai and Beijing drives standardized packaging demand at manufacturing cost advantages. GB standards for food packaging materials create compliance thresholds for exporters. The Yangtze River Delta concentration of molded fiber production supplies both domestic foodservice and export markets.
India
Organized foodservice penetration in tier-2 and tier-3 cities remains below 15 percent, creating first-mover positioning for sustainable packaging suppliers. BIS certification mandates impose testing requirements on imported barrier coatings. The Mumbai-Pune industrial corridor attracts converting partnerships targeting quick-service expansion.
France
Premium cafe and catering channels emphasize brand aesthetics, pulling custom-printed paperboard with embossed finishes. Citeo packaging taxes reward fiber content with lower fee schedules under extended producer responsibility schemes. The Paris metropolitan cluster pilots Loop-style reusable container pooling systems for workplace foodservice.
Takeaway Containers Market Competitive Landscape
On the supply side, the industry is consolidating around substrate specialists with integrated barrier coating capabilities and regional thermoforming footprints. Tier-one players combine European regulatory affairs expertise with Asian manufacturing scale. Three archetypes dominate: multinational converters with multi-substrate portfolios, regional fiber specialists with compostable certifications, and foam legacy producers retooling for biopolymer alternatives. Competitive moves center on thermoforming line retooling for PLA and crystallized PET, plus strategic partnerships with cloud kitchen operators for direct procurement relationships.
Within the multinational converter tier, Huhtamäki Oyj and Faerch AS exemplify substrate-specific specialization strategies. Dart Container Corporation anchors North American production infrastructure across alternative-material categories. Berry Global and Amcor plc occupy positions spanning flexible and rigid packaging portfolios with cross-regional regulatory compliance capabilities.
| Leading Market Players |
|---|
| Berry Global |
| Amcor plc |
| Dart Container Corporation |
| Karat Packaging |
| Sealed Air Corporation |
| Sabert Corporation |
| Huhtamäki Oyj |
| Faerch AS |
| Genpak |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed price spreads between Asian molded fiber suppliers and European converters, concentrating pricing power among integrated producers with captive coating facilities while fragmenting margin capture across distributor-dependent independents.
Pricing Analysis
Industrial OEM buyers anchor contract structures around annual volume commitments with price-adjustment clauses tied to bleached kraft pulp indices. Three-tier pricing structure across premium compostable-certified, standard fiber-based, and economy polystyrene alternatives reflects certification grade and geographic delivery cost differentials. Pricing pressure stems from EU F-Gas Regulation compliance costs accelerating barrier coating reformulation timelines. Quick-service chains exhibit highest price sensitivity due to standardized procurement specifications, while premium cafe operators absorb material premiums for brand-differentiated substrates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days among European quick-service chains strain converter working capital, driving supply-chain finance facility adoption among mid-tier molders. Production gravity centers on China, Germany, and the United States, with the Yangtze River Delta and Rhine-Ruhr corridor hosting integrated fiber-forming and coating capacity. Raw material dependencies span Nordic bleached kraft pulp, Brazilian eucalyptus fiber, and bio-based PLA resin from Thailand. Single-source vulnerability concentrates in fluorine-free barrier coating chemistry where ECHA's REACH restrictions have eliminated qualified suppliers. Distribution runs through direct procurement relationships with cloud kitchen operators and broadline foodservice distributors serving fragmented independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud kitchen platform consolidation is transforming takeaway container procurement into an interoperability game where real-time inventory API integration determines supplier inclusion, mirroring platform-economics dynamics seen in ride-hailing and food delivery orchestration.
For Market Incumbents: Entrench position through backward integration into barrier coating formulation, capturing margin currently leaked to specialty chemical suppliers facing ECHA compliance attrition. Accelerate thermoforming line retooling for crystallized PET and PLA ahead of pending EU Single-Use Plastics Directive enforcement waves. Prioritize direct procurement relationships with multi-brand cloud kitchen operators consolidating specification authority at headquarters. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities present white-space terrain where organized foodservice penetration sits below 15 percent and sustainable packaging infrastructure remains undeveloped. Establish local converting partnerships in the Mumbai-Pune industrial corridor to capture quick-service expansion ahead of BIS certification mandates tightening import pathways. Lead with compostable-certified molded pulp formats where Citeo fee schedules reward fiber content in European export markets. For Investors and Strategic Acquirers: ECHA's proposed PFAS ban reshapes the acquisition landscape toward converters with validated fluorine-free barrier chemistries and regulatory affairs capabilities spanning FDA, EFSA, and BIS protocols. Target mid-cap fiber specialists with industrial composting certifications and European production footprints. Monitor cloud kitchen operator procurement centralization rates as the inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating | Captures margin from specialty chemical suppliers exiting under REACH pressure. |
| Thermoforming Line Retooling | Enables PLA and crystallized PET production as polystyrene bans tighten across EU member states. |
| Direct Procurement API Development | Secures cloud kitchen platform inclusion through real-time inventory visibility integration. |
| Industrial Composting Certification | Qualifies for Citeo fee reductions in France and Netherlands extended producer responsibility schemes. |
| Indian Converting Partnership | Positions for organized foodservice penetration in tier-2 and tier-3 cities ahead of BIS enforcement. |
Research Methodology
The analysis maps fiber-based, plastic, foam, and metal container sub-sectors, each validated through packaging procurement directors at quick-service chains, cloud kitchen supply chain leads, thermoforming equipment operators, and barrier coating R&D heads. Primary fieldwork combined with secondary validation from FDA food contact notifications, EFSA scientific opinions, EU Single-Use Plastics Directive implementation reports, and customs trade data for molded pulp and PLA resin flows. Bottom-up shipment estimates triangulated against top-down foodservice expenditure models.
Assumptions held fixed include regulatory enforcement timelines for EU member state transpositions of the Single-Use Plastics Directive and cloud kitchen platform consolidation trajectories across United States metropolitan clusters. Variables included pulp price volatility scenarios and industrial composting infrastructure buildout rates. The projection horizon spans material substitution curves across biodegradable, non-biodegradable, recyclable, and composite categories, with CAGRs derived from segment-level demand elasticity modeling against quick-service chain expansion and extended producer responsibility fee schedule implementations.
Practitioners should monitor ECHA PFAS restriction finalization, Nordic pulp supply disruptions, and cloud kitchen operator procurement centralization rates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Cardboard Box and Container Market
Containers
Oblong Tub Lids Market
Containers
Laminated Bulk Bins Market
Containers
Two Compartment Bottles Market
Containers
Twist Up Stick Container Market
Containers
Acrylic Container Market
Containers
Stainless Steel Cask Market
Containers
Compartment Trays Market
Containers
Slotted Containers Market
Containers
Foam Containers Market
Containers
Packer Bottle Market
Containers
APAC Container Technology Market
Containers
Composite Ibcs System Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Sample Containers Market
Containers
Grab and Go Containers Market