
 Latin America Intermediate Bulk Container Liner Market | 2026-2036
Latin America Intermediate Bulk Container Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Intermediate Bulk Container Liner Market Analytics
Preventive liner replacement programs and digital inventory tracking is shifting how buyers procure IBC liners across Latin America. Greif leverages its captive container fleet to anchor liner bundling contracts with multinational chemical accounts. Scholle IPN specializes in aseptic bag-in-box technology and extends its liquid-handling expertise into bulk pharmaceutical applications. Smurfit Kappa dominates corrugated IBC outer packaging in Brazil and competes by integrating liner supply with box fabrication.
Intermediate bulk container liners are multi-ply flexible films, typically 2-6 mil polyethylene or polypropylene laminates, designed to line rigid or collapsible bulk containers for liquid, paste, or granular cargo transport. These liners eliminate drum cleaning costs, reduce cross-contamination risk, and enable single-use compliance in regulated supply chains. Polyethylene formulations lead material selection for chemical and food applications due to cost-performance balance and broad regulatory acceptance, while nylon coextrusions capture premium pharmaceutical segments demanding oxygen barrier properties. The food processing end user category generates the densest procurement frequency as Latin American juice concentrate and edible oil exporters adopt disposable liner systems for export compliance.
ANVISA in Brazil and COFEPRIS in Mexico enforce pharmaceutical contact-material standards that shape liner resin grades and extractable testing protocols. Brazil's INMETRO certification requirements for food packaging migration limits add compliance layers for polyethylene and polypropylene suppliers. Argentina's national food safety authority maintains parallel additive restrictions that fragment formulation specifications across Mercosur trade corridors. Stakeholders must monitor evolving national pharmacopeia harmonization and sub-regional mutual recognition agreements to optimize single-SKU strategies versus localized production.
Market Dynamics
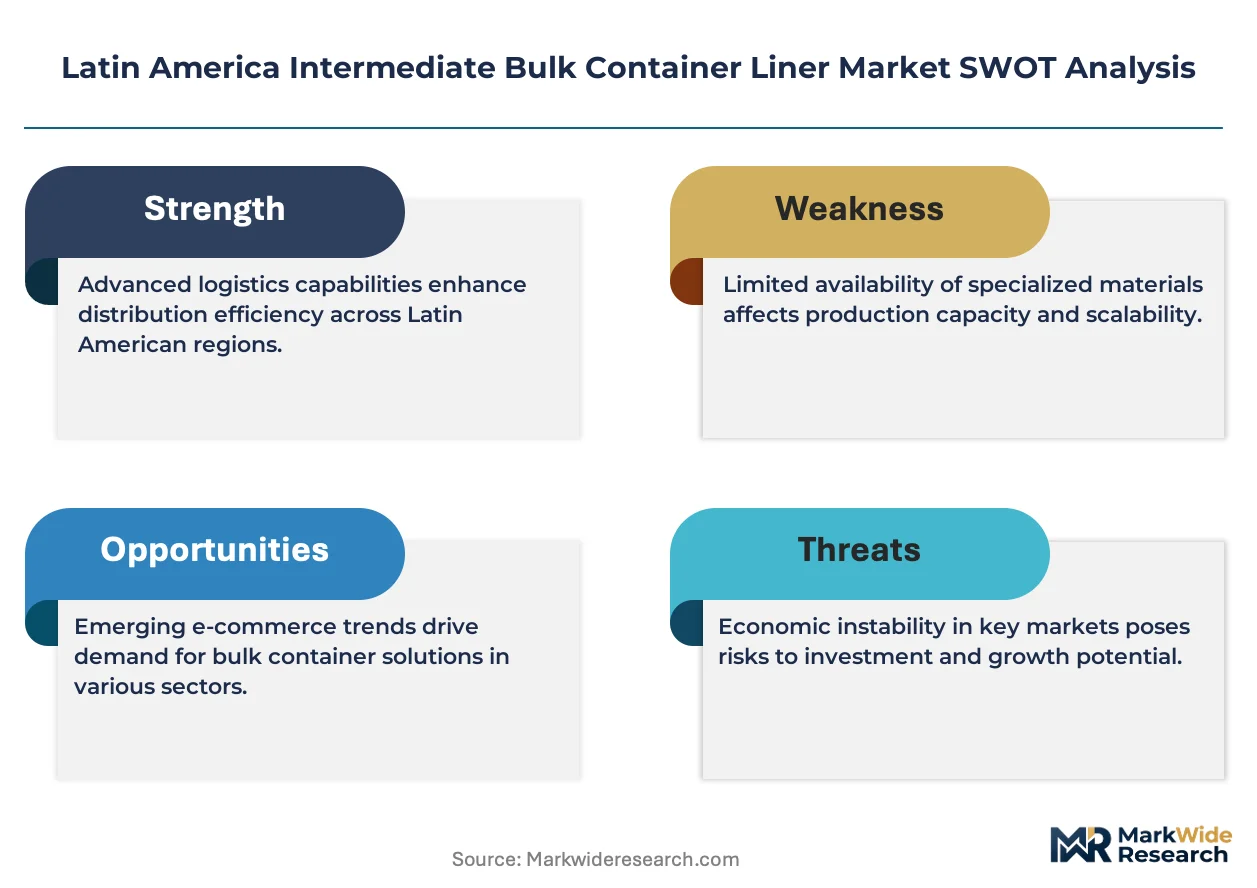
Chemical exporters across Brazil and Mexico are consolidating liner procurement around single-use compliance systems as ANVISA and COFEPRIS tighten extractable testing protocols for pharmaceutical contact materials.
Growth Catalysts
- Brazilian petrochemical corridor expansion:São Paulo's industrial belt is absorbing multi-layer polyethylene liners for bulk solvent transport, with chemical producers replacing drum fleets to eliminate cleaning costs and cross-contamination liability.
- ANVISA pharmaceutical packaging mandates:Brazil's national health surveillance agency now requires validated extractable profiles for all primary packaging, pushing sterile drug manufacturers toward certified liner suppliers with pre-submitted resin documentation.
- Multi-ply coextrusion advances:Nylon-barrier laminates are capturing oxygen-sensitive pharmaceutical segments as local compounders master 5-7 layer blown film lines previously imported from European equipment suppliers.
Market Restraints
- Polyethylene resin import dependency:Brazil and Mexico rely on Gulf Coast polyethylene supply, exposing converter margins to USD-denominated feedstock volatility and ocean freight rate spikes.
- Argentina's fragmented additive regulations:The national food safety authority maintains additive restrictions that diverge from Mercosur neighbors, forcing dual-SKU production for cross-border food-grade liner shipments.
- Collapsible container substitution:Flexible intermediate bulk containers without rigid outers are displacing lined rigid IBCs in non-pharmaceutical chemical transport, compressing addressable liner volume in commodity solvent applications.
Strategic Opportunities
- Colombian Pacific port infrastructure:Buenaventura's expanding juice concentrate export terminals lack established liner supply relationships, creating first-mover positioning for converters offering integrated bag-in-box-to-liner portfolios.
- INMETRO-ANVISA harmonization talks:Pending mutual recognition between Brazil's food packaging and pharmaceutical regulators could collapse dual-certification costs, rewarding pre-invested suppliers with unified SKU strategies.
- RFID-enabled liner tracking:Convergence of flexible packaging with low-cost sensor tags is enabling pharmaceutical shippers to monitor temperature excursion and chain-of-custody without secondary datalogger hardware.
Industry Challenges
- Blown film technician scarcity:Multi-layer coextrusion operation requires specialized calibration skills that outpace vocational training output in São Paulo and Monterrey industrial zones.
- Extractable study backlog:ANVISA's testing queue for novel resin formulations now exceeds fourteen months, delaying product launches for reformulated barrier films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Intermediate Bulk Container Liner Market |
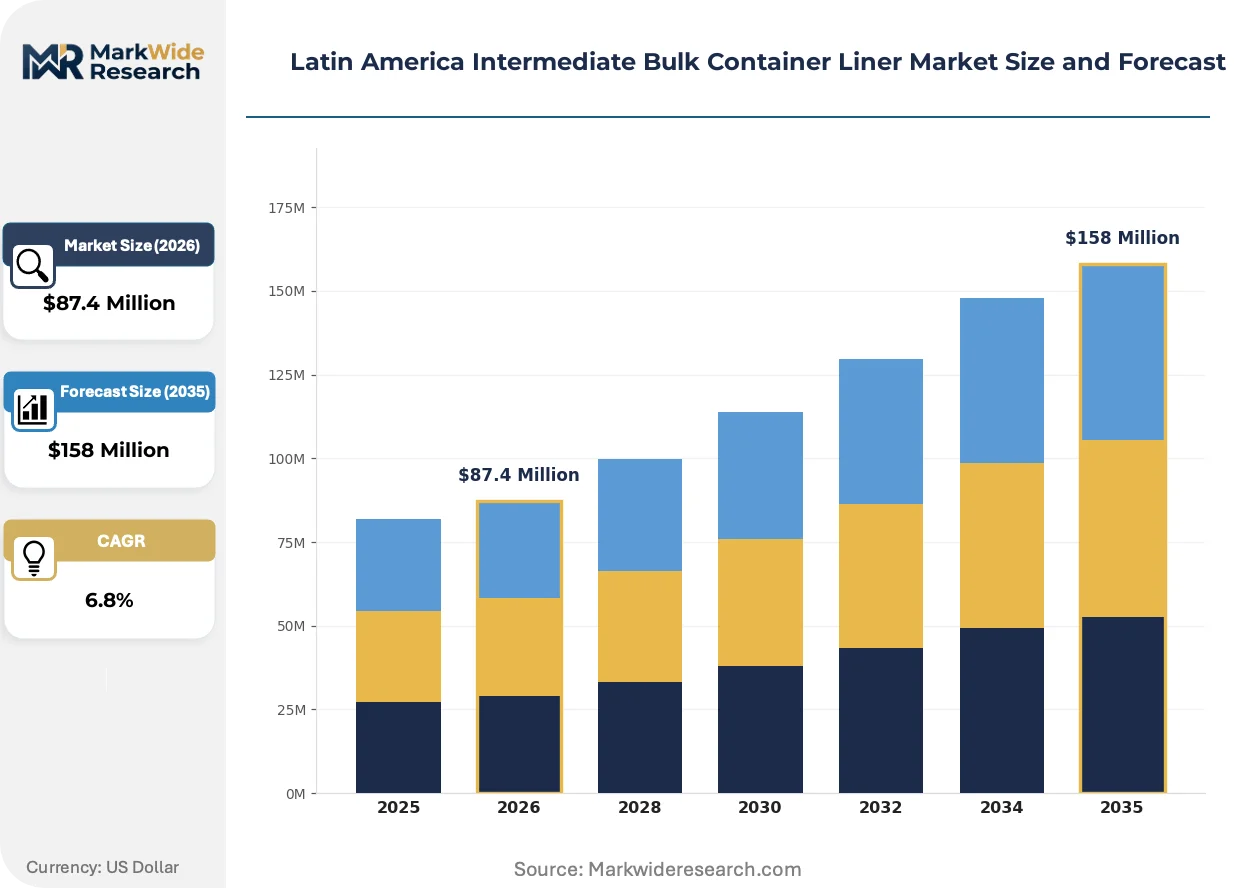
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture Material: Polyethylene, Polypropylene, Nylon, PVC Capital Type: Manufacturers, Distributors, Exporters, Retailers End User: Logistics, Food Processing, Chemical Production, Beverage Industry |
| Companies Covered | Arena Products, Inc., Liquibox, Amcor plc, Greif, ILC Dover LP, Sealed Air, Scholle IPN, Smurfit Kappa, CHEP, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Intermediate Bulk Container Liner Market Evolving Landscape
Digital inventory systems and preventive replacement scheduling are compressing procurement cycles across Latin American chemical and pharmaceutical supply chains, forcing liner suppliers to embed themselves deeper in buyer ERP workflows.
Metallocene-catalyzed polyethylene is overtaking conventional Ziegler-Natta resins in pharmaceutical-grade liners due to superior clarity and lower extractable profiles. Brazilian sterile drug manufacturers are specifying metallocene grades for parenteral solution transport despite 15-20% cost premiums. This resin shift is compressing the supplier base toward compounders with dedicated metallocene extrusion lines and pre-validated ANVISA master files.
COFEPRIS in Mexico is accelerating alignment with US FDA extractable testing protocols for pharmaceutical contact materials, forcing domestic liner converters to adopt USP Class VI and ISO 10993 biocompatibility frameworks previously treated as export-only requirements. The regulatory convergence is most acute in Mexico City's pharmaceutical manufacturing cluster, where multinational drug sponsors now demand identical liner specifications across their US and Mexican fill-finish operations.
Preventive replacement programs are displacing failure-driven liner procurement in Brazil's São Paulo chemical corridor. Large solvent distributors now schedule liner swaps based on cycle-count thresholds rather than visual inspection, unbundling liner supply from emergency logistics and compressing supplier margins on spot orders. This behavioral shift is most visible among multinational chemical accounts with centralized procurement functions operating across Mercosur trade corridors.
Latin America Intermediate Bulk Container Liner Market Segmentation
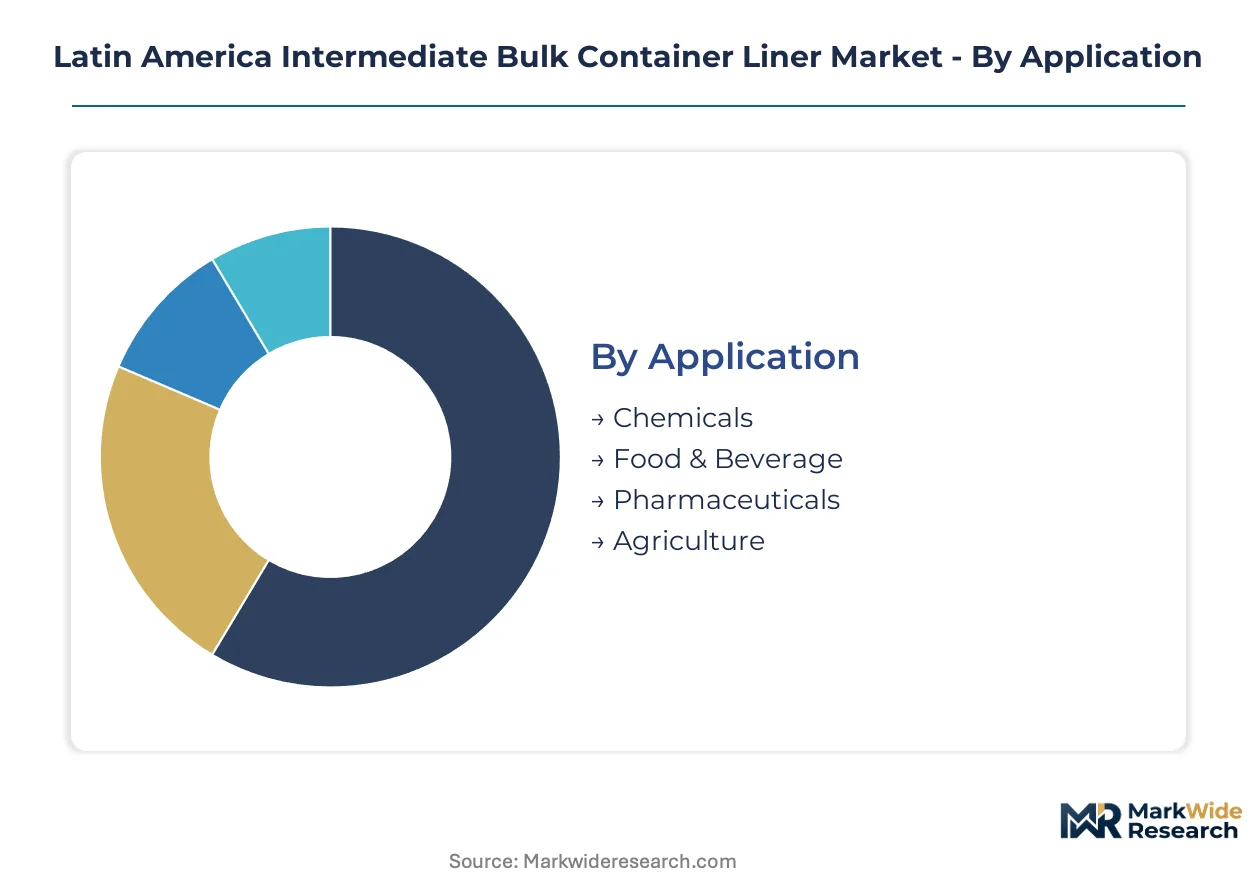
IBC liner procurement in Latin America fragments across resin chemistry, container integration depth, and regulatory compliance tiers. Buyers optimize total landed cost by matching material specifications to cargo reactivity and transport distance rather than defaulting to standard formulations.
Application:
Chemical transport dominates standalone liner deployment, while pharmaceutical and food systems embed deeper into validated supply chains with extractable documentation.
- Chemicals:Multi-ply polyethylene laminates handle solvents, acids, and base chemicals across Brazil's São Paulo petrochemical corridor. São Paulo industrial distributors specify 4-6 mil coextruded barriers to eliminate drum cleaning costs and cross-contamination liability in multi-product logistics networks.
- Food & Beverage:Juice concentrate and edible oil exporters adopt food-grade polyethylene with INMETRO migration compliance for disposable export systems. Brazilian orange juice processors in São Paulo state drive dense procurement frequency for aseptic bag-in-box integration with corrugated IBC outers.
- Pharmaceuticals:ANVISA-validated liners with pre-submitted resin master files serve sterile drug manufacturers.
- Agriculture:Fertilizer and agrochemical distributors use standard polyethylene formulations for seasonal bulk nutrient transport.
Volume placements concentrate in Chemicals; the faster expansion belongs to Pharmaceuticals.
Material:
Resin selection maps directly to barrier requirements and regulatory acceptance tiers across Latin American converter networks.
- Polyethylene:Metallocene-catalyzed grades are overtaking Ziegler-Natta resins in pharmaceutical applications due to superior clarity and lower extractable profiles. Brazilian sterile drug manufacturers specify these grades for parenteral solution transport despite cost premiums, compressing the supplier base toward compounders with dedicated extrusion lines.
- Polypropylene:High-clarity formulations capture food-grade segments requiring hot-fill tolerance and steam sterilization compatibility. Mexican edible oil processors along the Gulf Coast specify biaxially oriented polypropylene coextrusions for oxygen barrier performance in extended shelf-life applications.
- Nylon:Coextruded barrier layers serve oxygen-sensitive pharmaceutical segments demanding 5-7 layer blown film construction.
- PVC:Limited adoption persists in legacy chemical applications with established compatibility profiles.
Polyethylene commands the highest placement volumes; nylon coextrusions are climbing the fastest on pharmaceutical oxygen-barrier demand.
Capital Type:
Supply chain positioning determines margin capture and technical service depth across the value chain.
- Manufacturers:Brazilian and Mexican blown film converters with multi-layer coextrusion capability anchor regional supply. São Paulo and Monterrey industrial zones concentrate production assets, though technician scarcity for 5-7 layer line calibration constrains capacity expansion.
- Distributors:Logistics-focused intermediaries bundle liner supply with container rental and emergency replacement services across Mercosur corridors.
- Exporters:Integrated juice concentrate and chemical traders specify custom formulations for destination-market compliance.
- Retailers:Limited direct participation; indirect sourcing through distributor networks dominates.
Manufacturer-direct relationships dominate high-compliance pharmaceutical segments; distributor intermediation persists in commodity chemical applications.
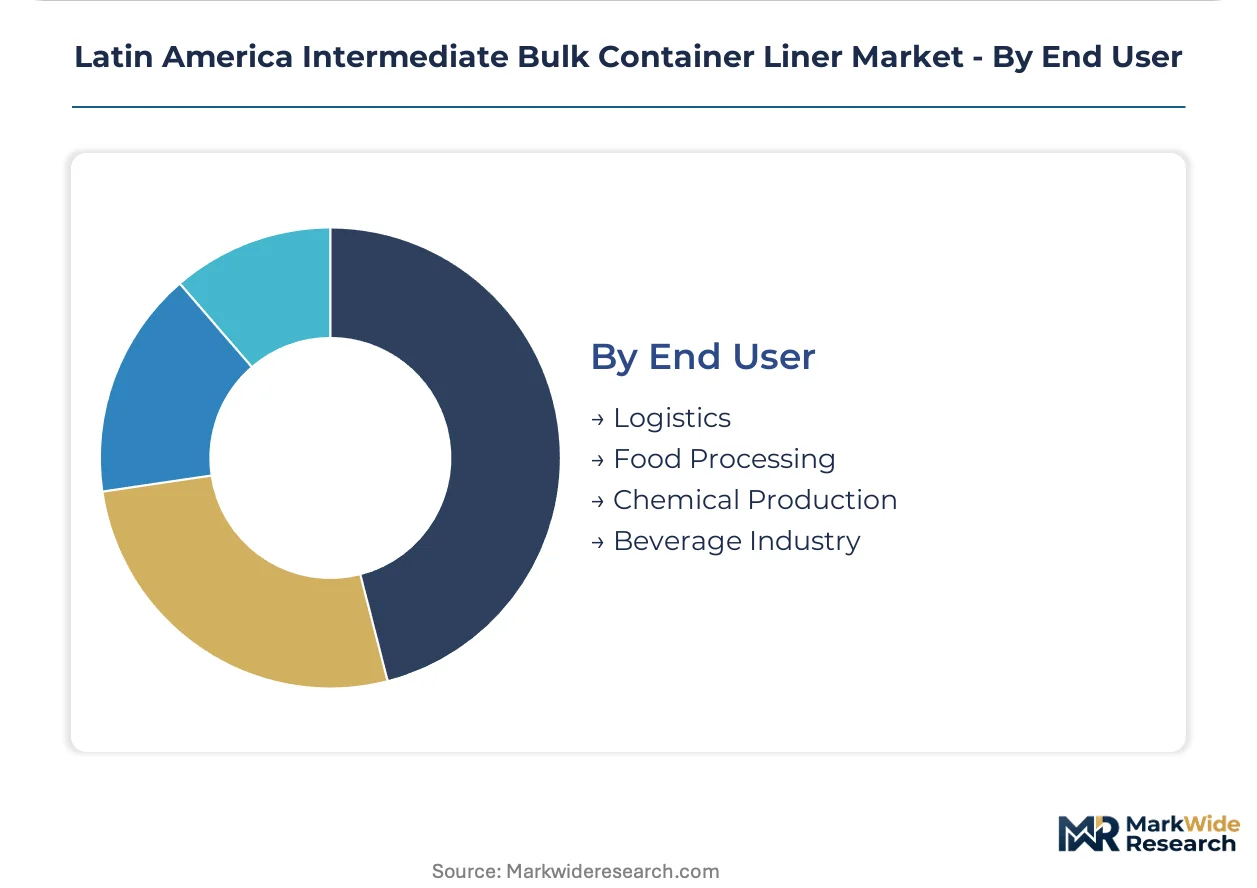
End User:
Operational intensity and regulatory exposure shape procurement sophistication across user categories.
- Logistics:Third-party bulk liquid handlers specify rapid-changeover liner systems to maximize container turns. São Paulo chemical distributors now schedule preventive replacement based on cycle-count thresholds rather than failure-driven procurement.
- Food Processing:Juice concentrate and edible oil exporters adopt disposable liner systems for export compliance. Colombian Pacific port terminals at Buenaventura represent underdeveloped demand with limited established supplier relationships.
- Chemical Production:Petrochemical manufacturers consolidate procurement around single-use compliance to eliminate cleaning infrastructure.
- Beverage Industry:Soft drink and brewing operations use standard food-grade formulations for syrup and concentrate transport.
Food Processing generates the densest procurement frequency; Logistics is gaining share fastest on digital inventory integration and preventive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes the majority of regional liner volumes while Mexico concentrates import-dependent production assets. Argentina and Colombia remain net importers of certified pharmaceutical-grade films. Chile's mining chemical demand runs through specialized barrier formulations.
Brazil
São Paulo's petrochemical corridor drives solvent and base chemical liner consumption as distributors replace drum fleets with single-use polyethylene systems. ANVISA pharmaceutical packaging mandates now require validated extractable profiles for all primary packaging materials. Campinas and São José dos Campos industrial zones anchor blown film converter capacity for multi-layer coextrusion lines.
Mexico
Gulf Coast petrochemical processors specify nylon-barrier laminates for oxygen-sensitive pharmaceutical transport. COFEPRIS alignment with US FDA extractable testing protocols forces adoption of USP Class VI biocompatibility frameworks. Monterrey industrial zone concentrates 5-7 layer blown film production assets serving multinational drug sponsors.
Argentina
Agrochemical distributors in Buenos Aires province absorb standard polyethylene formulations for seasonal fertilizer bulk transport. The national food safety authority maintains additive restrictions diverging from Mercosur neighbors. Rosario agricultural trading hub drives procurement frequency for disposable export liner systems.
Colombia
Buenaventura Pacific port terminals generate unmet demand for juice concentrate export liner supply. INMETRO-equivalent migration compliance requirements shape food-grade polyethylene specifications for edible oil processors. Bogotá pharmaceutical manufacturing cluster lacks established certified liner supplier relationships.
Chile
Mining chemical solvent transport in Antofagasta region requires specialized acid-resistant barrier formulations. The national pharmaceutical regulator enforces extractable testing protocols parallel to ANVISA standards. Santiago metropolitan area concentrates logistics provider demand for rapid-changeover liner systems.
Latin America Intermediate Bulk Container Liner Market Competitive Landscape
Capital-heavy blown film converters compete with asset-light packaging designers and logistics integrators for margin capture across Latin America. The supplier base fragments between multinational resin compounders with dedicated metallocene extrusion lines and regional distributors bundling liner supply with container rental services. Three archetypes dominate: integrated packaging conglomerates with captive container fleets, specialized aseptic film producers, and corrugated outer packaging suppliers backward integrating into liner fabrication. Competitive moves concentrate on strategic partnerships with pharmaceutical sponsors and geographic expansion through distributor acquisition.
Among integrated packaging conglomerates, Greif anchors the liner-bundling contract segment through its captive container fleet relationships with multinational chemical accounts. Scholle IPN exemplifies the aseptic specialization archetype, extending liquid-handling expertise into bulk pharmaceutical applications. Smurfit Kappa represents corrugated outer packaging integration, competing through combined liner supply and box fabrication capabilities in Brazil.
| Leading Market Players |
|---|
| Arena Products, Inc. |
| Liquibox |
| Amcor plc |
| Greif |
| ILC Dover LP |
| Sealed Air |
| Scholle IPN |
| Smurfit Kappa |
| CHEP |
| Others |
Value Network & Pricing Analysis
INMETRO migration compliance for food-grade polyethylene functions as a gatekeeper mechanism, restricting qualified supply to converters with certified extrusion lines and enabling tiered pricing separation between certified and uncertified producers across Brazilian and Mexican procurement networks.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects metallocene resin premiums and ANVISA master file validation costs. Three-tier pricing structure across certified pharmaceutical, food-grade INMETRO-compliant, and standard chemical grades dominates transactional flows. Price differentiation traces to extractable documentation depth and barrier layer complexity. Chemical distributors exhibit highest price sensitivity; sterile drug manufacturers absorb premiums for pre-validated supply security.
Supply Chain Analysis
Container return flows and liner disposal logistics constrain working capital efficiency for São Paulo chemical distributors operating multi-product rotation systems. Supply concentrates in Brazil and Mexico, with blown film capacity anchored in Campinas and Monterrey industrial zones. Raw material dependencies center on Gulf Coast polyethylene resin, nylon barrier coextrusions, and imported European extrusion equipment. Single-source vulnerability to ocean freight rate volatility threatens converter margins. Distribution runs through manufacturer-direct relationships for pharmaceutical accounts and distributor intermediation for commodity chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer coextrusion technician scarcity across São Paulo and Monterrey props pricing power for qualified converters, constraining rapid capacity expansion regardless of demand signals.
For Market Incumbents: Lock in long-term resin offtake agreements with Gulf Coast suppliers to hedge USD-denominated feedstock exposure. Anchor liner supply contracts to captive container fleet relationships, creating switching costs that defend against corrugated outer packaging integrators backward integrating into film fabrication. Prioritize ANVISA master file pre-submission for metallocene grades to compress approval timelines for sterile drug sponsors. For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms targeting mid-sized Brazilian chemical distributors offer lowest barrier entry, bypassing established distributor relationships in São Paulo. Colombian Pacific port infrastructure at Buenaventura represents the most penetrable geography, with juice concentrate exporters lacking established liner supply partnerships. Lead with integrated bag-in-box-to-liner portfolio positioning against fragmented local suppliers. For Investors and Strategic Acquirers: INMETRO-ANVISA harmonization announcement is the leading indicator that unified SKU strategies will reward pre-invested suppliers with margin expansion. Long-term viability centers on converters with dedicated metallocene extrusion lines and validated pharmaceutical master files. Target acquisition archetype: Brazilian blown film specialists with existing ANVISA submissions and underutilized 5-7 layer coextrusion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Resin Compounding | Captive supply of pharmaceutical-grade polyethylene reduces ANVISA validation dependencies and extractable study backlogs. |
| RFID-Enabled Liner Tracking Integration | Sensor-tag convergence enables temperature excursion monitoring for COFEPRIS-compliant pharmaceutical shipments without secondary hardware. |
| Colombian Pacific Port Distribution Partnership | Buenaventura juice concentrate terminal access captures first-mover positioning in underdeveloped export liner demand. |
| Preventive Replacement Program Embedding | ERP workflow integration with São Paulo chemical distributors compresses spot order margins and locks in recurring revenue. |
| Multi-Layer Coextrusion Technician Training Consortium | São Paulo vocational pipeline expansion alleviates capacity constraints for 5-7 layer blown film calibration skills. |
Research Methodology
Multi-period observation of ANVISA submission queues, INMETRO certification grants, and resin import volumes anchored the trend analysis, supplemented by interviews with blown film plant managers, pharmaceutical packaging engineers, chemical procurement leads, and logistics coordinators across São Paulo, Monterrey, and Buenos Aires. Secondary validation drew from Brazilian customs records, ANVISA public master file databases, SEC filings of multinational chemical sponsors, and trade association reports from the Latin American Packaging Association. Bottom-up converter capacity estimates triangulated against top-down end-use demand segmentation.
Input-output matrices modeled resin throughput against container fleet utilization rates across the projection horizon. Segmentation dimensions included material chemistry tier, regulatory compliance grade, application reactivity class, and regional production hub concentration. CAGRs derived from fitted growth curves applied to validated base-year consumption estimates, with cross-reference to petrochemical capacity expansion announcements and pharmaceutical manufacturing investment pipelines.
The model holds under stable ANVISA-COFEPRIS regulatory alignment and continued Gulf Coast resin supply access; deviation in Mercosur trade corridor harmonization or ocean freight rate spikes would shift volume trajectories. Forecasts embed assumptions regarding technician training output and extrusion equipment import lead times. Practitioners should monitor INMETRO-ANVISA mutual recognition negotiations and Colombian port infrastructure award announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stock Clamshell Packaging Market
Containers
Lever Lid Tinplate Containers Market
Containers
Light Resistant Containers Market
Containers
PVC Container Market
Containers
North America Plastic Bottles and Containers Market
Containers
2 Piece Cans Market
Containers
In-Mold Labelled Containers Market
Containers
Canning Jars Market
Containers
Food Grade Stainless Steel Container Market
Containers
Flexible Water Tanks Market
Containers
Single Wall Jars Market
Containers
Foldable Steel Containers Market
Containers
Global Cardboard Box and Container Market
Containers
Carboy Market
Containers
Pocket Containers Market
Containers
Injection Molding Containers Market