
 Pails Market | 2026-2036
Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Pails Market Analytics
Skilled blow-molding technician availability is redrawing competitive boundaries across the pails industry. Greif Inc. leverages captive steel drum fabrication expertise to anchor industrial metal pail supply chains in North America. Time Technoplast Ltd. sustains cost leadership through high-volume plastic pail production serving Asian chemical distributors. Mauser Group N.V. dominates reconditioned and recycled pail circuits across European manufacturing corridors.
A pail is a cylindrical container, typically manufactured through injection molding, blow molding, or metal stamping, with capacities ranging from one to twenty gallons and featuring integrated handles, tamper-evident lids, or UN-rated closures for hazardous material transport. Plastic pails command the largest volume share due to resin cost efficiency and chemical resistance, while metal pails retain premium positioning in solvent and flammable liquid applications where UN certification and spark-resistant properties are mandatory. The five-gallon capacity band generates the densest margin pool, serving paint, coating, and adhesive formulations across construction and automotive supply chains.
FDA food-contact substance notifications govern resin selection for dairy and edible oil pails in the United States, while REACH restrictions on heavy metal pigments and phthalate plasticizers constrain coating formulations across Europe. India's BIS certification mandates dimensional stability and migration testing for domestic food-grade pail producers, creating compliance barriers for unqualified imports. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates, as these will determine which material technologies and regional supply bases capture the next wave of specification-driven procurement.
Market Dynamics
Resin formulation chemistry is fragmenting the pails industry as FDA food-contact substance notifications and EU REACH chemical restrictions force simultaneous compliance with divergent material specifications. Molders must maintain dual resin inventories and coating systems to serve cross-border supply chains without contamination risk or regulatory rejection.
Growth Catalysts
- India's PLI scheme:Domestic packaging localization incentives are accelerating captive blow-molding capacity expansion for food-grade dairy and edible oil intermediates. BIS certification mandates create procurement preference for qualified local producers over imports.
- REACH chemical compliance:Heavy metal pigment and phthalate plasticizer restrictions are compressing legacy coating formulations. Reformulation demand is pulling advanced polymer barrier technologies into European industrial pail specifications.
- Construction chemical distribution:Paint, coating, and adhesive formulators are consolidating five-gallon procurement around tamper-evident UN-rated closures for hazardous material transport compliance.
Market Restraints
- Polypropylene resin volatility:Feedstock cost swings compress margin stability for high-volume plastic pail producers serving price-sensitive Asian chemical distributors.
- Steel sheet supply concentration:Industrial metal pail fabrication depends on captive North American steel drum supply chains vulnerable to tariff and energy cost shocks.
- Reconditioning circuit limits:European reconditioned pail flows face quality inconsistency constraints that block penetration into food-contact and pharmaceutical intermediate applications.
Strategic Opportunities
- Extended producer responsibility frameworks:EU recycled content mandates and deposit-return schemes are creating specification premiums for post-consumer resin integration in industrial packaging.
- Dual-carbon compliance in China:GB standards for packaging material circularity are forcing domestic brand owners toward certified recyclable pail sourcing from qualified molders.
- Automotive adhesive localization:Electric vehicle battery assembly plants in Germany and South Korea are specifying UN-rated pails for electrolyte and thermal management fluid handling.
Industry Challenges
- Blow-molding technician scarcity:Skilled process engineers capable of maintaining dimensional stability across high-cavitation food-grade production lines command premium wages and limit capacity expansion velocity.
- Migration testing timelines:FDA food-contact substance notification review periods and BIS certification queue delays extend new product qualification cycles beyond customer procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pails Market |
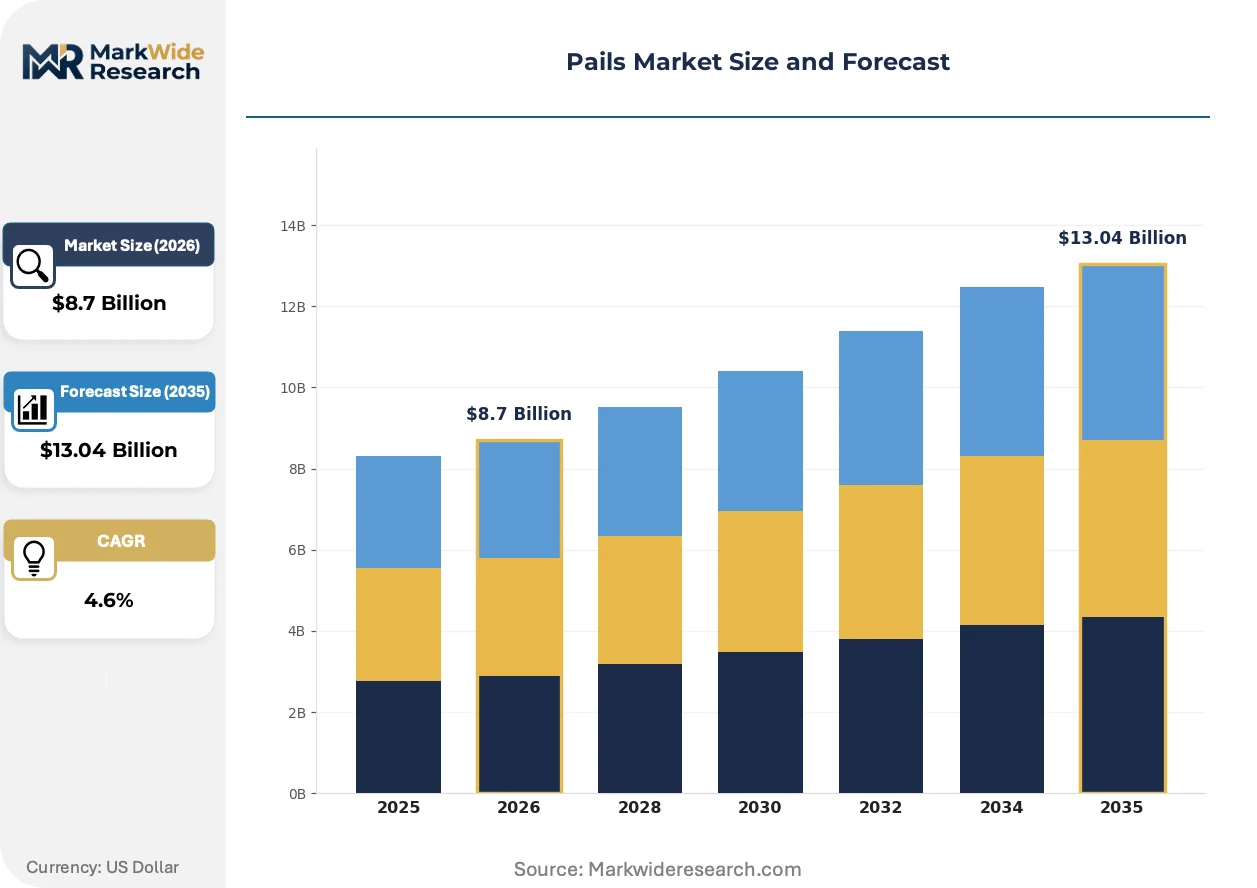
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pails, Metal Pails, Fiber Pails, Wood Pails Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 20 Gallon Packaging Type: Bulk Packaging, Carton, Individual Packaging, Wrapping End User: Food Industry, Chemical Industry, Agriculture, Household |
| Companies Covered | Berry Global Inc., ExxonMobil, Greif Inc., NCI Packaging, Rieke Corporation, Time Technoplast Ltd., FDL Packaging Group, The Cary Company, Mauser Group N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pails Market Evolving Landscape
Material science divergence and circular economy mandates are compressing legacy pail specifications while opening premium niches for advanced barrier and recycled-content formulations. Molders must now engineer for simultaneous compliance with incompatible regulatory frameworks.
Multi-layer co-extrusion barrier technology is fragmenting the standard monolayer plastic pail market. Dairy and edible oil processors in the United States are specifying ethylene vinyl alcohol interlayers to prevent oxygen ingress and rancidity without metal can substitution. This capability stratification is fragmenting supplier tiers into barrier-certified specialists and commodity volume players.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick interior coatings from European solvent and flammable liquid pail specifications. Fluoropolymer-free alternatives based on ceramic-impregnated epoxies are entering qualification trials with German paint formulators. The transition is compressing coating supplier margins while creating first-mover advantage for compliant resin system developers.
Direct procurement from certified molders is displacing distributor-mediated pail sourcing among large North American construction chemical formulators. Volume consolidation around five-gallon paint and coating specifications is enabling specification-lock contracts with captive production slots. This channel compression is most visible in Texas and California regional supply corridors where distributor inventories previously buffered demand volatility.
Pails Market Segmentation
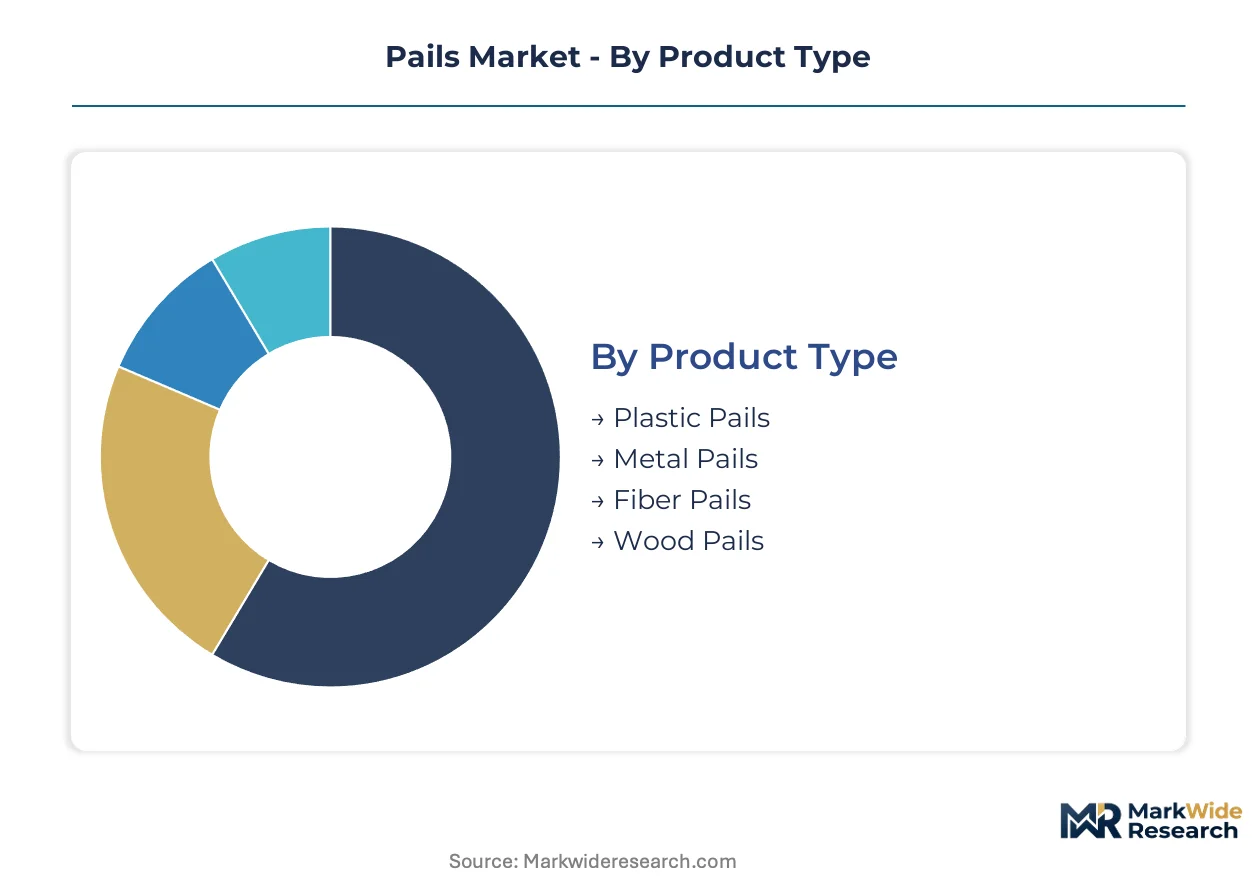
Pails specification varies sharply across material chemistry, volume bands, and regulatory exposure zones. Procurement teams segment sourcing strategies by product type and capacity to align resin or metal fabrication costs with end-use compliance requirements.
Product Type:
Margin pools concentrate in barrier-certified plastic formulations and UN-rated metal fabrications where regulatory compliance creates specification premiums.
- Plastic Pails:Polypropylene and high-density polyethylene constructions dominate volume through injection and blow molding processes. FDA food-contact substance notifications and EU REACH chemical restrictions force dual resin inventory maintenance for cross-border dairy and coating supply chains.
- Metal Pails:Cold-rolled steel with interior epoxy or phenolic linings retains mandatory positioning for solvent, flammable liquid, and UN-certified hazardous material transport where spark resistance is non-negotiable.
- Fiber Pails:Molded pulp and composite fiber constructions serve niche dry goods and agricultural seed applications with biodegradable disposal pathways.
- Wood Pails:Cooperage-style wooden pails persist in specialty food presentation and craft brewing segments where aesthetic differentiation commands price premiums.
The dominant share belongs to Plastic Pails, while Metal Pails is closing the gap fastest through UN-rated specification expansion in chemical distribution.
Capacity:
Five-gallon specifications anchor the densest margin concentration by serving paint, coating, and adhesive formulators with standardized logistics and closure systems.
- 5 Gallon:The construction chemical distribution standard integrates tamper-evident lids and UN-rated closures for hazardous material compliance. Texas and California regional supply corridors show direct molder procurement consolidation around this capacity band.
- 1 Gallon:Compact formats target household consumer goods, specialty lubricants, and sample-size industrial formulations with retail shelf presence requirements.
- 10 Gallon:Mid-volume specifications serve agricultural chemical concentrates and bulk food intermediates where handling equipment compatibility limits smaller formats.
- 20 Gallon:Maximum standard capacity addresses industrial bulk dispensing, drum-to-pail transfer operations, and high-volume adhesive manufacturing with forklift handling integration.
Five-gallon specifications capture procurement consolidation benefits, while ten-gallon formats are expanding most quickly through agricultural chemical concentration trends.
Packaging Type:
Distribution economics and contamination risk stratify packaging approaches across direct industrial supply and retail-mediated channels.
- Bulk Packaging:Palletized unit loads with stretch-wrapped containment serve construction chemical formulators and automotive adhesive plants with direct molder contracts and captive production slots.
- Individual Packaging:Single-unit retail-ready formats with branded labeling target household consumers and specialty food retailers with point-of-sale presentation requirements.
- Carton:Corrugated containment provides secondary protection for multi-unit shipments of food-grade and pharmaceutical intermediate pails with dimensional stability requirements.
- Wrapping:Shrink-film and banding configurations offer cost-minimized containment for non-hazardous industrial chemicals with established distributor handling protocols.
Bulk Packaging holds the dominant procurement volume, while Individual Packaging is gaining share fastest through retail channel expansion in household and specialty food segments.
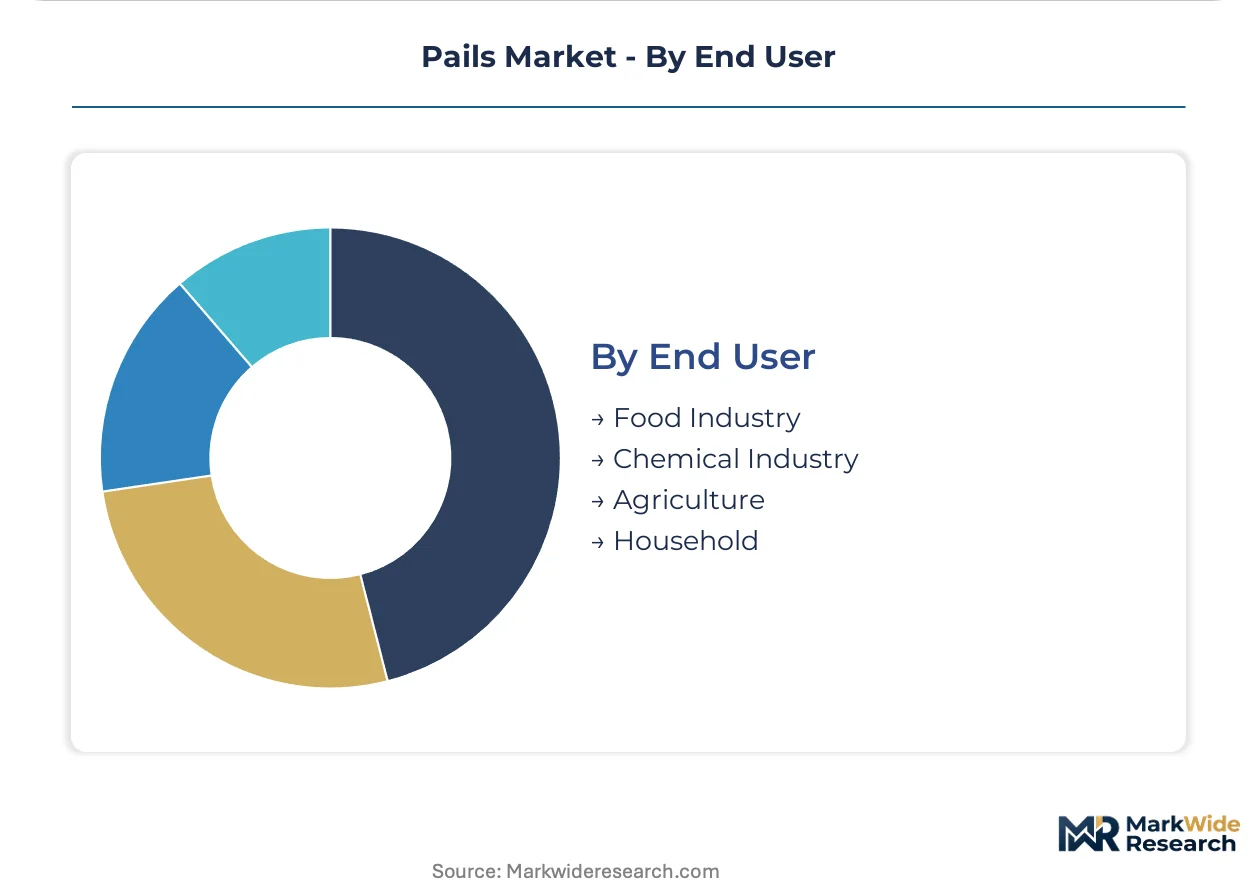
End User:
Regulatory exposure intensity and qualification timeline requirements fragment end-user segmentation between food-contact certification and industrial hazard compliance.
- Food Industry:Dairy, edible oil, and sauce processors specify ethylene vinyl alcohol barrier interlayers and FDA-compliant resin systems with extended migration testing timelines. India's BIS certification mandates and PLI scheme incentives are accelerating domestic molding capacity for this segment.
- Chemical Industry:Paint, coating, adhesive, and solvent formulators drive five-gallon standardization with UN-rated closure requirements. REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick coatings from European specifications.
- Agriculture:Fertilizer, pesticide, and seed treatment applications demand UV-stabilized resin formulations and vented closure systems for extended outdoor storage.
- Household:Consumer cleaning products and home improvement supplies prioritize retail aesthetics, child-resistant closures, and e-commerce shipping durability.
The Food Industry commands premium pricing through certification barriers, while the Chemical Industry is climbing the fastest through construction and automotive adhesive localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact substance notifications anchor United States regulatory exposure for dairy and edible oil pail procurement. Divergent compliance frameworks across major economies force molders to maintain dual resin inventories and coating systems for cross-border supply chains.
United States
Paint, coating, and adhesive formulators in Texas and California regional supply corridors are consolidating five-gallon procurement around direct molder contracts. FDA food-contact substance notifications govern resin selection for dairy intermediates with extended migration testing timelines. Houston and Los Angeles industrial clusters show specification-lock contracts replacing distributor-mediated sourcing for construction chemical distribution.
Germany
Automotive adhesive plants specifying UN-rated pails for electric vehicle battery electrolyte handling are expanding procurement volumes. ECHA REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick interior coatings from solvent pail specifications. The Ruhr industrial corridor hosts qualification trials for fluoropolymer-free ceramic-impregnated epoxy alternatives with paint formulators.
India
BIS certification mandates for dimensional stability and migration testing are creating procurement preference for qualified domestic producers over imports. The PLI scheme for packaging localization is accelerating captive blow-molding capacity expansion for food-grade dairy and edible oil intermediates. Maharashtra and Gujarat industrial zones concentrate new molding investments serving Asian chemical distributors.
China
GB standards for packaging material circularity under dual-carbon compliance frameworks are forcing domestic brand owners toward certified recyclable pail sourcing. Yangtze River Delta manufacturing corridors show qualified molders capturing specification premiums for post-consumer resin integration. Shanghai and Jiangsu province clusters lead barrier-certified plastic pail production for cross-border dairy supply chains.
South Korea
Electric vehicle battery assembly plants are specifying UN-rated pails for thermal management fluid handling with localized procurement requirements. MFDS food-contact material regulations align with export-market compliance for dairy intermediate packaging. Gyeonggi-do and Busan-Ulsan industrial basins concentrate molding capacity serving automotive adhesive and construction chemical formulators.
Pails Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pails industry. The vendor base stratifies into barrier-certified specialists, commodity volume molders, and reconditioning circuit operators. Three strategic archetypes dominate: captive steel drum fabricators leveraging metal fabrication expertise, high-volume plastic molders serving price-sensitive chemical distributors, and circular-economy specialists integrating post-consumer resin streams. Competitive moves concentrate on geographic capacity expansion and specification-lock contracts with direct procurement consolidation.
Among North American metal fabricators, Greif Inc. exemplifies the captive steel drum expertise archetype. Time Technoplast Ltd. represents the high-volume plastic molding tier serving Asian chemical distribution channels. Mauser Group N.V. occupies a position within the circular-economy and reconditioning specialist segment across European manufacturing corridors.
| Leading Market Players |
|---|
| Berry Global Inc. |
| ExxonMobil |
| Greif Inc. |
| NCI Packaging |
| Rieke Corporation |
| Time Technoplast Ltd. |
| FDL Packaging Group |
| The Cary Company |
| Mauser Group N.V. |
| Others |
Value Network & Pricing Analysis
FDA food-contact substance notifications gate both supply qualification and price differentiation simultaneously, creating tiered entry barriers where barrier-certified specialists command premiums over commodity volume molders while unqualified imports face automatic exclusion from dairy and edible oil procurement channels.
Pricing Analysis
Price spreads widen between North American and Asian production bases as resin cost volatility and certification overhead accumulate differently across regulatory jurisdictions. Three-tier pricing structure across premium barrier-certified, standard food-grade, and economy industrial tiers reflects migration testing timelines and UN-rated closure requirements. Pricing pressure stems from polypropylene feedstock swings compressing margin stability for high-volume producers serving price-sensitive chemical distributors. Construction chemical formulators show lowest price sensitivity due to specification-lock contracts, while household consumer segments drive hardest bargaining on per-unit costs.
Supply Chain Analysis
Inventory lead times stretch for dual-resin systems as molders maintain parallel stocks to serve cross-border dairy and coating supply chains without contamination risk. Supply concentrates in India, China, and Germany where PLI scheme incentives, GB circularity standards, and REACH compliance infrastructure anchor regional production hubs. Raw material flows draw from polypropylene resin suppliers, cold-rolled steel sheet producers, and ceramic-impregnated epoxy coating formulators. Single-source vulnerability runs through concentrated steel drum fabrication expertise in North American captive supply chains. Distribution runs through direct molder contracts displacing distributor mediation in Texas and California regional corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from flexible intermediate bulk containers and aseptic bag-in-box systems in food-grade liquid logistics, requiring defensive positioning around certification moats and specification-lock contracts that lock out lower-cost alternatives.
For Market Incumbents: Secure barrier-certified production slots with dairy processors through ethylene vinyl alcohol interlayer investments that flexible packaging cannot replicate. Lock in backward integration into resin compounding to buffer polypropylene cost swings and deny margin capture to raw material suppliers. Defend against reconditioned pail encroachment by extending migration testing documentation that recycled-content competitors cannot match.
For New Entrants and Emerging Players: Lead with fluoropolymer-free ceramic-impregnated epoxy coatings for European solvent pail specifications where REACH restrictions eliminate legacy suppliers. Target German automotive adhesive plants specifying UN-rated electrolyte handling pails for electric vehicle battery assembly. Pursue qualification trials with paint formulators in the Ruhr industrial corridor as the fastest path to specification credibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underoptimized pail divisions lacking barrier certification capabilities. Long-term viability hinges on positioning for extended producer responsibility frameworks and recycled content mandates tightening across the projection horizon. Watch for BIS certification queue acceleration in India as the signal indicating which domestic molders will capture PLI scheme procurement preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Certification Investment | EVOH interlayer capabilities unlock FDA-compliant dairy contracts with 18-month migration testing moats. |
| Backward Integration into Resin | Captive polypropylene compounding buffers feedstock volatility for high-volume Asian chemical distributors. |
| Fluoropolymer-Free Coating Transition | Ceramic-impregnated epoxy qualification with German paint formulators captures REACH-compliant market share. |
| Direct Procurement Consolidation | Specification-lock contracts with Texas construction chemical formulators displace distributor inventory buffers. |
| Post-Consumer Resin Integration | Certified recyclable pail sourcing under EU extended producer responsibility frameworks commands premium positioning. |
Research Methodology
A spread of perspectives from blow-molding process engineers, dairy procurement directors, chemical distributor category managers, and coating formulation specialists converged on the working assumptions driving resin selection and barrier technology adoption. Primary fieldwork combined plant-level interviews across Maharashtra, Gujarat, Texas, and Ruhr industrial zones with secondary validation from FDA food-contact substance notification databases, ECHA REACH restriction updates, BIS certification registries, and customs trade flow records. Bottom-up capacity tallies and top-down end-use consumption estimates were triangulated against disclosed capital expenditure patterns.
Segmentation dimensions modeled include material chemistry tiers, capacity bands from one to twenty gallons, packaging configuration types, and end-use regulatory exposure zones across the projection horizon. CAGRs were derived from weighted average growth contributions across food industry barrier adoption, construction chemical distribution consolidation, and automotive adhesive localization trends. Forecast inputs incorporated PLI scheme capacity commissioning timelines, BIS certification queue velocities, and REACH restriction implementation phases without year-specific anchoring.
Forecasts assume regulatory continuity in FDA food-contact regimes, EU REACH chemical restrictions, and India's BIS certification mandates; material policy shifts would require re-modeling migration testing timelines or resin formulation compliance costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PET Containers Market
Containers
Aluminum Foil Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Compartment Trays Market
Containers
Straight Sided Glass Jar Market
Containers
Injection Molding Containers Market
Containers
Thin Wall Plastic Containers Market
Containers
Disposable Cups and Lids Market
Containers
Sandwich Containers Market
Containers
HDPE Crates Market
Containers
Pinch Grip Jars Market
Containers
Takeout Containers Market
Containers
Light Resistant Containers Market
Containers
Wooden Barrels Market
Containers
EPS Container Market
Containers
Metal Crates Market