
 Mercerized Cotton Market | 2026-2036
Mercerized Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Mercerized Cotton Market Intelligence
Direct-to-garment sourcing channels are reshaping how mercerized cotton reaches premium apparel buyers. Arvind Limited leverages its integrated denim and shirting operations to control mercerized yarn flows from fiber to finished fabric. Weiqiao Textile Company Limited anchors massive spinning capacity in Shandong Province, supplying ringspun mercerized grades to Asian garment exporters. Parkdale Mills sustains its position through automated open-end and ringspun lines serving US-based home textile brands.
Mercerized cotton undergoes caustic soda treatment under tension to swell fibers, increase luster, and improve dye uptake, yielding tensile strength gains of 15-25% over untreated equivalents; this functional upgrade serves premium apparel, luxury bedding, and technical reinforcement applications. Yarn and fabric segments lead value capture, with ringspun mercerized yarn commanding margin premiums in dress shirt and high-end knitwear supply chains. Staple fiber mercerization remains concentrated among integrated spinners, while blended fabric applications expand as mills combine mercerized cotton with modal or silk for drape and sheen.
REACH restricts caustic soda handling and effluent discharge across European mercerization facilities, while India's Central Pollution Control Board enforces zero-liquid-discharge mandates on textile clusters in Tamil Nadu and Gujarat. OEKO-TEX Standard 100 certification now filters market access for mercerized cotton destined for EU and US infant apparel and luxury home textile segments. Stakeholders must monitor caustic soda price volatility and effluent treatment technology costs as regulatory thresholds tighten across major production basins.
Market Dynamics
REACH compliance and India's zero-liquid-discharge mandates are forcing mercerization facilities to absorb capital-intensive effluent treatment upgrades, reshaping cost structures and supplier viability across European and South Asian production basins.
Growth Catalysts
- Premium Apparel Specifications:Luxury dress shirt and knitwear brands specify mercerized cotton for its 15-25% tensile strength advantage and superior dye uptake, locking in yarn premiums across European and North American supply chains.
- REACH Chemical Handling Standards:ECHA enforcement on caustic soda storage and discharge protocols is filtering out subscale European processors, concentrating volume among compliant integrated mills.
- Technical Textile Expansion:Medical gauze reinforcement and high-performance sewing thread applications are absorbing mercerized yarn volumes as fiber strength specifications tighten.
Market Restraints
- Caustic Soda Price Volatility:Energy-intensive chlor-alkali production exposes mercerization margins to input cost swings, particularly acute for standalone processors lacking captive chemical supply.
- Integrated Mill Concentration:Yarn and fabric mercerization capacity clusters among vertically controlled operations in India and China, limiting third-party toll processing viability.
- Viscose Substitution:Modal and lyocell fibers compete for drape and luster applications in luxury bedding, compressing addressable market for mercerized cotton blends.
Strategic Opportunities
- United States Home Textile Channel:Direct sourcing relationships with hospitality and institutional bedding buyers bypass traditional fabric merchant intermediaries, capturing margin compression from disintermediation.
- Silk-Cotton Blend Innovation:Technical advances in tension-controlled mercerization enable stable processing of silk-cotton unions for premium eveningwear, opening adjacent luxury segments.
- India PLI Textile Incentives:Production-linked incentive schemes for man-made fiber and technical textile investments indirectly support mercerization capacity expansion in integrated Tamil Nadu and Gujarat clusters.
Industry Challenges
- Certification Timeline Compression:OEKO-TEX Standard 100 and GOTS dual certification requirements for EU infant apparel extend qualification cycles by 4-6 months, straining working capital for export-oriented mills.
- Caustic Recovery System Integration:Zero-liquid-discharge mandates require membrane filtration and evaporation capex that standalone processors struggle to finance, accelerating consolidation toward integrated chemical-textile complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercerized Cotton Market |
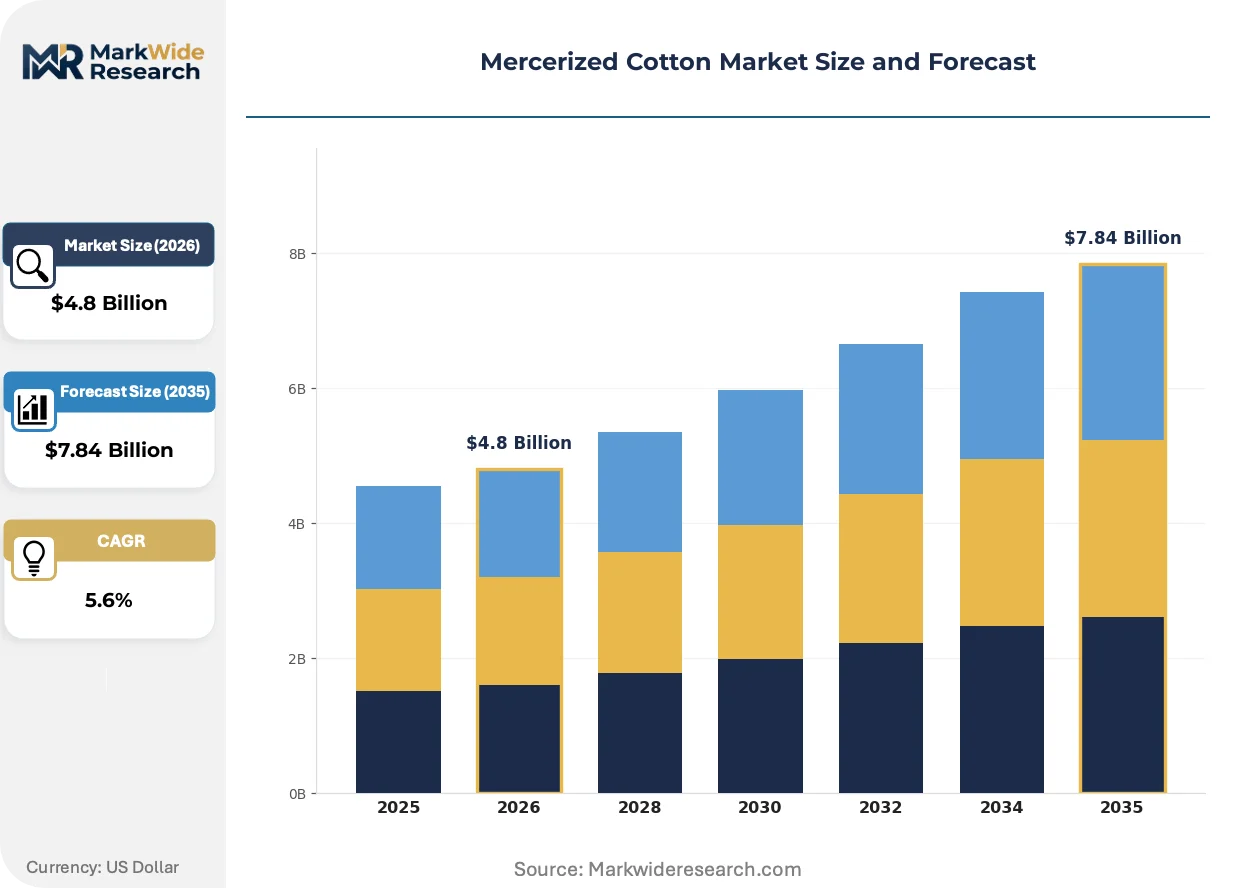
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Staple Fiber, Yarn, Fabric, Blended Fabric Application: Home Textiles, Apparel, Technical Textiles, Upholstery End User: Textile Mills, Garment Manufacturers, Interior Decorators, OEMs Form: Carded, Combed, Ringspun, Open-End |
| Companies Covered | MT Royal, Mount Vernon Mills, Wuxi Natural Textile Industrial Co., Ltd., Weiqiao Textile Company Limited, Arvind Limited, Gul-Ahmed Textile Mills Ltd., Parkdale Mills, Suzhou Facto Textile Co., Ltd., Savana Textile Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercerized Cotton Market Strategic Shifts & Innovations
Process intensification and digital process control are compressing mercerization cycle times while regulatory transparency requirements force real-time effluent monitoring adoption across major production basins.
Continuous mercerization systems with tension-controlled caustic application is migrating from batch kettle operations in European technical textile plants. Medical gauze and industrial sewing thread manufacturers in Germany and Switzerland are adopting these lines to meet ISO 13485 traceability requirements. The shift is compressing unit processing costs by 12-18% while enabling lot-level digital records for downstream certification.
ECHA's 2023 update to REACH Annex XVII restrictions on sodium hydroxide workplace exposure limits is mandating enclosed fiber handling systems in Italian and Portuguese mercerization facilities. The regulation is accelerating capital replacement cycles for open-width equipment installed before 2015. Premium shirting exporters in Northern Italy are responding by consolidating operations into fewer, larger automated lines to amortize compliance investment.
Direct mill-to-brand contracting is displacing traditional yarn merchant intermediaries in North American premium apparel supply chains. Dress shirt specialists in New York and Los Angeles now specify mercerized yarn parameters directly with Indian integrated spinners, bypassing European trading houses. The pattern is most visible in small-batch luxury menswear where lot traceability and custom dye shade matching override volume aggregation economics.
Mercerized Cotton Market Segmentation
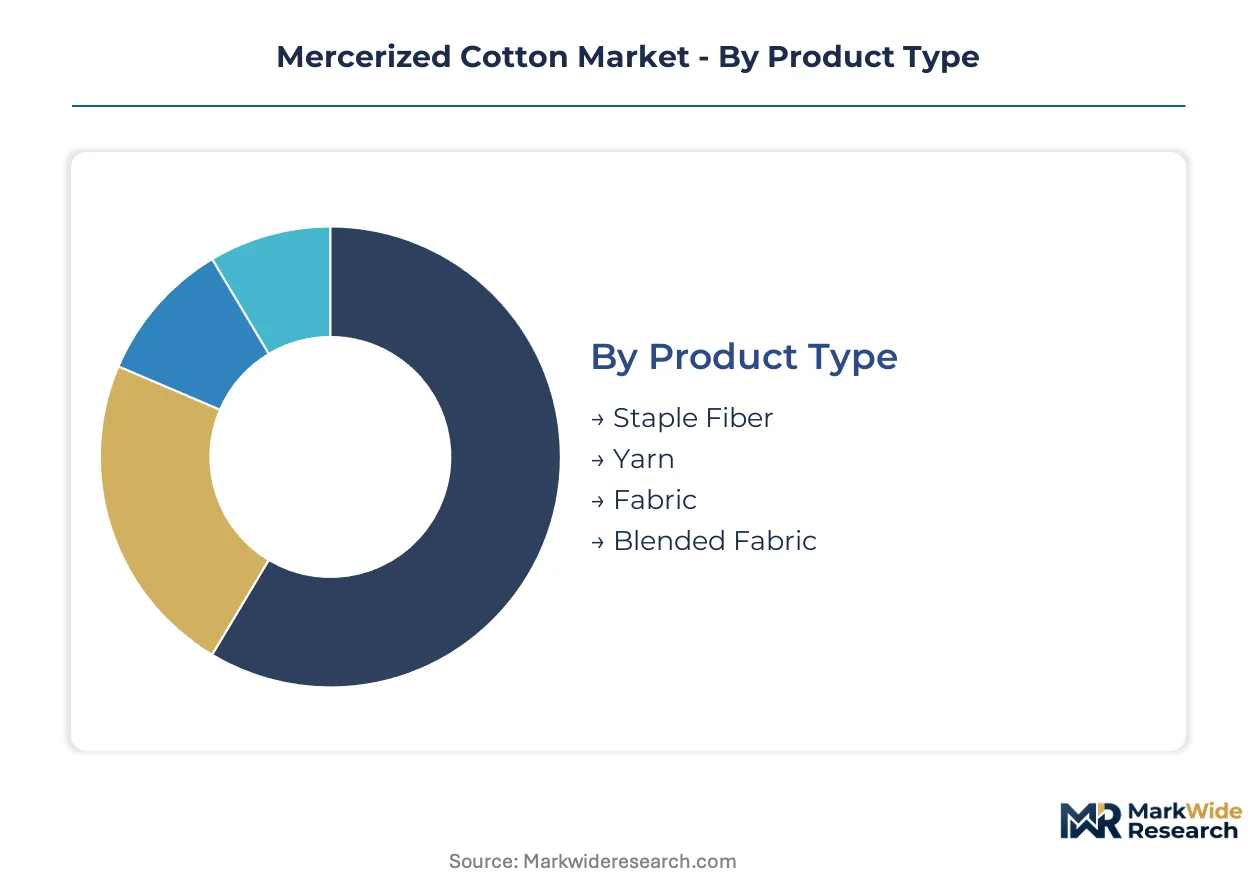
Mercerized cotton segments diverge sharply by processing depth and buyer technical requirements. Staple fiber mercerization serves integrated spinners seeking captive yarn feedstock, while fabric-stage treatment commands premium positioning in finished goods channels.
Product Type:
Yarn and fabric stages capture divergent value pools across the mercerization use-case spectrum, from commodity reinforcement to luxury surface aesthetics.
- Yarn:Ringspun mercerized yarn undergoes controlled caustic soda immersion under tension to swell fibers and lock in tensile gains of 15-25%. Dress shirt specialists in Italy and premium knitwear producers in Japan specify these grades for dye brilliance and sewability.
- Fabric:Open-width mercerization of woven sheeting and shirting delivers uniform luster across broad goods, serving hospitality bedding buyers and luxury apparel cutters who reject piece-to-piece variation. REACH-compliant Italian finishers dominate this tier for EU-bound goods.
- Staple Fiber:Raw cotton mercerization before spinning remains concentrated among Indian and Chinese integrated mills controlling fiber-to-yarn flows.
- Blended Fabric:Mercerized cotton-modal and cotton-silk unions target drape-sensitive applications in eveningwear and luxury bedding.
Established volume favors yarn; emerging adoption favors blended fabric.
Application:
End-use requirements split between surface-critical consumer goods and strength-driven technical specifications.
- Apparel:Dress shirts, knitwear, and formalwear specify mercerized cotton for luster stability through repeated laundering. New York and Los Angeles-based menswear brands now contract directly with Indian spinners for custom shade lots.
- Technical Textiles:Medical gauze reinforcement and industrial sewing thread exploit the fiber's tensile upgrade for load-bearing applications. German and Swiss manufacturers adopt continuous mercerization lines to meet ISO 13485 traceability mandates.
- Home Textiles:Institutional and hospitality bedding absorbs substantial mercerized fabric volume for wash durability and appearance retention.
- Upholstery:Decorative fabric applications for contract furniture specify mercerized grades for abrasion resistance and color fastness.
Apparel maintains margin leadership; technical textiles are climbing the fastest.
End User:
Buyer scale and integration depth determine mercerization service procurement patterns.
- Textile Mills:Vertically controlled spinning and weaving operations in Tamil Nadu and Gujarat perform captive mercerization to capture margin upstream.
- Garment Manufacturers:Cut-make-trim contractors in Bangladesh and Vietnam source pre-mercerized yarn from Indian integrated suppliers.
- Interior Decorators:Specification-driven buyers for hospitality and residential projects dictate fabric mercerization standards to finishing subcontractors.
- OEMs:Automotive and medical device manufacturers contract specialized mercerized reinforcement materials through qualified tier-2 textile suppliers.
Mill integration favors captive processing; garment outsourcing favors merchant yarn supply.
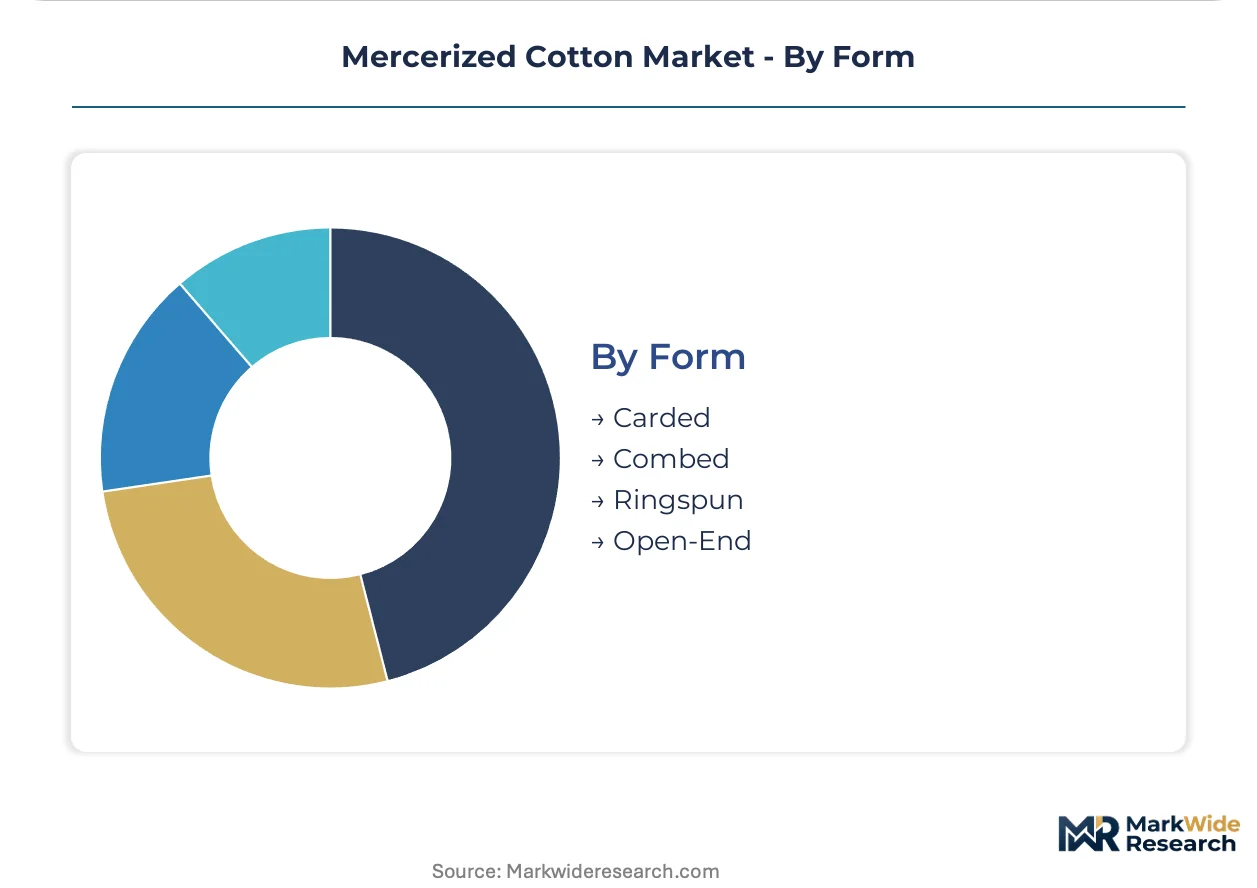
Form:
Spinning technology selection governs mercerization timing and fiber preparation intensity.
- Ringspun:Long-staple combed cotton processed on ring frames yields the finest mercerized yarn counts for premium shirting. Italian and Portuguese mills concentrate capacity here.
- Combed:Extended fiber preparation removes short fibers before mercerization, enabling superior luster and reduced hairiness in finished yarn.
- Carded:Shorter staple processing for mid-tier applications accepts mercerization at yarn or fabric stage with acceptable quality trade-offs.
- Open-End:Rotor-spun mercerized yarn serves bulk home textile and industrial applications where tensile gain matters more than surface refinement.
Combed ringspun commands premium positioning; open-end serves volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian finishers command 35-40% price premiums over Indian integrated mills for REACH-compliant mercerized shirting, yet Tamil Nadu and Gujarat clusters absorb 60% of incremental capacity investment through 2035.
India
Tamil Nadu and Gujarat textile clusters drive captive mercerization expansion for dress shirt and home textile exports. The Central Pollution Control Board enforces zero-liquid-discharge mandates on Tiruppur and Surat processors, forcing membrane filtration capex that favors integrated chemical-textile complexes over standalone operators.
China
Shandong Province spinning capacity anchors ringspun mercerized yarn supply to Asian garment exporters. MIIT dual carbon goals tighten energy intensity standards on caustic soda production, pushing Weiqiao-scale integrated mills toward captive chlor-alkali supply.
Italy
Como and Biella finishing districts specialize in open-width mercerization for luxury apparel brands specifying OEKO-TEX Standard 100 certification. ECHA REACH Annex XVII updates on sodium hydroxide workplace exposure mandate enclosed fiber handling systems, consolidating volume among automated lines installed post-2015.
United States
North Carolina and South Carolina spinning corridors sustain automated open-end and ringspun mercerized output for hospitality bedding and institutional home textile buyers. EPA effluent guidelines under the Clean Water Act filter processor viability, though integrated mills with on-site chemical recovery maintain cost parity.
Germany
Technical textile manufacturers in Baden-Württemberg adopt continuous mercerization systems for medical gauze and industrial sewing thread meeting ISO 13485 traceability. KBA chemical handling inspections and ECHA enforcement on caustic soda storage protocols accelerate capital replacement for batch kettle operations.
Mercerized Cotton Market Key Industry Players
Integrated chemical-textile complexes and specialized finishing houses split the market between volume efficiency and certification premiums. The supplier base concentrates among vertically controlled operations in India and China, with European finishers occupying boutique positioning for REACH-compliant goods. Three archetypes dominate: captive mercerization within spinning-weaving combinations, toll processors serving merchant yarn demand, and technical specialists for medical and industrial reinforcement applications. Capacity expansion and regulatory compliance automation constitute the dominant competitive moves, with zero-liquid-discharge system integration separating viable from marginal processors.
Among India-based integrated textile groups, Arvind Limited and Gul-Ahmed Textile Mills Ltd. exemplify captive mercerization strategies controlling fiber-to-fabric flows for premium apparel export channels. Weiqiao Textile Company Limited anchors the scale-driven tier within Shandong Province, representing massive spinning capacity directed toward ringspun mercerized grades. These three occupy positions that mirror the broader market structure: integrated Indian and Chinese mills capture volume, while European and North American specialists defend certification-premium positioning.
| Leading Market Players |
|---|
| MT Royal |
| Mount Vernon Mills |
| Wuxi Natural Textile Industrial Co., Ltd. |
| Weiqiao Textile Company Limited |
| Arvind Limited |
| Gul-Ahmed Textile Mills Ltd. |
| Parkdale Mills |
| Suzhou Facto Textile Co., Ltd. |
| Savana Textile Co. |
| Others |
Cost & Logistics Intelligence
Tiruppur's zero-liquid-discharge compliance investments are compressing standalone processor margins while amplifying pricing power for integrated Tamil Nadu mills supplying REACH-certified mercerized yarn to European apparel buyers.
Pricing Analysis
The customization-premium spread between configured-to-order ringspun mercerized yarn and standard open-end grades runs wide, with OEKO-TEX Standard 100 certification and custom dye shade matching commanding substantial uplifts over commodity offerings. Pricing stratifies across premium certified, standard merchant, and economy toll-processing tiers, with REACH compliance costs and caustic soda price volatility squeezing mid-tier standalone processors most acutely. Brand-direct procurement by New York and Los Angeles menswear labels shows lowest price sensitivity; Bangladeshi garment contractors exhibit highest.
Supply Chain Analysis
Tariff exposure between the United States and China is reshourcing mercerized cotton flows toward Indian integrated mills and Vietnamese garment cut-make-trim contractors. Supply concentrates in India, China, and Italy, with raw cotton lint, caustic soda, and membrane filtration equipment anchoring input dependencies. Single-source vulnerability in Italian finishing districts for EU luxury apparel certification creates concentration risk. Distribution runs through direct mill-to-brand contracting, displacing traditional yarn merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story, where ECHA REACH enforcement and India's zero-liquid-discharge mandates erect switching costs that entrench compliant integrated operators against marginal standalone processors.
For Market Incumbents: Harden certification barriers by pursuing dual OEKO-TEX Standard 100 and GOTS accreditation for EU infant apparel channels, while consolidating captive chlor-alkali supply to neutralize caustic soda price volatility threatening standalone competitors. Expand automated continuous mercerization lines in Tamil Nadu and Gujarat to amortize compliance capex across volume throughput.
For New Entrants and Emerging Players: Build out technical textile specialization for medical gauze reinforcement and industrial sewing thread applications, where ISO 13485 traceability requirements and German KBA chemical handling inspections filter incumbent competition. Target Baden-Württemberg and Swiss medical device OEM supply chains with continuous mercerization systems offering lot-level digital records.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chemical-textile complexes with captive caustic soda production and long-term direct brand contracts. Long-term viability favors Indian and Chinese operators with zero-liquid-discharge infrastructure already deployed. Watch ECHA enforcement intensity on sodium hydroxide workplace exposure as inflection signal for European processor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge System Integration | Membrane filtration and evaporation capex separates viable Tamil Nadu processors from regulatory casualties. |
| Captive Chlor-Alkali Supply | Backward integration into caustic soda production neutralizes energy-intensive input cost volatility for Shandong mills. |
| Continuous Mercerization Line Adoption | German technical textile manufacturers deploy these systems to meet ISO 13485 traceability for medical gauze. |
| Dual Certification Investment | Combined OEKO-TEX Standard 100 and GOTS accreditation unlocks EU infant apparel and luxury home textile segments. |
| Direct Mill-to-Brand Contracting | Bypassing yarn merchant intermediaries captures margin compression from supply chain disintermediation in North America. |
Research Approach
Cross-validation between primary interviews with spinning mill technical directors, chemical procurement leads, and European apparel brand sourcing managers and secondary validation against ECHA REACH enforcement records, Indian Central Pollution Control Board discharge monitoring data, and customs trade flows anchors the qualitative findings. Bottom-up capacity assessments across Tiruppur, Surat, and Shandong clusters were triangulated against top-down demand modeling from dress shirt and home textile export statistics.
Calibration against historical caustic soda price cycles and regulatory implementation timelines shaped the projection framework across the analysis window. Segmentation dimensions include processing stage, spinning technology, end-use application, and regional compliance cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Industry-specific inputs incorporate ECHA Annex XVII enforcement trajectory and MIIT dual carbon goal implementation pace.
Stress conditions across caustic soda price volatility, ECHA workplace exposure limit tightening, and zero-liquid-discharge mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and brand certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Europe Cotton Market